
 Industrial Grout Pumps Market | 2026-2036
Industrial Grout Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Grout Pumps Market Foresight
The capital-intensity divergence between integrated pump manufacturers and component assemblers is collapsing as proprietary hydraulic systems become commoditized. Putzmeister Holding GmbH leverages in-house casting capabilities to sustain margin control across European infrastructure contracts. Sika AG anchors its position through chemical grout formulation expertise that locks in recurring pump consumables revenue. Atlas Copco AB competes by dominating pneumatic systems for underground mining applications where explosion-proof requirements apply.
Industrial grout pumps are positive-displacement or peristaltic machines engineered to inject cementitious, epoxy, or chemical grouts at controlled pressures ranging from 50 to 10,000 psi for structural reinforcement and void filling. Electric grout pumps are gaining share in urban construction zones where emission regulations restrict diesel equipment, while hydraulic variants retain dominance in remote mining and oil field settings lacking grid connectivity. Peristaltic technology leads in waterproofing applications due to its gentle handling of abrasive slurries, whereas diaphragm systems capture margin pools in precision crack injection where pulsation control determines warranty outcomes.
OSHA confined-space entry standards and EPA spill prevention requirements shape pump specifications for US contractors, while REACH compliance in Europe restricts certain chemical grout formulations and drives equipment substitution cycles. China's GB standards for tunneling safety and India's BIS certification for construction machinery create parallel compliance tracks that fragment product portfolios. Stakeholders must monitor how regional decarbonization mandates redistribute demand between electric, pneumatic, and hydraulic technologies before committing to capacity expansion or platform retirement decisions.
Market Dynamics
The EU F-Gas Regulation is forcing hydraulic system manufacturers toward electric and pneumatic architectures, collapsing the historical performance gap between high-pressure hydraulics and cleaner alternatives in underground mining and tunneling applications.
Growth Catalysts
- Western Chinese Infrastructure:Hydropower and tunneling projects in Sichuan and Yunnan provinces require specialized soil stabilization equipment, concentrating demand for high-pressure injection systems.
- REACH Chemical Restrictions:European limitations on certain grout formulations accelerate equipment replacement cycles as contractors substitute compliant chemistries requiring different pump specifications.
- Peristaltic Abrasion Handling:Waterproofing contractors favor peristaltic technology for gentle slurry transport, expanding addressable applications in heritage structure rehabilitation and marine infrastructure.
Market Restraints
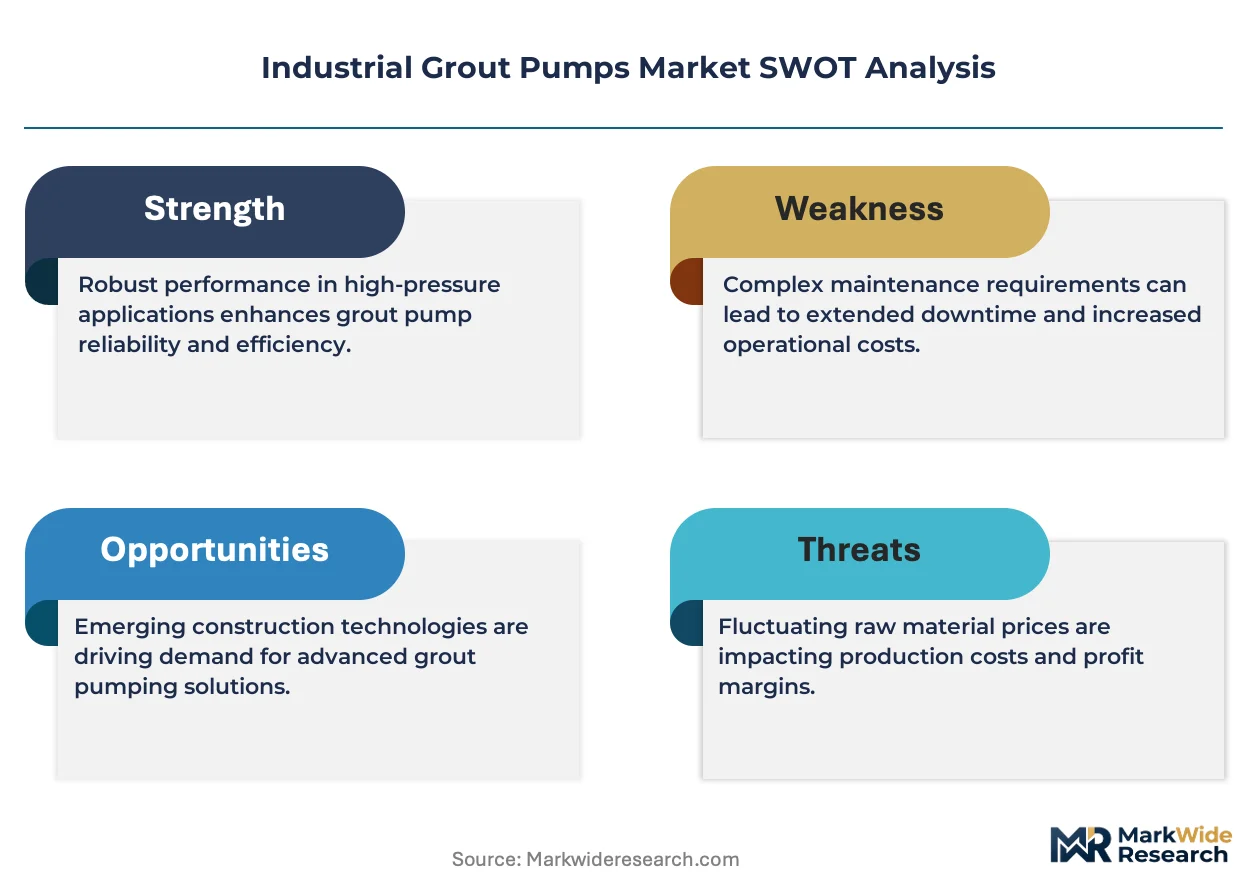
- Specialized Alloy Input Costs:High-nickel stainless steel and tungsten carbide components for abrasive grout handling face volatile commodity pricing, compressing assembler margins.
- Hydraulic Component Supply Concentration:Precision hydraulic valve and pump subassembly production concentrates in German and Japanese tier-two suppliers, creating single-source vulnerability.
- Electric Grid Connectivity Gaps:Remote Australian and Chilean mining sites lack reliable grid infrastructure, restricting electric pump deployment despite emission mandates.
Strategic Opportunities
- India Tunneling Safety Mandates:BIS certification requirements for construction machinery create first-mover advantage for compliant equipment suppliers in metro rail and highway tunnel projects.
- IoT Predictive Maintenance Convergence:Integration of pressure sensors and cloud analytics enables outcome-based service contracts, shifting revenue from equipment sales to uptime guarantees.
- Epoxy Grout Precision Injection:Wind turbine foundation specifications increasingly require low-pulsation diaphragm systems for structural crack repair, opening premium aftermarket segments.
Industry Challenges
- Hydraulic Technician Scarcity:Maintenance of high-pressure hydraulic units requires specialized fluid power expertise that mining contractors struggle to source in remote operational theaters.
- Multi-Jurisdiction Certification Timelines:Parallel OSHA, REACH, and GB standard compliance testing extends product launch cycles by 8-14 months for universal platform designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Grout Pumps Market |
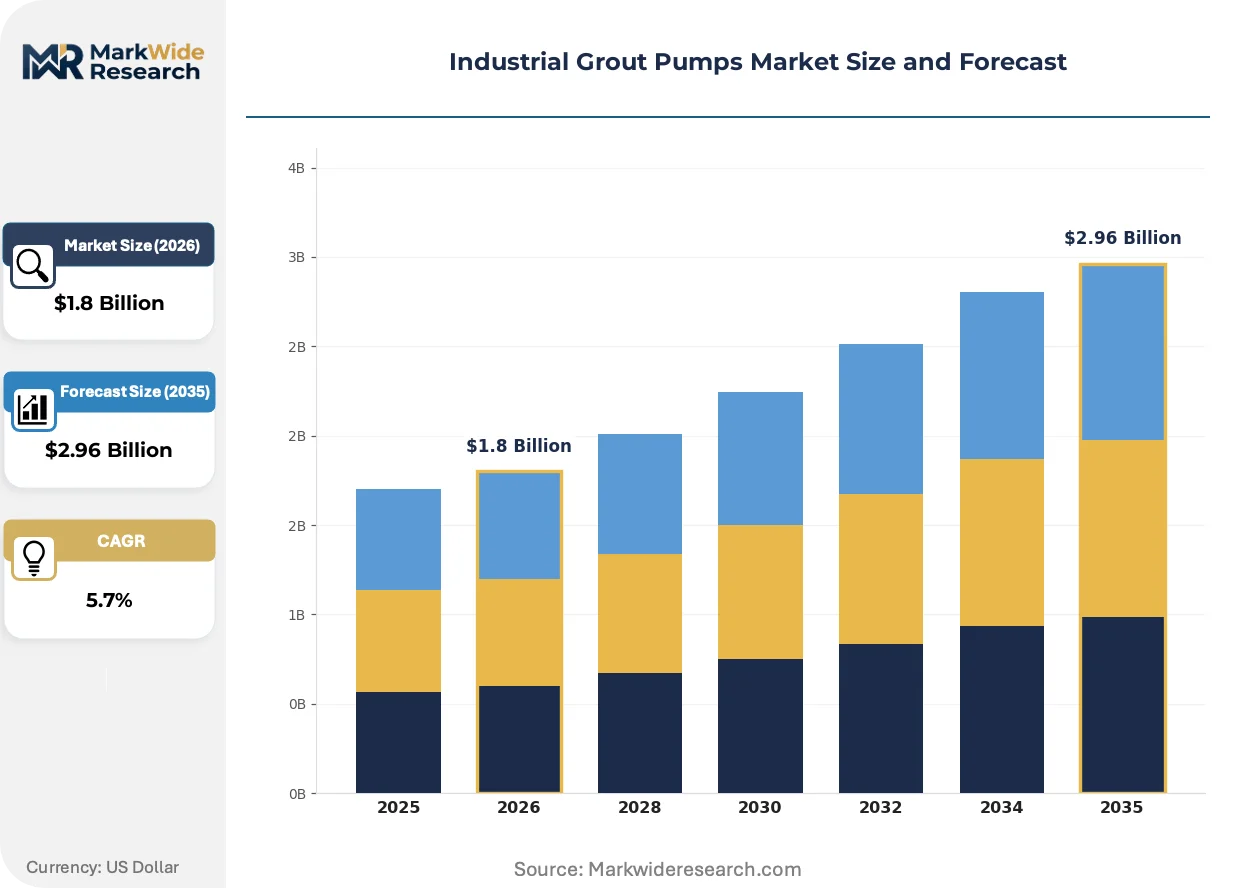
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grout Pumps, Pneumatic Grout Pumps, Hydraulic Grout Pumps, Manual Grout Pumps End User: Construction, Mining, Oil & Gas, Infrastructure Application: Flooring, Crack Injection, Waterproofing, Soil Stabilization Technology: Positive Displacement, Peristaltic, Diaphragm, Rotary |
| Companies Covered | Putzmeister Holding GmbH, Sika AG, Atlas Copco AB, Graco Inc., ChemGrout Inc., Cemen Tech Inc., Sany Heavy Industry, Schwing Stetter, Normet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Grout Pumps Market Shifts & Advancements
Electrification architectures and digital monitoring systems are fragmenting the traditional equipment-supplier relationship, shifting value capture toward software-enabled service layers and away from pure hardware transactions.
Modular electric drive systems is fragmenting the long-standing dominance of integrated hydraulic powerpacks in medium-pressure applications. Urban construction contractors in emission-restricted zones adopt swappable battery-electric units for foundation work. This technology is fragmenting the aftermarket service market, enabling third-party electronics specialists to compete with OEM maintenance networks.
The EU F-Gas Regulation mandates phased reduction of hydrofluorocarbon-based hydraulic fluids, compelling manufacturers to reformulate seal compatibility and thermal management systems. Equipment suppliers must recertify entire product lines under revised pressure vessel directives. Underground mining operators in Germany and Poland face accelerated replacement schedules for existing hydraulic fleets.
Rental-first procurement patterns now dominate European infrastructure contractors, compressing direct equipment sales and elevating fleet management software capabilities as competitive differentiators. OEMs respond with telematics-integrated units that monitor utilization rates and predictive wear. This shift is most pronounced in Benelux and Nordic markets where project-based contracting favors operational expenditure models.
Industrial Grout Pumps Market Segmentation
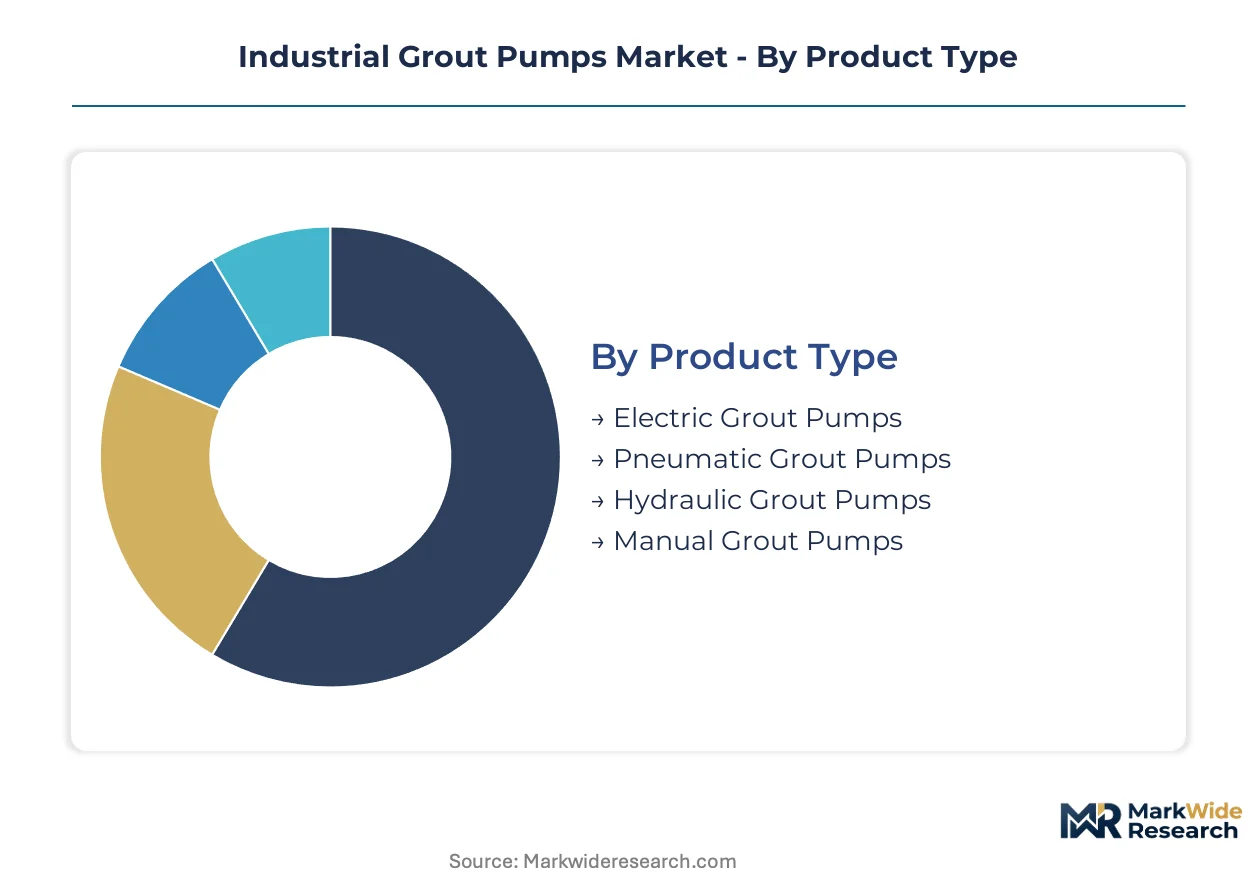
Grout pump procurement decisions diverge sharply across regulatory jurisdictions, with emission mandates in European urban zones favoring electric architectures while remote mining theaters in Australia and Chile retain hydraulic dominance due to grid infrastructure gaps. Technology selection further fragments by application chemistry, as abrasive cementitious slurries demand peristaltic handling whereas precision epoxy injection requires low-pulsation diaphragm systems.
Product Type:
OSHA confined-space standards and EPA spill prevention requirements in the US, alongside EU F-Gas Regulation phase-downs, are redistributing procurement volumes across powertrain architectures.
- Electric Grout Pumps:Battery-electric and corded units deliver zero-emission operation for urban foundation work and tunneling projects. Demand concentrates in Germany and the Netherlands where municipal emission zones restrict diesel equipment, though grid connectivity limits deployment in Western Australian iron ore operations.
- Hydraulic Grout Pumps:High-pressure hydraulic powerpacks generate 5,000-10,000 psi for deep soil stabilization and mining void filling. Procurement clusters in Chilean copper belt operations and Chinese hydropower tunneling where remote locations lack reliable electricity supply.
- Pneumatic Grout Pumps:Compressed-air systems provide explosion-proof operation for underground coal and methane-rich environments. Mines in Poland and Germany specify these units for compliance with ATEX directives.
- Manual Grout Pumps:Hand-operated piston units serve small-scale repair contractors and heritage restoration projects requiring portable, low-volume injection. Specialist waterproofing crews in Italian historic centers favor this category for monument conservation work.
Established volume favors hydraulic systems; emerging adoption favors electric architectures.
End User:
Capital expenditure cycles and project financing structures shape equipment ownership models, with rental penetration highest in European infrastructure and direct procurement dominating Asian mining.
- Construction:General contractors deploy medium-pressure electric and hydraulic units for building foundation grouting and structural reinforcement. Urban high-rise projects in Singapore and Dubai specify low-noise electric systems to comply with municipal construction hour restrictions.
- Mining:Underground hard-rock and coal operations require explosion-proof pneumatic or high-pressure hydraulic pumps for ground support and backfilling. Procurement volumes concentrate in Western Australia and Chile where ore body depth demands intensive ground stabilization.
- Oil & Gas:Offshore platform maintenance and pipeline repair operations use corrosion-resistant diaphragm pumps for structural crack injection. North Sea operators specify stainless steel construction to withstand salt spray exposure.
- Infrastructure:Highway tunneling, dam construction, and metro rail projects drive demand for high-reliability injection systems. China's western provinces account for concentrated procurement of specialized soil stabilization equipment for hydropower development.
Volume concentrates in mining procurement; steepest expansion trajectory appears in infrastructure electrification.
Application:
Material rheology and placement precision requirements dictate technology selection, with abrasive slurries favoring peristaltic handling and thin epoxy formulations requiring pulsation-controlled diaphragm systems.
- Soil Stabilization:High-volume cement and chemical grout injection for ground improvement and liquefaction mitigation. Dam foundation work in Sichuan province and highway tunneling in Norway drive specification of high-pressure hydraulic units.
- Crack Injection:Precision placement of low-viscosity epoxy and polyurethane grouts for structural concrete repair. Wind turbine foundation specifications increasingly mandate low-pulsation diaphragm systems to ensure complete void penetration.
- Waterproofing:Membrane-grade slurry application for basements, tunnels, and marine structures. Peristaltic pumps dominate due to gentle handling of abrasive bentonite and cement mixtures without valve wear.
- Flooring:Self-leveling underlayment and industrial floor topping placement. Commercial construction in US metropolitan areas favors electric pumps for indoor emission compliance.
Mature demand centers on waterproofing; precision crack injection gains share fastest.
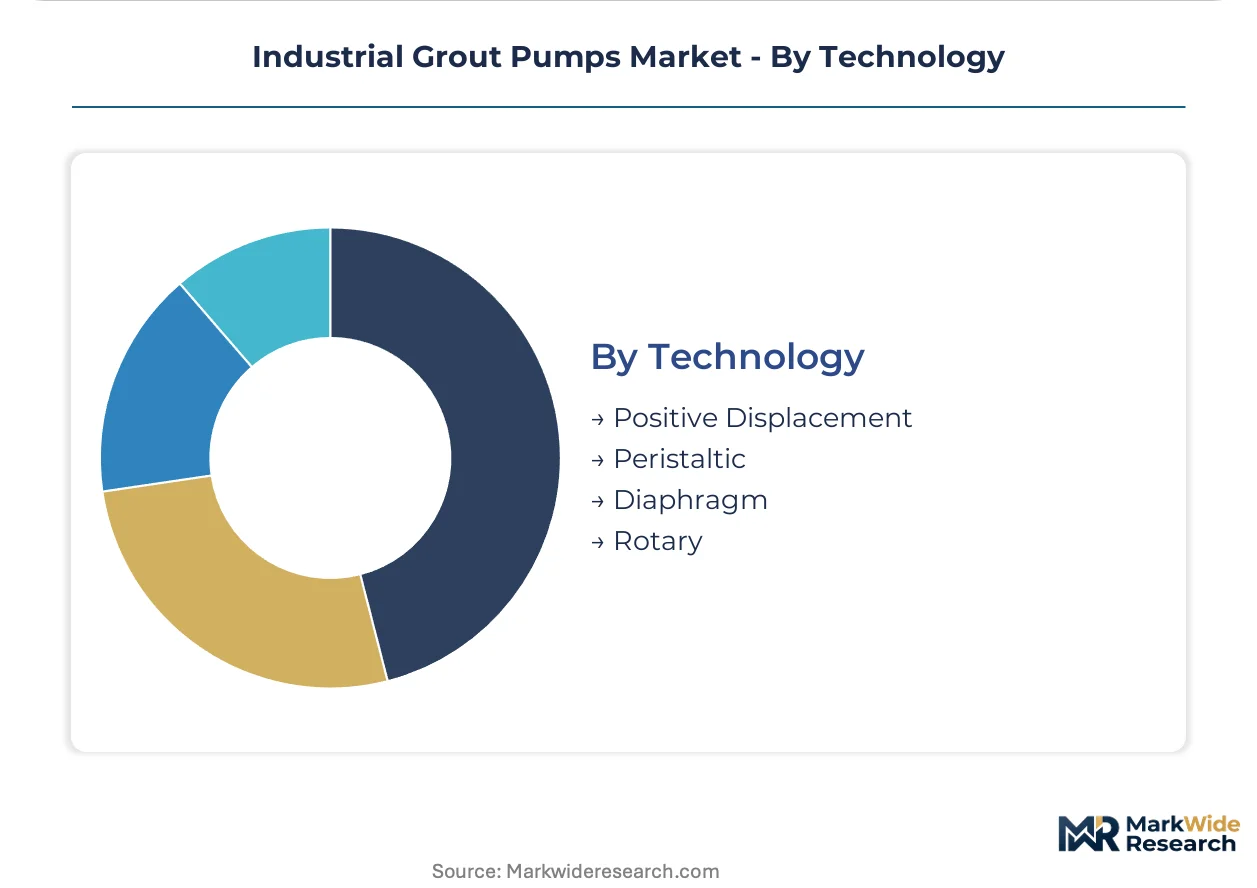
Technology:
Intellectual property concentration in seal materials and rotor geometries is collapsing as Chinese component suppliers commoditize core subassemblies.
- Peristaltic:Hose-based compression systems eliminate contact between grout and mechanical components, enabling abrasive slurry handling with minimal wear. Waterproofing contractors in marine infrastructure and heritage restoration specify these units for reliability.
- Diaphragm:Pulsation-dampened reciprocating action delivers precise flow control for critical structural injection. Warranty requirements in wind turbine foundation repair mandate this technology for crack penetration assurance.
- Positive Displacement:Piston and plunger systems generate extreme pressures for deep soil stabilization and rock fissure grouting. Mining contractors in Western Australia specify these for ground support in seismically active zones.
- Rotary:Lobe and gear pump configurations handle high-viscosity thixotropic grouts for specialized geotechnical applications. Limited deployment in tunneling backfill operations where continuous flow outweighs precision requirements.
Positive displacement retains volume leadership; peristaltic systems climb the fastest in waterproofing substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the highest price elasticity for electric grout pumps under municipal emission mandates, while mining operators in Western Australia and Chile prioritize reliability over cost for hydraulic units in grid-deficient territories.
United States
Foundation contractors in Texas and Florida drive steady procurement of medium-pressure electric units for commercial high-rise work. OSHA confined-space entry standards and EPA spill prevention requirements shape pump specifications across state-level contracting pools. Houston's energy corridor anchors demand for corrosion-resistant diaphragm systems in offshore platform maintenance.
Germany
Underground mining operators in the Ruhr and Saarland regions face accelerated hydraulic fleet replacement under EU F-Gas Regulation phase-down schedules. REACH compliance restricts certain chemical grout formulations, forcing equipment substitution toward compatible chemistries. Munich-based infrastructure contractors favor rental-first procurement with telematics-integrated units.
Australia
Western Australian iron ore and lithium operations concentrate procurement of high-pressure hydraulic pumps for deep ground stabilization. Grid infrastructure gaps in the Pilbara and Goldfields restrict electric deployment despite corporate decarbonization pledges. Perth serves as the regional distribution hub for mining-focused equipment servicing.
China
Hydropower development in Sichuan and Yunnan provinces concentrates demand for specialized soil stabilization equipment in tunneling applications. GB standards for tunneling safety create compliance-driven replacement cycles for domestic and imported equipment. Chengdu's machinery manufacturing cluster supplies high-pressure injection systems for western infrastructure projects.
Chile
Copper belt operations in the Atacama and Antofagasta regions sustain demand for hydraulic powerpacks in remote, high-altitude mining environments. Explosion-proof pneumatic systems penetrate deeper shaft operations under national mining safety protocols. Santiago-based distributors coordinate aftermarket parts logistics across the Andean mining corridor.
Industrial Grout Pumps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated European and Japanese manufacturers commanding premium positioning through proprietary hydraulic systems while Chinese fabricators compress pricing on commoditized electric platforms. The vendor base stratifies across three tiers: multinational OEMs with captive component production, regional specialists serving mining or construction verticals, and emerging electric-drive assemblers leveraging modular subsystems. Dominant competitive moves include capacity expansion in battery-electric architectures and strategic partnerships with grout chemistry suppliers to lock in consumables revenue.
Among German-origin industrial equipment groups, Putzmeister Holding GmbH and Schwing Stetter occupy positions emphasizing integrated manufacturing control, while Sika AG represents the chemical-formulation archetype that anchors recurring revenue through proprietary grout compatibility requirements. Atlas Copco AB exemplifies the pneumatic specialization vector for explosion-critical underground applications. Chinese heavy industry participants including Sany Heavy Industry sit within the scale-driven tier targeting cost-sensitive infrastructure markets through standardized electric platforms.
| Leading Market Players |
|---|
| Putzmeister Holding GmbH |
| Sika AG |
| Atlas Copco AB |
| Graco Inc. |
| ChemGrout Inc. |
| Cemen Tech Inc. |
| Sany Heavy Industry |
| Schwing Stetter |
| Normet |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for precision hydraulic valve subassemblies from German and Japanese tier-two suppliers concentrate pricing power with integrated OEMs while compressing assembler margins on commoditized electric platforms. This inventory pressure feeds back into procurement strategies, with rental-first contractors in Benelux and Nordic markets prioritizing telematics-integrated fleet availability over unit acquisition cost.
Pricing Analysis
After-sales service contracts and consumables revenue from chemical grout formulations anchor lifetime value capture for incumbent suppliers. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with captive hydraulic casting from Chinese assemblers of modular electric drives. Cost compression in mid-pressure electric tiers is intensifying because Chinese component suppliers have commoditized rotor and seal geometries. Mining contractors in Western Australia exhibit lowest price sensitivity, prioritizing reliability in grid-deficient territories, while urban foundation contractors in Germany and the Netherlands face municipal emission mandates that elevate total cost of ownership scrutiny.
Supply Chain Analysis
Ruhr Valley precision machining clusters and Osaka hydraulic component corridors constitute chokepoints where single-source valve and pump subassembly production concentrates. High-nickel stainless steel and tungsten carbide for abrasive grout handling draw from Australian mining and Chinese refining operations. Single-source vulnerability in German and Japanese tier-two suppliers exposes assemblers to allocation risk during commodity price spikes. Distribution runs through regional equipment rental networks in Europe and OEM-direct mining procurement in Australia and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fluid power expertise for high-pressure hydraulic maintenance is scarce across remote mining theaters, creating defensive moats for incumbent service networks while constraining new entrant scale-up. This capability gap shapes competitive dynamics across procurement, aftermarket, and technology transition decisions.
For Market Incumbents: Consolidate control over hydraulic technician training pipelines and captive casting capabilities to defend against modular electric-drive substitution. Add certified service capacity in Western Australia and Chilean mining corridors before emerging electric entrants establish beachheads. Lock in recurring grout chemistry revenue through formulation-pump compatibility requirements that elevate switching costs. For New Entrants and Emerging Players: Differentiate on battery-electric architectures with swappable powerpacks for urban emission-restricted zones where grid infrastructure supports deployment. Target waterproofing contractors in heritage restoration and marine infrastructure where peristaltic technology specifications favor gentle slurry handling over hydraulic pressure ratings. Pursue rental-fleet partnerships with telematics integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-electric pump subsegments as modular subsystems reduce in-house manufacturing requirements. Long-term viability favors asset-light assemblers with software-enabled service layers over integrated hydraulic foundries. Acquisition target archetype: regional specialists with BIS certification for Indian tunneling safety mandates and established aftermarket parts logistics. Watch EU F-Gas Regulation enforcement timelines as the inflection signal for hydraulic fleet replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Casting | Putzmeister and Schwing Stetter sustain margin control through Ruhr Valley captive foundry capacity. |
| Grout Chemistry Partnership | Sika AG locks in recurring consumables revenue through proprietary formulation-pump compatibility specifications. |
| Telematics Fleet Integration | Rental-first procurement in Benelux elevates utilization-monitoring software as competitive differentiator. |
| BIS Certification Investment | Compliant equipment suppliers capture first-mover advantage in Indian metro rail and highway tunnel projects. |
| Electric Architecture Modularization | Swappable battery-electric units fragment aftermarket service markets, enabling third-party electronics competition. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Western Australian mining operations, plant engineers at Chinese hydropower contractors, OEM procurement teams at European infrastructure specialists, and aftermarket service heads at Chilean distributors. Secondary validation drew from customs and trade data for grout pump imports, SEC filings of listed equipment manufacturers, tunneling safety certification databases, and EU regulatory implementation notices. Bottom-up equipment shipment data and top-down infrastructure investment flows were triangulated to anchor volume estimates.
Across the analysis window, the forecasting framework models powertrain architecture substitution, application chemistry requirements, and regional regulatory compliance tracks as primary segmentation dimensions. CAGRs were derived from installed base replacement cycles, project pipeline visibility in western Chinese provinces, and rental penetration trajectories in European markets. Industry-specific inputs include hydropower development timelines in Sichuan and Yunnan, copper belt expansion schedules in Chile, and REACH chemical restriction implementation phases.
Decision-makers should treat outputs as directional under base assumptions of sustained infrastructure investment in China and stable mining output in Australia and Chile; material deviation in commodity prices or regulatory enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and grid infrastructure buildout timelines in remote mining territories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Case Erectors Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Aerial Work Platform (AWP) Market