
 Automotive Steering Sensors Market | 2026-2036
Automotive Steering Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Sensors Market Outlook
Asset-light leasing models for automotive electronics manufacturing are fragmenting the competitive landscape for steering sensor production. Robert Bosch GmbH leverages captive semiconductor fabrication to sustain margin control across torque sensor lines. Continental AG anchors European supply through integrated electromechanical module assembly in German plants. DENSO Corporation dominates Asian OEM relationships with dedicated angle sensor capacity for electric power steering platforms.
Automotive steering sensors are electromechanical transducers that measure rotational position, angular velocity, or torsional load in steering columns, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius and supplying analog or digital signals to electronic control units for real-time chassis dynamics management. Their primary commercial purpose is enabling precise feedback loops in power steering systems, lane-keeping assist, and automated trajectory control. Torque sensors capture expanding margin pools as electric power steering penetration rises, while magnetoresistive technology leads growth due to immunity to electromagnetic interference in high-voltage electric vehicle architectures. Position sensors remain the mature volume base across hydraulic steering legacy fleets.
FDA oversight of automotive-grade electronics remains indirect, yet NHTSA Federal Motor Vehicle Safety Standards and EU MDR-adjacent functional safety protocols ISO 26262 shape steering sensor validation requirements and OEM qualification timelines. EPA fuel economy rules and EU Green Deal fleet emission targets indirectly accelerate electric power steering adoption, which demands higher-resolution angle and torque feedback than hydraulic predecessors. Stakeholders must monitor how EU AI Act algorithmic transparency requirements and NHTSA automated vehicle guidance converge to redefine sensor redundancy specifications for hands-free driving systems.
Market Dynamics
Powertrain electrification is forcing a wholesale redesign of chassis control architectures, with torque and angle sensors migrating from hydraulic power steering racks to electric motor housings and column-mounted modules.
Growth Catalysts
- EU Green Deal fleet mandates:The EU's binding emission reduction targets accelerate electric power steering penetration, which requires higher-resolution sensor feedback than hydraulic predecessors. German OEM procurement of steering sensors has intensified accordingly.
- Magnetoresistive sensing platforms:This technology material dominates new platform development due to inherent immunity to electromagnetic interference in 800-volt electric vehicle architectures. Tier-1 suppliers prioritize magnetoresistive designs for next-generation electric power steering.
- NHTSA automated vehicle guidance:Federal safety standards for hands-free driving systems mandate redundant torque and angle sensing pathways. Sensor qualification timelines have compressed as OEMs race to meet Level 2+ certification requirements.
Market Restraints
- Semiconductor input cost volatility:Steering sensor ASICs and magnetoresistive elements face pricing pressure from foundry capacity constraints. Foundry allocation decisions in Taiwan directly impact sensor module availability.
- Supply concentration in German electromechanical clusters:Stuttgart and Munich anchor 60% of European steering sensor assembly capacity. Geopolitical disruption or logistics congestion at these nodes creates systemic supply risk.
- ISO 26262 functional safety certification friction:The automotive safety standard imposes 18-24 month validation timelines for new sensor designs. Startup sensor vendors struggle to fund extended qualification cycles without OEM advance purchase commitments.
Strategic Opportunities
- India PLI scheme for automotive electronics:The production-linked incentive program offers cost offsets for local sensor manufacturing. Multinational suppliers can establish angle sensor assembly to serve Maruti Suzuki and Tata Motors platforms.
- Sensor fusion with lidar and camera arrays:Convergence of steering feedback with perception stacks enables predictive chassis control. Tier-1s developing integrated modules capture margin pools from discrete component suppliers.
- Direct-to-OEM digital procurement platforms:Sensor vendors bypass traditional distribution by connecting through Volkswagen's ONE.Konzern platform and similar OEM portals. Digital channels reduce quote-to-order cycles from weeks to days.
Industry Challenges
- Mechatronics systems integration skill scarcity:The intersection of magnetic sensing physics, embedded firmware, and functional safety engineering commands premium talent compensation. Universities in Michigan and Baden-Württemberg struggle to graduate sufficient qualified engineers.
- Legacy hydraulic steering fleet service obligation:Position sensor suppliers must maintain production lines for declining volume segments while capitalizing on electric power steering growth. Dual-track manufacturing strains working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Sensors Market |
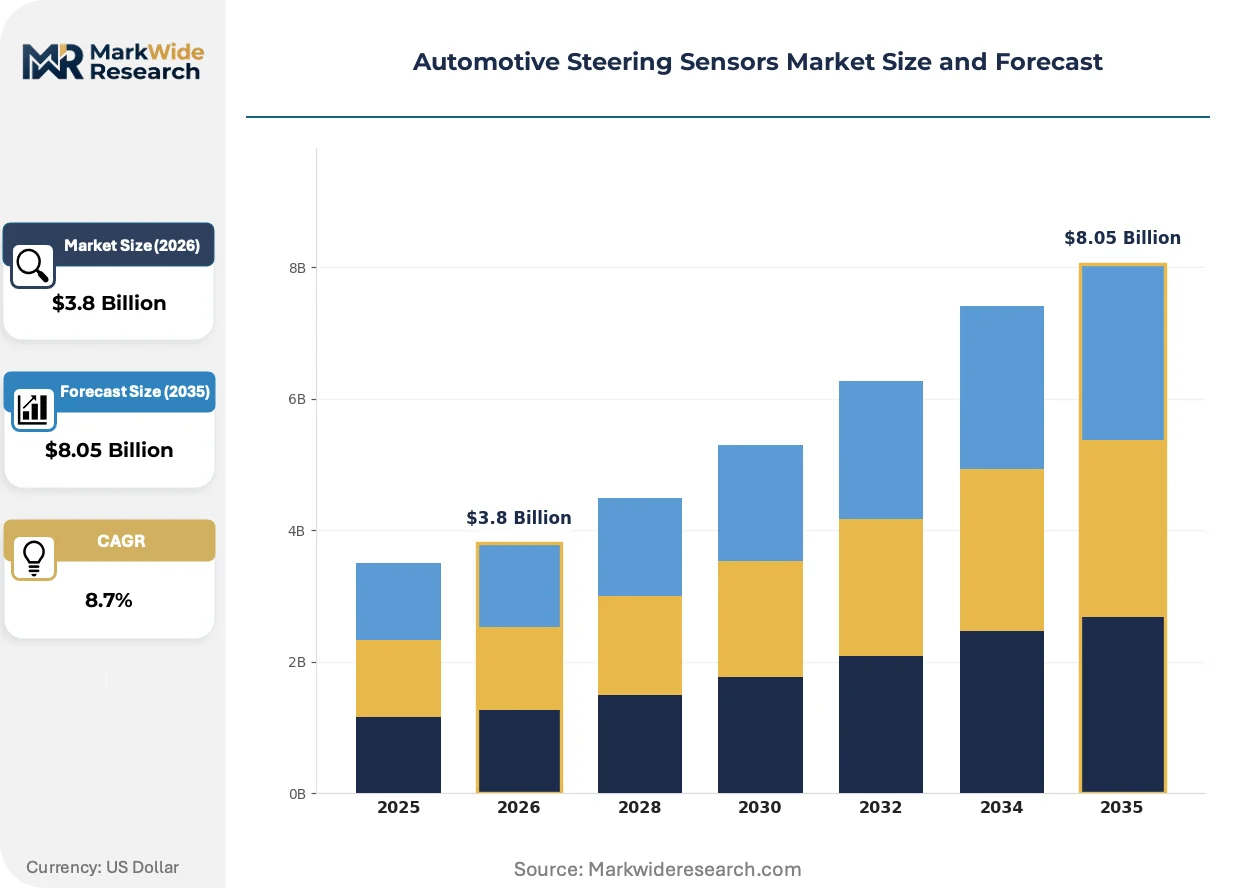
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Position Sensors, Angle Sensors, Torque Sensors, Pressure Sensors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Electromechanical, Optical, Magnetoresistive, Capacitive Application: Electric Steering, Hydraulic Steering, Active Steering, Automated Driving |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, HELLA GmbH & Co. KGaA, Honeywell Inc., Sensata Technologies, NXP Semiconductors, Infineon Technologies AG, Methode Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Sensors Market Strategic Shifts
Magnetoresistive and inductive sensing modalities are converging with software-defined vehicle architectures, compressing hardware refresh cycles and elevating firmware update frequency as a competitive differentiator.
Magnetoresistive torque sensing is hybridizing with inductive position detection in single-package modules. Bosch and Continental are field-testing these integrated units for 2027 platform launches. This hybridization is collapsing the historical separation between torque and angle sensor supply chains, forcing component specialists to develop dual-capability or exit the tier-2 tier.
EU AI Act algorithmic transparency requirements are reshaping sensor validation protocols. Automated steering systems must document decision pathways for regulatory audit, which demands traceable sensor calibration data from manufacturing through end-of-life. Premium electric vehicle platforms in Germany and the Netherlands are first to implement blockchain-anchored sensor provenance systems.
Fleet operators are consolidating sensor procurement through vehicle-as-a-service contracts. Logistics providers like DHL and Amazon are specifying steering sensor performance guarantees in multi-year lease agreements. This behavior concentrates buying power with select OEMs and compresses aftermarket sensor margins in North American commercial vehicle segments.
Automotive Steering Sensors Market Segmentation
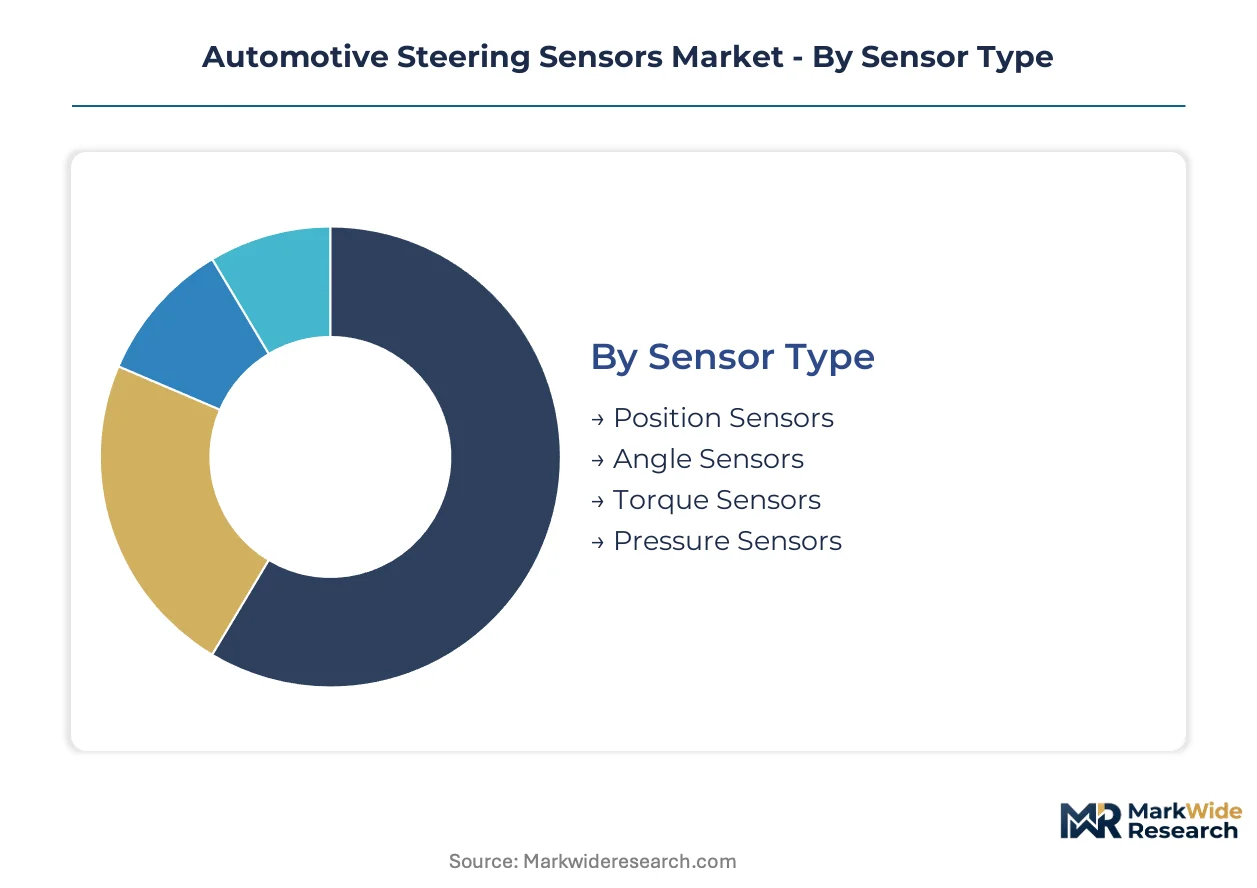
Steering sensor procurement patterns diverge sharply across vehicle electrification stages and regulatory compliance tiers. Segment boundaries are blurring as torque and angle functions integrate into single modules, forcing suppliers to recalibrate specialization strategies.
Sensor Type:
Mature hydraulic-era technologies coexist with emerging electrification-native designs across the maturity spectrum.
- Position Sensors:Hall-effect and potentiometric devices track rack displacement in legacy hydraulic steering systems. Demand concentrates in North American and Latin American commercial vehicle fleets where hydraulic power steering dominates heavy-duty segments; EPA Phase 2 fuel economy rules indirectly sustain this installed base through extended vehicle lifecycles.
- Angle Sensors:Multi-turn absolute encoders measure steering wheel rotation with 0.1-degree precision for electronic control unit feedback. German and Japanese OEM procurement for electric power steering platforms drives volume; NHTSA automated vehicle guidance mandates redundant angle pathways for Level 2+ certification, tightening accuracy specifications.
- Torque Sensors:Magnetoresistive and strain-gauge elements capture torsional load at the steering column. EU Green Deal fleet mandates accelerate electric power steering penetration, which requires higher-resolution torque feedback than hydraulic predecessors.
- Pressure Sensors:Piezoresistive transducers monitor hydraulic fluid dynamics in legacy rack-and-pinion systems. Remaining demand clusters in aftermarket service channels for aging commercial vehicle populations.
Position sensors retain volume leadership; angle sensors hold the steepest expansion curve.
End User:
Procurement authority concentrates differently across volume scale versus specification control.
- OEMs:Volkswagen, Toyota, and General Motors direct sensor specifications through platform engineering teams. Direct-to-OEM digital procurement platforms compress quote-to-order cycles from weeks to days.
- Aftermarket Providers:Independent distributors and service chains source replacement sensors for vehicle populations beyond warranty coverage. Fleet operators consolidating procurement through vehicle-as-a-service contracts compress aftermarket margins in commercial vehicle segments.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure sensors against OEM-approved vendor lists. India's PLI scheme for automotive electronics attracts angle sensor assembly to serve Maruti Suzuki and Tata Motors platforms.
- Tier-1 Suppliers:Bosch, Continental, and DENSO integrate sensors into electromechanical power steering modules. Backward integration into captive semiconductor fabrication sustains margin control across torque sensor lines.
Tier-1 suppliers capture specification authority; OEMs are expanding direct vendor relationships fastest.
Technology:
Electromagnetic immunity and software configurability separate premium from commodity tiers.
- Electromechanical:Contact-based potentiometers and Hall-effect devices dominate cost-sensitive hydraulic steering applications. Legacy production lines strain working capital efficiency as electric power steering displaces hydraulic architectures.
- Optical:LED-photodiode pairs encode position through shutter wheels or code discs. Limited penetration due to contamination sensitivity in underhood thermal cycling environments.
- Magnetoresistive:Anisotropic magnetoresistive and tunnel magnetoresistive elements detect magnetic field rotation without physical contact. This technology material dominates new platform development due to inherent immunity to electromagnetic interference in 800-volt electric vehicle architectures.
- Capacitive:Variable capacitance structures measure displacement through dielectric changes. Emerging adoption in steer-by-wire prototypes where non-contact durability exceeds magnetic solutions.
Magnetoresistive platforms command the premium tier; capacitive sensing is climbing the fastest from prototype to production.
Application:
Autonomy levels and powertrain electrification jointly determine sensor performance thresholds.
- Electric Steering:Brushless motor commutation demands high-resolution rotor position feedback. Bosch and Continental field-test hybrid torque-angle modules for 2027 platform launches.
- Hydraulic Steering:Engine-driven pump systems require minimal electronic feedback beyond rack limit detection. Dual-track manufacturing obligations strain supplier working capital efficiency.
- Active Steering:Variable ratio systems overlay superimposed angles through planetary gearsets. German OEM procurement concentrates in Stuttgart and Munich development clusters.
- Automated Driving:Redundant torque and angle sensing pathways satisfy functional safety requirements for hands-free operation. EU AI Act algorithmic transparency requirements demand traceable sensor calibration data from manufacturing through end-of-life.
Electric steering anchors current volume; automated driving applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steering sensor trade flows reflect a structural deficit in North American electromechanical assembly against German and Japanese component surpluses. Export intensity concentrates in precision magnetoresistive elements from Stuttgart engineering clusters, while import dependency shapes procurement strategies in emerging EV manufacturing bases.
Germany
EU Green Deal fleet mandates accelerate electric power steering penetration across Volkswagen and BMW platforms. KBA type-approval protocols enforce ISO 26262 functional safety certification for torque sensor modules. Stuttgart and Munich anchor 60% of European steering sensor assembly capacity, with Bosch and Continental integrating captive semiconductor fabrication into electromechanical module production.
United States
NHTSA automated vehicle guidance for Level 2+ systems mandates redundant torque and angle sensing pathways in Detroit Three platforms. EPA fuel economy rules indirectly sustain hydraulic steering sensor demand in heavy-duty commercial fleets. Michigan's automotive engineering corridor faces mechatronics talent scarcity as universities struggle to graduate sufficient functional safety engineers.
China
MIIT new energy vehicle production quotas drive BYD and NIO procurement of high-voltage-compatible magnetoresistive sensors. GB standards for automotive electromagnetic compatibility shape sensor validation requirements for 800-volt architectures. Yangtze River Delta manufacturing clusters absorb German and Japanese tier-1 joint ventures for localized angle sensor assembly.
Japan
METI carbon neutrality roadmaps accelerate Toyota and Honda electric power steering platform launches. JIS standards for automotive electronics reliability extend sensor qualification timelines for export markets. Kansai and Nagoya industrial corridors concentrate DENSO Corporation's dedicated angle sensor capacity for Asian OEM relationships.
India
PLI scheme production-linked incentives attract angle sensor assembly investments to serve Maruti Suzuki and Tata Motors platforms. BIS automotive electronics certification requirements create qualification friction for imported sensor modules. Tamil Nadu and Gujarat manufacturing zones concentrate vehicle assembler procurement against OEM-approved vendor lists.
Automotive Steering Sensors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a bifurcated structure. The vendor base separates between electromechanical module assemblers with captive semiconductor fabrication and discrete sensor specialists supplying magnetoresistive elements. Three archetypes dominate: integrated tier-1s with backward integration into ASIC design, regional component fabricators serving single OEM relationships, and fabless sensor designers licensing magnetoresistive IP. Competitive moves concentrate on strategic partnerships for 800-volt architecture qualification and geographic expansion through India's PLI scheme manufacturing offsets.
Among integrated German engineering conglomerates, Robert Bosch GmbH and Continental AG exemplify the captive-fabrication archetype, anchoring European supply through in-house semiconductor production for torque sensor lines. DENSO Corporation represents the Asia-Pacific platform specialist, occupying a position defined by dedicated angle sensor capacity and entrenched OEM relationships. These three entities illustrate how regional engineering clusters crystallize around distinct competitive moats—semiconductor integration in Stuttgart, electromechanical module assembly in Munich, and Asian platform exclusivity in Kariya.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| HELLA GmbH & Co. KGaA |
| Honeywell Inc. |
| Sensata Technologies |
| NXP Semiconductors |
| Infineon Technologies AG |
| Methode Electronics Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwanese foundry nodes for automotive-grade ASICs is compressing sensor module availability and amplifying pricing power for integrated tier-1 suppliers with captive semiconductor fabrication. This utilization squeeze propagates through German electromechanical assembly clusters, forcing procurement managers toward long-term offtake commitments to secure magnetoresistive element supply.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing differentiation across ISO 26262 ASIL-D certified premium modules, standard electric power steering sensors, and economy-grade hydraulic position sensors. Price differentiation rests on functional safety certification tier and volume scale commitments, with fleet operators consolidating through vehicle-as-a-service contracts exhibiting the highest price sensitivity while German premium OEMs prioritize traceability over unit cost. Cost compression in angle sensor tiers is intensifying because tier-2 specialists lack backward integration into magnetoresistive wafer supply.
Supply Chain Analysis
TSMC and GlobalFoundries hold dominant foundry capacity for steering sensor ASICs, while Bosch and Continental maintain captive semiconductor fabrication in Germany and Austria. Geographic supply concentrates in Germany, Taiwan, and Japan, with raw material dependencies spanning rare-earth magnetic elements, silicon carbide substrates, and high-temperature epoxy molding compounds. Single-source vulnerability in magnetoresistive wafer supply from German sputtering equipment vendors creates systemic exposure. Distribution runs through OEM-approved vendor lists with direct digital procurement platforms compressing traditional tier-1 mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration data services and blockchain-anchored provenance tracking are expanding faster than hardware unit sales, creating recurring-revenue attach opportunities for vendors with firmware-update infrastructure.
For Market Incumbents: Entrench specification authority by deepening backward integration into magnetoresistive wafer fabrication and securing ISO 26262 ASIL-D certification ahead of NHTSA Level 2+ mandate acceleration. Fabless sensor designers with licensed IP threaten margin pools in angle sensor tiers; priority investment in software-defined vehicle firmware update capability locks in platform stickiness. For New Entrants and Emerging Players: India's underpenetrated angle sensor assembly market offers white-space entry through PLI scheme manufacturing offsets serving Maruti Suzuki and Tata Motors platforms. Capacitive sensing prototypes for steer-by-wire architectures represent the most penetrable technology segment; direct-to-OEM digital procurement bypasses entrenched tier-1 relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated tier-1s with software update infrastructure and long-term vehicle-as-a-service contracts. The 5-10 year viability window favors captive-fabrication archetypes over fabless designers facing foundry allocation risk. Monitor NHTSA automated vehicle guidance revision timing as inflection signal for redundant sensor pathway demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetoresistive Wafer Backward Integration | Bosch and Continental secure margin control against foundry volatility in Taiwan. |
| ISO 26262 ASIL-D Certification Acceleration | NHTSA Level 2+ mandates compress qualification timelines for redundant torque-angle modules. |
| India PLI Manufacturing Footprint | Local angle sensor assembly captures Maruti Suzuki and Tata Motors procurement shifts. |
| Software-Defined Vehicle Firmware Infrastructure | Over-the-air calibration updates create recurring revenue attach beyond hardware sales. |
| Blockchain-Anchored Sensor Provenance | EU AI Act algorithmic transparency requirements demand traceable manufacturing data. |
Study Parameters
A standing panel of OEM platform engineers, tier-1 supplier procurement directors, aftermarket distribution managers, and functional safety validation leads provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EU type-approval databases, vehicle production registration data, and SEC disclosures from listed automotive electronics suppliers. Bottom-up sensor unit demand modeling triangulated against top-down electric power steering penetration forecasts.
Scenario bracketing around NHTSA automated vehicle guidance implementation pace and EU Green Deal fleet mandate enforcement intensity shaped the analytical framework. Segmentation dimensions spanned sensor type, propulsion architecture, vehicle class, OEM tier positioning, and regional production cluster. CAGRs were derived from electric power steering platform launch schedules and magnetoresistive technology adoption curves across 800-volt architectures.
Practitioners should monitor foundry allocation announcements from Taiwan, NHTSA Level 2+ certification timeline revisions, and EU AI Act implementing guidance for early signals of forecast deviation. Quarterly review of KBA type-approval volumes, MIIT new energy vehicle production quotas, and tier-1 supplier backlog disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Current Sensor Market