
 Global Solar Power Windows Market | 2026-2036
Global Solar Power Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar Power Windows Market Outlook
Modular facade bundling is expanding as the dominant procurement configuration, allowing developers to source photovoltaic glazing, framing, and power electronics as unified building envelopes rather than discrete trades. Onyx Solar anchors this shift through vertical integration across transparent solar cell manufacturing and curtain wall system fabrication. SolarWindow Technologies differentiates by specializing in organic photovoltaic coatings applied to existing glass substrates. Ubiquitous Energy competes on technology leadership in near-infrared harvesting transparent cells that preserve visible light transmission.
Solar power windows incorporate thin-film or organic photovoltaic layers deposited onto transparent glass substrates, converting ultraviolet and near-infrared light into electricity while maintaining visible transparency for interior illumination. Photovoltaic glass dominates current installations due to mature supply chains and predictable performance warranties, while organic photovoltaics represent the fastest-expanding technology segment as manufacturing yields improve and material costs decline. BIPV technology commands the deepest margin pools where structural glazing and electrical generation merge into single specification packages.
The EU Green Deal and F-Gas Regulation shape product standards by mandating lower embodied carbon in building materials and restricting fluorinated greenhouse gases used in conventional insulation. The EPA and state-level renewable portfolio standards in California and New York drive demand through compliance obligations and incentive eligibility. Stakeholders must monitor how evolving grid interconnection rules from FERC and national regulators affect the economic viability of distributed facade generation in mixed-use developments.
Market Dynamics
Modular facade bundling is compressing traditional trade separations between glazing contractors and electrical integrators, forcing photovoltaic suppliers to absorb curtain wall engineering capabilities or surrender specification control to vertically integrated building envelope specialists.
Growth Catalysts
- EU Green Deal embodied carbon mandates:New construction in Germany and France must demonstrate reduced lifecycle emissions, accelerating BIPV facade procurement as developers seek dual compliance with energy performance and material carbon rules.
- Japan METI grid interconnection streamlining:Simplified distributed generation protocols in Tokyo and Osaka metropolitan zones reduce project approval timelines, concentrating developer interest in high-rise commercial retrofits.
- Organic photovoltaic yield improvements:Manufacturing process refinements are lowering material waste rates and expanding viable substrate sizes for transparent solar coatings.
Market Restraints
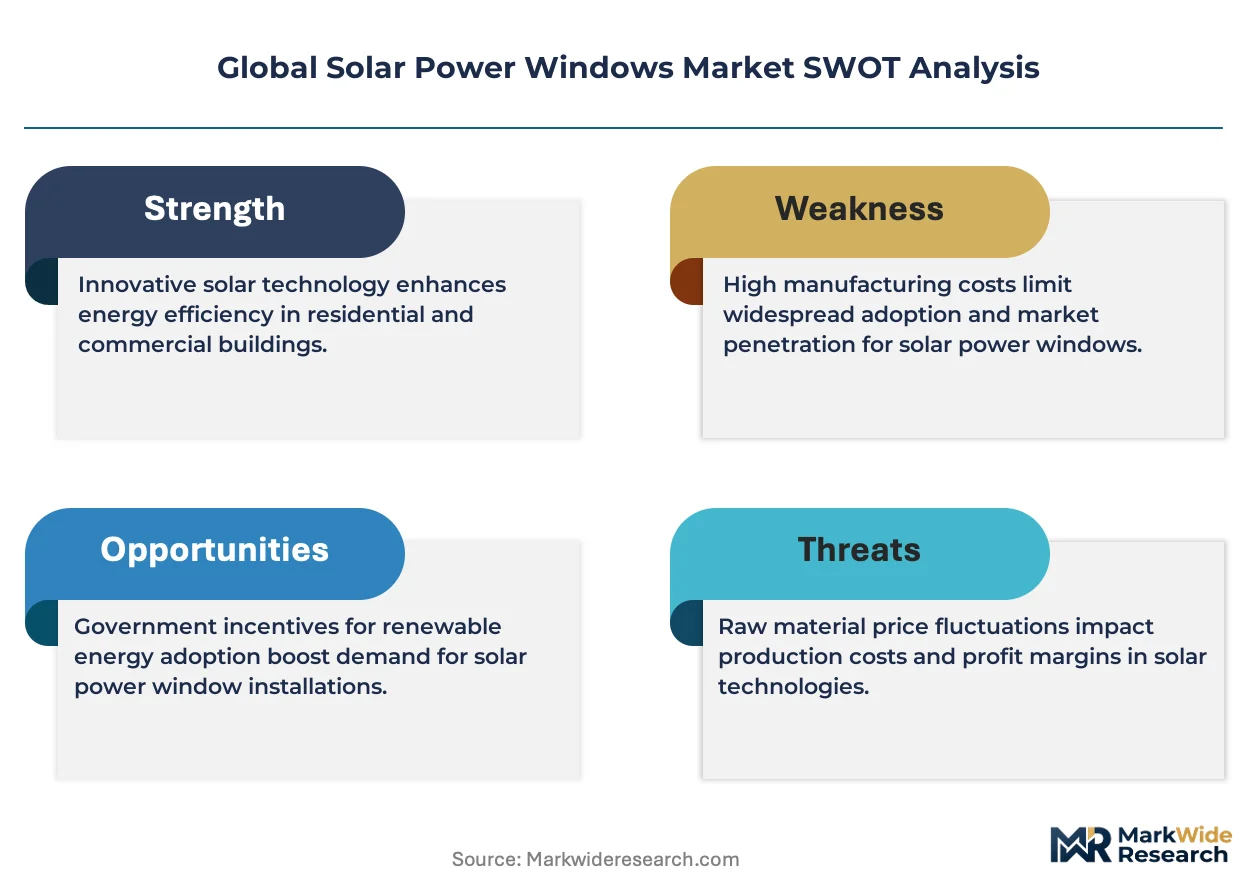
- Indium supply concentration:Thin-film transparent conductive oxide production depends on Chinese and Korean indium refining capacity, exposing photovoltaic glass manufacturers to input cost volatility and export restriction risk.
- Fluorinated gas regulatory friction:The EU F-Gas Regulation restricts conventional insulating gas options for high-performance glazing, forcing costly reformulation of vacuum-insulated photovoltaic units.
- Building-integrated electrical performance uncertainty:Facade-mounted generation suffers from orientation-dependent output variability that standard rooftop warranties do not address, limiting institutional investor comfort.
Strategic Opportunities
- India PLI scheme for solar manufacturing:Production-linked incentives for domestic photovoltaic component fabrication create localized supply chain options for transparent cell and module assembly serving South Asian commercial construction.
- Near-infrared harvesting convergence:Transparent organic photovoltaics that capture non-visible wavelengths while preserving daylighting are opening specification pathways in museum, healthcare, and retail environments where glare control is paramount.
- California Title 24 compliance pathways:The state's building energy code creates mandatory demand for on-site renewable generation in new commercial construction, with photovoltaic glazing qualifying for streamlined compliance verification.
Industry Challenges
- Facade-electrical integration skill scarcity:Project execution requires professionals conversant in both curtain wall structural engineering and distributed power electronics, a dual competency rarely housed within single contracting firms.
- Multi-jurisdiction certification timelines:Photovoltaic glazing must satisfy both building safety codes and electrical generation standards, with divergent approval processes across US states and EU member countries extending pre-construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar Power Windows Market |
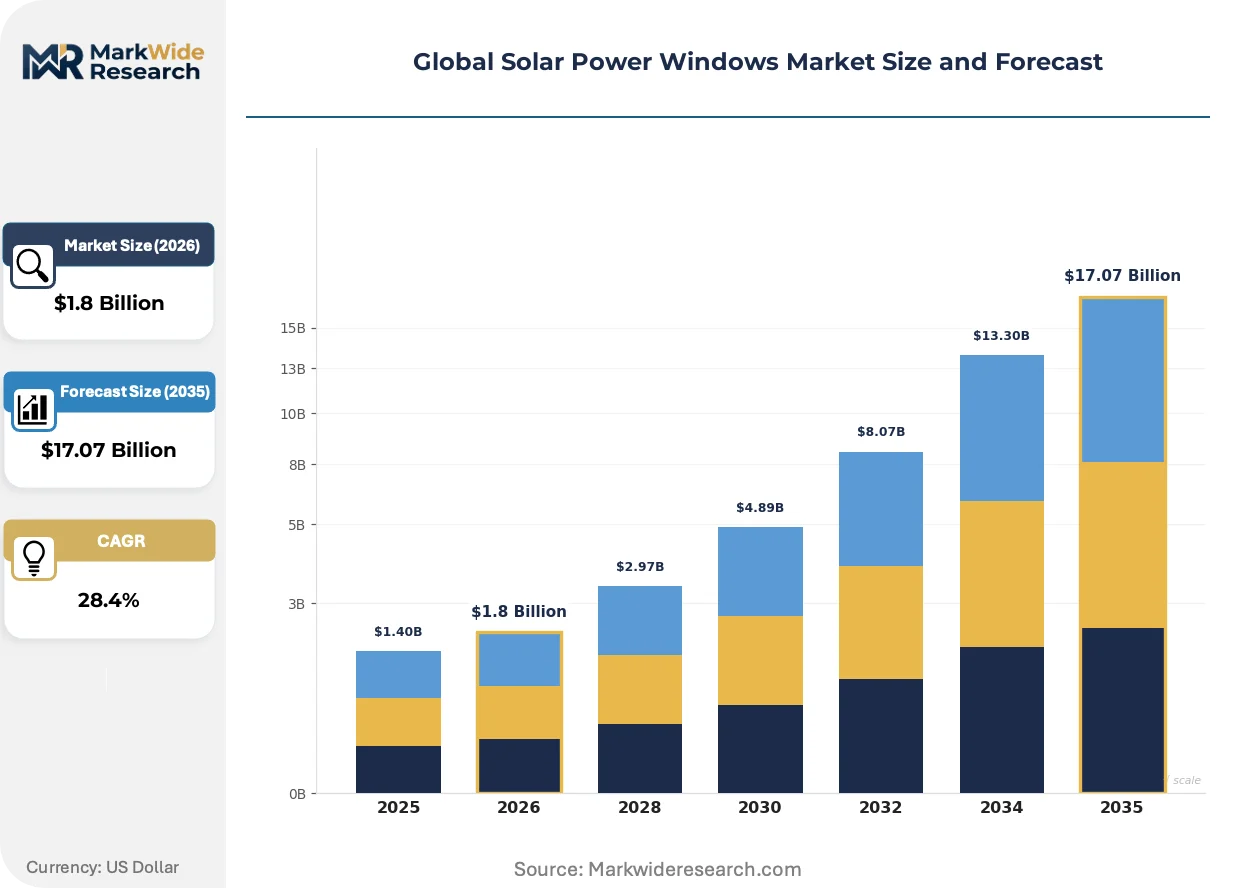
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Glass, Transparent Solar Cells, Integrated Windows, Smart Windows End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Infrastructure Projects Technology: CIGS, Crystalline Silicon, BIPV, Organic Photovoltaics Installation Type: Retrofit, New Construction, On-Site, Off-Site |
| Companies Covered | Ubiquitous Energy, SolarWindow Technologies, Onyx Solar, Polysolar, Brite Solar, Solaria Corporation, Physee, EnergyGlass, Sunpartner Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar Power Windows Market Strategic Shifts
Transparent photovoltaic technology is crossing performance thresholds that enable functional substitution of conventional architectural glass, with manufacturing scale and installation methodology evolving in parallel to capture specification momentum in commercial envelope design.
Perovskite-silicon tandem architectures are converging with transparent electrode deposition techniques to harvest broader solar spectra while maintaining visible light transmission above sixty percent. High-performance building developers in Switzerland and the Netherlands are piloting these configurations in atrium and skylight applications. The structural consequence is compressing the efficiency gap between transparent and opaque photovoltaic surfaces, eroding a long-standing barrier to facade integration.
The EU Corporate Sustainability Reporting Directive is mandating granular disclosure of embodied carbon in construction materials, with photovoltaic glazing suppliers now required to provide environmental product declarations validated by third-party assessors. Industrial consequence includes accelerated supplier consolidation as smaller fabricators lack lifecycle assessment documentation capacity. German and French commercial developers are responding by pre-qualifying only envelope suppliers with established EPD libraries, reshaping competitive access to public-sector-adjacent projects.
Building owners are unbundling facade procurement from general contractor packages, establishing direct relationships with photovoltaic glazing specialists who assume performance risk for both weather protection and energy generation. This disintermediation is displacing traditional curtain wall subcontractors in UK and Nordic markets where power purchase agreement structures favor single-point accountability. The shift is most visible in London and Copenhagen mixed-use towers where lease pricing now incorporates guaranteed renewable output from integrated envelope systems.
Global Solar Power Windows Market Segmentation
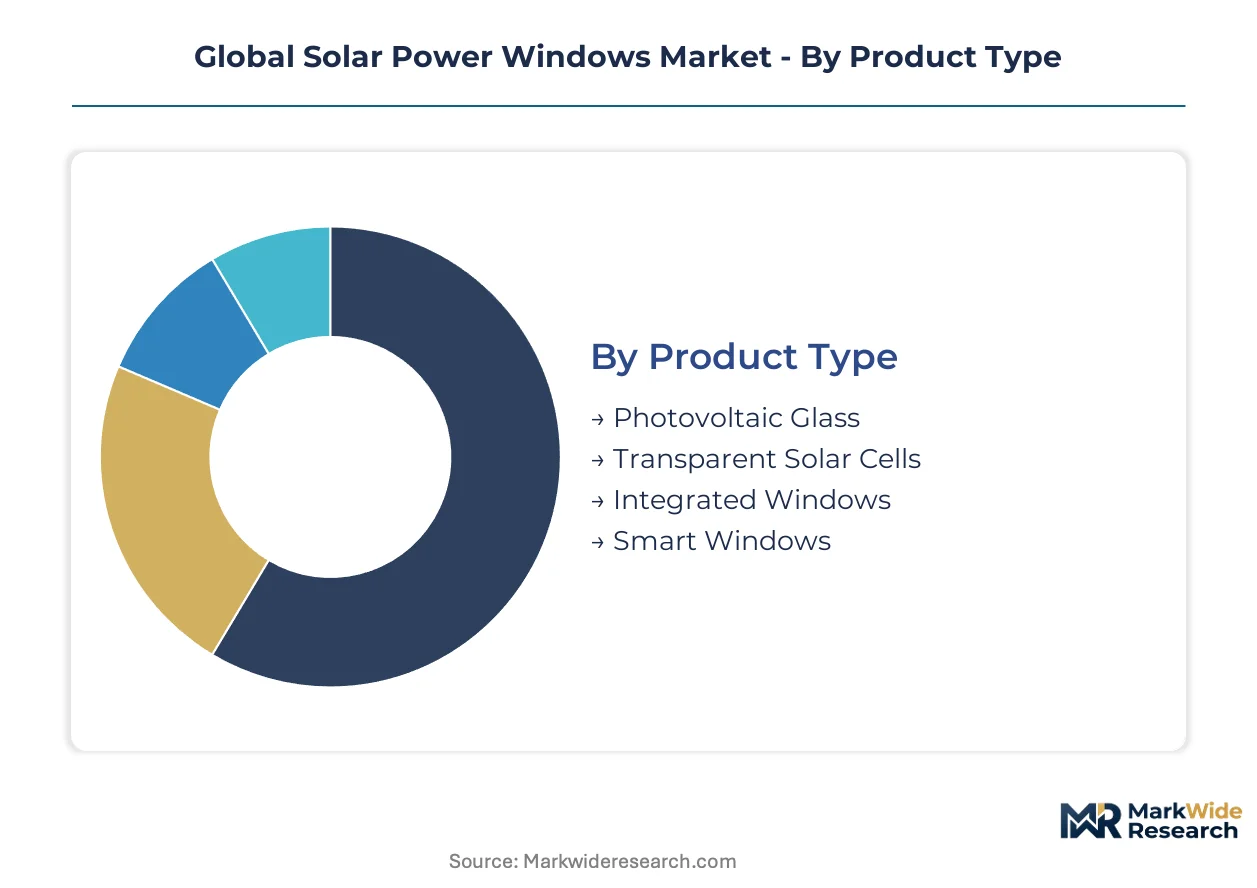
Product architecture, buyer sophistication, and installation context fragment demand across incompatible specification pathways. Each segmentation dimension isolates distinct margin pools and technical competency requirements for suppliers competing in transparent photovoltaic envelope systems.
Product Type:
Buyer procurement sophistication separates facade specialists seeking unified envelope performance from electrical integrators prioritizing generation yield.
- Photovoltaic Glass:Thin-film semiconductor layers deposited onto transparent substrates deliver predictable electrical output with established warranty structures. German and Dutch commercial developers favor this category for atrium and curtain wall applications where weather protection and generation must share single-source accountability.
- Transparent Solar Cells:Near-infrared harvesting architectures preserve visible light transmission above sixty percent while capturing non-visible wavelengths. Swiss museum and Nordic healthcare projects specify these for daylight-sensitive environments where glare control is paramount.
- Integrated Windows:Factory-assembled units combining photovoltaic glazing with thermal breaks and framing systems. Demand concentrates in UK mixed-use towers where lease pricing incorporates guaranteed renewable output.
- Smart Windows:Electrochromic or thermochromic layers paired with photovoltaic generation for dynamic solar control. California Title 24 compliance pathways accelerate specification in new commercial construction.
Photovoltaic Glass leads volumes today; Transparent Solar Cells is gaining share fastest.
End User:
Project scale and capital structure determine whether buyers prioritize first-cost minimization or lifecycle performance contracting.
- Commercial Buildings:High-rise office and retail developers in Tokyo and Osaka metropolitan zones leverage Japan METI streamlining for distributed generation approvals. Power purchase agreement structures favor single-point envelope accountability.
- Infrastructure Projects:Airports, transit hubs, and public facilities with extended ownership horizons absorb higher first costs for integrated BIPV systems. EU Green Deal embodied carbon mandates accelerate procurement for German and French public-sector-adjacent developments.
- Residential Buildings:Single-family and low-rise multifamily construction favors retrofit-friendly transparent solar coatings over full facade replacement.
- Industrial Facilities:Manufacturing and warehouse developers prioritize rooftop generation over facade integration due to simpler orientation optimization and lower structural load requirements.
Commercial Buildings dominates current procurement; Infrastructure Projects shows the steepest expansion trajectory.
Technology:
Manufacturing yield maturity and material supply security separate bankable technologies from pilot-scale alternatives.
- Organic Photovoltaics:Solution-processed active layers enable roll-to-roll deposition onto flexible glass and polymer substrates. Manufacturing refinements are lowering material waste rates and expanding viable substrate sizes for transparent solar coatings.
- BIPV:Building-integrated photovoltaic systems merge structural glazing with electrical generation in single specification packages. This category commands the deepest margin pools where envelope performance and energy output share warranty terms.
- CIGS:Copper indium gallium selenide thin-film architectures offer favorable temperature coefficients for facade-mounted applications. Indium supply concentration from Chinese and Korean refining capacity exposes manufacturers to input cost volatility.
- Crystalline Silicon:Mature supply chains and predictable performance warranties dominate opaque rooftop installations. Transparency requirements limit applicability in full vision glazing applications.
Crystalline Silicon anchors rooftop-adjacent volumes; Organic Photovoltaics is climbing the fastest in transparent applications.
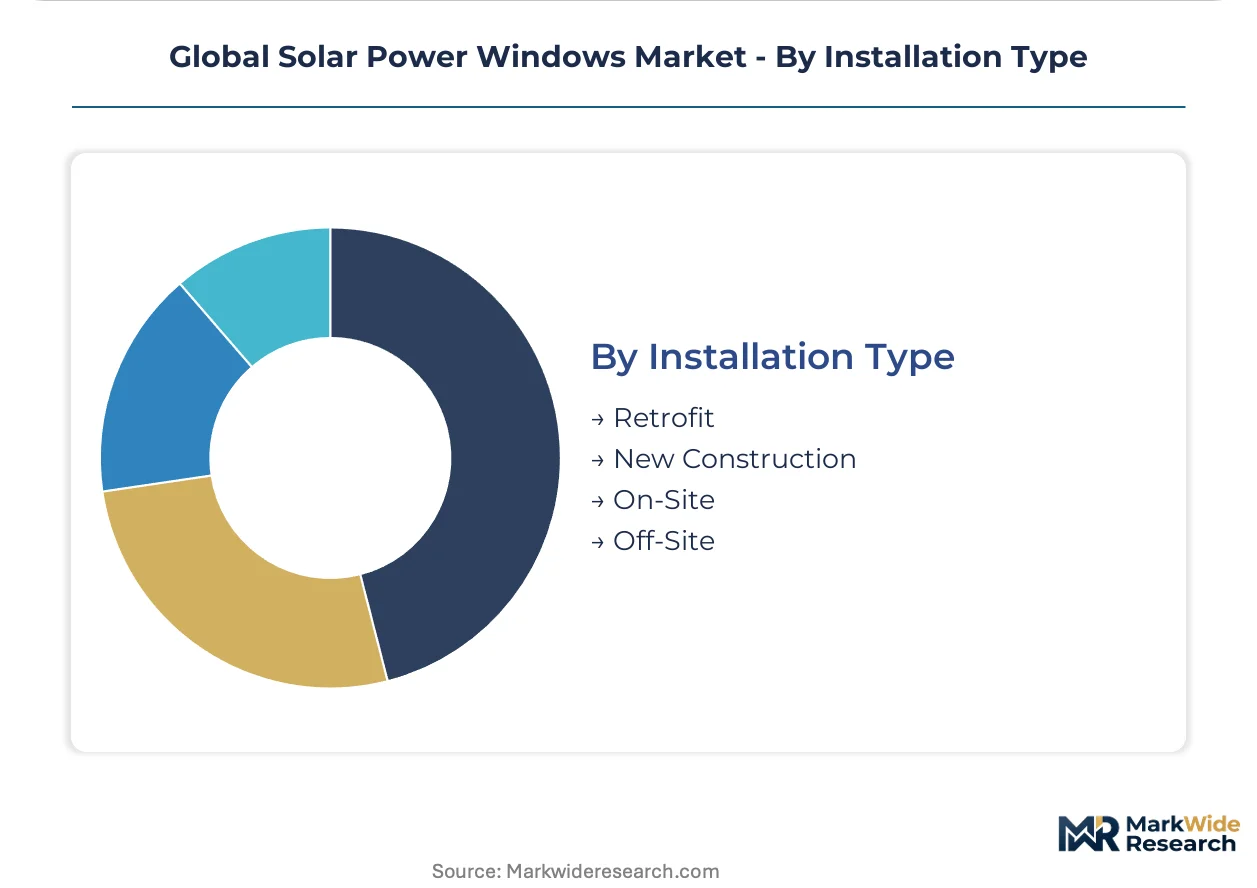
Installation Type:
Project delivery method and site constraints determine whether fabrication occurs under factory quality control or field-adjusted conditions.
- New Construction:Design-phase integration enables optimized electrical routing and structural loading for photovoltaic facades. Copenhagen and London mixed-use towers increasingly unbundle envelope procurement from general contractor packages.
- Retrofit:Existing building upgrades demand minimally invasive installation and compatibility with legacy structural systems. SolarWindow Technologies specializes in organic photovoltaic coatings applied to existing glass substrates for this pathway.
- On-Site:Field assembly of photovoltaic glazing within curtain wall framing accommodates project-specific dimensional tolerances.
- Off-Site:Factory fabrication of complete facade modules under controlled conditions reduces weather-dependent schedule risk and improves quality consistency.
New Construction leads specification volumes today; Retrofit is expanding most quickly as building stock renovation accelerates under EU decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transparent photovoltaic technology first achieved commercial scale in European building envelope applications during the mid-2010s, with Swiss and German facade specialists pioneering integrated glazing systems. This established the regulatory and certification frameworks now diffusing across North American and Asian construction markets.
United States
California Title 24 mandates on-site renewable generation for new commercial construction, creating compliance-driven procurement of photovoltaic glazing in Los Angeles and San Francisco high-rise developments. The EPA administers embodied carbon disclosure requirements for federal-adjacent projects. Developer concentration in Manhattan and Boston financial districts accelerates direct envelope procurement unbundled from general contractor packages.
Germany
EU Green Deal lifecycle emissions rules compel developers in Frankfurt and Munich to specify BIPV facades for dual energy-carbon compliance. The national building energy code (GEG) tightens envelope performance standards annually. Industrial clustering in the Rhine-Ruhr corridor supports vertically integrated curtain wall fabricators with captive photovoltaic glazing capacity.
Japan
METI streamlined grid interconnection protocols reduce approval timelines for distributed facade generation in Tokyo and Osaka metropolitan office markets. The national regulator concentrates developer interest in high-rise commercial retrofits through simplified technical standards. Yokohama and Nagoya construction consortia now specify factory-assembled integrated window units with guaranteed renewable output.
United Kingdom
London mixed-use towers increasingly structure lease pricing around guaranteed generation from photovoltaic envelope systems. The national building safety regulator mandates post-Grenfell facade performance accountability favoring single-source envelope specialists. Manchester and Birmingham commercial developments follow London procurement patterns for power purchase agreement compatibility.
India
The PLI scheme for solar manufacturing attracts domestic transparent cell and module assembly investment serving South Asian commercial construction. The Central Electricity Authority regulates distributed generation interconnection standards. Hyderabad and Bengaluru IT campus developers pilot near-infrared harvesting glazing for daylight-sensitive office environments.
Global Solar Power Windows Market Competitive Environment
The competitive structure tilts toward vertically integrated envelope specialists controlling specification access through unified curtain wall and photovoltaic performance warranties. Market concentration remains moderate with tiering between technology originators and manufacturing-scale fabricators. Two strategic archetypes dominate: transparent cell technology developers pursuing licensing revenue, and building envelope integrators capturing installation margin through captive glazing supply. Dominant competitive moves include backward integration into transparent conductive oxide deposition and strategic partnerships with curtain wall engineering firms to compress facade-electrical integration timelines.
Among technology-originator archetypes, Ubiquitous Energy and SolarWindow Technologies exemplify divergent pathways in transparent photovoltaic commercialization. Onyx Solar anchors the vertically integrated fabricator tier with unified manufacturing across transparent solar cell production and curtain wall system fabrication. These three entities occupy distinct competitive positions without overlapping core capabilities, enabling segmented market development rather than direct confrontation.
| Leading Market Players |
|---|
| Ubiquitous Energy |
| SolarWindow Technologies |
| Onyx Solar |
| Polysolar |
| Brite Solar |
| Solaria Corporation |
| Physee |
| EnergyGlass |
| Sunpartner Technologies |
| Others |
Value Chain & Pricing Dynamics
Backward integration into transparent conductive oxide deposition anchors supply position and pricing power for photovoltaic glazing manufacturers, compressing margin capture from raw material refinement through finished facade installation. Onyx Solar's unified manufacturing across transparent solar cell production and curtain wall system fabrication exemplifies this pattern, enabling single-source accountability that commands premium specification access in German and Dutch commercial developments.
Pricing Analysis
Project-based long-term offtake contracts with guaranteed renewable output clauses dominate commercial procurement, with price differentiation hinging on certification grade (third-party validated EPDs under EU Corporate Sustainability Reporting Directive) and volume scale (modular facade bundling for high-rise towers versus discrete trade sourcing). Cost compression in standard photovoltaic glass tiers is intensifying because indium supply volatility from Chinese and Korean refining capacity feeds input price uncertainty. Infrastructure project developers with extended ownership horizons exhibit lowest price sensitivity, while residential retrofit buyers prioritize minimally invasive transparent solar coatings with lower absolute cost exposure.
Supply Chain Analysis
Returns and refurbishment flows remain nascent in transparent photovoltaic envelopes, though end-of-life glass recovery programs in Germany and the Netherlands are piloting remanufacturing pathways for semiconductor layer reclamation. Manufacturing concentration centers on China for indium refining and transparent conductive oxide substrates, Germany for curtain wall system integration, and Japan for near-infrared harvesting cell architectures. Raw material dependencies encompass indium for thin-film electrodes, silver for electrical busbars, and specialized glass substrates with low-iron content. Single-source vulnerability in Chinese indium processing creates tariff exposure risk under evolving trade frameworks. Distribution runs through vertically integrated envelope specialists who assume performance risk for both weather protection and energy generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar power windows market reads as a late-cycle quality story where procurement is shifting toward premium specifications with validated environmental product declarations and guaranteed renewable output warranties.
For Market Incumbents: Anticipate margin compression from organic photovoltaic yield improvements by accelerating captive supply of transparent conductive oxides and consolidating curtain wall engineering capabilities. Indium supply concentration from Chinese and Korean refining capacity represents the critical vulnerability requiring geographic diversification or alternative electrode material R&D. Certification investment in third-party EPD libraries under EU Corporate Sustainability Reporting Directive secures access to German and French public-sector-adjacent projects. For New Entrants and Emerging Players: Begin with retrofit-friendly transparent solar coatings applied to existing glass substrates, where building stock renovation under EU decarbonization mandates creates penetrable white-space with lower capital intensity than new construction facade integration. California Title 24 compliance pathways for on-site renewable generation offer a concentrated go-to-market angle through direct relationships with commercial developers unbundling envelope procurement from general contractor packages. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated envelope specialists because building owners are unbundling facade procurement and establishing direct relationships with single-source accountability providers. The five-to-ten year viability window favors acquisition targets with established EPD libraries and captive transparent cell manufacturing. The signal to watch is FERC and national regulator evolution of grid interconnection rules affecting distributed facade generation economics in mixed-use developments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transparent Conductive Oxides | Captive indium processing reduces exposure to Chinese and Korean supply volatility. |
| Third-Party EPD Certification Investment | EU Corporate Sustainability Reporting Directive mandates validate competitive access to German developments. |
| Curtain Wall Engineering Capability Acquisition | Single-source envelope accountability displaces traditional glazing subcontractors in UK and Nordic markets. |
| Near-Infrared Harvesting Technology Licensing | Swiss museum and Nordic healthcare specifications favor glare-controlled daylighting preservation. |
| Factory-Assembled Integrated Window Scale-Up | Off-site fabrication reduces weather-dependent schedule risk for Copenhagen and London mixed-use towers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facade procurement directors at German and Dutch commercial developers, curtain wall engineering leads, photovoltaic glazing manufacturing executives, and distributed generation regulatory specialists with secondary validation. Secondary sources encompassed EU Green Deal implementation guidance, METI grid interconnection protocols, California Title 24 compliance documentation, and environmental product declaration registries. Bottom-up project pipeline tracking and top-down construction market sizing were triangulated to anchor volume estimates.
Comparable historical reference periods spanning pre-pandemic baseline, supply disruption interval, and policy acceleration phase anchored the forecast window across the analysis window. Segmentation dimensions modeled encompassed product architecture (photovoltaic glass, transparent solar cells, integrated windows, smart windows), end-user capital structure (commercial buildings, infrastructure projects, residential, industrial), technology maturity (organic photovoltaics, BIPV, CIGS, crystalline silicon), and installation context (new construction, retrofit, on-site, off-site). CAGRs were derived from installation volume trajectories correlated with regulatory mandate timelines and grid interconnection standard evolution.
Several conditions sit outside the modeled scope, including perovskite-silicon tandem commercialization timelines and fluorinated gas regulatory friction resolution under EU F-Gas Regulation. Forecasts reflect assumptions regarding manufacturing yield improvements and material cost trajectories that could revise substantially with indium supply disruption or organic photovoltaic substrate size breakthroughs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Concentrated Photovoltaic System Market