
 UAE Laser Hair Removal Market | 2026-2036
UAE Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Laser Hair Removal Market Intelligence
Multi-source equipment procurement is decoupling from the single-brand loyalty that historically dominated UAE clinic operations. Alma Lasers Ltd leverages its Middle East service infrastructure to sustain long-term contracts with hospital-affiliated dermatology centers. Candela Medical competes through flexible leasing programs that lower capital barriers for independent medical spas in Dubai Healthcare City. Aesthetica Clinic anchors its reputation on physician-supervised protocols, differentiating from salon-grade operators in Sharjah and Ajman.
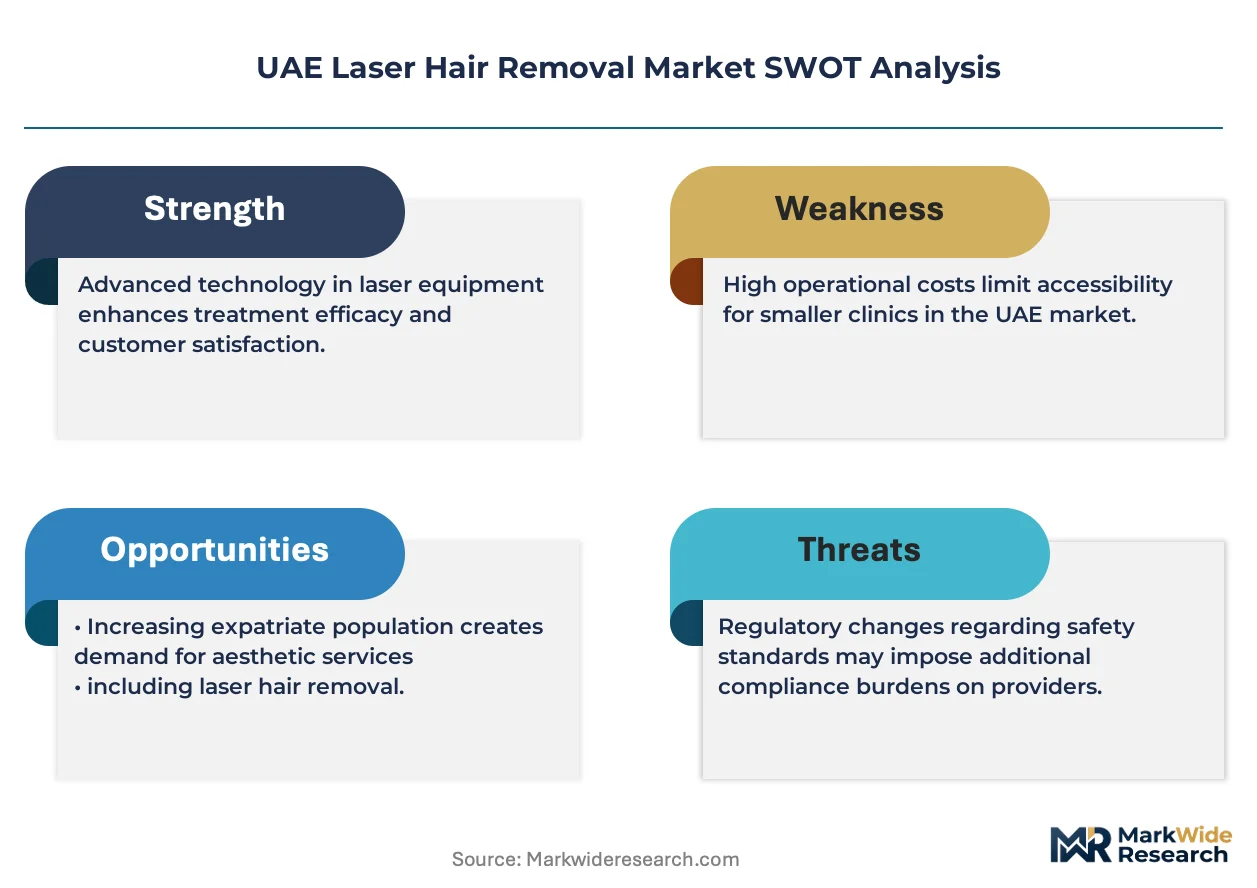
Laser hair removal employs selective photothermolysis, wherein melanin in the hair follicle absorbs pulsed laser energy at wavelengths between 755 nm and 1064 nm to thermally disable regrowth without damaging surrounding dermal tissue. The procedure serves cosmetic and medical indications, including hirsutism management and pseudofolliculitis barbae treatment in darker skin phototypes. Diode laser devices dominate installed capacity across UAE dermatology clinics due to their efficacy across Fitzpatrick skin types III through V. Medical spas represent the fastest-growing end-user channel, though dermatology clinics retain the premium pricing tier. Male demand concentrates in facial and full-body service categories, where Nd:YAG systems address thicker terminal hair with reduced post-inflammatory hyperpigmentation risk.
MOHAP and Dubai Health Authority enforce medical device registration under the UAE's centralized healthcare IT system, requiring laser manufacturers to submit clinical evidence for skin safety profiles. The country's national standards body aligns aesthetic equipment specifications with IEC 60601-1 electrical safety benchmarks, while municipal health departments conduct unannounced facility inspections. Stakeholders must monitor evolving federal versus emirate-level licensing divergences, as Abu Dhabi's Department of Health tightens physician-presence mandates that could reshape staffing models across medical spa chains.
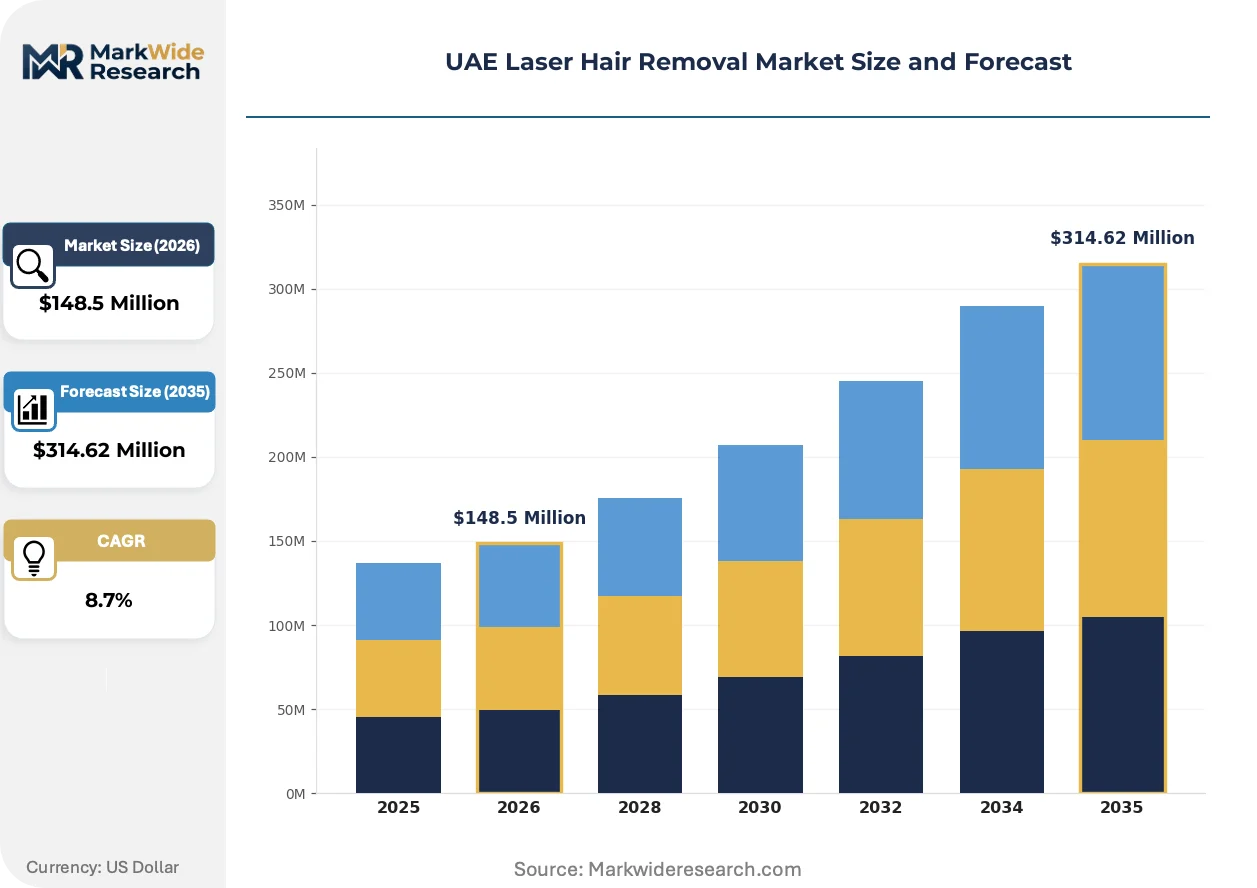
Market Dynamics
MOHAP's dual-licensing framework for medical spas is compressing operational flexibility while elevating physician-supervision mandates across Dubai and Abu Dhabi, forcing clinic chains to restructure staffing models and capital allocation.
Growth Catalysts
- Medical Tourism Inflows:Dubai Healthcare City draws cross-border patients from Saudi Arabia, Kuwait, and Oman seeking diode and alexandrite laser protocols unavailable in home markets.
- MOHAP Device Registration:Centralized aesthetic equipment oversight under the UAE's healthcare IT system validates clinical safety profiles and accelerates premium-tier provider consolidation.
- Male Grooming Normalization:Facial and full-body service categories among male consumers now outpace female demand growth in Abu Dhabi dermatology clinics.
Market Restraints
- Laser Device Import Dependence:Installed diode and Nd:YAG capacity relies on European and Israeli original equipment manufacturers, exposing clinics to currency volatility and shipping delays.
- Physician Presence Mandates:Abu Dhabi Department of Health tightening supervision requirements raises fixed labor costs for medical spa chains operating across multiple emirates.
- Electrical Safety Compliance Burden:IEC 60601-1 alignment requirements for all new device registrations extend procurement timelines and disqualify lower-tier Asian manufacturers.
Strategic Opportunities
- Sharjah and Ajman Market Development:Salon-grade operators in northern emirates lack physician-supervised positioning, creating white space for differentiated medical spa entrants.
- Pseudofolliculitis Barbae Protocols:Nd:YAG systems addressing thicker terminal hair in darker skin phototypes open medical reimbursement pathways previously restricted to cosmetic billing.
- Flexible Leasing Structures:Independent medical spas in Dubai Healthcare City access capital-light equipment deployment models unavailable to hospital-affiliated dermatology centers.
Industry Challenges
- Laser Technician Certification Gaps:MOHAP-mandated training protocols for Fitzpatrick skin type assessment lag behind device capability expansion, forcing clinics to restrict service menus.
- Post-Inflammatory Hyperpigmentation Liability:Nd:YAG wavelength selection errors in darker skin phototypes expose operators to malpractice exposure and reputational damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Laser Hair Removal Market |
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $314.62 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Diode Laser, Alexandrite Laser, Nd:YAG, IPL End User: Salons, Dermatology Clinics, Medical Spas, Home Use Gender: Female, Male, Unisex, Others Service Type: Full Body, Facial, Underarm, Bikini |
| Companies Covered | SKINIII, Aesthetica Clinic, The Private Clinic Medical & Aesthetic Centre, Alma Lasers Ltd, Kayle Aesthetic Clinic, Biolite Aesthetic Clinic, Lucia Aesthetic Clinic, Candela Medical, Aestheticon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Laser Hair Removal Market Strategic Shifts & Innovations
Device architecture and procurement logic are diverging from the single-brand loyalty that historically governed UAE clinic operations, with multi-source equipment strategies and outcome-based service contracting now reshaping competitive positioning.
Diode laser platforms with interchangeable handpiece configurations are modularizing treatment capabilities across single device footprints. Independent medical spas in Dubai Healthcare City adopt these systems to compress capital expenditure while expanding service menus. This architecture is modularizing the historical trade-off between wavelength specificity and equipment cost, enabling mid-tier operators to compete on protocol breadth previously reserved for hospital-affiliated dermatology centers.
MOHAP's aesthetic device registration requirements under the UAE centralized healthcare IT system are tightening clinical evidence standards for skin safety profiles. Manufacturers must submit Fitzpatrick skin type-specific thermal injury data, extending registration timelines and favoring established players with existing Middle East service infrastructure. Dermatology clinics in Abu Dhabi face the steepest compliance burden as the emirate's Department of Health layers additional physician-presence documentation atop federal requirements.
Service contracting is unbundling from equipment procurement as independent medical spas demand usage-based fee structures over capital purchase models. Leasing programs displace outright ownership in Dubai Healthcare City, transferring maintenance liability and technology obsolescence risk to manufacturers. This shift concentrates most visibly among mid-scale operators seeking Nd:YAG capability without the fixed asset intensity of hospital-affiliated competitors.
UAE Laser Hair Removal Market Segmentation
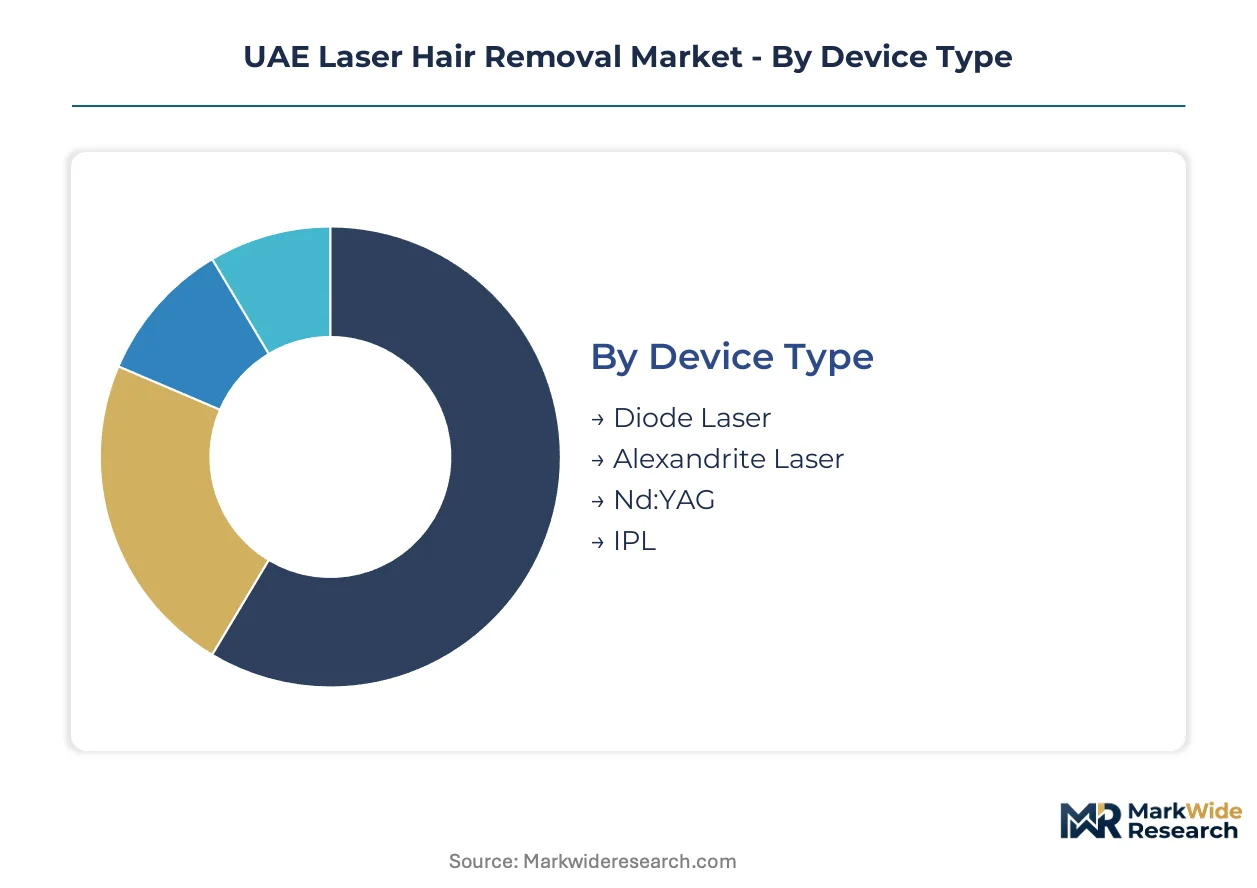
Segmentation in the UAE laser hair removal market reveals distinct regulatory burdens and capital intensity profiles across device technologies and service delivery channels. Each category carries specific MOHAP registration requirements and physician-presence mandates that reshape competitive positioning.
Device Type:
Diode and Nd:YAG systems require MOHAP clinical evidence submissions for Fitzpatrick skin type-specific thermal injury profiles, while IPL devices face lighter documentation thresholds under aesthetic equipment guidelines.
- Diode Laser:Pulsed semiconductor systems operating at 800-810 nm wavelength dominate installed capacity across Abu Dhabi and Dubai dermatology clinics. Demand concentrates among medical spas serving Fitzpatrick types III through V, where diode platforms balance melanin absorption safety with treatment speed. MOHAP's device registration timelines extend longest for diode manufacturers lacking prior Middle East service infrastructure.
- Nd:YAG:Neodymium-doped yttrium aluminum garnet systems at 1064 nm wavelength enable safe penetration through darker skin phototypes. Abu Dhibi clinics specializing in male facial hair removal and pseudofolliculitis barbae protocols drive demand, as Nd:YAG's longer wavelength minimizes post-inflammatory hyperpigmentation risk in terminal hair treatment.
- Alexandrite Laser:Chromium-doped chrysoberyl systems at 755 nm wavelength serve lighter skin phototypes with high melanin contrast requirements.
- IPL:Intense pulsed light platforms with broad-spectrum filters occupy salon-grade segments in Sharjah and Ajman where physician supervision is absent.
Leading the category by volume: Diode Laser. Growing fastest: Nd:YAG.
End User:
Capital deployment and staffing models diverge sharply across channels, with hospital-affiliated dermatology centers absorbing fixed physician costs that independent operators avoid through leasing structures.
- Dermatology Clinics:Physician-supervised facilities in Dubai Healthcare City and Abu Dhabi maintain premium pricing tiers through MOHAP-compliant protocols and Fitzpatrick-specific consultation documentation. These centers capture cross-border medical tourism flows from Saudi Arabia and Kuwait seeking diode and alexandrite treatments unavailable in home markets. Fixed labor intensity from dual-licensing mandates compresses margin flexibility.
- Medical Spas:Hybrid facilities operating under MOHAP's dual-licensing framework represent the fastest-expanding channel, particularly in Dubai where flexible equipment leasing from Candela Medical and Alma Lasers lowers capital barriers. Demand concentrates among male consumers seeking facial and full-body service categories without hospital-grade overhead.
- Salons:Non-medical operators in northern emirates face tightening exclusion as Abu Dhabi's Department of Health mandates physician presence for all laser procedures.
- Home Use:Consumer-grade IPL devices occupy minimal share due to MOHAP import restrictions on non-clinical aesthetic equipment.
Capturing premium pricing: Dermatology Clinics. Expanding most quickly: Medical Spas.
Gender:
Service menu configuration and marketing expenditure allocation now pivot toward male demand normalization, reversing historical female-centric clinic positioning.
- Male:Facial hair management and full-body grooming categories now outpace female demand growth in Abu Dhabi dermatology clinics, with Nd:YAG protocols addressing thicker terminal hair density. Male consumers from Saudi Arabia and Oman drive cross-border medical tourism volumes.
- Female:Traditional bikini and underarm service categories retain volume concentration but face slowing growth as market penetration matures among Emirati and expatriate resident populations.
- Unisex:Standardized protocol offerings across gender-neutral service menus enable operational efficiency in mid-scale medical spa chains.
- Others:Specialized consultation frameworks for non-binary consumers remain underdeveloped across UAE clinic networks.
Highest volume concentration: Female. Steepest expansion trajectory: Male.
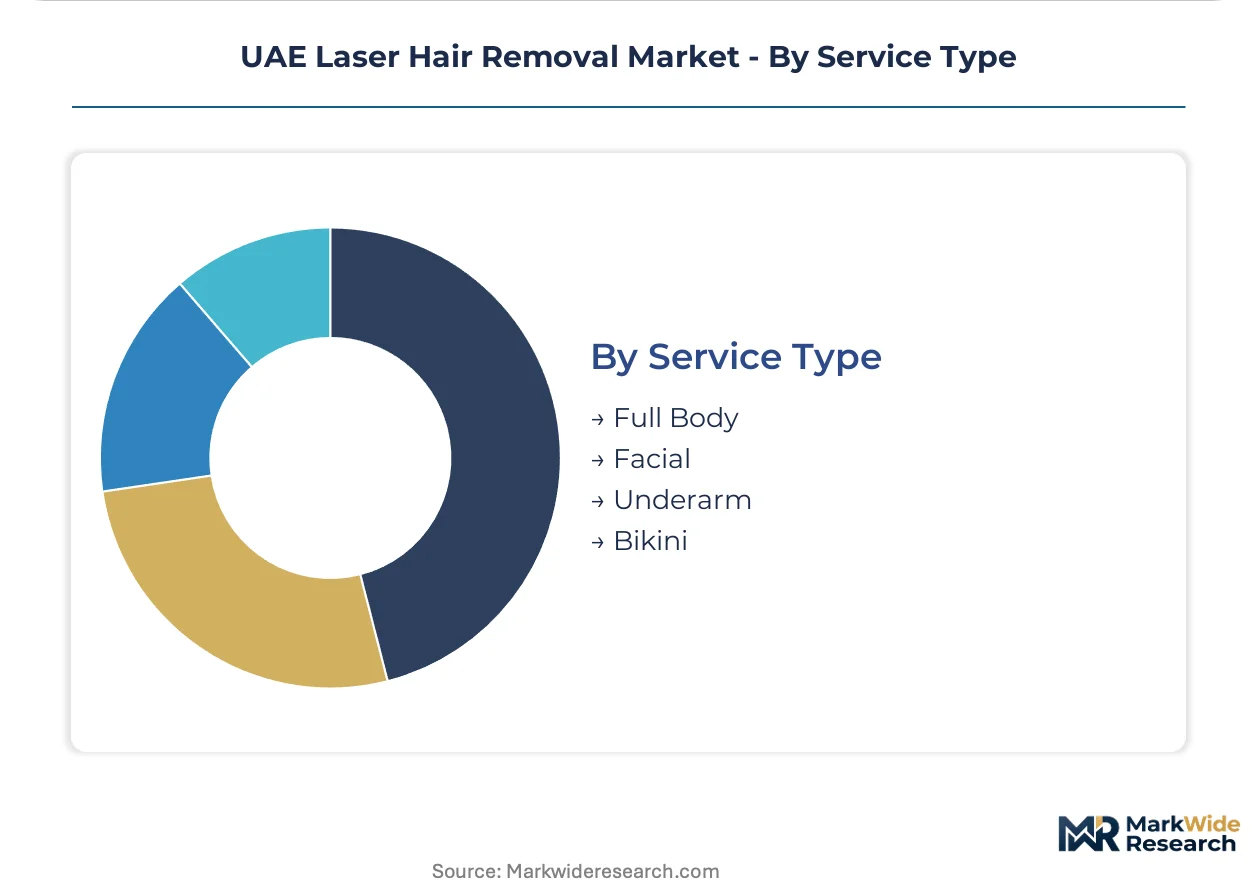
Service Type:
Treatment area selection determines equipment utilization rates and per-session revenue capture, with full-body protocols requiring modular diode platforms and extended appointment blocks.
- Full Body:Comprehensive treatment protocols spanning multiple anatomical zones demand interchangeable handpiece configurations and compressed capital expenditure through single-device footprints. Dubai medical spas adopt these modular systems to compete with hospital-affiliated dermatology centers on service breadth.
- Facial:Precision-focused Nd:YAG applications for male beard shaping and pseudofolliculitis barbae management concentrate in Abu Dhabi clinics with physician-supervised consultation protocols. Medical reimbursement pathways for hirsutism treatment differentiate facial services from purely cosmetic billing.
- Underarm:Rapid treatment cycles with minimal skin type variation enable high-throughput scheduling efficiency across all operator tiers.
- Bikini:Cultural sensitivity requirements and privacy protocols elevate staffing costs for female technician assignment in conservative emirate segments.
Dominating revenue per session: Full Body. Gaining share fastest: Facial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for laser hair removal services concentrates in Dubai and Abu Dhabi, where medical tourism infrastructure and physician-supervised clinic networks attract cross-border patients from Saudi Arabia, Kuwait, and Oman. Northern emirates present untapped expansion corridors as regulatory tightening excludes salon-grade operators.
Dubai
Medical tourism flows from Saudi Arabia and Kuwait drive diode and alexandrite laser demand in Dubai Healthcare City. MOHAP's dual-licensing framework mandates physician supervision for all medical spa operations. Dubai Marina and Downtown clusters host the highest concentration of Candela Medical and Alma Lasers Ltd equipment deployments.
Abu Dhabi
Male grooming services for facial hair management and pseudofolliculitis barbae treatment outpace female demand growth across dermatology clinics. The Department of Health tightens physician-presence documentation requirements beyond federal MOHAP standards. Corniche and Al Maryah Island medical districts absorb premium-tier capital allocation from hospital-affiliated operators.
Sharjah
Salon-grade IPL operators face exclusion as federal regulations extend physician-mandate coverage to all laser procedures. Price-sensitive resident populations seek cross-border treatment in Dubai or Ajman. Industrial zones near Sharjah International Airport concentrate logistics infrastructure for European and Israeli device imports.
Ajman
Underserved mid-income demographics create white space for differentiated medical spa entrants with flexible leasing structures. Regulatory enforcement lags Dubai and Abu Dhabi, attracting transitional operators upgrading from salon-grade services. Al Zorah and Al Nuaimia districts concentrate emerging clinic development.
Northern Emirates
Ras Al Khaimah and Fujairah host minimal installed laser capacity, with residents traveling to Dubai or Abu Dhabi for physician-supervised protocols. Federal MOHAP registration requirements for diode and Nd:YAG devices extend procurement timelines for independent entrants. Coastal tourism corridors present long-term medical spa development potential.
UAE Laser Hair Removal Market Key Industry Players
Flexible leasing program deployment dominates the current landscape as manufacturers transfer technology obsolescence risk to clinic operators. Market structure segments into three tiers: hospital-affiliated dermatology centers with fixed physician costs, independent medical spas leveraging usage-based fee structures, and salon-grade operators facing regulatory exclusion. Two strategic archetypes define positioning: equipment manufacturers with Middle East service infrastructure, and physician-supervised clinic chains differentiating on protocol safety. Competitive moves concentrate on multi-source equipment procurement and outcome-based service contracting.
Among Israel-based laser manufacturers, Alma Lasers Ltd anchors the premium-tier equipment supply vector through long-term service contracts with hospital-affiliated dermatology centers. Candela Medical, a US-based device company, exemplifies the capital-light deployment archetype through leasing programs targeting independent medical spas in Dubai Healthcare City. Aesthetica Clinic occupies a differentiated position within the physician-supervised clinic tier, leveraging consultation documentation protocols to separate from salon-grade competitors in Sharjah and Ajman.
| Leading Market Players |
|---|
| SKINIII |
| Aesthetica Clinic |
| The Private Clinic Medical & Aesthetic Centre |
| Alma Lasers Ltd |
| Kayle Aesthetic Clinic |
| Biolite Aesthetic Clinic |
| Lucia Aesthetic Clinic |
| Candela Medical |
| Aestheticon |
| Others |
Cost & Logistics Intelligence
Laser diode arrays and Nd:YAG crystal assemblies from Israeli and European original equipment manufacturers flow through Dubai's Jebel Ali logistics corridor into three-tier pricing structures across physician-supervised dermatology centers, independent medical spas, and salon-grade operators facing regulatory exclusion. This upstream component concentration grants established manufacturers like Alma Lasers and Candela Medical substantial pricing power over clinic operators absorbing currency volatility and extended procurement timelines.
Pricing Analysis
Volume concentration in facial and underarm service categories compresses per-session margins, while full-body protocols in premium dermatology clinics sustain higher pricing through physician-supervised consultation documentation and Fitzpatrick-specific safety protocols. Price differentiation rests on certification grade—MOHAP-registered devices with IEC 60601-1 alignment command premium positioning over unregistered salon-grade IPL systems. Cost compression in mid-tier medical spas is intensifying because flexible leasing structures transfer technology obsolescence risk to manufacturers while lowering capital barriers. Independent operators in Dubai Healthcare City exhibit highest price sensitivity, whereas hospital-affiliated dermatology centers in Abu Dhabi's Corniche district absorb fixed physician costs with least sensitivity.
Supply Chain Analysis
MOHAP's clinical evidence requirements for Fitzpatrick skin type-specific thermal injury data function as certification gating that filters device suppliers to established Israeli, German, and US manufacturers with Middle East service infrastructure. Raw material dependencies center on semiconductor laser diodes, neodymium-doped yttrium aluminum garnet crystals, and precision optical handpiece assemblies. Single-source vulnerability concentrates in European and Israeli OEM channels exposed to shipping delays and currency fluctuations. Distribution runs through Dubai Healthcare City procurement hubs for hospital-affiliated centers, with direct manufacturer relationships dominating independent medical spa channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE laser hair removal market has become a vertical-integration race as equipment manufacturers deepen service infrastructure control and clinic chains pursue captive patient flow through medical tourism partnerships.
For Market Incumbents: Hedge against regulatory divergence by securing dual-licensing compliance across all seven emirates before Abu Dhabi's Department of Health tightens physician-presence mandates beyond federal MOHAP standards. Prioritize backward integration into technician training certification to offset MOHAP-mandated Fitzpatrick assessment gaps that currently restrict service menus. Lock in long-term service contracts with hospital-affiliated dermatology centers to defend against Candela Medical's capital-light leasing incursions. For New Entrants and Emerging Players: Begin with Ajman's underserved mid-income demographics where regulatory enforcement lags Dubai and Abu Dhabi, creating white space for differentiated medical spa positioning between salon-grade exclusion and premium hospital overhead. Target male grooming service categories in facial and full-body protocols where Nd:YAG demand growth outpaces female segments. Pursue outcome-based service contracting with flexible equipment leasing from established manufacturers to minimize fixed asset intensity. For Investors and Strategic Acquirers: Distressed-cycle entries favor physician-supervised clinic chains with established MOHAP registration portfolios in Dubai and Abu Dhabi, as salon-grade operators face systematic regulatory exclusion. Long-term viability over a multi-year window rests on capturing medical tourism flows from Saudi Arabia, Kuwait, and Oman through Dubai Healthcare City infrastructure. Monitor MOHAP device registration timeline extensions as the inflection signal indicating consolidation pressure on smaller independent operators lacking compliance resources.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Dual-Licensing Compliance | Abu Dhabi's Department of Health layering additional physician-presence mandates reshapes staffing models across medical spa chains. |
| Flexible Equipment Leasing Programs | Candela Medical's usage-based fee structures transfer technology obsolescence risk and lower capital barriers for independent operators. |
| Medical Tourism Partnership Development | Dubai Healthcare City infrastructure captures cross-border patient flows from Saudi Arabia and Kuwait seeking unavailable diode protocols. |
| Technician Certification Investment | MOHAP-mandated Fitzpatrick skin type assessment training closes capability gaps that currently restrict service menu expansion. |
| Nd:YAG Capability Expansion | 1064 nm wavelength systems address male facial hair management and pseudofolliculitis barbae with reduced post-inflammatory hyperpigmentation risk. |
Research Approach
MOHAP device registration databases, UAE customs import records for aesthetic equipment, and IEC 60601-1 certification filings formed the secondary backbone, supplemented by primary interviews with dermatology clinic medical directors, medical spa operations managers, biomedical equipment procurement officers, and laser technician training program administrators. Bottom-up triangulation across installed device counts by emirate and top-down validation through manufacturer shipment data ensured cross-source consistency.
Historical trendline analysis of procedure volumes across Dubai, Abu Dhabi, Sharjah, and Ajman established baseline growth patterns, with projection modeling incorporating device type segmentation by wavelength technology, end-user channel differentiation between hospital-affiliated and independent operators, and gender-based service category splits. CAGRs were derived through logarithmic trend fitting adjusted for regulatory intervention points, with medical tourism inflow assumptions and male grooming normalization rates serving as key demand-side inputs.
Underlying measurement precision varies by segment; dermatology clinic procedure data carries tighter precision than salon-grade operator estimates facing regulatory exclusion. Forecasts reflect assumptions about MOHAP enforcement consistency and physician-presence mandate harmonization across emirates. A model refresh is warranted upon material change in medical tourism policy or federal-emirate regulatory divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Alexandrite Laser Treatment Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Body Contouring Market