
 Europe Aesthetic Dermatology Market | 2026-2036
Europe Aesthetic Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aesthetic Dermatology Market Foresight
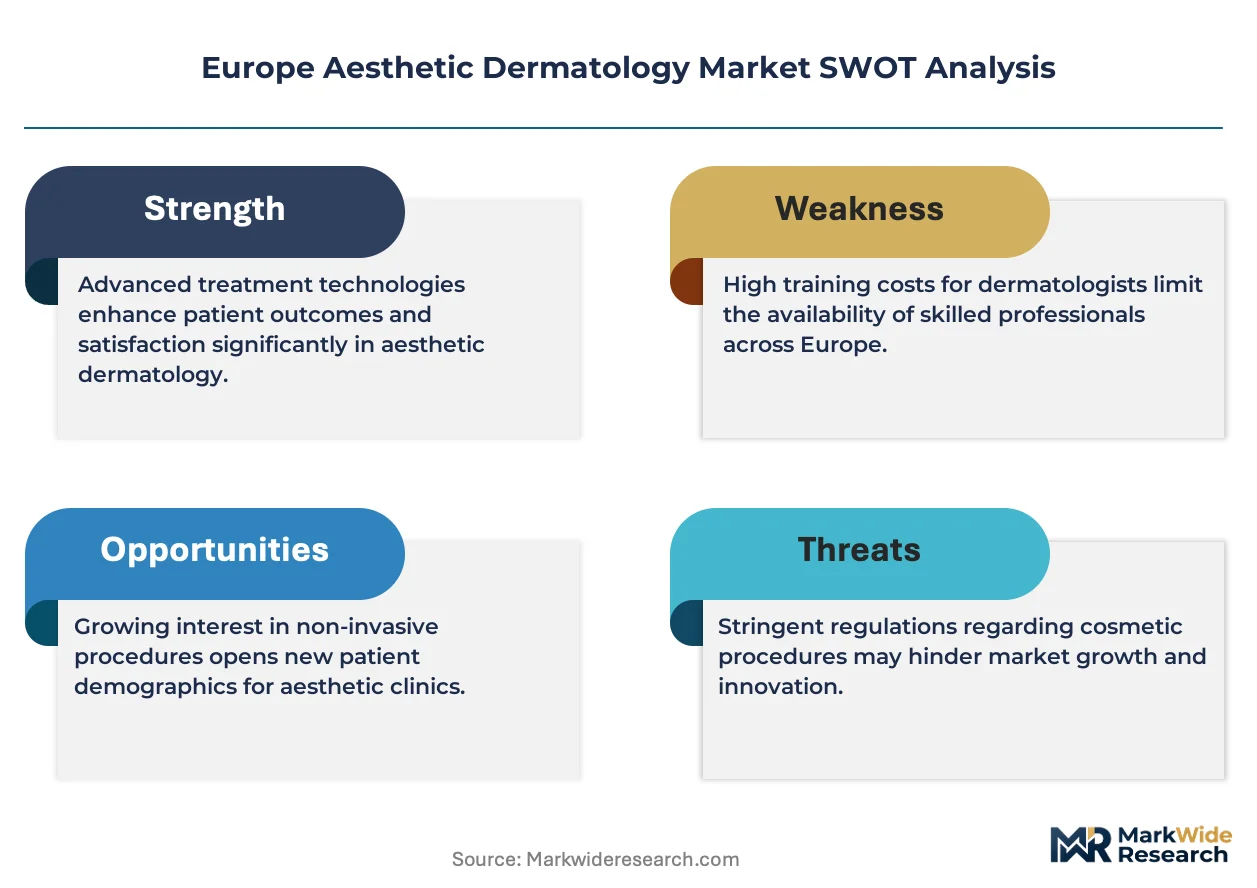
CE marking under the EU Medical Device Regulation is rotating toward stricter clinical evidence requirements for Class IIa and IIb aesthetic devices. Galderma leverages its vertically integrated filler manufacturing network to sustain supply continuity across Northern Europe. Merz Pharma anchors its position through R&D intensity in incobotulinumtoxinA formulations. AbbVie Inc competes via brand strength and channel control in the premium injectables tier.
Europe aesthetic dermatology encompasses minimally invasive and non-invasive procedures using energy-based devices, injectable biologics, and topical resurfacing agents, with laser systems typically operating at wavelengths between 532 nm and 10,600 nm depending on target chromophore and clinical indication. The field serves primarily cosmetic enhancement, skin rejuvenation, and corrective dermatology across outpatient settings. Injectable treatments including botulinum toxin and hyaluronic acid fillers command the dominant margin pool due to recurring patient visits and practitioner certification dependencies. Laser resurfacing segments are accelerating fastest in Southern Europe where sun-damage correction demand concentrates. Chemical peels occupy a mature position with stable volume but compressed pricing across mass-market spa channels.
The European Medicines Agency oversees pharmacological agent approvals while notified bodies execute CE conformity assessments under the MDR framework, with REACH compliance additionally governing chemical peel constituent safety. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM enforce national vigilance reporting that shapes post-market surveillance obligations for device manufacturers. Stakeholders must monitor evolving MDR transition deadlines and national reimbursement stance shifts for medically indicated versus purely cosmetic procedures.
Market Dynamics
The EU Medical Device Regulation's extended compliance timelines are restructuring competitive positioning across laser and energy-based device categories, forcing manufacturers to accelerate clinical evidence generation while notified body capacity constraints create registration bottlenecks.
Growth Catalysts
- Medical tourism flows:Patients from the United Kingdom and Germany are traveling to Poland and Turkey for cost-competitive aesthetic procedures, expanding clinic addressable markets in destination countries.
- CE marking pathway evolution:The MDR framework's stricter clinical evidence requirements for Class IIa and IIb devices is elevating barriers that favor established manufacturers with robust quality management systems.
- Injectable biologics recurrence economics:Botulinum toxin and hyaluronic acid treatments require repeat patient visits, creating predictable revenue streams that attract practitioner investment in certification and facility infrastructure.
Market Restraints
- Notified body capacity scarcity:The limited number of designated bodies under MDR is extending device registration timelines and compressing product launch windows for smaller manufacturers.
- Input material concentration:Hyaluronic acid raw material supply concentrates among specialized fermentation producers, creating vulnerability to batch quality variability and price volatility.
- Substitution pressure from topical alternatives:Advanced peptide-based cosmeceuticals are capturing preventive maintenance demand that might otherwise flow to early-stage injectable treatments.
Strategic Opportunities
- Eastern European clinic network expansion:Poland and Romania present underpenetrated demand relative to Western European saturation, with rising disposable incomes supporting premium service uptake.
- Combination protocol adoption:Sequential laser resurfacing plus injectable treatments are commanding premium pricing in French and Italian metropolitan markets through enhanced outcomes positioning.
- Digital consultation channel development:Telemedicine-enabled pre-screening and treatment planning is reducing patient acquisition costs while expanding geographic reach beyond traditional catchment areas.
Industry Challenges
- Practitioner certification pipeline constraints:The specialized training required for safe energy-based device operation and injectable administration is limiting scalable workforce expansion.
- MDR technical documentation burden:The depth of clinical evaluation reports and post-market surveillance systems required is consuming disproportionate regulatory affairs resources relative to product revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aesthetic Dermatology Market |
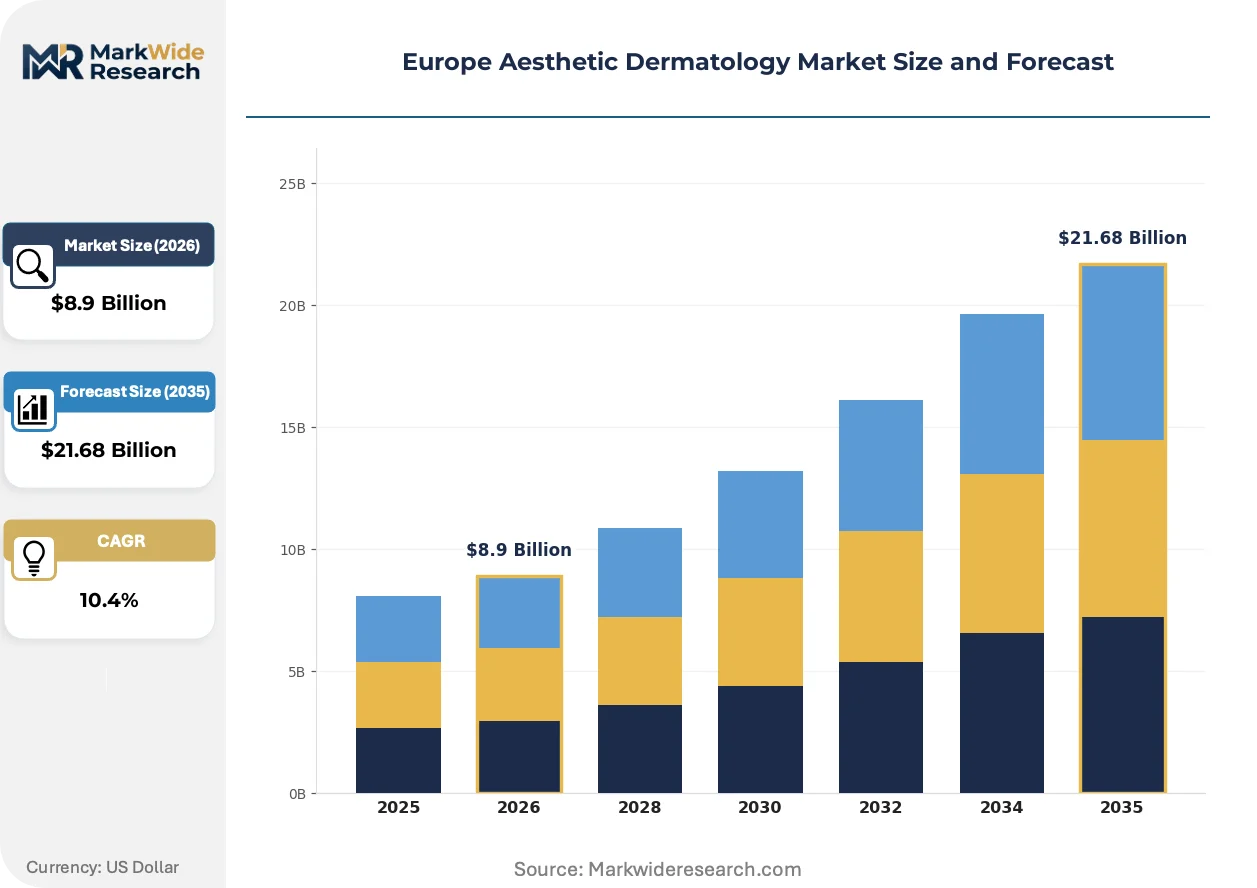
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $21.68 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Botox, Fillers, Chemical Peels, Laser Resurfacing End User: Clinics, Hospitals, Dermatology Centers, Spas Distribution Channel: Online, Offline, Direct Sales, Partnerships Treatment Area: Facial, Body, Hair, Scars |
| Companies Covered | AbbVie Inc, Merz Pharma, Galderma, Cutera, Cynosure, Candela Medical, Alma Lasers, Lumenis, Fotona, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aesthetic Dermatology Market Shifts & Advancements
Technology convergence between diagnostic imaging and treatment delivery systems is redefining procedure precision standards, while regulatory evidence requirements and patient acquisition channels undergo parallel transformation.
Fractional laser technology is decomposing the traditional ablative versus non-ablative dichotomy by enabling tunable thermal injury profiles that match specific skin type and indication requirements. German and French dermatology clinics are adopting these platforms at accelerated replacement cycles. The technology is decomposing market share concentration among legacy CO2 laser manufacturers by lowering capital barriers for mid-tier entrants.
REACH compliance enforcement for chemical peel constituent safety is tightening supply chain documentation obligations across formulators serving the European market. The regulation's industrial consequence is accelerating reformulation investments and raw material substitution toward biogenic acid sources. Spa-channel peel providers in Italy and Spain are responding by consolidating supplier relationships to reduce audit complexity.
Subscription-based treatment packages are displacing single-session pricing in premium clinic segments, locking patient commitment through prepaid multi-visit structures. This model is disrupting traditional fee-for-service dermatology practices and independent medspa operators. The shift is most visible in United Kingdom urban centers where competitive density pressures patient lifetime value optimization.
Europe Aesthetic Dermatology Market Segmentation
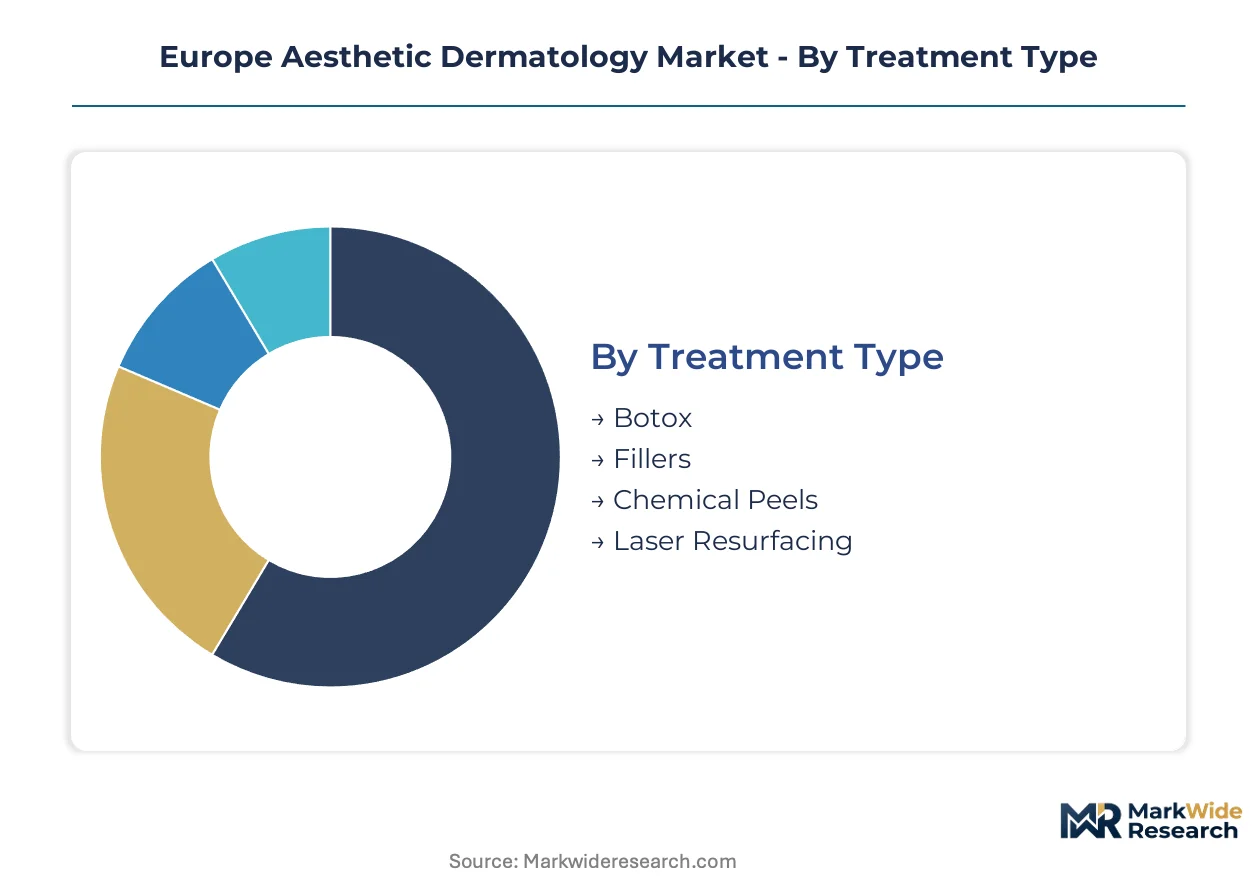
Channel configuration across Europe's aesthetic dermatology market determines margin capture and patient access patterns. Treatment type and distribution channel segmentation reveals how regulatory pathways and practitioner certification requirements reshape competitive boundaries.
Treatment Type:
Channel-mix dynamics concentrate premium injectable flows through dermatology centers and hospital outpatient units, while energy-based devices penetrate broader clinic networks.
- Botox:Purified botulinum toxin formulations target dynamic rhytides through neuromuscular blockade. Demand clusters in French and Italian metropolitan markets where practitioner certification density supports premium positioning. Recurrence economics drive patient loyalty programs and subscription packaging.
- Fillers:Cross-linked hyaluronic acid and calcium hydroxylapatite compounds restore volume and contour. German and United Kingdom urban centers show disproportionate uptake for facial rejuvenation protocols. Supply continuity concerns concentrate procurement decisions around vertically integrated manufacturers.
- Chemical Peels:Acid-based exfoliation agents operating at superficial to medium depths.
- Laser Resurfacing:Fractional and ablative systems targeting photodamage and textural irregularities.
By volume, Botox leads. By growth pace, Laser Resurfacing is expanding most quickly.
End User:
Cost tier stratification separates high-complexity procedural settings from volume-driven service channels.
- Clinics:Independent and chain-affiliated outpatient facilities performing minimally invasive procedures. Poland and Turkey destination markets leverage cost arbitrage to capture United Kingdom and German medical tourism flows.
- Hospitals:Acute care and dedicated cosmetic surgery units handling complex reconstructive cases. France's ANSM vigilance reporting requirements elevate documentation burdens relative to standalone settings.
- Dermatology Centers:Specialist-led practices with advanced energy-based device portfolios.
- Spas:Wellness-oriented channels delivering superficial peels and maintenance protocols.
Clinics command the dominant patient volume share. Dermatology Centers capture the steepest margin expansion trajectory.
Distribution Channel:
Geography dictates channel efficiency, with direct sales penetrating saturated Western European markets while partnerships unlock Eastern European expansion.
- Online:Digital platforms for consumables, skincare adjuncts, and patient education resources. United Kingdom telemedicine-enabled pre-screening reduces acquisition costs for premium clinic networks.
- Offline:Traditional medical supply distributors and device representative networks. German BfArM vigilance obligations require traceability systems that favor established distribution relationships.
- Direct Sales:Manufacturer-controlled channels for capital equipment and high-value consumables.
- Partnerships:Strategic alliances between device manufacturers and clinic networks for bundled service offerings.
Offline channels retain the largest transaction value. Online infrastructure is climbing the fastest as patient acquisition digitizes.
Treatment Area:
Application focus shifts with demographic aging patterns and sun exposure correction demand across Mediterranean markets.
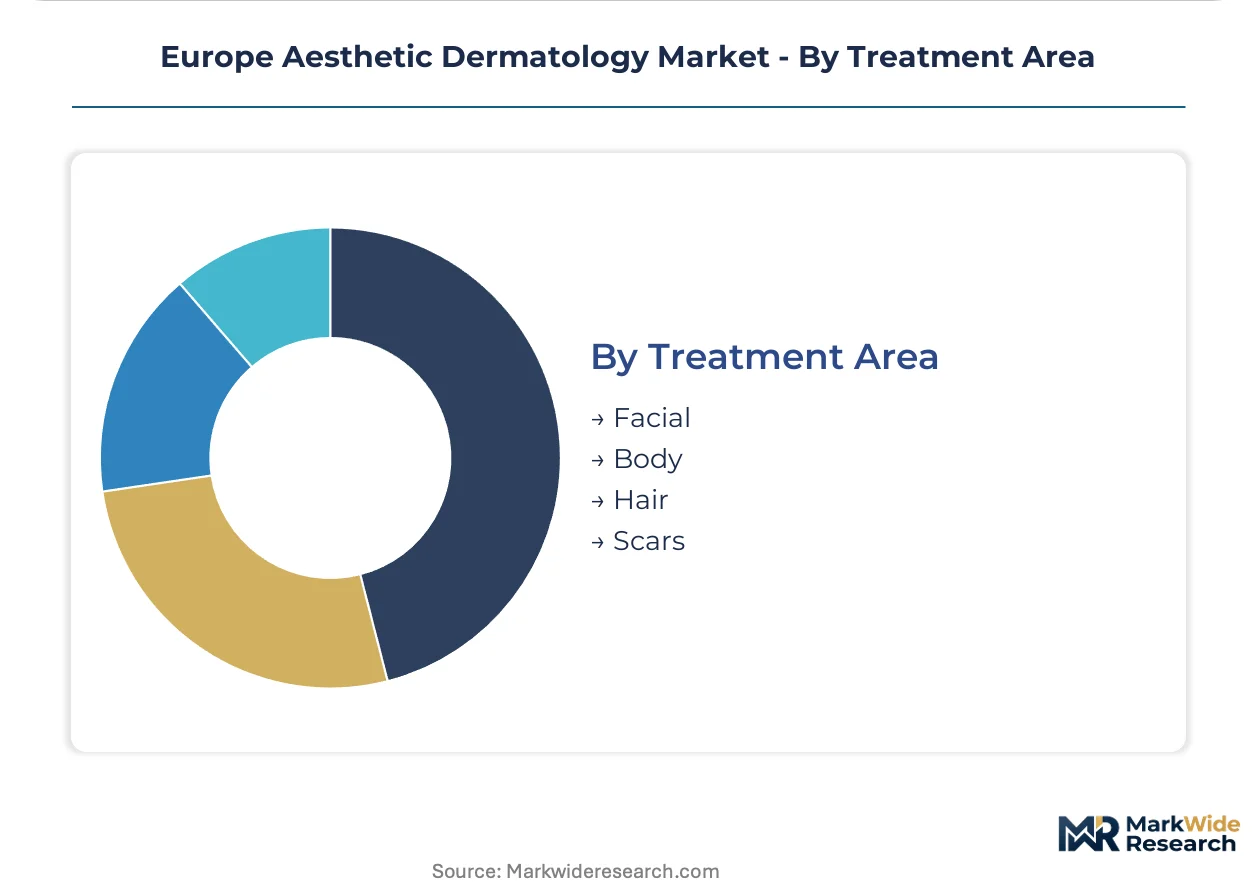
- Facial:Comprehensive rejuvenation targeting periorbital, perioral, and midface zones. Italian and Spanish markets show concentrated demand for sun-damage reversal protocols.
- Body:Contouring and skin tightening applications extending beyond traditional facial focus. Rising disposable incomes in Romanian urban centers support premium body treatment uptake.
- Hair:Restoration and scalp rejuvenation procedures.
- Scars:Acne and traumatic scar revision using fractional laser and subcision techniques.
Facial applications dominate current revenue composition. Body treatments are gaining share fastest as procedure portfolios diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Medical Device Regulation transition deadlines are redistributing manufacturing investment across member states while notified body capacity constraints concentrate registration activity in Germany and France. National reimbursement stance variations between medically indicated and cosmetic procedures are shaping clinic network expansion patterns.
Germany
Federal Institute for Drugs and Medical Devices vigilance obligations elevate documentation burdens for device manufacturers serving the market. BfArM post-market surveillance requirements favor established quality management systems over emerging entrants. Berlin and Munich dermatology centers anchor premium injectable demand through practitioner certification density.
United Kingdom
Telemedicine-enabled pre-screening is reducing patient acquisition costs for urban clinic networks. MHRA regulatory divergence from EU MDR frameworks is creating parallel compliance pathways for device manufacturers. London metropolitan practices command premium positioning through subscription-based treatment packaging.
France
ANSM national vigilance reporting shapes post-market surveillance obligations for energy-based device operators. REACH compliance enforcement tightens chemical peel constituent documentation across formulators. Paris and Lyon specialist clinics drive disproportionate demand for combination laser-plus-injectable protocols.
Italy
Sun-damage correction demand concentrates in Mediterranean coastal markets where fractional laser adoption accelerates. ANSM-equivalent regional health authority oversight varies across autonomous provinces. Milan and Rome aesthetic centers capture premium facial rejuvenation volumes through enhanced outcomes positioning.
Poland
Medical tourism inflows from Western European markets expand clinic addressable patient bases beyond domestic demand. Cost-competitive procedure pricing attracts United Kingdom and German patient flows. Warsaw and Krakow destination clinics invest in energy-based device portfolios to capture premium service tiers.
Europe Aesthetic Dermatology Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and practitioner channel control. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with vertically integrated filler networks, dedicated aesthetic device manufacturers with concentrated R&D pipelines, and regional clinic operators capturing medical tourism flows. Strategic moves center on M&A for technology access and direct sales force expansion into underpenetrated Eastern European markets.
Within the pharmaceutical-tier segment, AbbVie Inc and Galderma occupy positions reflecting divergent channel strategies for premium injectable distribution. Merz Pharma exemplifies the specialized manufacturer archetype with concentrated formulation development in neurotoxin segments. These three entities anchor competitive dynamics through contrasting approaches to practitioner certification support and supply chain configuration.
| Leading Market Players |
|---|
| AbbVie Inc |
| Merz Pharma |
| Galderma |
| Cutera |
| Cynosure |
| Candela Medical |
| Alma Lasers |
| Lumenis |
| Fotona |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements between German clinic networks and Swiss hyaluronic acid fermenters lock in supply access while anchoring price visibility for premium filler portfolios. These contractual structures insulate established operators from spot-market volatility in raw material inputs.
Pricing Analysis
Certification level (MDR Class IIb versus legacy CE-marked) creates the primary spread between premium device placements and economy-tier alternatives. Subscription-based treatment packaging dominates injectable segments, locking patient commitment through prepaid multi-visit structures. Cost compression in spa-channel chemical peels intensifies as REACH compliance elevates documentation burdens. Independent clinics in Poland and Turkey exhibit highest price sensitivity; Paris and London dermatology centers show lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for energy-based device components sourced from Israeli and Korean manufacturers. Hyaluronic acid raw material concentrates in Swiss and Japanese fermentation facilities; laser system assemblies draw from German and Italian precision optics clusters. Single-source vulnerability concentrates in specialized peptide suppliers serving neurotoxin formulation. Distribution runs through manufacturer-direct sales forces for capital equipment, with consumables flowing via medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe aesthetic dermatology market operates as a defensive-moat story where regulatory entrenchment creates durable barriers. MDR compliance timelines and practitioner certification dependencies protect incumbent positions from rapid displacement.
For Market Incumbents: Shield market position by deepening backward integration into hyaluronic acid fermentation capacity and accelerating MDR technical documentation investments. The notified body capacity scarcity threatens smaller competitors with registration delays. Channel control through exclusive practitioner certification programs represents the critical defensive lever.
For New Entrants and Emerging Players: Differentiate on digital consultation infrastructure and telemedicine-enabled pre-screening capabilities. The Romanian and Bulgarian clinic networks present the most penetrable geography, with rising disposable incomes and limited incumbent saturation. A direct-to-clinic SaaS model for patient acquisition offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive supply of critical inputs. Long-term viability hinges on regulatory compliance capabilities rather than pure technology differentiation. Acquisition targets should display robust quality management systems and established notified body relationships. The signal to watch is MDR transition deadline extensions that compress competitive timelines for non-compliant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates CE marking pathways for Class IIb laser devices under EMA oversight. |
| Practitioner Certification Program Expansion | Locks channel loyalty through specialized training in neurotoxin administration protocols. |
| Backward Integration into Fermentation Capacity | Secures captive hyaluronic acid supply against batch quality variability risks. |
| Digital Consultation Platform Development | Reduces patient acquisition costs for United Kingdom clinic networks via telemedicine. |
| Eastern European Clinic Network Acquisition | Captures medical tourism flows from German and British patient segments. |
Research Methodology
A spread of perspectives from dermatology clinic operators, biomedical device engineers, regulatory affairs specialists at notified bodies, and pharmaceutical procurement managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EMA submission databases, BfArM vigilance reports, ANSM post-market surveillance filings, and REACH compliance registries. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue assessments.
Segmentation dimensions modeled include treatment type, end-user facility tier, distribution channel configuration, and geographic regulatory cluster across the analysis window. CAGRs derived from procedure volume trajectories and average selling price evolution. Forecast inputs incorporated MDR transition deadline assumptions and medical tourism flow projections between origin and destination markets.
The analysis sits within stated boundaries; outcomes outside sustained MDR compliance timelines and stable cross-border patient mobility would require recalibration. Forecasts reflect documented assumptions regarding notified body capacity expansion and raw material supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Global Buttock Augmentation Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Aesthetic Services Market
Aesthetic Medicine
Global Stretch Marks Treatment Market