
 Ultraviolet Transilluminator Imaging Systems Market | 2026-2036
Ultraviolet Transilluminator Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraviolet Transilluminator Imaging Systems Market Analytics
Aftermarket service revenue is reshaping margin distribution across the Ultraviolet Transilluminator Imaging Systems landscape. Thermo Fisher Scientific leverages its global service infrastructure to capture recurring calibration and maintenance contracts. Bio-Rad Laboratories anchors its position through deep specialization in gel imaging workflows for academic and government research accounts. Cleaver Scientific competes aggressively on replacement lamp and filter aftermarket accessibility.
Ultraviolet transilluminator imaging systems employ UV-A/UV-B excitation wavelengths, typically 302 nm or 365 nm, to induce fluorescence in ethidium bromide or SYBR-stained nucleic acid gels, with captured images processed through CCD or CMOS sensors for documentation and quantification. Gel imaging systems dominate installed base volumes due to entrenched demand from molecular biology protocols, while LED transilluminators represent the fastest-expanding product category as mercury lamp phase-outs accelerate under REACH and RoHS substance restrictions. CMOS technology is displacing legacy CCD architectures in mid-tier instruments, driven by lower power requirements and faster frame capture rates.
FDA 21 CFR Part 11 compliance requirements shape software validation burdens for clinical diagnostic deployments, while the EU IVDR framework imposes stricter performance documentation on imaging systems used in vitro diagnostic workflows. ISO 13485 quality management certification has become a baseline gating factor for vendor participation in hospital and reference laboratory procurement. Stakeholders must monitor evolving photobiological safety standards from IEC and national laser safety committees as LED and laser-induced fluorescence technologies broaden wavelength ranges.
Market Dynamics
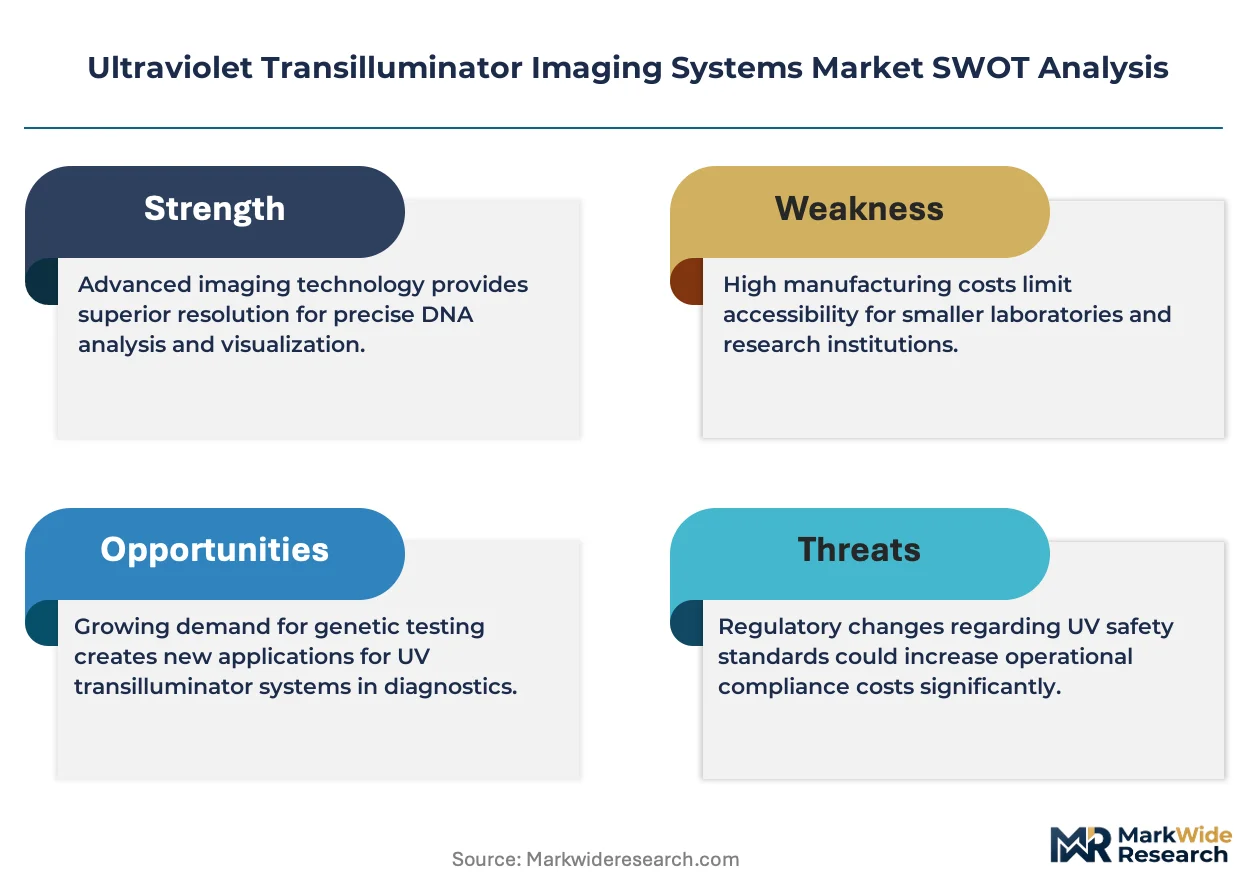
Mercury lamp phase-outs under REACH and RoHS substance restrictions are forcing rapid LED transilluminator adoption, compressing replacement cycles and reshaping vendor aftermarket revenue streams across molecular biology workflows.
Growth Catalysts
- Genomics infrastructure investments:Biopharma R&D spending in the United States, Germany, and China sustains demand for high-throughput nucleic acid visualization systems in academic and commercial laboratories.
- IVDR framework implementation:Europe's stricter performance documentation requirements for in vitro diagnostic workflows expand the addressable market for validated imaging equipment in clinical reference laboratories.
- CMOS sensor maturation:Lower power requirements and faster frame capture rates accelerate displacement of legacy CCD architectures in mid-tier gel documentation instruments.
Market Restraints
- Mercury supply chain concentration:Lamp component sourcing remains concentrated among specialized European and Asian suppliers, exposing lead times to raw material volatility.
- FDA 21 CFR Part 11 compliance burden:Electronic records validation requirements impose substantial software documentation costs on clinical diagnostic deployments, extending sales cycles.
- Ethidium bromide substitution pressure:Safer nucleic acid stains reduce UV excitation efficiency, creating performance trade-offs that complicate instrument specification.
Strategic Opportunities
- Indian biopharma expansion:CDSCO regulatory alignment with international standards and PLI scheme incentives create entry pathways for validated imaging systems in contract research organizations.
- Laser-induced fluorescence convergence:Integration of solid-state laser sources with CMOS detection architectures enables multiplexed wavelength excitation beyond traditional UV-A/UV-B ranges.
- Service contract unbundling:Independent calibration and maintenance providers can capture recurring revenue from installed base instruments as manufacturer service premiums face price resistance.
Industry Challenges
- Photobiological safety certification complexity:Evolving IEC standards for LED and laser-based illumination systems require ongoing engineering redesign and documentation updates.
- ISO 13485 quality management implementation:Hospital and reference laboratory procurement gates demand certified suppliers, excluding smaller vendors without dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraviolet Transilluminator Imaging Systems Market |
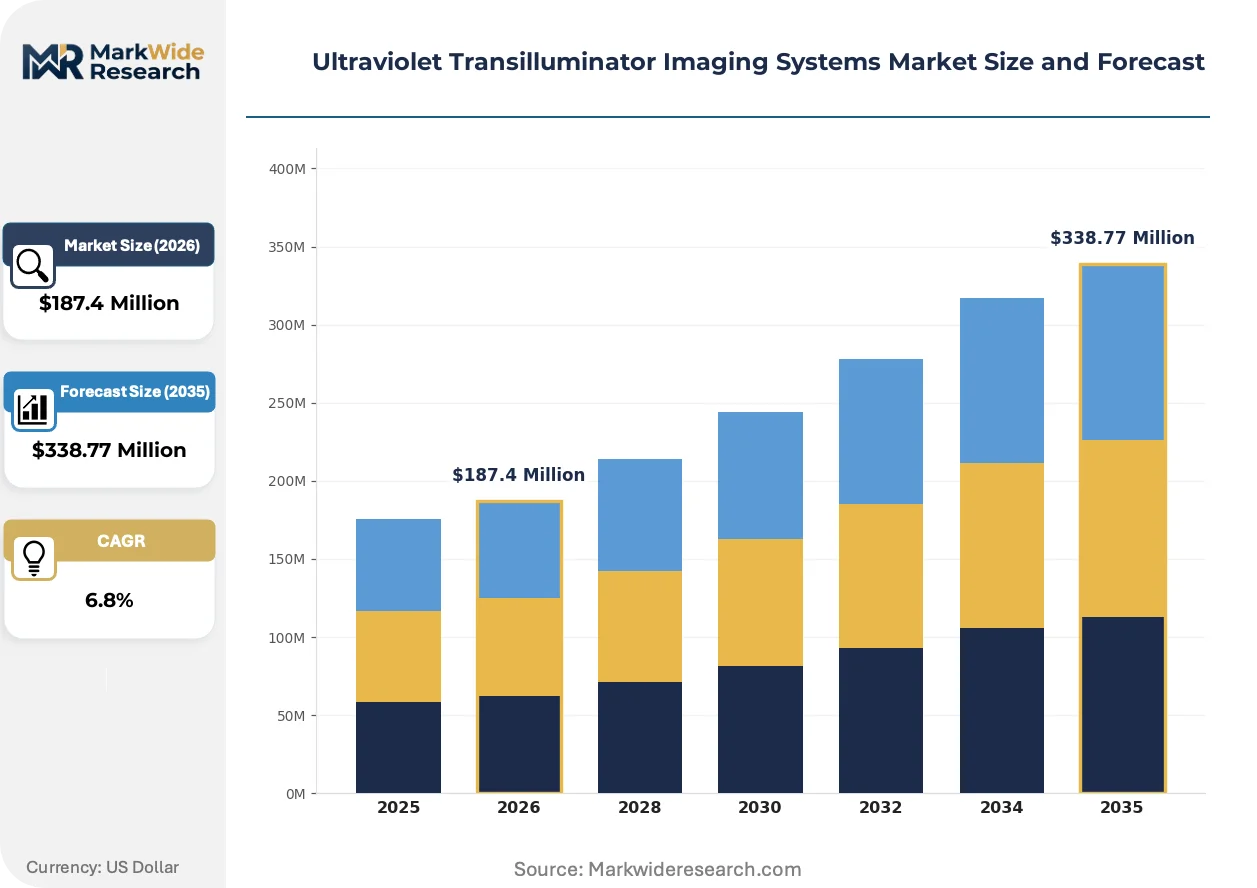
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Imaging Systems, Hybrid Imaging Systems, LED Transilluminators, UV Transluminators Application: Molecular Biology, Forensic Science, Clinical Diagnostics, Agriculture Research End User: Research Laboratories, Clinical Laboratories, Educational Institutions, Biotechnology Firms Technology: CCD Technology, CMOS Technology, Digital Image Processing, Laser Induced Fluorescence |
| Companies Covered | Thermo Fisher Scientific, Cleaver Scientific, Bio-Rad Laboratories, VWR International, Spectronics Corporation, Syngene, Thomas Scientific, Maestrogen, DNR Bio-Imaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraviolet Transilluminator Imaging Systems Market Evolving Landscape
Cloud-native image analysis platforms are virtualizing traditional hardware-bound documentation workflows, while regulatory harmonization pressures and buyer consolidation reshape competitive differentiation strategies.
CMOS-based gel documentation systems are virtualizing the role of dedicated darkroom infrastructure in molecular biology laboratories. Academic research facilities in North America and Europe are adopting these instruments at accelerated replacement cycles. This shift is virtualizing capital allocation from enclosed imaging enclosures toward software-defined analysis environments that integrate directly with laboratory information management systems.
REACH substance restrictions on mercury-containing equipment are tightening enforcement timelines across European member states. Manufacturers must redesign excitation sources and validate alternative illumination architectures before sunset dates. Gel imaging product lines destined for EU clinical diagnostics face the steepest compliance costs, driving consolidation among vendors with dedicated regulatory engineering teams.
Research consortia are consolidating purchasing authority through shared service centers and core facility budgets. University and government laboratory buyers now negotiate enterprise pricing across multiple instrument categories simultaneously. This concentration is most pronounced in the United States, where NIH funding consolidation has reduced the number of independent procurement decision-makers by half in major research clusters.
Ultraviolet Transilluminator Imaging Systems Market Segmentation
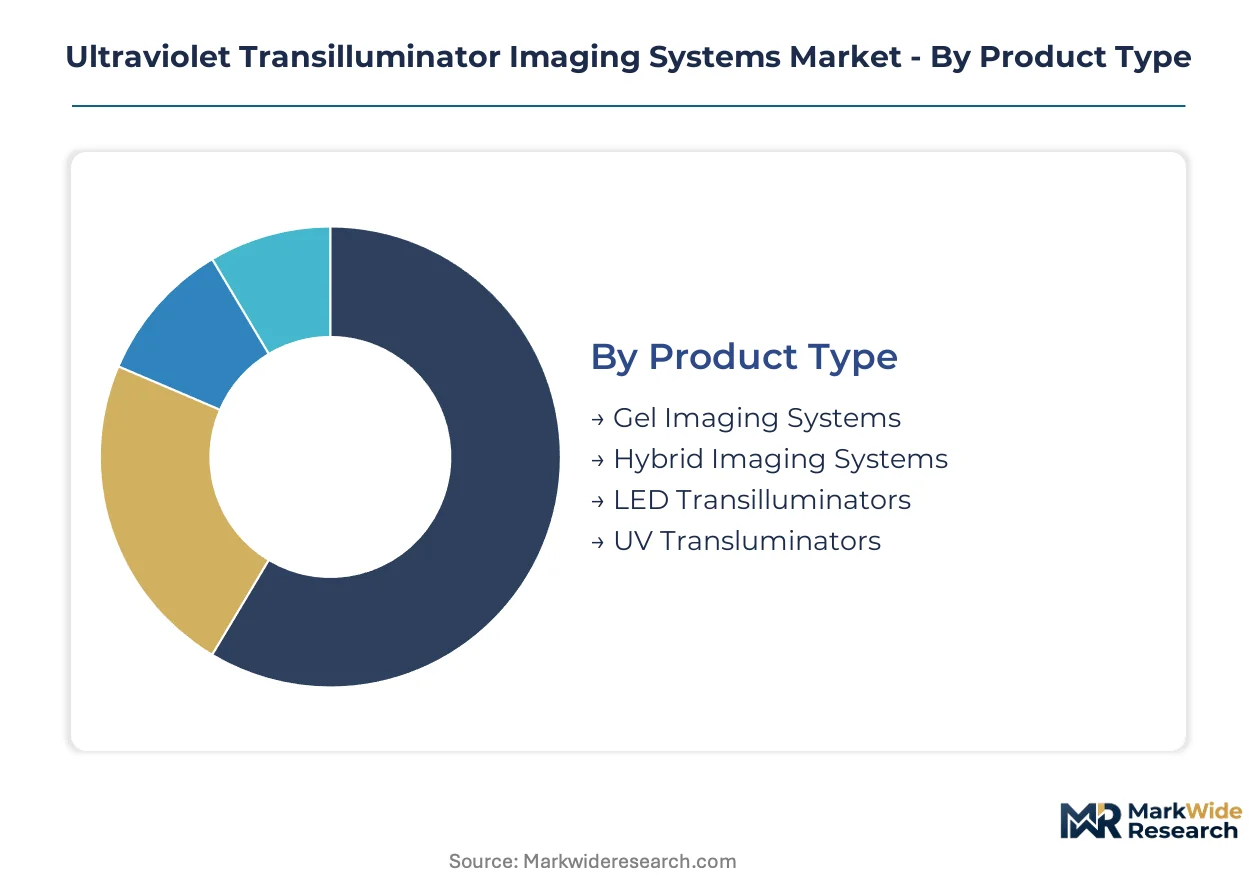
Segmentation reveals how wavelength specifications, sensor architectures, and regulatory compliance requirements fragment procurement decisions across molecular biology workflows. Buyers prioritize different performance thresholds depending on whether applications demand quantitative documentation, rapid screening, or clinical-grade validation.
Product Type:
Use-case spectrum spans from routine nucleic acid visualization in academic settings to multiplexed fluorescence detection in regulated clinical environments.
- Gel Imaging Systems:Enclosed CCD or CMOS-based platforms with integrated darkroom enclosures capture high-resolution fluorescence images of ethidium bromide or SYBR-stained gels. Demand concentrates in United States academic research laboratories where NIH-funded molecular biology protocols require standardized documentation for publication compliance. FDA 21 CFR Part 11 software validation burdens extend sales cycles for clinical diagnostic deployments.
- LED Transilluminators:Solid-state excitation sources operating at 302 nm or 365 nm wavelengths eliminate mercury lamp maintenance and disposal costs. REACH and RoHS substance restrictions across European Union member states are accelerating replacement of legacy UV transluminators in German and French research institutions. CMOS detection architectures dominate new installations due to lower power requirements.
- UV Transluminators:Traditional mercury vapor lamp-based benchtop units remain entrenched in budget-constrained educational settings where capital replacement cycles extend beyond hardware lifecycles.
- Hybrid Imaging Systems:Modular platforms combining multiple excitation sources with interchangeable filter sets support multiplexed fluorescence applications in biotechnology firm R&D departments.
Established volume favors Gel Imaging Systems; emerging adoption favors LED Transilluminators.
Application:
Regulatory stringency and sample throughput requirements create distinct performance tiers across diagnostic and research workflows.
- Molecular Biology:Nucleic acid quantification, PCR product verification, and cloning workflow documentation represent the core installed base. Demand concentrates in United States and China where biopharma R&D spending sustains instrument refresh cycles. Academic core facilities negotiate enterprise pricing across multiple gel documentation platforms simultaneously.
- Clinical Diagnostics:In vitro diagnostic workflows require ISO 13485-certified instruments with validated software meeting EU IVDR performance documentation standards. Europe's stricter compliance framework expands addressable market for qualified imaging equipment in hospital and reference laboratories.
- Forensic Science:DNA profiling and evidence analysis applications in government crime laboratories demand ruggedized hardware with chain-of-custody documentation features.
- Agriculture Research:Plant genotyping and seed quality testing applications in China and India drive demand for portable, field-deployable fluorescence detection systems.
Volume concentration sits with Molecular Biology; regulatory premium capture sits with Clinical Diagnostics.
End User:
Procurement authority and budget structures fragment across institutional categories with divergent validation requirements.
- Research Laboratories:Academic and government facilities prioritize CMOS-based systems with cloud-native image analysis integration. NIH funding consolidation in United States research clusters has halved independent procurement decision-makers, concentrating purchasing authority through shared service centers.
- Biotechnology Firms:Commercial R&D operations demand high-throughput platforms with automated analysis pipelines. India's PLI scheme incentives and CDSCO regulatory alignment are creating entry pathways for validated imaging systems in contract research organizations.
- Clinical Laboratories:Hospital and reference laboratory procurement gates require ISO 13485 quality management certification, excluding smaller vendors without dedicated regulatory affairs functions.
- Educational Institutions:Undergraduate teaching laboratories prioritize capital cost minimization over performance specifications, sustaining demand for legacy UV transluminator architectures.
Replacement velocity is highest in Biotechnology Firms; price resistance is deepest in Educational Institutions.
Technology:
Sensor architecture migration and illumination source innovation are restructuring competitive differentiation.
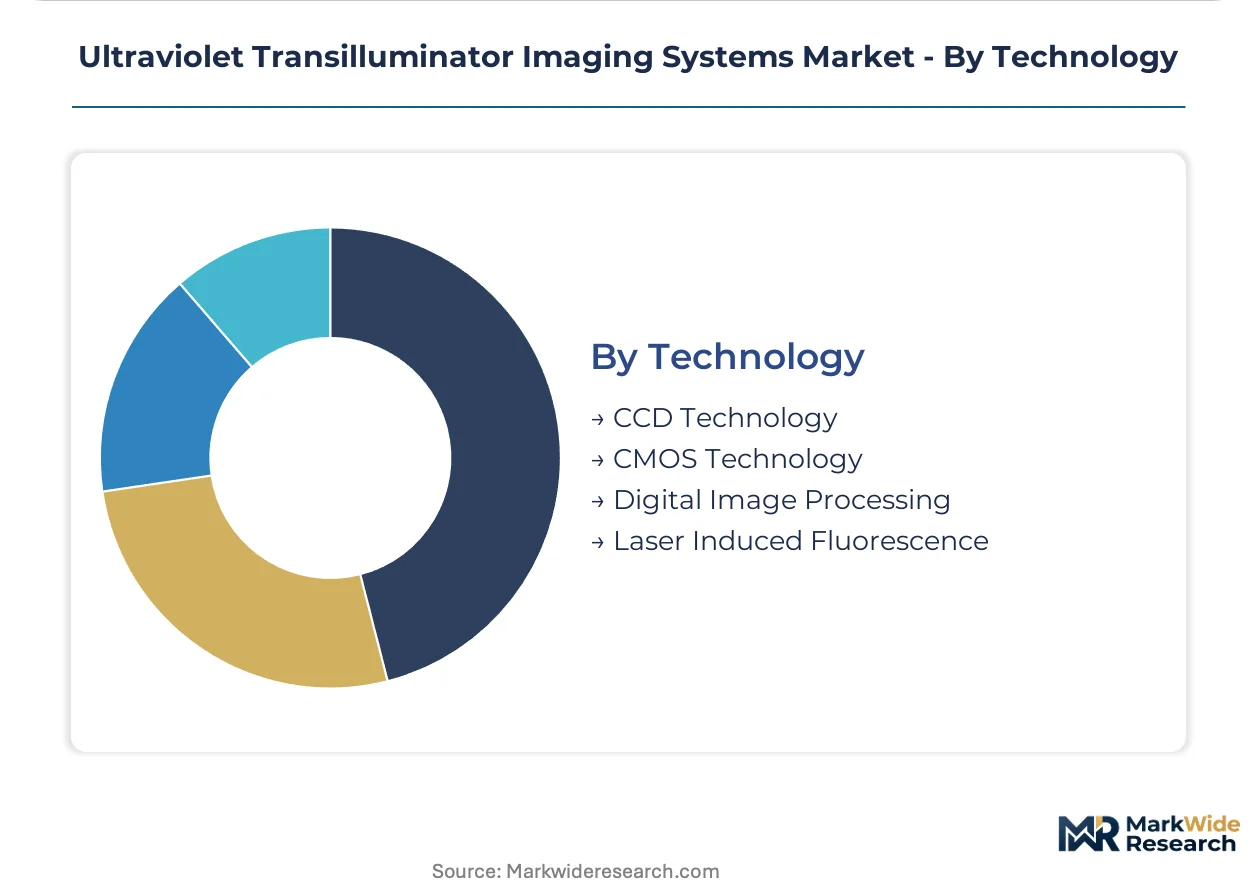
- CMOS Technology:Lower power consumption, faster frame capture rates, and reduced heat generation are displacing legacy CCD architectures in mid-tier instruments. Academic research facilities in North America and Europe are adopting CMOS-based gel documentation systems at accelerated replacement cycles.
- Laser Induced Fluorescence:Solid-state laser sources enable multiplexed wavelength excitation beyond traditional UV-A/UV-B ranges, supporting advanced applications in quantitative proteomics and multi-color nucleic acid detection.
- CCD Technology:Legacy architectures persist in installed base instruments where calibration and maintenance contracts generate recurring aftermarket revenue.
- Digital Image Processing:Software-defined analysis environments integrate directly with laboratory information management systems, virtualizing traditional hardware-bound documentation workflows.
Technology transition favors CMOS Technology; specialized application depth favors Laser Induced Fluorescence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Educational institutions in India and Brazil exhibit the highest price elasticity, prioritizing capital cost minimization over performance specifications. Biotechnology firms in the United States and Germany demonstrate the lowest price sensitivity, accepting premium pricing for validated clinical-grade instruments. China's hybrid demand profile splits between cost-conscious provincial universities and R&D-intensive biopharma clusters in Shanghai and Suzhou.
United States
NIH-funded molecular biology protocols sustain standardized documentation requirements across academic core facilities. FDA 21 CFR Part 11 compliance burdens extend sales cycles for clinical diagnostic deployments. The Greater Boston and San Francisco Bay Area biotech corridors concentrate procurement authority through consolidated shared service centers.
Germany
REACH and RoHS substance restrictions accelerate mercury lamp phase-outs in research institutions. The IVDR framework imposes stricter performance documentation requirements on imaging systems used in hospital laboratories. Bavaria's Munich-Heidelberg biotech axis drives demand for ISO 13485-certified gel documentation platforms.
China
Biopharma R&D spending in Shanghai and Suzhou sustains high-throughput nucleic acid visualization demand. NMPA regulatory alignment with international standards creates pathways for validated imaging equipment in contract research organizations. The Yangtze River Delta biotech corridor concentrates genomics infrastructure investments.
India
CDSCO regulatory harmonization and PLI scheme incentives expand entry pathways for validated imaging systems. Contract research organizations in Hyderabad and Bengaluru drive instrument refresh cycles. State-funded agricultural research stations in Maharashtra and Gujarat prioritize portable fluorescence detection for plant genotyping applications.
United Kingdom
Research council funding consolidation reduces independent procurement decision-makers across university clusters. The MHRA's post-Brexit regulatory framework maintains alignment with EU IVDR documentation standards. The Cambridge-Oxford-London golden triangle concentrates demand for CMOS-based gel documentation systems.
Ultraviolet Transilluminator Imaging Systems Market Competitive Landscape
Capability concentration sits with specialized imaging equipment manufacturers; scale advantage sits with diversified life sciences conglomerates. The vendor base stratifies across three tiers: global platform providers with integrated service networks, regional specialists with deep workflow expertise, and component suppliers competing on replacement part accessibility. Two dominant competitive moves define current positioning: strategic unbundling of service contracts to capture recurring revenue, and vertical integration into cloud-native image analysis software.
Among diversified life sciences platform providers, Thermo Fisher Scientific and Bio-Rad Laboratories occupy positions exemplifying scale-driven competitive advantage. Thermo Fisher leverages global service infrastructure to anchor recurring calibration and maintenance contract capture. Bio-Rad represents specialization depth in academic and government research account penetration. Cleaver Scientific sits within the regional specialist tier, competing on aftermarket lamp and filter accessibility.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Cleaver Scientific |
| Bio-Rad Laboratories |
| VWR International |
| Spectronics Corporation |
| Syngene |
| Thomas Scientific |
| Maestrogen |
| DNR Bio-Imaging Systems |
| Others |
Value Network & Pricing Analysis
Mercury lamp component sourcing in Germany and Japan concentrates upstream supply for UV transluminators, anchoring margin capture in aftermarket replacement cycles rather than initial equipment sales. This concentration forces buyers into long-term service dependencies that reshape lifetime value economics across molecular biology workflows.
Pricing Analysis
Aftermarket service contracts and replacement lamp revenues drive lifetime value for installed base instruments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical systems from research-grade CMOS platforms and educational UV transluminators. Cost compression in the economy tier intensifies as Indian and Brazilian educational institutions extend replacement cycles beyond hardware lifecycles. Biotechnology firms in the United States and Germany demonstrate the lowest price sensitivity, accepting premium pricing for validated clinical-grade instruments with FDA 21 CFR Part 11 software documentation.
Supply Chain Analysis
Extended payment terms from specialized European and Asian lamp suppliers finance inventory buffers for downstream distributors. Germany, Japan, and China concentrate manufacturing of mercury vapor lamps, CMOS sensors, and precision optical filters. Component sourcing draws from specialized suppliers for 302 nm and 365 nm excitation sources, UV-grade optical glass, and thermal management substrates. Single-source vulnerability in mercury lamp phosphor materials exposes lead times to raw material volatility. Distribution runs through life sciences distributors with regional service depots and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent capable of integrating CMOS architectures with laser-induced fluorescence platforms remains scarce, constraining vendor expansion into multiplexed detection applications. This capability gap separates incumbents with dedicated R&D teams from aspirants dependent on outsourced sensor integration.
For Market Incumbents: Insulate installed base positions by unbundling calibration and maintenance contracts before independent service providers capture recurring revenue streams. Accelerate backward integration into cloud-native image analysis software to virtualize hardware-bound documentation workflows and defend against software-defined competitors. Prioritize ISO 13485 certification investments for hospital laboratory procurement gates that exclude uncertified suppliers. For New Entrants and Emerging Players: Build out regulatory engineering capabilities to serve India's CDSCO-aligned contract research organizations in Hyderabad and Bengaluru, where PLI scheme incentives reduce effective customer acquisition costs. Target agricultural research stations in Maharashtra and Gujarat with portable fluorescence detection systems for plant genotyping applications, a segment underserved by clinical-focused incumbents. Lead with field-deployable form factors and local language software interfaces. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LED transilluminator manufacturing as solid-state excitation sources displace mercury lamp assembly lines and associated hazardous material handling infrastructure. Acquisition candidates with captive CMOS sensor partnerships and validated EU IVDR technical documentation offer the strongest five-to-ten-year viability. Monitor REACH enforcement timelines for mercury-containing equipment as an inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| LED Excitation Source Transition | REACH and RoHS substance restrictions in Germany and France accelerate mercury lamp phase-outs and reshape vendor R&D allocation. |
| CMOS Sensor Platform Migration | Faster frame capture rates and lower power requirements displace legacy CCD architectures in mid-tier gel documentation instruments. |
| Cloud-Native Image Analysis Development | Software-defined environments integrate directly with laboratory information management systems in United States academic core facilities. |
| ISO 13485 Quality Certification Investment | Hospital and reference laboratory procurement gates in Germany's Munich-Heidelberg biotech axis demand certified suppliers. |
| Service Contract Unbundling | Independent calibration providers capture recurring revenue from Thermo Fisher Scientific and Bio-Rad Laboratories installed base instruments. |
Research Methodology
The analysis maps gel imaging systems, LED transilluminators, UV transluminators, and hybrid imaging platforms, each validated through primary interviews with molecular biology laboratory directors, clinical diagnostics procurement managers, biomedical equipment service technicians, and regulatory affairs specialists at imaging equipment manufacturers. Secondary sources include FDA 510(k) filings for clinical diagnostic devices, ECHA REACH substance restriction documentation, NIH grant expenditure databases, and SEC 10-K filings from diversified life sciences conglomerates. Bottom-up instrument shipment estimates triangulate against top-down biopharma R&D spending allocations.
Assumptions held fixed include continued enforcement of REACH mercury phase-out timelines, sustained NIH funding levels for academic molecular biology protocols, and stable CDSCO regulatory alignment with international standards. The projection horizon spans product type, application, end user, technology, and regional adoption pattern segments. CAGRs derive from regression analysis of historical replacement cycles against genomics infrastructure investment trajectories. Forecast inputs incorporate sensor architecture migration rates and LED excitation source cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified life sciences conglomerates would shift outcomes through accelerated software platform consolidation. Macroeconomic contraction in biopharma R&D spending, regulatory delay in IVDR enforcement, or breakthrough in safer nucleic acid stain chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Fiducial Markers Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Micro Computed Tomography Market
Imaging
Global Whole Slide Imaging Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Document Imaging Market
Imaging
Side View Camera System Market
Imaging
Global Broadcast Cameras Market
Imaging
X-Ray Microscopes Market
Imaging
Silent Scan Technology Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Thermal Imaging Market
Imaging
Hyperspectral Imaging Market
Imaging
Borescope Market
Imaging
Handheld Imager Market
Imaging
High-Speed Camera Market