
 Japan Food Emulsifiers Market | 2026-2036
Japan Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Food Emulsifiers Market Foresight
Japan's Food Labeling Act is restructuring the cost-of-entry calculus for emulsifier suppliers by mandating clearer additive disclosure and tightening permissible ingredient lists. Riken Vitamin Co., Ltd. anchors its position through deep domestic manufacturing scale and specialized lecithin derivatives. Mitsubishi Chemical Food Corporation leverages proprietary esterification technology to differentiate in polyglycerol esters. Kao Corporation sustains competitive pressure through integrated oleochemical supply chains and strong bakery channel relationships.
Food emulsifiers are surface-active compounds, typically amphiphilic molecules with hydrophilic-lipophilic balance values between 3 and 6, that reduce interfacial tension between immiscible phases such as oil and water in processed food matrices. Their primary commercial purpose is to stabilize texture, extend shelf life, and enable consistent mouthfeel across industrial-scale production runs. Lecithin and mono- and diglycerides occupy mature volume positions in baked goods and dairy applications where formulation standards are well codified. Polyglycerol esters represent the fastest-expanding product class, driven by sauce and condiment manufacturers seeking heat-stable emulsification for retort-processed products.
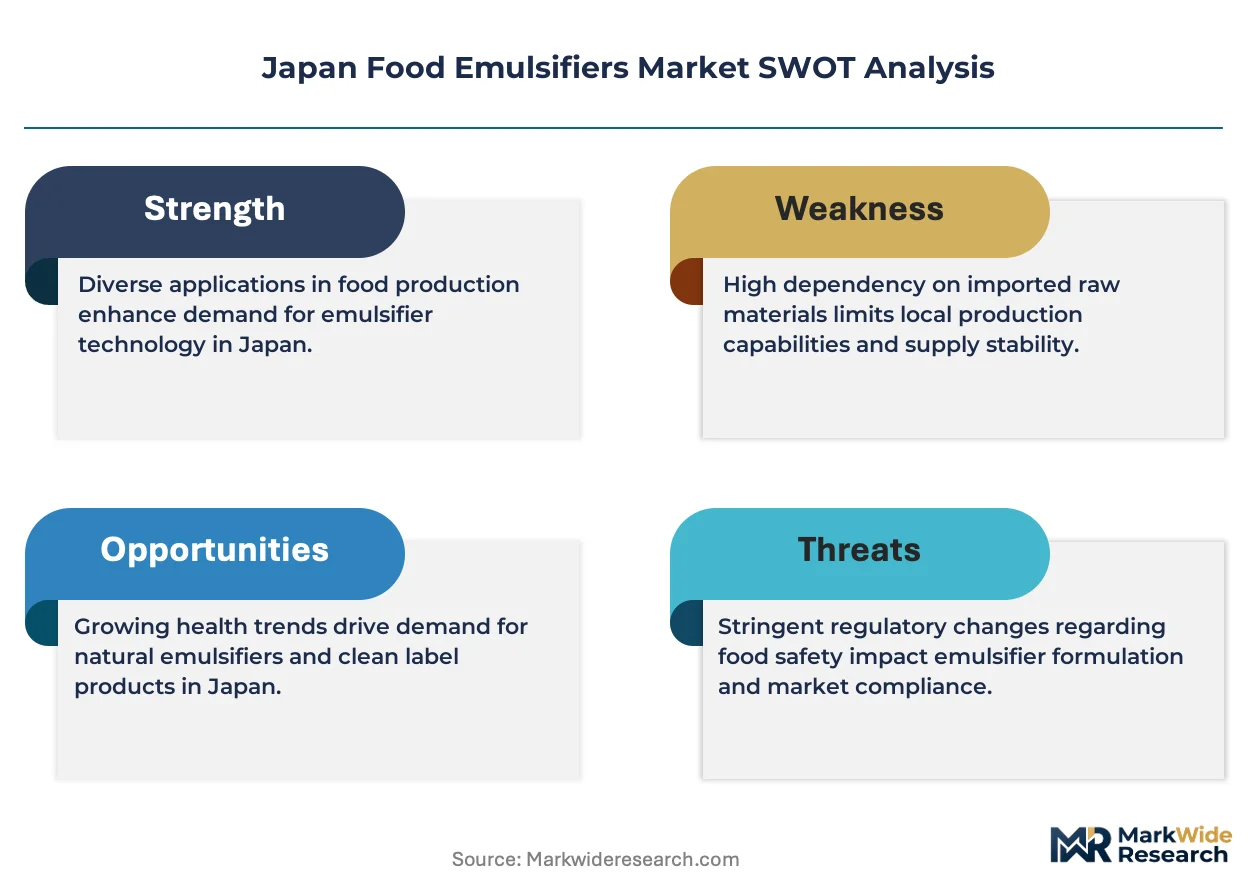
METI enforces industrial chemical safety standards that govern emulsifier manufacturing facility certifications, while the Consumer Affairs Agency administers food labeling rules that directly shape end-user purchasing criteria. JIS standards for food-grade chemicals create additional compliance layers that foreign suppliers must navigate before market entry. Stakeholders should monitor evolving clean-label interpretations under Japanese regulatory guidance, as these definitions will determine which synthetic emulsifiers retain formulation access and which natural alternatives capture premium positioning.
Market Dynamics
Clean-label procurement mandates from Japan's leading bakery chains are forcing emulsifier suppliers to reformulate synthetic additives into plant-derived alternatives, compressing R&D timelines and restructuring supplier qualification protocols.
Growth Catalysts
- Processed Food Export Expansion:Japanese sauce and condiment manufacturers are scaling retort-compatible emulsifier volumes to supply Southeast Asian retail chains.
- METI Sustainability Standards:The ministry's tightening guidelines on food additive environmental profiles are accelerating adoption of bio-based emulsification systems.
- Kanto Cluster Concentration:Tokyo's dense network of dairy and bakery processing facilities generates concentrated demand for high-performance lecithin derivatives.
Market Restraints
- Soy Lecithin Price Volatility:Raw material costs for Japan's dominant natural emulsifier fluctuate with Argentine and Brazilian harvest cycles.
- Import Dependency:Over half of specialty polyglycerol ester feedstocks originate from Chinese oleochemical processors.
- Clean-Label Technical Ceiling:Natural emulsifiers fail to match synthetic alternatives in heat stability for ultra-high-temperature processed dairy.
Strategic Opportunities
- Hokkaido Dairy Integration:Proximity to Japan's milk powder production hub offers captive supply chain positioning for dairy-specific emulsifier blends.
- Convenience Store Channel:Lawson and 7-Eleven Japan's private-label expansion creates direct procurement relationships bypassing traditional distributors.
- JIS Certification Arbitrage:Early compliance with revised food-grade chemical standards opens premium positioning before foreign competitors adapt.
Industry Challenges
- Formulation Chemist Scarcity:Japanese universities produce limited graduates specializing in food-grade surfactant chemistry.
- Multi-Regulatory Synchronization:Suppliers must align METI facility certifications with Consumer Affairs Agency labeling rules and JIS chemical standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Food Emulsifiers Market |
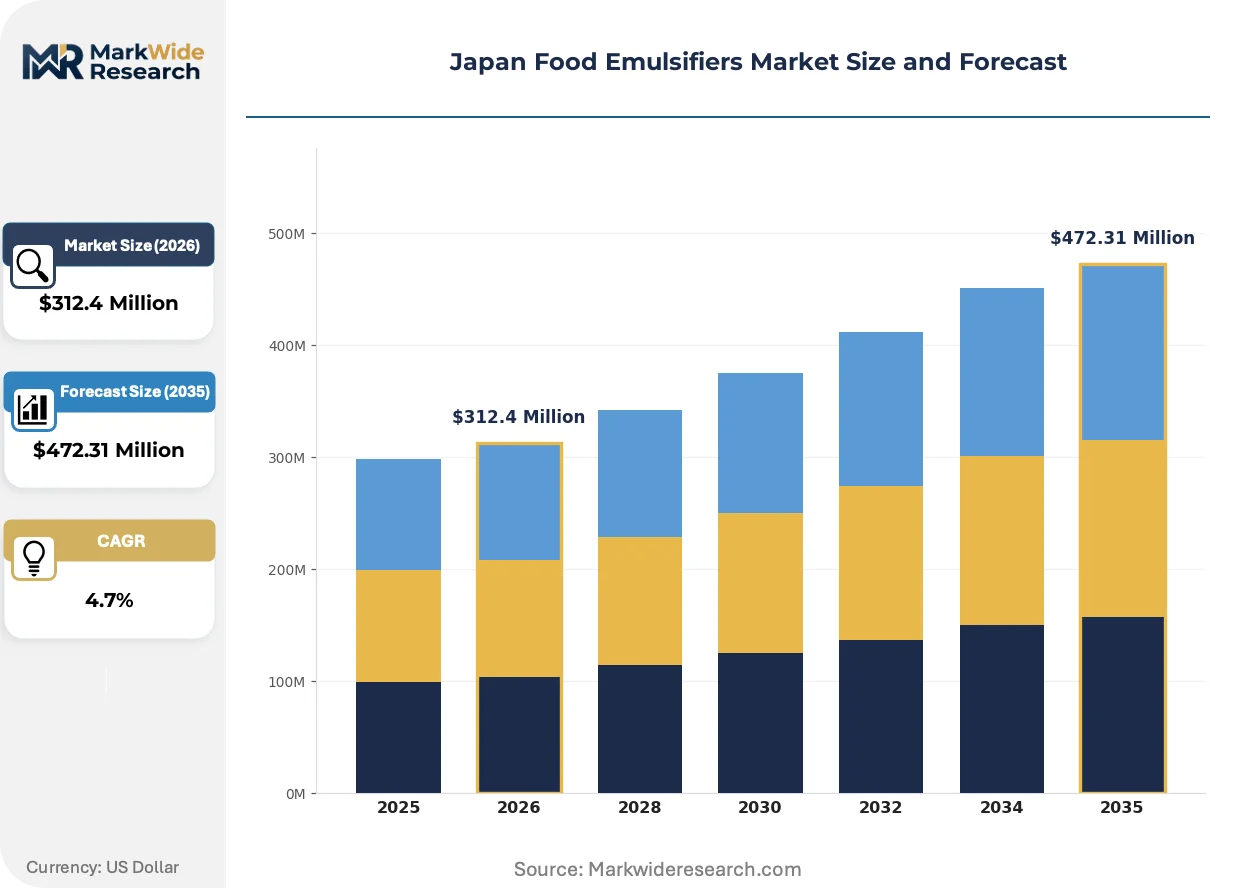
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Sorbitan Esters, Polyglycerol Esters Application: Baked Goods, Dairy Products, Sauces, Condiments Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Restaurants, Retailers, Bakeries |
| Companies Covered | Archer Daniels Midland Company, Riken Vitamin Co., Ltd., Cargill, Incorporated, Mitsubishi Chemical Food Corporation, BASF SE, DuPont de Nemours, Inc, Kerry Group plc, Kao Corporation, Corbion N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Food Emulsifiers Market Shifts & Advancements
Enzymatic modification of natural emulsifiers is compressing the performance gap with synthetic alternatives, while regulatory pressure and channel consolidation reshape how suppliers capture value.
Enzyme-catalyzed esterification of plant-derived phospholipids is electrifying the clean-label segment by delivering heat-stable emulsification previously achievable only with synthetic mono- and diglycerides. Major bakery chains in Osaka and Nagoya are piloting these modified lecithins for extended-shelf-life bread applications. The technology is electrifying supplier R&D priorities, forcing accelerated patent filings around enzymatic process conditions.
METI's 2023 amendments to chemical manufacturing facility standards now mandate continuous emissions monitoring for emulsifier production sites. This regulatory tightening disqualifies older batch-processing infrastructure and favors capital-intensive continuous-flow systems. Small and mid-sized suppliers in the Chubu region face consolidation pressure as compliance costs escalate.
Direct procurement contracts between emulsifier manufacturers and national bakery chains are displacing traditional trading house intermediaries. This channel compression concentrates volume with suppliers demonstrating formulation collaboration capabilities. The shift is most pronounced in the Kanto region, where Yamazaki Baking and Pasco Shikishima have established technical partnership programs with preferred additive vendors.
Japan Food Emulsifiers Market Segmentation
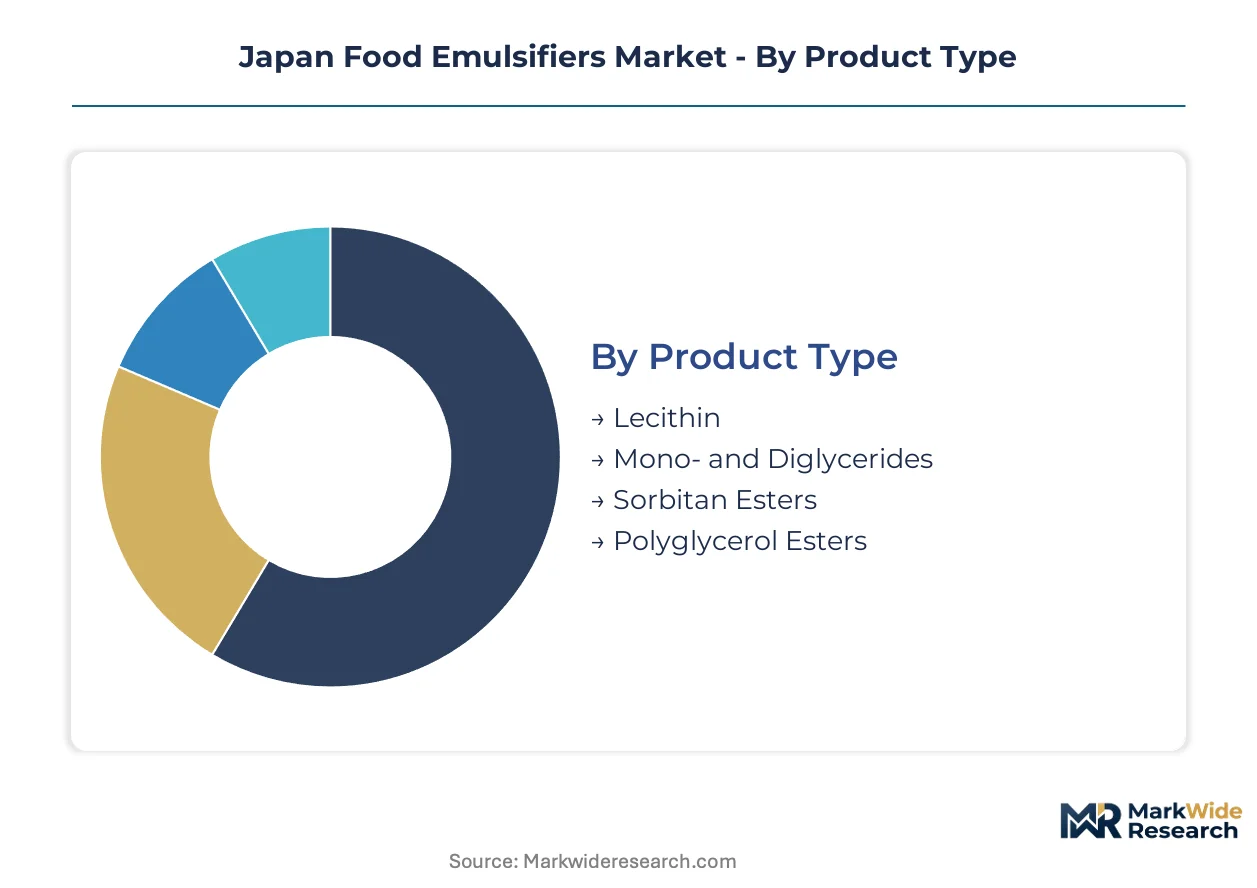
Emulsifier specification in Japan varies sharply by processing environment and end-product requirements. Suppliers must align molecular architecture with regional manufacturing clusters and channel-specific formulation standards.
Product Type:
Customization intensity spans from commodity lecithin to engineered polyglycerol esters, with specification depth determining margin capture across bakery and dairy channels.
- Lecithin:Phospholipid mixtures extracted from soy or sunflower oil provide baseline emulsification for volume bread production. Kanto bakeries favor enzymatically modified variants that extend shelf life without synthetic additives, though heat stability remains inferior to ester alternatives.
- Polyglycerol Esters:Multi-hydroxyl head groups deliver superior thermal stability for retort-processed sauces targeting Southeast Asian export markets. Mitsubishi Chemical's proprietary esterification technology dominates this specification tier, capturing premium positioning from condiment manufacturers in Osaka and Nagoya.
- Mono- and Diglycerides:Partial esters of fatty acids and glycerol occupy mature volume positions in industrial dairy processing.
- Sorbitan Esters:Span-series emulsifiers serve niche applications requiring precise HLB tuning for oil-in-water systems.
Leading the category by volume: Lecithin. Growing fastest: Polyglycerol Esters.
Application:
End-use differentiation tracks processing intensity, with heat treatment requirements dictating emulsifier selection and procurement relationships.
- Baked Goods:Extended-shelf-life bread and confectionery demand emulsifiers that retard staling while maintaining clean-label compliance. Yamazaki Baking and Pasco Shikishima have established direct technical partnerships with preferred suppliers, bypassing traditional trading houses for formulation collaboration.
- Sauces:Retort-compatible emulsification enables shelf-stable mayonnaise and dressing production for convenience store channels. Lawson and 7-Eleven Japan's private-label expansion concentrates procurement with suppliers demonstrating heat-stable natural alternatives.
- Dairy Products:Ultra-high-temperature processing creates technical ceilings for natural emulsifiers in milk powder and cream applications.
- Condiments:Fermented and pickled product lines require emulsifiers stable across acidic pH ranges.
Volume concentrates in: Baked Goods. Steepest expansion trajectory: Sauces.
Form:
Physical state selection hinges on manufacturing infrastructure compatibility and dosing precision requirements across facility scales.
- Powder:Spray-dried emulsifiers integrate cleanly into automated dry-mix systems at large-scale bakery complexes. The form dominates Hokkaido dairy powder production where moisture control is critical.
- Liquid:Pumpable concentrates reduce dust exposure and enable continuous-flow dosing in high-throughput sauce manufacturing. METI's 2023 emissions monitoring mandates favor liquid systems with closed-loop handling.
- Granular:Intermediate flow properties serve mid-sized processors lacking pneumatic conveying infrastructure.
- Paste:High-viscosity formulations target artisanal bakeries requiring manual incorporation.
Standard grade by volume: Powder. Gaining share fastest: Liquid.
End User:
Procurement sophistication varies from technical partnership programs at national manufacturers to price-driven spot purchasing at independent retailers.
- Food Manufacturers:Industrial processors in Tokyo's Kanto cluster negotiate multi-year supply agreements with embedded R&D collaboration. These relationships prioritize formulation stability and regulatory documentation over unit cost minimization.
- Bakeries:Chain operations across Osaka and Nagoya pilot enzymatically modified lecithins through direct vendor programs, compressing qualification timelines for clean-label transitions.
- Restaurants:Central kitchen operations for chain dining groups drive consolidated emulsifier purchasing.
- Retailers:Private-label development at convenience store operators creates direct procurement relationships with mid-tier suppliers.
Procurement volume leader: Food Manufacturers. Channel transformation fastest: Bakeries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keihin Industrial Zone's tax incentives and infrastructure subsidies concentrate emulsifier demand among Tokyo's processed food manufacturers. METI's regional development programs reinforce this clustering through dedicated chemical processing districts. The Kanto region's dominance shapes procurement patterns across adjacent prefectures.
Kanto Region
Tokyo's dense bakery and dairy processing cluster generates concentrated demand for lecithin derivatives and enzymatically modified emulsifiers. METI's 2023 facility certification standards favor capital-intensive continuous-flow production systems in this zone. Yamazaki Baking and Pasco Shikishima operate central kitchens across Saitama and Chiba prefectures, sourcing directly from preferred additive suppliers.
Kansai Region
Osaka and Nagoya manufacturers pilot heat-stable natural emulsifiers for extended-shelf-life bread applications. The Consumer Affairs Agency's labeling enforcement creates procurement pressure for clean-label alternatives in this manufacturing belt. Mitsubishi Chemical Food Corporation anchors polyglycerol ester supply to condiment producers concentrated in Osaka's harbor industrial district.
Hokkaido
Japan's milk powder production hub drives captive demand for dairy-specific emulsifier blends. The prefecture's cold-chain infrastructure supports spray-dried powder formulations integrating seamlessly with automated dry-mix systems. Regional dairy cooperatives negotiate multi-year supply agreements prioritizing formulation stability over unit cost.
Chubu Region
Nagoya's sauce and condiment manufacturers scale retort-compatible emulsifier volumes for Southeast Asian export markets. METI's emissions monitoring mandates disqualify older batch-processing infrastructure here, forcing consolidation among small and mid-sized suppliers. The region's chemical processing heritage supports specialized esterification capabilities.
Kyushu
Fukuoka's food manufacturing base serves as a distribution gateway for emulsifier supply to Okinawa and southern markets. The prefecture's port infrastructure enables import receipt of soy lecithin feedstocks from Argentine and Brazilian origins. Regional processors face price volatility transmission from raw material harvest cycles.
Japan Food Emulsifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The market structure consolidates around three strategic archetypes: integrated oleochemical operators with captive feedstock supply, specialized emulsifier manufacturers with proprietary esterification technology, and global trading houses with broad additive portfolios. Competitive dynamics center on direct technical partnerships with national bakery chains and accelerated JIS certification timelines.
Among Japan-based specialists, Riken Vitamin Co., Ltd. and Mitsubishi Chemical Food Corporation occupy positions reflecting deep domestic manufacturing scale. Kao Corporation exemplifies the integrated archetype through oleochemical supply chain control. Archer Daniels Midland Company and Cargill, Incorporated represent global agricultural processors with lecithin extraction capabilities. BASF SE and DuPont de Nemours, Inc anchor the multinational chemical conglomerate tier.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Riken Vitamin Co., Ltd. |
| Cargill, Incorporated |
| Mitsubishi Chemical Food Corporation |
| BASF SE |
| DuPont de Nemours, Inc |
| Kerry Group plc |
| Kao Corporation |
| Corbion N.V. |
| Others |
Supply & Pricing Matrix
Enzymatic modification of plant-derived phospholipids is compressing cost economics while concentrating supply among capital-intensive continuous-flow operators. METI's 2023 emissions monitoring mandates disqualify older batch-processing infrastructure, forcing consolidation that reshapes pricing power across the Kanto manufacturing belt.
Pricing Analysis
Short lead-time premiums command substantial markups as national bakery chains compress qualification timelines for clean-label transitions. Pricing stratifies across JIS-certified premium tiers, enzymatically modified mid-tier alternatives, and commodity soy lecithin economy levels. Cost compression in the economy tier is intensifying because Argentine and Brazilian harvest volatility transmits directly to raw material costs. Independent regional bakeries exhibit acute price sensitivity, while Yamazaki Baking and Pasco Shikishima prioritize formulation collaboration over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from METI-certified manufacturers mandate multi-supplier qualification for critical lecithin and polyglycerol ester feedstocks. Supply draws from Chinese oleochemical processors for specialty ester inputs, Argentine and Brazilian crushing operations for soy lecithin origins, and domestic enzymatic modification facilities in Saitama and Chiba. Single-source vulnerability concentrates in Chinese polyglycerol ester intermediates where tariff exposure and logistics chokepoints at Yokohama Port create systemic risk. Distribution runs through direct technical partnerships with national bakery chains, displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's food emulsifier market operates under supply constraint as METI facility certification bottlenecks prop pricing for compliant domestic capacity. Formulation chemist scarcity and capital-intensive continuous-flow requirements limit new entrant supply expansion.
For Market Incumbents: Deploy enzymatic process patent filings to lock in clean-label performance advantages before foreign competitors adapt. Secure backward integration into Hokkaido dairy powder production hubs to capture captive supply chain positioning. Channel control through direct technical partnerships with Lawson and 7-Eleven Japan's private-label programs defends against trading house displacement. For New Entrants and Emerging Players: Launch via JIS certification arbitrage targeting revised food-grade chemical standards before established foreign suppliers complete compliance adaptation. Chubu region sauce manufacturers scaling Southeast Asian export volumes represent the most penetrable segment, with retort-compatible natural emulsifier gaps in their formulation portfolios. Go-to-market through enzymatically modified lecithin pilot programs with Osaka and Nagoya bakery chains bypasses entrenched Kanto supplier relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated oleochemical conglomerates seeking Japanese regulatory expertise and bakery channel access. Long-term viability favors specialists with proprietary esterification technology and embedded R&D collaboration frameworks. Watch enzymatic modification yield breakthroughs as the inflection signal determining which natural alternatives capture synthetic emulsifier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Patent Filing | Locks clean-label performance advantages ahead of foreign competitor adaptation timelines. |
| Hokkaido Dairy Integration | Captures captive supply positioning at Japan's milk powder production hub. |
| JIS Certification Acceleration | Opens premium positioning before foreign suppliers complete revised standard compliance. |
| Direct Bakery Partnership Programs | Displaces trading house intermediaries through embedded formulation collaboration. |
| Continuous-Flow Capacity Investment | Qualifies for METI emissions monitoring mandates disqualifying batch processors. |
Research Methodology
Regulatory filings from METI and the Consumer Affairs Agency, Japanese customs trade data, and JIS standard documentation formed the secondary backbone. Primary interviews with emulsifier plant managers, procurement leads at Yamazaki Baking and Pasco Shikishima, distribution channel partners in the Kanto region, and technical R&D directors at enzymatic modification facilities combined with secondary validation. Bottom-up volume modeling across product type, application, form, and end-user segments triangulated against top-down value estimates derived from trade flow analysis.
Historical trendline analysis of lecithin and polyglycerol ester trade volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product specification tier, processing heat-stability requirement, physical form compatibility, and regional manufacturing cluster concentration. CAGRs were derived from regression analysis against processed food export expansion and clean-label procurement adoption curves. Forecast inputs incorporated METI sustainability standard enforcement intensity and enzymatic modification technology diffusion rates.
The model assumes a particular technology adoption path for enzymatic modification of natural emulsifiers; alternative pathways for synthetic retention in ultra-high-temperature dairy would alter the outlook. Forecasts reflect assumptions around METI facility certification timelines and Argentine soybean harvest stability. Deviation in Chinese polyglycerol ester feedstock availability or Kanto bakery chain consolidation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Lactose Monohydrate Market