
 Hydrolysed Vegetable Protein (HVP) Market | 2026-2036
Hydrolysed Vegetable Protein (HVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrolysed Vegetable Protein (HVP) Market Insights
Soy protein concentrate supply from Brazilian processors is hardening as drought cycles tighten raw material availability. Ajinomoto Co., Inc. leverages its fermentation technology leadership to sustain premium positioning in Asian savory markets. Kerry Group plc anchors European food service channels with customized HVP blends for plant-based formulations. Cargill, Incorporated controls upstream oilseed processing, extending its cost advantage across multiple protein ingredient categories.
Hydrolysed vegetable protein denotes plant-derived proteins broken down by acid or enzymatic hydrolysis into free amino acids and short peptides, typically achieving 40-90% protein content with pronounced umami characteristics that function as flavor enhancers and nutritional fortifiers in processed foods. Food Grade HVP dominates value generation due to stringent purity requirements and clean-label premiums, while Hydrolysed Pea Protein captures the fastest trajectory as allergen-free positioning displaces soy in European and North American formulations. Powder form leads industrial procurement volumes for shelf stability and transport efficiency, though liquid concentrates gain traction in ready-to-use sauce applications where hydration steps add processing cost.
EU REACH chemical safety protocols and EFSA food additive evaluations shape permissible hydrolysis methods and residual solvent limits for European market access, while FDA GRAS self-affirmation pathways govern US ingredient compliance with varying documentation intensity. China's SAMR enforces GB standards for imported HVP that diverge from Codex Alimentarius parameters on heavy metal thresholds, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor evolving allergen labeling mandates and carbon footprint disclosure requirements that will reshape sourcing geography and process technology selection.
Market Dynamics
EU Green Deal sustainability mandates are compressing ingredient sourcing timelines for European food manufacturers, forcing accelerated reformulation cycles in savory applications and meat alternatives.
Growth Catalysts
- EU Green Deal sourcing requirements:Sustainability disclosure obligations under the Corporate Sustainability Reporting Directive are pulling hydrolysed vegetable protein into clean-label savory formulations across German and Dutch food manufacturing.
- Enzymatic hydrolysis advancement:Fermentation-derived processing methods are displacing acid hydrolysis in premium applications, yielding cleaner taste profiles and lower residual solvent burdens.
- Pea protein feedstock expansion:Canadian and Ukrainian yellow pea cultivation is diversifying raw material geography beyond Brazilian soy concentration, reducing single-origin supply risk.
Market Restraints
- Soy concentrate input volatility:Brazilian drought cycles are hardening soy protein pricing and tightening availability from Paraná and Mato Grosso processors.
- REACH compliance friction:ECHA chemical safety protocols impose dual-certification burdens on Asian suppliers seeking European market access, extending validation timelines.
- Yeast extract substitution:Autolyzed yeast derivatives are capturing umami enhancement share in cost-sensitive sauce applications, pressuring HVP volume in commodity segments.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia and Vietnam food service channels show minimal HVP adoption in traditional broth formulations, presenting first-mover positioning for enzymatic grades.
- Cell-cultured meat hybrid applications:Scaffold protein and flavor masking requirements in cultivated meat platforms are creating specification demand for low-sodium hydrolyzed vegetable proteins.
- Carbon border adjustment mechanism:EU CBAM implementation is incentivizing regional European production investment to avoid embedded emissions tariffs on imported Asian HVP.
Industry Challenges
- Fermentation technologist scarcity:Industrial microbiology and enzyme engineering talent pools are thinning across European and North American hiring markets, constraining process optimization.
- Dual-certification timeline compression:Parallel GB standard and REACH dossier preparation for Chinese and European market entry is stretching regulatory affairs capacity at mid-scale suppliers.
- Legacy acid hydrolysis asset stranding:Depreciated European acid hydrolysis capacity faces accelerated obsolescence under tightening EFSA residual solvent limits, forcing premature capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrolysed Vegetable Protein (HVP) Market |
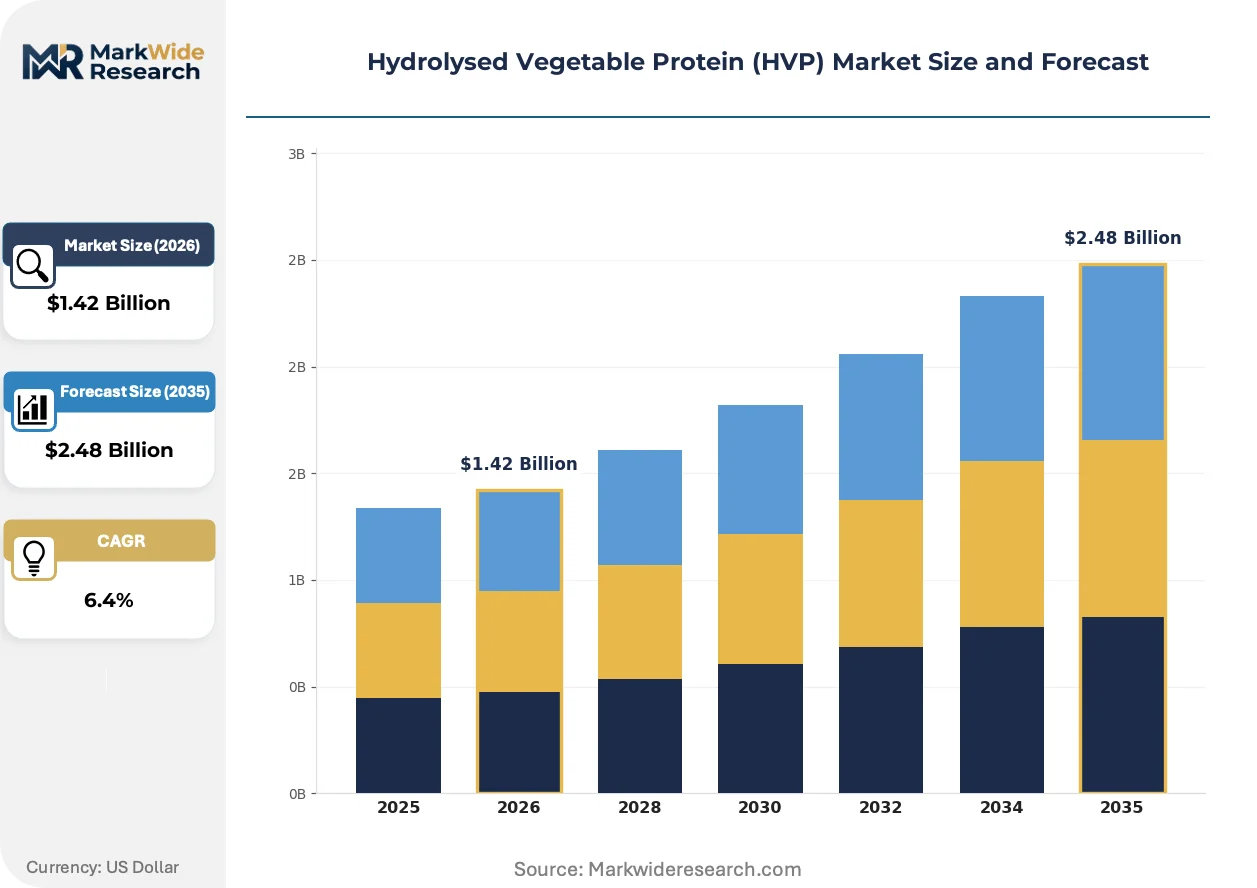
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Hydrolysed Soy Protein, Hydrolysed Pea Protein Application: Meat Alternatives, Sauces, Snacks, Nutritional Supplements Form: Powder, Liquid, Granules, Paste End User: Food Manufacturers, Animal Feed Producers, Nutraceutical Companies, Restaurants |
| Companies Covered | Ajinomoto Co., Inc., Kerry Group plc, Sensient Technologies Corporation, Archer Daniels Midland, Cargill, Incorporated, Givaudan, Roquette Freres, Tate & Lyle, Griffith Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrolysed Vegetable Protein (HVP) Market Trends and Innovations
Process technology convergence and regulatory disclosure mandates are compressing traditional supply chain configurations while opening specification gaps for novel protein sources and clean-label hydrolysis methods.
Enzymatic hydrolysis with targeted protease blends is unifying taste optimization and allergen mitigation in a single processing step. German savory manufacturers are adopting these systems at pilot scale ahead of 2025 formulation deadlines. The technology is unifying what previously required sequential acid treatment and flavor masking, collapsing unit economics for premium positioning.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent liquid HVP storage infrastructure across French and Italian sauce manufacturers. Industrial consequence includes accelerated powder form conversion and reformulation of ready-to-use applications toward ambient-stable concentrates. Southern European food service channels are responding with hybrid procurement models splitting volume between powder base stocks and regional liquid compounding.
Clean-label preference is rotating procurement authority from cost-driven commodity buyers to technical marketing teams specifying hydrolysis method disclosure. Direct supplier relationships are displacing distributor intermediation in mid-scale European meat alternative ventures. German and Dutch plant-based formulation labs are most visible in this channel restructuring, consolidating volume with single-source fermentation technology partners.
Hydrolysed Vegetable Protein (HVP) Market Segmentation
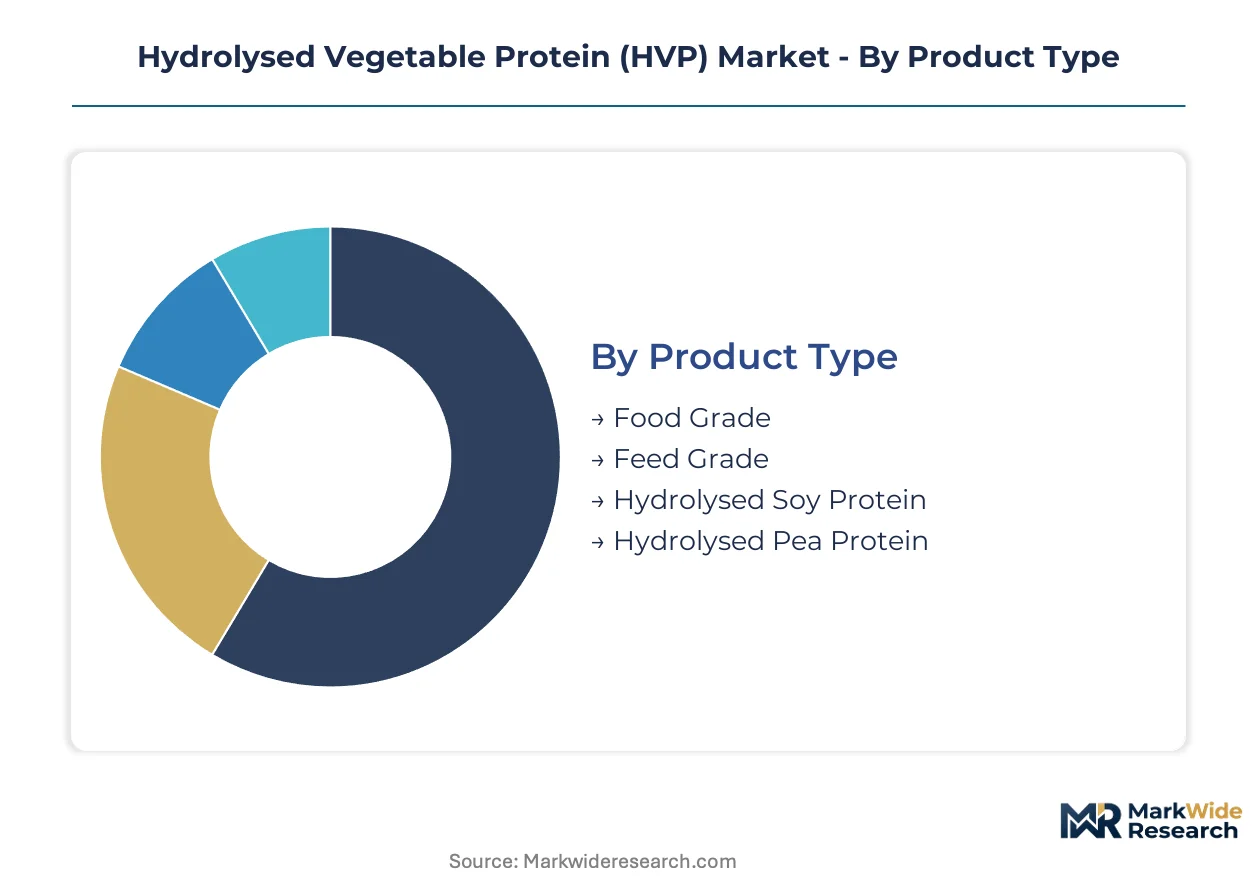
Hydrolysed vegetable protein specifications diverge sharply across downstream applications, with food safety certifications and processing method disclosures now functioning as primary selection criteria. Procurement teams weight enzymatic versus acid hydrolysis documentation differently depending on end-use exposure and regional regulatory exposure.
Product Type:
Certification burdens stratify sharply across this category, with food-grade segments requiring EFSA additive evaluations and FDA GRAS documentation while feed-grade alternatives face less stringent purity thresholds.
- Food Grade:Stringent residual solvent limits under REACH protocols and EFSA purity mandates command premium positioning in clean-label savory formulations. German and Dutch plant-based meat manufacturers specify enzymatic hydrolysis methods exclusively, disqualifying acid-processed alternatives from premium tenders.
- Hydrolysed Pea Protein:Allergen-free positioning is displacing soy-derived alternatives in European and North American formulations, with Canadian yellow pea feedstock diversifying raw material geography beyond Brazilian concentration. Ukrainian cultivation expansion is reducing single-origin supply risk for processors.
- Feed Grade:Lower purity thresholds reduce regulatory documentation intensity for animal nutrition applications.
- Hydrolysed Soy Protein:Brazilian drought cycles are hardening concentrate availability from Paraná and Mato Grosso processors.
Food Grade sits at the top of the volume ranking, with Hydrolysed Pea Protein climbing the fastest.
Application:
Cost tier differentiation separates commodity sauce applications from premium meat alternative formulations, with enzymatic hydrolysis commanding three-to-four-fold price premiums over acid-processed alternatives.
- Meat Alternatives:EU Green Deal sustainability mandates are compressing sourcing timelines for European food manufacturers, forcing accelerated reformulation cycles in plant-based savory applications. Clean-label positioning requires full hydrolysis method disclosure to meet German retailer specifications.
- Sauces:Ready-to-use liquid concentrates gain traction where hydration steps add processing cost, though yeast extract substitution is pressuring HVP volume in cost-sensitive commodity segments.
- Snacks:Umami enhancement functions in seasoned coatings and flavor dust applications.
- Nutritional Supplements:High-protein fortification targets sports nutrition and clinical nutrition formulations.
Meat Alternatives dominates procurement volume, with Nutritional Supplements expanding most quickly on allergen-free positioning.
Form:
Supply chain configuration favors powder dominance for shelf stability and transport efficiency, while liquid concentrates serve regional compounding operations with refrigerated infrastructure.
- Powder:Shelf-stable industrial procurement volumes dominate long-distance supply chains, with EU F-Gas Regulation phase-down schedules pressuring refrigeration-dependent alternatives across French and Italian manufacturers.
- Liquid:Ready-to-use sauce applications reduce hydration processing steps, though ambient-stable concentrate development is accelerating to circumvent cold-chain dependencies.
- Granules:Intermediate dissolution properties suit specific seasoning and broth applications.
- Paste:High-moisture formulations target niche traditional food service channels.
Powder leads industrial procurement, with Liquid gaining share fastest in ready-to-use reformulations.
End User:
Customer type determines specification intensity, with food manufacturers demanding full process documentation while restaurant channels prioritize cost and flavor performance over certification depth.
- Food Manufacturers:Direct supplier relationships are displacing distributor intermediation in mid-scale European meat alternative ventures, with technical marketing teams now controlling procurement authority for hydrolysis method disclosure.
- Nutraceutical Companies:Protein fortification specifications require amino acid profile documentation and heavy metal testing under divergent GB standard and Codex Alimentarius parameters.
- Animal Feed Producers:Lower documentation thresholds reduce certification burden for protein supplementation applications.
- Restaurants:Food service channels in Indonesia and Vietnam show minimal HVP adoption in traditional broth formulations.
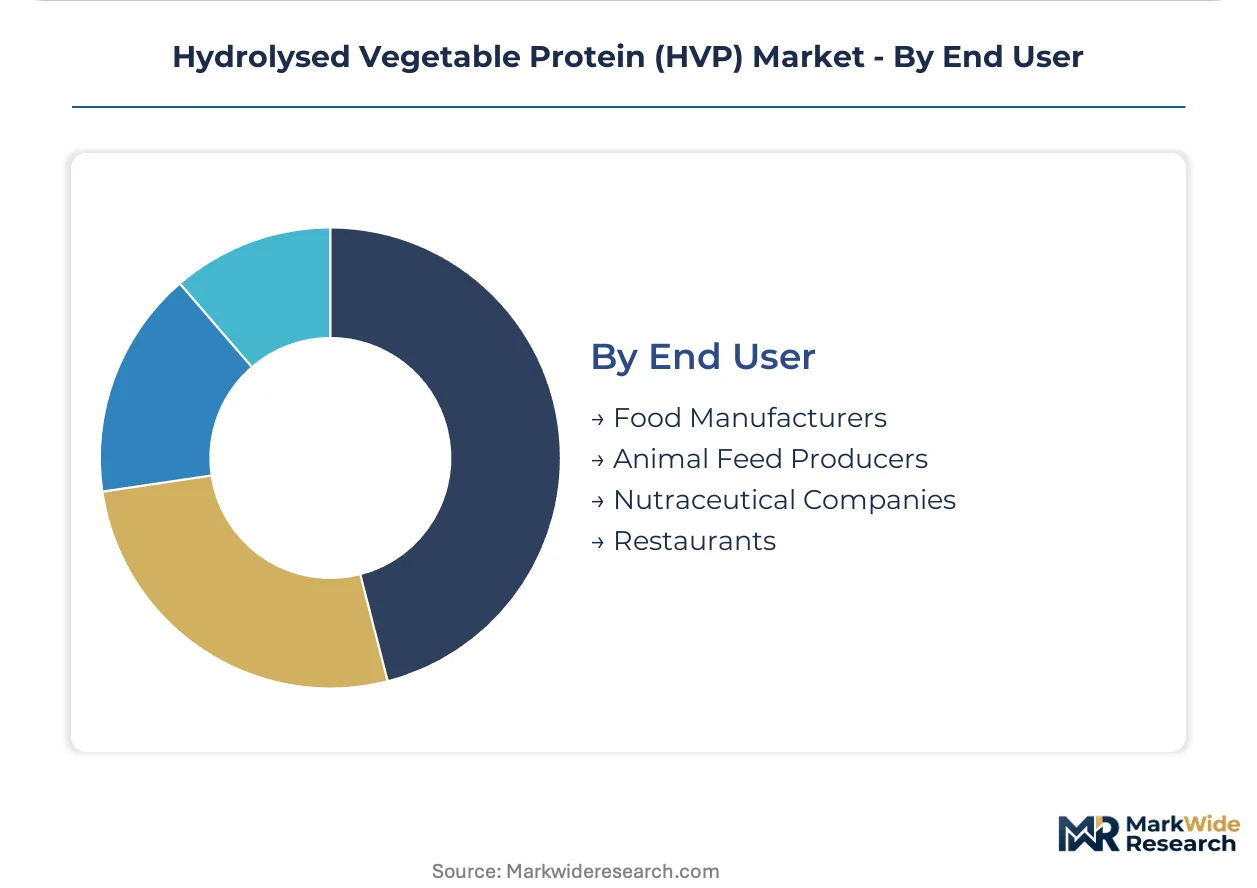
Food Manufacturers represents the largest addressable base, with Nutraceutical Companies ascending fastest on clinical nutrition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning for clean-label savory formulations while Indonesia presents underpenetrated food service channels with minimal HVP adoption in traditional broth applications. Market development diverges sharply between mature European markets with tightening sustainability mandates and emerging Asian economies with nascent ingredient specification culture.
Germany
Plant-based meat manufacturers in Cologne and Hamburg specify enzymatic hydrolysis methods exclusively for clean-label positioning. EFSA additive evaluations and REACH chemical safety protocols disqualify acid-processed alternatives from premium retailer tenders. Bavarian savory formulation labs consolidate volume with single-source fermentation technology partners, displacing distributor intermediation.
United States
FDA GRAS self-affirmation pathways govern ingredient compliance with varying documentation intensity across sauce and snack applications. Clinical nutrition demand pushes nutraceutical companies toward amino acid profile documentation and heavy metal testing. Midwest food manufacturers anchor procurement volumes for powder form shelf stability in long-distance supply chains.
China
SAMR enforces GB standards for imported HVP that diverge from Codex Alimentarius parameters on heavy metal thresholds, creating dual-certification burdens. Yangtze River Delta processors face tightening residual solvent limits under evolving national food safety protocols. Shanghai-based suppliers navigate parallel dossier preparation for European and domestic market entry.
Netherlands
Rotterdam food service channels accelerate customized HVP blends for plant-based formulations under EU Green Deal sustainability disclosure obligations. Corporate Sustainability Reporting Directive mandates pull hydrolysed vegetable protein into clean-label savory applications ahead of 2025 formulation deadlines. Dutch meat alternative ventures consolidate procurement authority with technical marketing teams specifying hydrolysis method disclosure.
Brazil
Paraná and Mato Grosso processors face hardened soy protein concentrate availability as drought cycles tighten raw material flows. ANVISA food additive regulations shape permissible hydrolysis methods for domestic manufacturers while export-oriented suppliers navigate divergent EFSA and FDA requirements. São Paulo-based ingredient distributors manage pricing volatility from single-origin supply concentration.
Hydrolysed Vegetable Protein (HVP) Market Competitive Landscape
European producers anchor the premium tier with fermentation technology leadership; Asian specialists hold cost-competitive positions in commodity acid-hydrolysis segments. The vendor base stratifies across three structural tiers: integrated oilseed processors with upstream cost advantages, dedicated savory ingredient houses with formulation partnerships, and regional hydrolysis specialists serving local sauce manufacturers. Two dominant competitive moves define current positioning: enzymatic hydrolysis capacity expansion for clean-label premiums and backward integration into oilseed crushing for input cost control.
Among fermentation-technology leaders, Ajinomoto Co., Inc. and Kerry Group plc exemplify the premium-tier archetype through sustained positioning in Asian savory markets and European food service channels respectively. Cargill, Incorporated anchors the integrated-processor segment with upstream oilseed processing control extending across multiple protein ingredient categories. These three entities represent distinct strategic positions: technology-driven taste optimization, customized blend formulation partnerships, and scale-driven raw material cost management.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Archer Daniels Midland |
| Cargill, Incorporated |
| Givaudan |
| Roquette Freres |
| Tate & Lyle |
| Griffith Foods |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal sustainability disclosure mandates are pulling enzymatic hydrolysis specifications into German and Dutch procurement tenders, forcing supply chain reconfiguration toward fermentation-capable processors and compressing acid-hydrolysis margins. This demand-side specification shift feeds directly into pricing power concentration among European producers with clean-label certification depth.
Pricing Analysis
Distributor margins in European savory ingredient channels absorb the steepest compression as direct supplier relationships displace intermediation in mid-scale meat alternative ventures. Three-tier pricing structure across premium enzymatic, standard acid-processed, and economy feed-grade levels stratifies by hydrolysis method disclosure and REACH certification completeness. Pricing pressure stems from yeast extract substitution in cost-sensitive sauce applications, with commodity HVP tiers most exposed. Food manufacturers exhibit lowest price sensitivity where clean-label positioning commands retail premium, while food service channels prioritize unit cost over process documentation.
Supply Chain Analysis
EFSA additive evaluations and REACH dossier requirements gate European market access, filtering Asian suppliers through dual-certification timelines that extend validation cycles. Raw material flows concentrate in Brazil for soy protein concentrate and Canada for yellow pea feedstock, with Ukrainian cultivation expanding as secondary origin. Processors draw from acid or enzymatic hydrolysis chemical inputs, fermentation-derived protease blends, and oilseed crushing byproducts. Single-origin concentration in Paraná and Mato Grosso soy processing creates drought-exposed vulnerability. Distribution runs through Rotterdam and Hamburg bulk terminals into direct manufacturer relationships, bypassing traditional distributor networks for premium enzymatic grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon border adjustment exposure and Asian production cost advantages, with embedded emissions tariffs incentivizing regional European fermentation capacity investment over imported acid-hydrolysis alternatives.
For Market Incumbents: Hedge against yeast extract substitution in commodity sauce segments by accelerating enzymatic capacity expansion ahead of EFSA residual solvent limit tightening. Secure backward integration into Canadian yellow pea crushing to reduce Brazilian soy concentration risk. Deepen technical marketing team capabilities to control procurement authority in Dutch and German plant-based formulation labs. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Southeast Asian food service channels offers white-space positioning where traditional broth formulations show minimal HVP adoption. Target Indonesia and Vietnam with ready-to-use liquid concentrate formats that circumvent cold-chain infrastructure gaps. Enter through enzymatic grade differentiation rather than commodity acid-hydrolysis cost competition. For Investors and Strategic Acquirers: Asymmetric upside sits with European fermentation technology specialists holding EFSA-compliant process documentation and single-source partnerships with German meat alternative ventures. Five-to-ten year viability hinges on carbon border adjustment mechanism enforcement intensity and enzymatic hydrolysis patent estate breadth. Watch for EU F-Gas Regulation acceleration signals as inflection indicator for powder form conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Positions suppliers for EFSA residual solvent limits and German clean-label tenders. |
| Backward Integration into Oilseed Crushing | Captures cost advantage in Canadian yellow pea and Brazilian soy supply chains. |
| Direct Manufacturer Relationship Development | Displaces distributor intermediation in Dutch and German meat alternative procurement. |
| Dual-Certification Dossier Investment | Enables parallel REACH and GB standard compliance for European and Chinese market entry. |
| Ambient-Stable Concentrate Formulation | Circumvents EU F-Gas Regulation pressure on refrigerated liquid HVP storage infrastructure. |
Research Methodology
Coverage spans Germany, Netherlands, United States, China, and Brazil, with primary inputs from each market cluster combining interviews with savory formulation technologists, regulatory affairs specialists at ingredient suppliers, procurement leads at plant-based meat manufacturers, and food service distribution channel managers. Secondary validation draws from EFSA additive evaluation databases, REACH registration dossiers, SAMR GB standard filings, and customs trade flow records. Bottom-up volume triangulation across hydrolysis method, feedstock origin, and end-use application segments reconciles against top-down market sizing from oilseed processing capacity and savory ingredient consumption patterns.
Rate-of-change decomposition separates volume growth drivers from price mix effects across the projection horizon, with analytical framework modeling product type, application, form, and end user dimensions alongside hydrolysis method certification tier as industry-specific stratification. CAGRs derive from segment-level trajectory blending rather than single-point extrapolation, incorporating enzymatic hydrolysis adoption curves, EU Green Deal compliance timeline assumptions, and pea protein feedstock expansion rates as forecast inputs.
Caveats apply where Brazilian drought recurrence, REACH protocol amendments, or carbon border adjustment mechanism scope expansion could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between HVP and yeast extract alternatives. A model refresh is warranted upon material change in EFSA residual solvent limit finalization or EU CBAM implementation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Stabilized Starch Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Bean Ingredients Market
Ingredients
South America Feed Yeast Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
Arrowroot Starch Market
Ingredients
Maracuja Oil Market
Ingredients
Pet Food Ingredients Market
Ingredients
United States Corn Glucose Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Borage Oil Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Lime Seed Oils Market
Ingredients
Pig Protein Concentrate Market