
 Angola Lubricants Market | 2026-2036
Angola Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Lubricants Market Insights
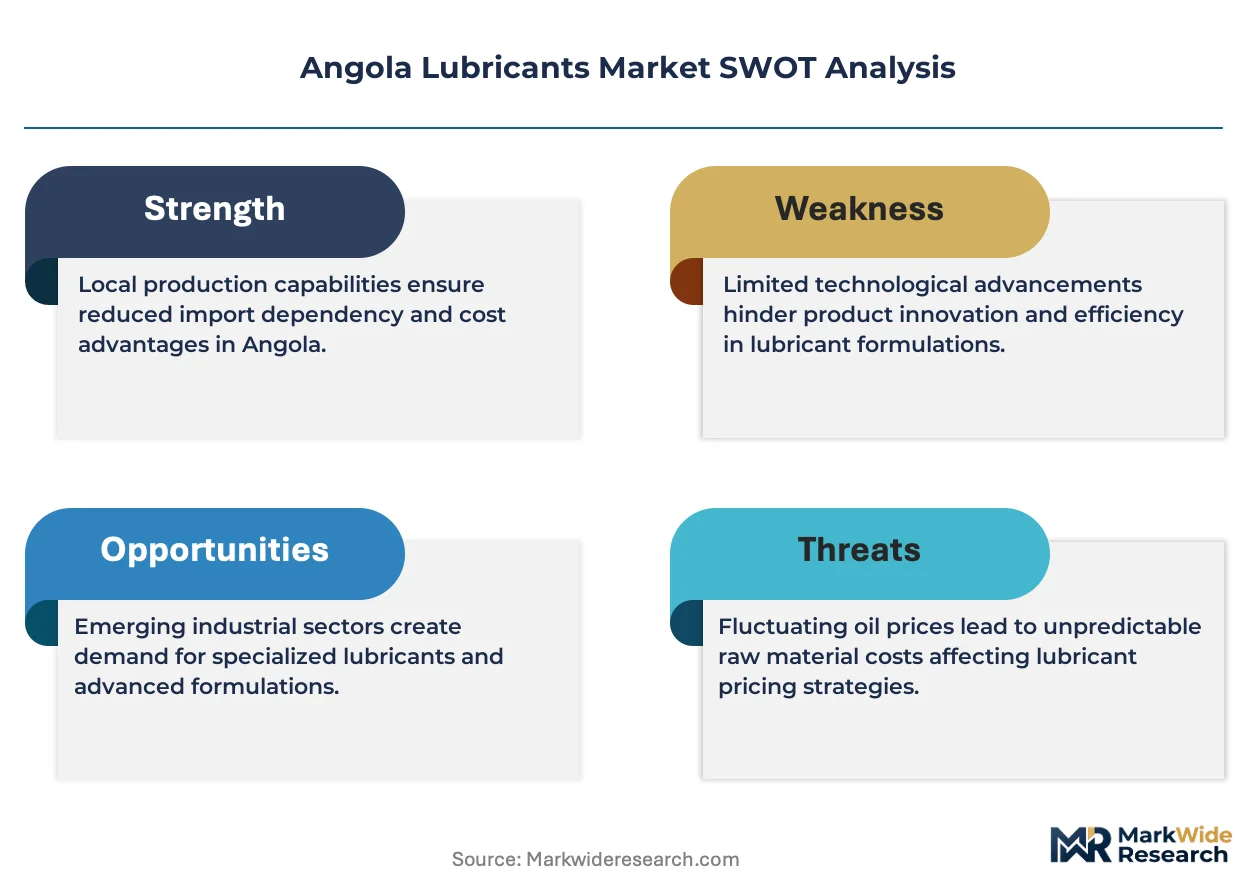
Aftermarket service revenue is narrowing as national oil company procurement shifts toward bundled supply contracts. Sonangol EP leverages its fuel retail network to control lubricant distribution across coastal depots. TotalEnergies anchors its position through technical partnerships with Angolan mining concessionaires. Shell plc competes via specialized hydraulic fluids tailored to tropical operating conditions.
Lubricants are formulated base oils combined with additive packages that reduce friction, dissipate heat, and prevent corrosion in mechanical systems; typical engine oils operate across viscosity grades from SAE 5W-30 to 15W-40 under high-shear conditions. Engine oil dominates product-type revenue due to Angola's expanding vehicle parc and commercial transport intensity. Industrial end users represent the fastest-growing demand pool as cement plants and mining operations upgrade preventive maintenance programs. Wholesale channels capture the largest volume share through direct supply agreements with fleet operators and state-owned enterprises.
Angola's Ministry of Petroleum and national environmental authority enforce storage standards for petroleum products that elevate compliance costs for importers and distributors. The country's quality inspectorate mandates adherence to American Petroleum Institute specifications for automotive lubricants sold through formal retail channels. Stakeholders must monitor infrastructure investment timelines for the Lobito Corridor and associated logistics hubs that will reshape distribution economics.
Market Dynamics
Sonangol EP's bundling of fuel and lubricant procurement is compressing aftermarket margins and forcing distributors to restructure around state-owned enterprise supply contracts.
Growth Catalysts
- Mining fleet synthetic adoption:Concessionaires in the Cuando Cubango diamond belts are switching to extended-drain synthetic formulations. Equipment uptime gains of 40-60 hours between service intervals justify the premium.
- API specification enforcement:Angola's quality inspectorate mandates American Petroleum Institute standards for automotive lubricants sold through formal retail channels. Compliance creates barrier-protected revenue pools for certified importers.
- Lobito Corridor infrastructure:Rehabilitation of the Benguela railway and associated logistics hubs is reducing inland distribution costs for bulk lubricant shipments to Huambo and Lubango industrial zones.
Market Restraints
- Base oil import dependency:Angola lacks domestic Group II/III base oil production. All high-performance lubricants rely on seaborne imports through Luanda port, exposing margins to freight rate volatility and currency fluctuation.
- Coastal storage compliance costs:The petroleum regulator's hazardous fluid handling codes for coastal depots require secondary containment and spill-response infrastructure that elevates working capital requirements for distributors.
- Extended drain intervals:Synthetic lubricant longevity reduces per-vehicle consumption volumes over the equipment lifecycle, compressing addressable market size despite premium pricing.
Strategic Opportunities
- Cabinda enclave penetration:Offshore oil operations in this northern exclave remain underserved by technical lubricant specialists. Local supply agreements with Cabinda Gulf Oil Company could anchor regional distribution.
- Cement plant predictive maintenance:Nova Cimangola and competing clinker producers are upgrading preventive maintenance programs. Condition monitoring integration creates demand for sensor-compatible lubricant formulations.
- Biodegradable hydraulic fluids:Malanje and Uige agricultural mechanization projects face water table protection requirements. Vegetable-oil-based hydraulic formulations qualify for environmental compliance credits.
Industry Challenges
- Blending technical capacity:Local compounders lack formulation chemists capable of additive package optimization for tropical oxidation conditions. Reliance on foreign technical support extends product development cycles.
- Used oil collection infrastructure:The environmental authority's extended producer responsibility framework lacks enforcement mechanisms. Informal disposal contaminates soil around informal mechanic clusters in Viana and Cacuaco.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Lubricants Market |
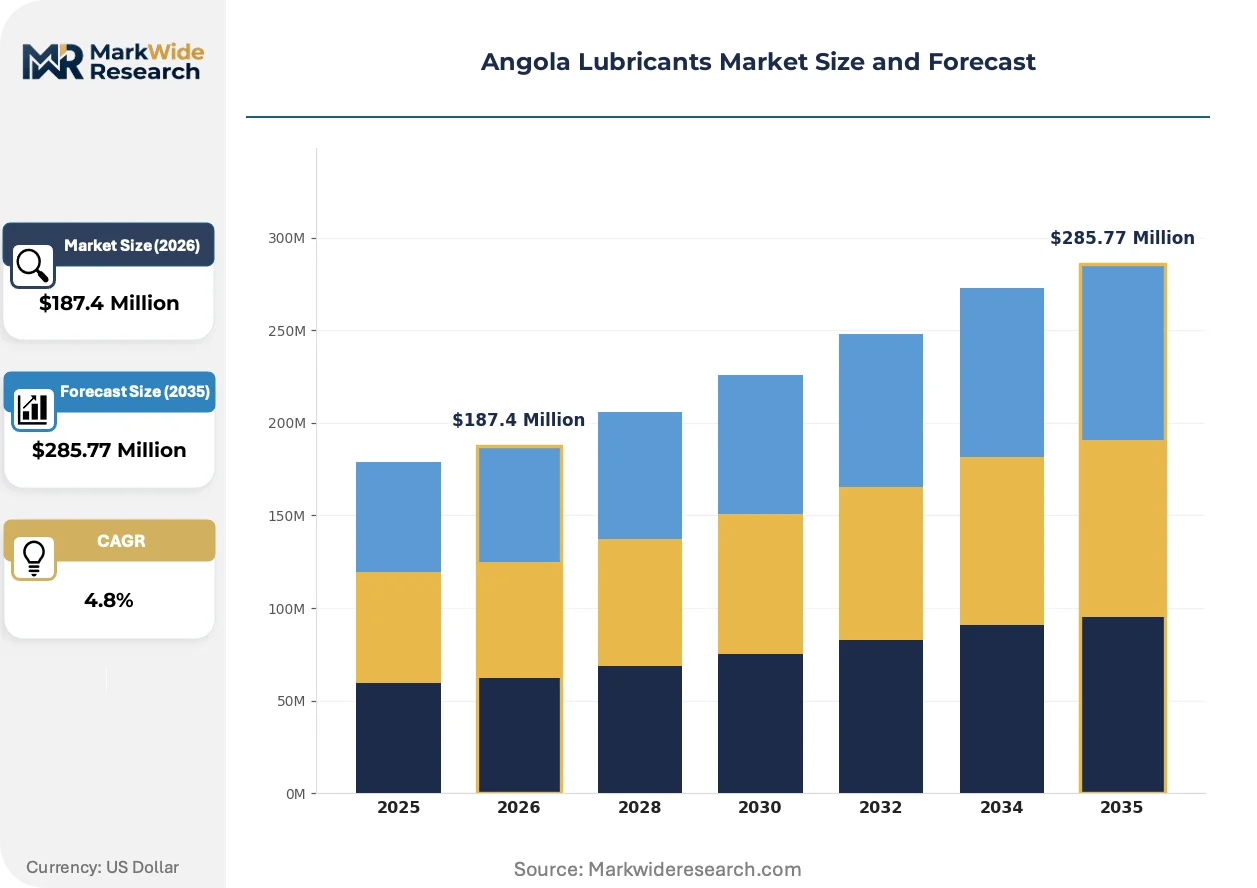
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil End User: Automotive, Industrial, Marine, Aviation Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Automobile Maintenance, Machinery Lubrication, Hydraulic Systems, Equipment Cooling |
| Companies Covered | Sonangol EP, Chevron Corporation, TotalEnergies, Galp, Shell plc, BP p.l.c., Astron Energy (Pty) Ltd, LUBÁFRICA, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Lubricants Market Trends and Innovations
Synthetic formulation advances and procurement restructuring are redrawing competitive boundaries between integrated suppliers and independent distributors.
Polyalphaolefin-based engine oils are hybridizing mineral and synthetic chemistries to deliver thermal stability at lower price points than full synthetics. Fleet operators in Luanda's port logistics sector are piloting these mid-tier formulations for mixed-duty commercial vehicles. The technology is hybridizing the traditional premium-economy segmentation that previously governed Angolan consumer lubricant purchasing.
Angola's Ministry of Petroleum storage standards for petroleum products mandate secondary containment and leak detection systems at coastal depots. Importers face elevated capital expenditure to retrofit existing Luanda and Lobito facilities. Wholesale distributors with compliant infrastructure are capturing volume from smaller competitors unable to absorb compliance costs.
Integrated supply contracts are displacing spot purchasing for state-owned transport and mining fleets. Sonangol EP's bundled fuel-lubricant procurement centralizes decision-making and compresses independent distributor margins. This concentration is most visible in the Luanda industrial corridor, where cement manufacturing and port logistics clusters have consolidated vendor bases around three approved suppliers.
Angola Lubricants Market Segmentation
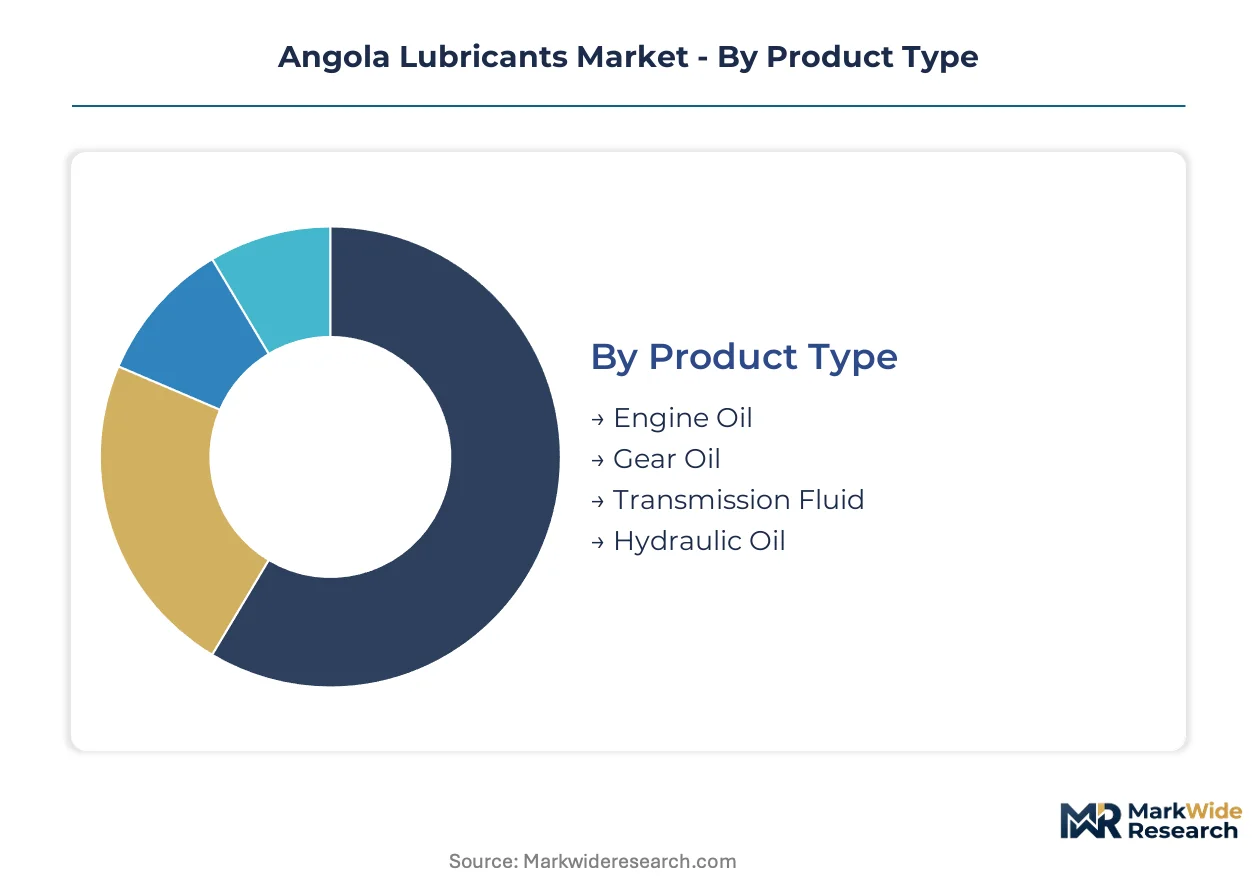
Segmentation in Angola's lubricants market reveals how procurement concentration, technical specifications, and distribution infrastructure shape competitive access. Understanding these divides exposes where bundling power accumulates and where specialist formulations command premium positioning.
Product Type:
Mature mineral formulations dominate volume, while synthetic and semi-synthetic chemistries represent the emerging performance tier where equipment uptime justifies price premiums.
- Engine Oil:Formulated base oils with additive packages spanning SAE 5W-30 to 15W-40 viscosity grades operate under high-shear thermal conditions. Demand concentrates in Luanda's commercial transport corridors, where expanding vehicle parc and fleet renewal programs drive consumption. Sonangol EP's bundled procurement compresses aftermarket margins for independent distributors.
- Hydraulic Oil:Anti-wear formulations with oxidation inhibitors protect high-pressure systems in tropical humidity. Mining concessionaires in Cuando Cubango diamond belts specify extended-drain synthetics to stretch service intervals. Shell plc tailors tropical-grade variants for this specification-sensitive segment.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry protect differentials and transmissions under shock loading. Cement plant operators in the Luanda industrial corridor specify these for raw material grinding equipment.
- Transmission Fluid:Friction-modified formulations enable smooth power transfer in automatic and manual gearboxes. Port logistics fleets favor bulk procurement through wholesale channels for mixed-duty commercial vehicles.
Engine Oil retains volume leadership; Hydraulic Oil holds the steepest expansion curve.
End User:
Cost tier segmentation separates state-backed volume purchasers from private operators optimizing total cost of ownership through premium formulations.
- Industrial:Cement manufacturing and mining operations drive demand for condition-monitoring-compatible lubricants with predictive maintenance integration. Nova Cimangola and competing clinker producers upgrade preventive programs, creating specification pull for sensor-compatible formulations.
- Automotive:Commercial transport intensity in Luanda's port logistics sector sustains bulk consumption, while passenger vehicle aftermarket channels face margin compression from Sonangol EP's retail network control.
- Marine:Offshore oil operations in the Cabinda enclave require specialized marine lubricants with high TBN retention for slow-speed two-stroke engines. Technical supply agreements with Cabinda Gulf Oil Company anchor regional distribution potential.
- Aviation:Jet engine oils and hydraulic fluids for commercial and charter operations at Luanda's Quatro de Fevereiro Airport demand certified supply chains with batch traceability and cold-flow performance guarantees.
Automotive retains volume leadership; Industrial holds the steepest expansion curve.
Distribution Channel:
Supply concentration favors wholesale direct agreements, while compliance cost barriers reshape retail and emerging digital pathways.
- Wholesale:Direct supply agreements with fleet operators and state-owned enterprises capture the largest volume share. Distributors with compliant coastal depot infrastructure capture volume from smaller competitors unable to absorb petroleum regulator secondary containment requirements.
- Retail:Formal channels through service stations and automotive parts networks face API specification enforcement barriers that protect certified importers. Sonangol EP leverages its fuel retail network to control lubricant distribution across coastal depots.
- Direct Sales:Integrated supply contracts displace spot purchasing for mining and cement manufacturing clusters, consolidating vendor bases around approved suppliers in the Luanda industrial corridor.
- Online:Emerging digital procurement platforms serve independent mechanics and smaller fleet operators, though logistics infrastructure limits penetration beyond Luanda and major provincial centers.
Wholesale retains volume leadership; Direct Sales holds the steepest expansion curve.
Application:
Geographic clustering determines where specification intensity meets procurement scale, with machinery lubrication and hydraulic systems commanding technical differentiation.
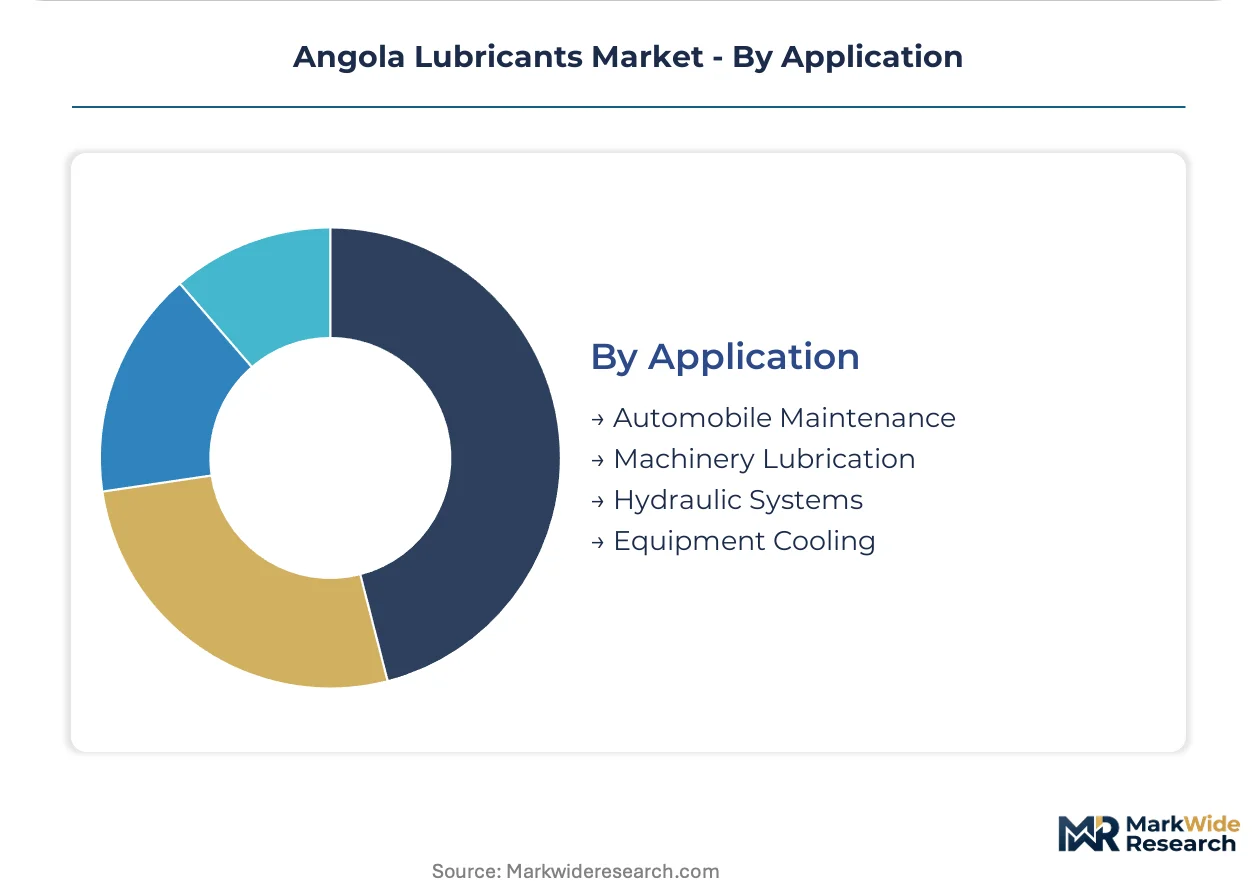
- Machinery Lubrication:Open-gear sprays, circulating oils, and compressor lubricants protect cement kilns, mining crushers, and agricultural equipment. Malanje and Uige agricultural mechanization projects face water table protection requirements that favor biodegradable formulations.
- Hydraulic Systems:High-pressure fluid power applications in mining shovels, port cranes, and drilling equipment demand cleanliness-coded products with particulate contamination control. Vegetable-oil-based formulations qualify for environmental compliance credits in sensitive watersheds.
- Automobile Maintenance:Engine oil changes, transmission servicing, and brake fluid replacement sustain high-frequency consumption in urban centers. Informal mechanic clusters in Viana and Cacuaco lack used oil collection infrastructure, creating regulatory exposure.
- Equipment Cooling:Heat transfer fluids and specialized coolants manage thermal loads in power generation and industrial process equipment. Lobito Corridor rehabilitation will reshape distribution economics for inland thermal power plant supply.
Automobile Maintenance retains volume leadership; Machinery Lubrication holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blending capacity concentrates in Luanda's industrial corridor, where port access and coastal depot infrastructure create distribution advantages for bulk lubricant handlers. Provincial demand centers in Huambo, Lubango, and Cabinda remain tethered to this coastal supply axis through rail and road logistics.
Luanda Province
Port logistics and cement manufacturing clusters drive specification-grade consumption across SAE 15W-40 and hydraulic oil categories. Angola's Ministry of Petroleum storage standards mandate secondary containment systems at coastal depots, elevating capital requirements for distributors. The Viana industrial zone hosts informal mechanic clusters lacking used oil collection infrastructure, creating regulatory exposure.
Benguela Province
Lobito Corridor rehabilitation reduces inland distribution costs for bulk shipments to competing industrial zones. The petroleum regulator's hazardous fluid handling codes apply with equal force here, though depot compliance lags Luanda's retrofit timeline. Nova Cimangola's clinker operations anchor demand for open-gear and circulating oils in this corridor.
Huíla Province
Lubango's emerging logistics hub status attracts wholesale distributors seeking alternatives to Luanda port congestion. Mining concessionaires in neighboring Cuando Cubango source synthetic formulations through this southern distribution node. The Benguela railway's operational reliability dictates replenishment cycle timing for high-performance lubricant stocks.
Cabinda Enclave
Offshore oil operations generate demand for marine lubricants with high TBN retention and slow-speed two-stroke compatibility. Cabinda Gulf Oil Company procurement operates through specialized technical supply agreements rather than bundled fuel contracts. Local distribution infrastructure remains underdeveloped relative to specification complexity.
Huambo Province
Agricultural mechanization projects in Malanje and Uige draw biodegradable hydraulic fluid demand through this central logistics node. Water table protection requirements favor vegetable-oil-based formulations qualifying for environmental compliance credits. Wholesale channels capture volume through direct agreements with state-backed farm equipment operators.
Angola Lubricants Market Competitive Landscape
Integrated petroleum majors and specialized lubricant distributors split the market between bundled procurement power and technical formulation expertise. Sonangol EP's vertical control over fuel retail networks compresses independent aftermarket margins. Three archetypes dominate: state-backed integrated suppliers, international majors with tropical formulation capabilities, and regional distributors with compliant coastal infrastructure. Competitive moves center on procurement bundling and depot compliance retrofitting.
Among international majors with African operational experience, TotalEnergies, Shell plc, and BP p.l.c. occupy positions defined by technical partnership depth and tropical-grade product portfolios. Chevron Corporation and ExxonMobil Corporation represent the scale-driven archetype with integrated upstream-downstream presence. Regional specialists including Galp and Astron Energy exemplify distributors leveraging geographic proximity and flexible supply arrangements. LUBÁFRICA anchors the local blending tier with Portuguese-African operational heritage.
| Leading Market Players |
|---|
| Sonangol EP |
| Chevron Corporation |
| TotalEnergies |
| Galp |
| Shell plc |
| BP p.l.c. |
| Astron Energy (Pty) Ltd |
| LUBÁFRICA |
| ExxonMobil Corporation |
| Others |
Pricing and Supply Chain Analysis
Freight rate volatility through Luanda port determines both the spread between mineral and synthetic lubricant pricing tiers and the coastal concentration of blending infrastructure. This dependency compresses margins for distributors lacking long-term shipping contracts while rewarding those with captive storage at compliant coastal depots.
Pricing Analysis
Angola's Ministry of Petroleum storage standards dictate the pricing tier structure by elevating compliance costs for secondary containment and leak detection systems. Three-tier pricing structure across premium, standard, and economy levels separates full synthetic formulations from mineral blends and polyalphaolefin hybrids. Price differentiation rests on API certification grade and volume scale, with Sonangol EP's bundled procurement extracting steepest discounts. Cost compression in the aftermarket tier is intensifying because independent distributors cannot absorb retrofit capital requirements. Fleet operators prove least price-sensitive due to uptime-value calculations, while informal mechanic clusters in Viana exhibit highest sensitivity.
Supply Chain Analysis
Export-control restrictions on advanced additive packages from European and North American suppliers limit formulation sophistication available to local compounders. Geographic supply concentrates in Belgium, Singapore, and the United Arab Emirates as primary sources for Group II/III base oils and additive masterbatches. Raw material dependencies span polyalphaolefin feedstocks, viscosity index improvers, and anti-wear chemistries. Single-source vulnerability runs through Luanda port congestion and currency fluctuation exposure. Distribution runs through wholesale direct agreements with state-owned enterprises and mining concessionaires, bypassing fragmented retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sonangol EP's procurement consolidation has shifted buyer power toward bundled contract structures, compressing aftermarket margins and forcing vendor base reduction around three approved suppliers in the Luanda industrial corridor.
For Market Incumbents: Harden coastal depot compliance infrastructure before petroleum regulator enforcement deadlines to capture volume from smaller distributors unable to retrofit secondary containment systems. Deepen technical partnerships with Cuando Cubango mining concessionaires to anchor synthetic formulation demand against substitute mineral blends. Prioritize additive package optimization for tropical oxidation conditions to reduce foreign technical support dependency. For New Entrants and Emerging Players: Pursue Cabinda enclave marine lubricant supply agreements where Cabinda Gulf Oil Company procurement operates outside Sonangol EP's bundled fuel contracts. Target biodegradable hydraulic fluid formulations for Malanje and Uige agricultural mechanization projects facing water table protection requirements. Lead with environmental compliance credits as the go-to-market angle to differentiate from established mineral suppliers. For Investors and Strategic Acquirers: Regional distributors with compliant coastal infrastructure and Portuguese-African operational heritage represent the most defensible acquisition profile. Long-term viability hinges on Lobito Corridor logistics hub positioning and Benguela railway reliability improvements. Watch for petroleum regulator enforcement acceleration as the inflection indicator forcing distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Storage | Captive supply of Group II/III stocks through Luanda port long-term terminal agreements insulates margin from freight volatility. |
| Long-term Supply Agreement with Mining Concessionaires | Extended-drain synthetic formulations for Cuando Cubango diamond belts anchor predictable offtake volumes. |
| Joint Venture with Local Blending Facility | Technical knowledge transfer addresses additive package optimization gaps for tropical oxidation conditions. |
| Green Certification Program for Biodegradable Formulations | Vegetable-oil-based hydraulic fluids qualify for environmental compliance credits in Malanje and Uige watersheds. |
| Capacity Expansion at Lobito Corridor Hub | Benguela railway rehabilitation reduces inland distribution costs for bulk shipments to Huambo and Lubango industrial zones. |
Research Methodology
Cross-validation between procurement director interviews at Sonangol EP and Nova Cimangola anchors the qualitative findings against distributor margin compression claims. Primary discussions with mining fleet managers, cement plant maintenance directors, coastal depot operators, and petroleum regulator officials combined with customs trade data, Ministry of Petroleum storage standard filings, and SEC disclosures from international majors. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down import value flows through Luanda port.
Calibration against historical base oil import volumes and synthetic formulation adoption curves in comparable African mining economies shapes the projection framework. Segmentation dimensions span product type viscosity grades, end-use industry intensity, distribution channel concentration, and regional logistics hub access. CAGRs derive from equipment parc expansion rates and drain interval extension trends. Forecast inputs incorporate Benguela railway rehabilitation timelines and petroleum regulator enforcement phase-in assumptions.
Macroeconomic conditions sit as an overlay; deviation in kwanza exchange rate stability and seaborne freight indices would shift the trajectory. Forecasts reflect documented assumptions regarding mining concession renewal patterns and cement capacity expansion schedules. Material shifts in Lobito Corridor infrastructure investment pacing or petroleum regulator enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Neat Cutting Oil Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Global Grease Market
Lubricants
Lubricity Improvers Market
Lubricants
Asia-Pacific Commercial Vehicles Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Europe Metalworking Fluids Market