
 Forestry Lubricants Market | 2026-2036
Forestry Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Forestry Lubricants Market Analysis
Biodegradable specification upgrades is reorganizing procurement priorities across the forestry lubricants sector. Exxon Mobil Corporation leverages its synthetic base stock technology to command premium positioning in chainsaw oil formulations. Shell plc anchors European supply through its Rotterdam blending complex, while FUCHS PETROLUB SE specializes in OEM-approved hydraulic fluid portfolios for harvester manufacturers.
Forestry lubricants comprise formulated oils and greases engineered with high viscosity indices, extreme-pressure additives, and anti-wear chemistries to protect equipment operating in abrasive, high-moisture woodland environments. Their primary purpose is to reduce friction-related downtime in chainsaws, skidders, and forwarders while mitigating soil contamination risks from fluid leakage. Chainsaw oils and hydraulic fluids carry the dominant volume positions, with biodegradable oils representing the fastest-expanding margin pool as regulatory thresholds tighten. Saw mill operations and logging equipment applications concentrate the highest per-unit lubricant consumption, while direct sales channels capture the largest revenue share through bulk supply contracts with integrated forestry companies.
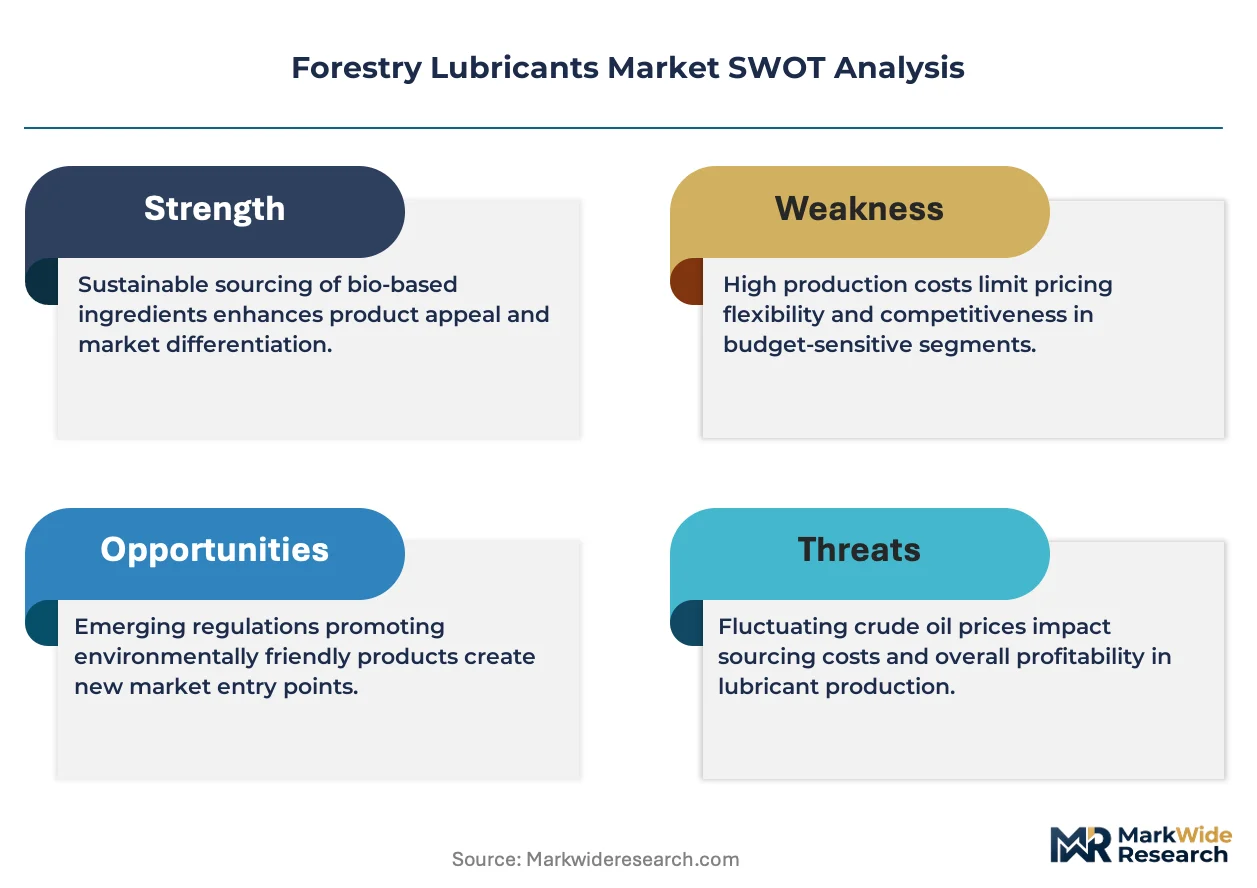
EPA guidelines in the United States and the EU Green Deal framework in Europe are elevating biodegradability benchmarks for lubricants used in sensitive watershed zones, forcing reformulation investments across the supply base. Health Canada's PMRA and the EU ECHA jointly influence acceptable additive chemistries through substance restriction schedules. Stakeholders must monitor evolving bio-based content mandates and assess backward integration into ester base stock production to secure formulation flexibility against tightening compliance timelines.
Market Dynamics
Mechanized logging intensity across Nordic boreal zones is compressing maintenance intervals and forcing fluid specification upgrades, while the EU F-Gas Regulation and EPA watershed guidelines simultaneously tighten biodegradability thresholds and refrigerant containment standards for forestry machinery.
Growth Catalysts
- EU Green Deal biodegradability mandates:Watershed protection zones in Finland and Sweden now require ester-based hydraulic fluids, pulling reformulation investment from blenders serving the Baltic timber corridor.
- Harvester automation density:Computerized felling heads and boom controls in mechanized cut-to-length systems multiply hydraulic circuit complexity and fluid volume requirements per machine.
- Finland's timber processing corridor:Stora Enso and UPM-Kymmene integrated operations concentrate bulk lubricant procurement through direct supply contracts, anchoring regional volume.
Market Restraints
- Base ester feedstock volatility:Rapeseed and sunflower oil prices swing with agricultural commodity cycles, squeezing margin predictability for biodegradable hydraulic fluid producers.
- Specialized additive supply concentration:Extreme-pressure sulfur-phosphorus chemistries and ashless dispersants for high-moisture woodland operation source from a narrow German and Swiss supplier base.
- Technical performance ceiling:Vegetable ester base stocks hydrolyze faster than mineral oils in high-temperature hydraulic pumps, limiting deployment in heavy-duty forwarder transmissions.
Strategic Opportunities
- Estonia and Latvia mechanization gap:Baltic states below Nordic automation penetration rates present conversion potential as EU rural development funds modernize logging fleets.
- Carbon accounting integration:The EU Corporate Sustainability Reporting Directive creates demand for lifecycle-assessed lubricants with verified bio-based content claims.
- Digital fluid monitoring convergence:IoT sensors embedded in harvester hydraulic systems enable predictive drain-interval optimization, opening subscription-based fluid management services.
Industry Challenges
- Tribology specialization scarcity:Formulation chemists with simultaneous expertise in biodegradable base stocks and extreme-pressure woodland performance are concentrated among retiring German technical staff.
- OEM approval timeline compression:John Deere and Ponsse certification protocols for new hydraulic fluid chemistries extend 18-24 months, lagging regulatory compliance deadlines.
- Legacy equipment compatibility:Seals and hoses in 10-15 year old Valmet and Timberjack machines degrade with high-oleic ester exposure, forcing fleet upgrade coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forestry Lubricants Market |
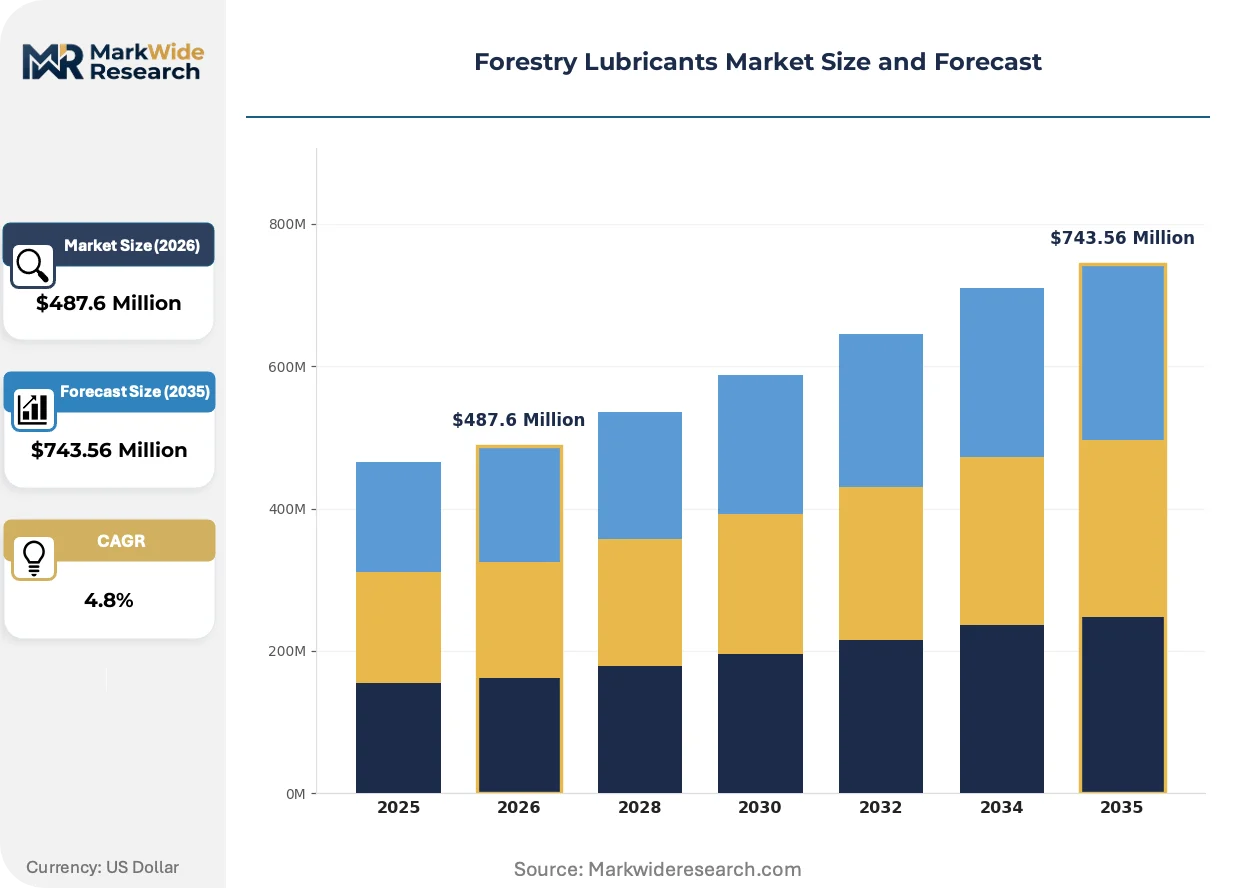
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Oils, Hydraulic Fluids, Greases, Chainsaw Oils Application: Logging Equipment, Tree Harvesting, Stump Grinding, Saw Mill Operations End User: Forestry Companies, Equipment Manufacturers, Independent Contractors, Tree Service Providers Distribution Channel: Retail, Wholesale, Direct Sales, E-Commerce |
| Companies Covered | FUCHS PETROLUB SE, Repsol SA, Exxon Mobil Corporation, Quaker Chemical Corporation, The Lubrizol Corporation, Shell plc, Phillips 66 Company, Petro-Canada Lubricants Inc., Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forestry Lubricants Market Emerging Trajectories
Synthetic ester chemistry, regulatory carbon accounting, and procurement digitization are simultaneously rewriting formulation priorities, compliance documentation, and buyer-supplier relationships across the forestry lubricants sector.
High-viscosity synthetic ester base stocks with tailored pour-point depressants are bifurcating the hydraulic fluid category. Mechanized harvester operators in Finland and Sweden are specifying these grades for year-round cold-start reliability despite 40% cost premiums over mineral alternatives. The technology is compressing conventional Group II hydraulic oil volumes in new equipment while creating a two-tier aftermarket split between premium synthetic and economy mineral segments.
The EU F-Gas Regulation phase-down schedule is forcing refrigerant containment upgrades in climate-controlled forestry machinery cabs. Compressor lubricant specifications now demand compatibility with lower-GWP HFO refrigerants, compelling blenders to reformulate polyolester chemistries. Nordic OEM equipment shipments are leading this transition, with hydraulic system integrators bundling compliant lubricant packages to simplify dealer compliance.
Integrated forestry companies are consolidating lubricant procurement through enterprise resource planning platforms that tie fluid consumption data to equipment telematics. Stora Enso's direct supplier relationships now incorporate automated reorder triggers based on operating hour accumulation rather than calendar-based contracts. This pattern is most advanced in Finnish saw mill operations where bulk tank monitoring enables just-in-time delivery optimization.
Forestry Lubricants Market Segmentation
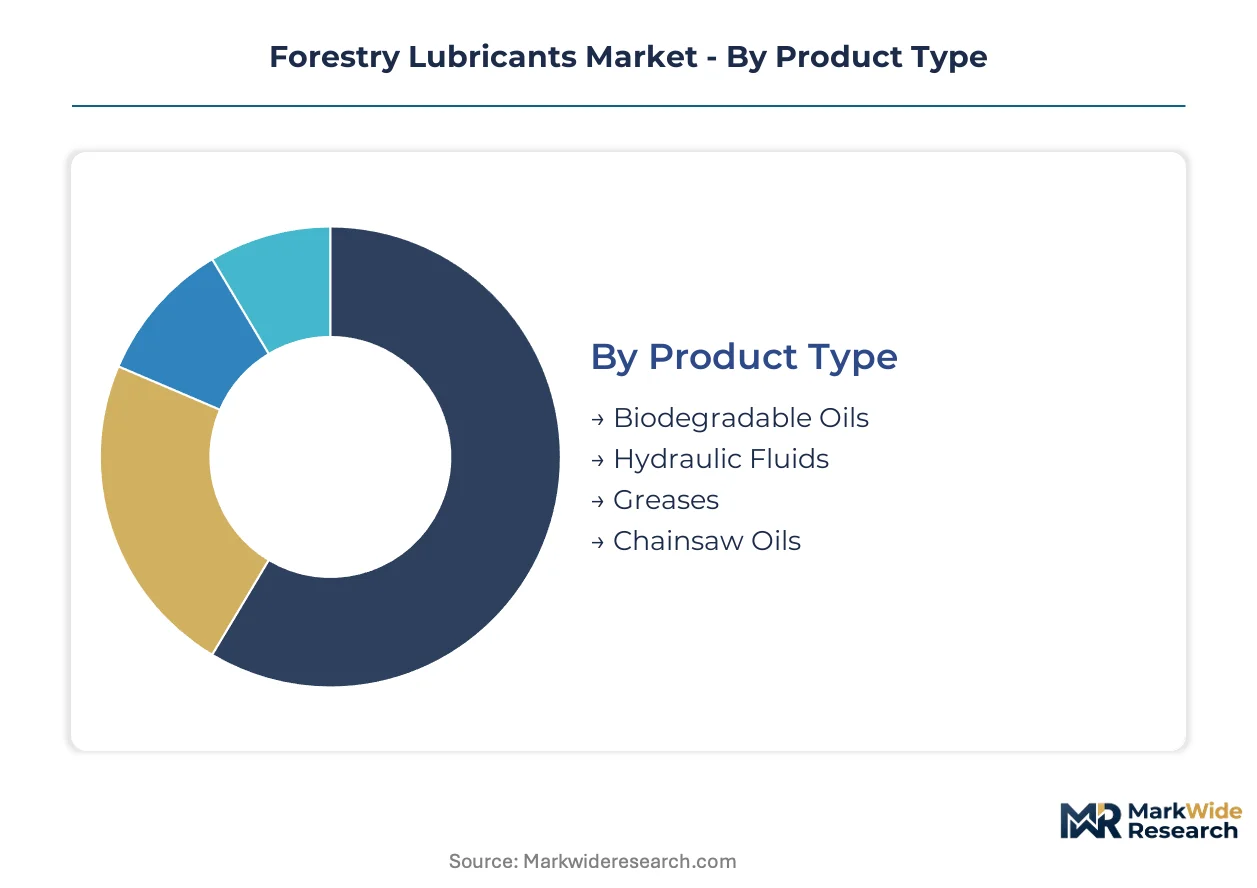
Segmentation in forestry lubricants reveals where specification pressures and procurement consolidation are reshaping supplier economics. Equipment complexity and regulatory thresholds fragment demand across performance tiers, forcing blenders to prioritize reformulation investments in high-margin biodegradable categories.
Product Type:
Biodegradable specification mandates are displacing mineral-based formulations fastest in hydraulic applications, where EU watershed regulations impose the steepest substitution penalties.
- Biodegradable Oils:Ester-based formulations with high oleic content deliver rapid environmental degradation in soil and water exposure. Finnish saw mill operators now mandate these grades for equipment operating within 500 meters of protected waterways, pulling rapeseed and sunflower base stock demand.
- Hydraulic Fluids:Synthetic and mineral formulations with extreme-pressure additives protect high-pressure circuits in mechanized harvesters. Computerized felling heads in Sweden's cut-to-length systems multiply fluid volume requirements per machine while compressing drain intervals.
- Greases:Lithium complex and calcium sulfonate thickeners protect boom pins and slew bearings in high-moisture woodland conditions.
- Chainsaw Oils:High-tack mineral and vegetable-based formulations reduce sling-off in high-speed cutting operations.
Biodegradable oils retain volume leadership; hydraulic fluids hold the steepest expansion curve as harvester automation density multiplies circuit complexity.
Application:
Mechanization intensity varies sharply across logging stages, concentrating lubricant consumption in capital-intensive equipment categories.
- Logging Equipment:Skidders, forwarders, and harvesters consume hydraulic fluids and greases at the highest per-machine rates. Stora Enso's integrated Finnish operations anchor bulk procurement through direct supply contracts tied to operating hour accumulation.
- Saw Mill Operations:Debarkers, edgers, and kilns require continuous lubrication of conveyor chains and bearing systems. Baltic states below Nordic automation penetration present conversion potential as EU rural development funds modernize processing facilities.
- Tree Harvesting:Chainsaw and felling head lubrication demands high-tack, anti-sling formulations.
- Stump Grinding:High-torque cutter wheel bearings and hydraulic lift circuits require extreme-pressure greases and fluids.
Logging equipment captures the dominant revenue share; saw mill operations are gaining share fastest as timber processing corridor investments concentrate in Finland and surrounding Baltic states.
End User:
Procurement sophistication separates integrated operators with enterprise resource planning platforms from fragmented contractor bases purchasing through retail channels.
- Forestry Companies:Stora Enso and UPM-Kymmene negotiate direct supply contracts with automated reorder triggers based on telematics data. Bulk tank monitoring enables just-in-time delivery optimization across Finnish saw mill networks.
- Equipment Manufacturers:John Deere and Ponsse specify OEM-approved hydraulic fluid portfolios, extending certification protocols 18-24 months and lagging regulatory compliance deadlines.
- Independent Contractors:Price-sensitive operators in Estonia and Latvia purchase through wholesale distributors with limited specification negotiation leverage.
- Tree Service Providers:Municipal and utility arborists source chainsaw oils through retail and e-commerce channels with smaller volume scale.
Forestry companies dominate procurement value; equipment manufacturers are expanding specification influence fastest through OEM approval requirements.
Distribution Channel:
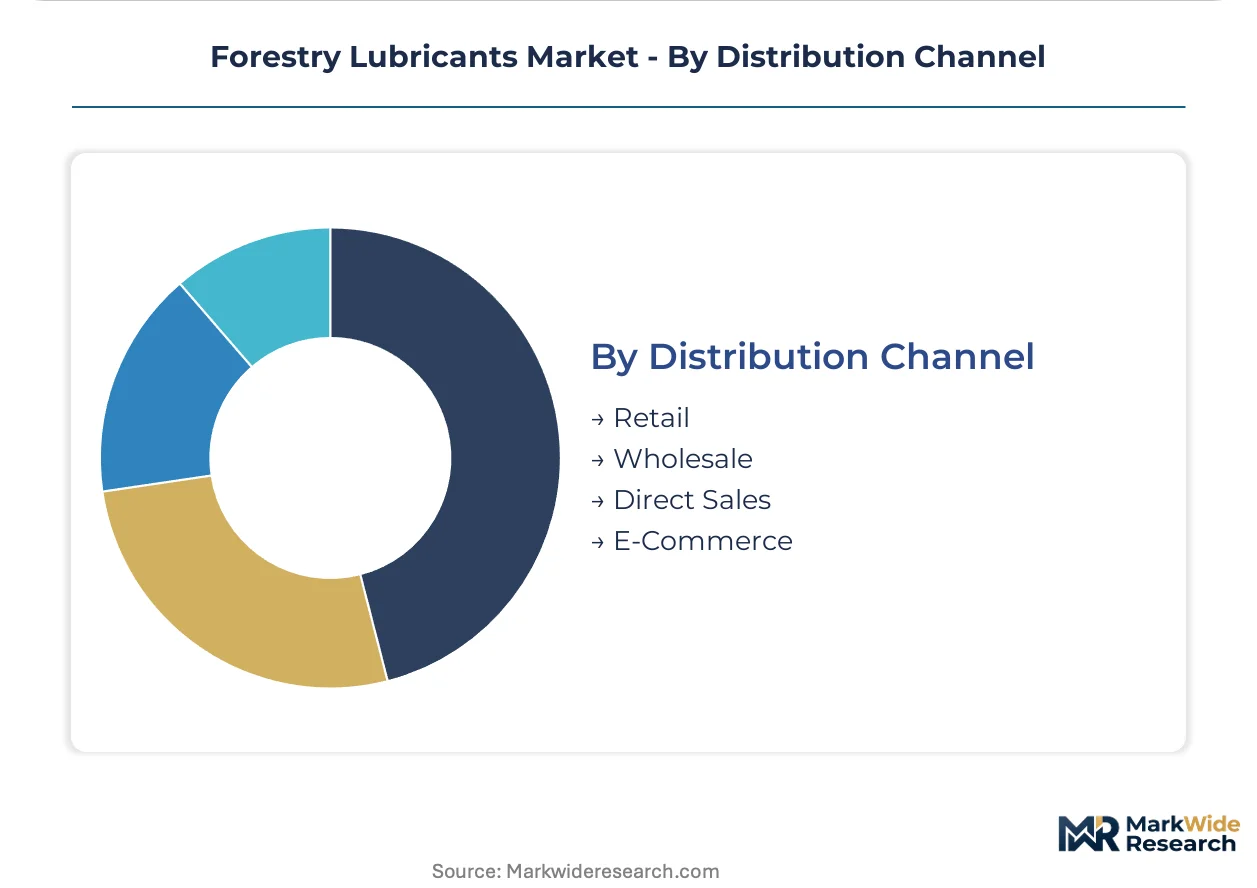
Channel selection correlates directly with end-user scale and technical service requirements.
- Direct Sales:Bulk supply contracts with integrated forestry companies capture the largest revenue share through tank wagon and drum deliveries coordinated with equipment telematics.
- Wholesale:Distributors serve mid-sized contractors and independent logging operations across the Baltic timber corridor with blended product portfolios.
- Retail:Chainsaw oils and small-package greases reach tree service providers and hobbyist users through agricultural supply stores.
- E-Commerce:Digital procurement platforms are emerging for standardized grades with documented specifications and rapid replenishment needs.
Direct sales anchor revenue concentration; e-commerce is climbing the fastest as procurement digitization penetrates smaller contractor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor segments in Estonia and Latvia exhibit acute price sensitivity to base ester feedstock swings, while integrated Finnish operators absorb premium synthetic grades with minimal volume elasticity.
Finland
Stora Enso and UPM-Kymmene operations anchor Nordic demand through enterprise resource planning platforms that automate reorder triggers based on equipment telematics. The EU F-Gas Regulation compels refrigerant containment upgrades in climate-controlled harvester cabs, pulling reformulation investment toward polyolester compressor lubricants. The timber processing corridor between Joensuu and Jyväskylä concentrates bulk hydraulic fluid procurement through direct supply contracts tied to operating hour accumulation.
Sweden
Computerized felling heads in cut-to-length systems multiply hydraulic circuit complexity and fluid volume requirements per machine. The EU Green Deal watershed protection mandates now require ester-based hydraulic fluids within 500 meters of protected waterways, forcing specification upgrades across Västerbotten and Norrbotten counties. Mechanized harvester operators in these northern zones specify high-viscosity synthetic ester grades for year-round cold-start reliability despite substantial cost premiums.
Germany
Extreme-pressure sulfur-phosphorus chemistries and ashless dispersants for high-moisture woodland operation source from a narrow German and Swiss supplier base concentrated in this market. REACH substance restriction schedules through ECHA influence acceptable additive chemistries across European formulation networks. The Baden-Württemberg industrial cluster hosts specialized tribology expertise for biodegradable base stock development, though retiring technical staff create capability scarcity.
Estonia
Baltic states below Nordic automation penetration rates present conversion potential as EU rural development funds modernize logging fleets. Price-sensitive independent contractors purchase through wholesale distributors with limited specification negotiation leverage, exposing them to rapeseed and sunflower oil commodity cycles. The Tartu-Pärnu corridor shows emerging mechanization density as foreign capital enters timber processing infrastructure.
Canada
Health Canada's PMRA jointly influences acceptable additive chemistries with EU ECHA through substance restriction schedules. British Columbia and Quebec forestry operations face watershed protection guidelines that elevate biodegradability benchmarks for lubricants used in sensitive zones. The Pacific Northwest timber belt shows concentrated demand for high-tack chainsaw formulations in steep-terrain logging applications.
Forestry Lubricants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the forestry lubricants sector. Integrated petrochemical majors leverage synthetic base stock capabilities and global blending networks, while specialized lubricant formulators compete through OEM approval relationships and biodegradable portfolio depth. The market structure separates into three strategic archetypes: petrochemical conglomerates with captive base stock supply, independent blenders with OEM certification focus, and regional distributors serving price-sensitive contractor segments. Competitive moves concentrate on backward integration into ester base stock production and predictive fluid management service bundling.
Among petrochemical conglomerates, Exxon Mobil Corporation and Shell plc occupy positions defined by synthetic base stock technology and European blending infrastructure respectively. FUCHS PETROLUB SE exemplifies the independent specialist archetype through OEM-approved hydraulic fluid portfolios. These three entities represent the dominant competitive vectors: petrochemical scale, regional supply integration, and equipment manufacturer certification depth.
| Leading Market Players |
|---|
| FUCHS PETROLUB SE |
| Repsol SA |
| Exxon Mobil Corporation |
| Quaker Chemical Corporation |
| The Lubrizol Corporation |
| Shell plc |
| Phillips 66 Company |
| Petro-Canada Lubricants Inc. |
| Chevron Corporation |
| Others |
Supply Flow & Price Mechanics
Rotterdam's synthetic base stock capacity utilization above 85% compresses margin flexibility for European blenders while anchoring price floors for biodegradable hydraulic fluid grades across the Nordic timber corridor. This scale concentration simultaneously elevates procurement leverage for integrated Finnish operators and squeezes independent Baltic contractors exposed to rapeseed oil commodity cycles.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by compelling polyolester compressor lubricant reformulation for climate-controlled harvester cabs. Three-tier pricing structure across premium synthetic ester, mid-grade mineral, and economy mineral levels separates OEM-approved formulations from bulk commodity grades. Cost compression in the economy tier is intensifying because independent Estonian and Latvian contractors exhibit acute price sensitivity to sunflower oil feedstock swings. Integrated forestry companies in Finland absorb premium synthetic grades with minimal volume elasticity.
Supply Chain Analysis
Just-in-time bulk tank monitoring dominates procurement relationships between Finnish saw mill operators and Rotterdam-based blenders, replacing calendar-based contracts with automated reorder triggers. Geographic supply concentration centers on Germany for extreme-pressure additive chemistries, the Netherlands for synthetic base stock production, and Finland for regional formulation blending. Raw material dependencies rest on rapeseed and sunflower oil esters, sulfur-phosphorus extreme-pressure compounds, and ashless dispersant packages. Single-source vulnerability from retiring German tribology specialists threatens formulation continuity. Distribution runs through direct tank-wagon contracts for integrated operators and wholesale distributors for fragmented Baltic contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through OEM approval timelines and biodegradability mandates creates substantial switching costs for end-users.
For Market Incumbents: Consolidate backward integration into ester base stock production to secure margin predictability against agricultural commodity volatility. Deepen certification relationships with John Deere and Ponsse to compress approval timelines below the current 18-24 month lag. Control channel access in the Tartu-Pärnu corridor before EU rural development funds accelerate Baltic mechanization.
For New Entrants and Emerging Players: Anchor in Estonia and Latvia's mechanization gap where price-sensitive independent contractors lack specification negotiation leverage. Target saw mill operations in the Baltic states below Nordic automation penetration rates. Pursue a digital fluid management service bundling strategy with IoT-enabled predictive drain-interval optimization.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEM-approved hydraulic fluid portfolios with multi-year direct supply contracts. Long-term viability favors blenders with captive ester base stock supply and established Nordic OEM relationships. Watch for inflection when EU Corporate Sustainability Reporting Directive compliance deadlines accelerate lifecycle-assessed lubricant procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Base Stocks | Captive supply of rapeseed and sunflower oil derivatives insulates margin predictability from agricultural commodity cycles. |
| OEM Certification Acceleration | Compressed approval timelines with Ponsse and John Deere preempt regulatory compliance deadlines for biodegradable formulations. |
| Digital Fluid Management Services | IoT sensor integration in harvester hydraulic systems enables subscription-based predictive maintenance revenue streams. |
| Baltic Mechanization Conversion | EU rural development fund deployment in Estonia and Latvia opens fleet modernization demand for specification-compliant lubricants. |
| Carbon Accounting Integration | Verified bio-based content claims align with EU Corporate Sustainability Reporting Directive procurement requirements. |
Methodological Framework
A standing panel of maintenance directors at integrated forestry companies, procurement leads at harvester OEMs, technical R&D directors at lubricant blenders, and aftermarket service heads provided ongoing calibration against secondary validation from customs trade data, SEC 10-K filings, EU ECHA substance restriction schedules, and Nordic timber industry association reports. Bottom-up equipment population modeling triangulated with top-down lubricant consumption intensity benchmarks.
Consistency checks validated volume and value outputs against external capacity utilization disclosures from Rotterdam blending complexes and rapeseed oil futures market indicators. Segmentation dimensions spanned product type, application, end-user procurement sophistication, and distribution channel across the projection horizon. CAGRs derived from equipment fleet expansion rates, regulatory compliance timeline acceleration, and bio-based content mandate adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal implementation and Nordic mechanization intensity; material deviation in agricultural commodity volatility or OEM approval timeline compression would warrant model refresh. Revision becomes warranted when rapeseed oil price swings exceed historical bands or when Baltic automation penetration accelerates beyond baseline rural development fund disbursement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Hydro Lubricants Market
Lubricants
Marine Grease Market
Lubricants
Global Finished Lubricant Market
Lubricants
Europe Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Global Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Polyurea Greases Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Construction Lubricants Market
Lubricants
Lube Skid Market