
 Open Gear Lubricants Market | 2026-2036
Open Gear Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Open Gear Lubricants Market Outlook
REACH is repositioning the European open gear lubricant landscape by elevating the cost of mineral-oil-based formulations and accelerating synthetic substitution timelines. FUCHS SE leverages its captive ester production network to secure supply continuity for high-load mining grades. Kluber Lubrications anchors its position through application engineering partnerships with original equipment manufacturers in heavy material handling. Shell plc differentiates via integrated base oil refining that tightens specification control across viscosity grades.
Open gear lubricants are viscous, adhesive lubricating materials formulated with high base oil viscosity, solid film additives such as graphite or molybdenum disulfide, and thickening agents to prevent squeeze-out under heavy load; they are designed to cling to exposed gear teeth in slow-moving, high-torque machinery operating under contamination stress. Grease formulations occupy the largest volume share due to their compatibility with manual and automatic lubrication systems on aging mining shovels. Oil-based open gear lubricants represent the fastest-expanding product category as synthetic polyalphaolefin and ester chemistries extend drain intervals in cement kiln girth gear drives. Mining equipment applications command the deepest margin pools because downtime costs at open-pit operations justify premium pricing for field-proven formulations.
The US EPA governs disposal pathways for open gear lubricants containing heavy metal additives, while China's MEE enforces emission-linked manufacturing standards that constrain solvent-based production processes. Germany's KBA and France's ANSM have no direct jurisdiction here, though EU-wide ECHA substance restrictions cascade into formulation decisions for suppliers serving the European mining and cement sectors. Stakeholders must monitor the trajectory of base oil reclassification under evolving chemical hazard frameworks, as this determines which product architectures remain licensable across major industrial jurisdictions.
Market Dynamics
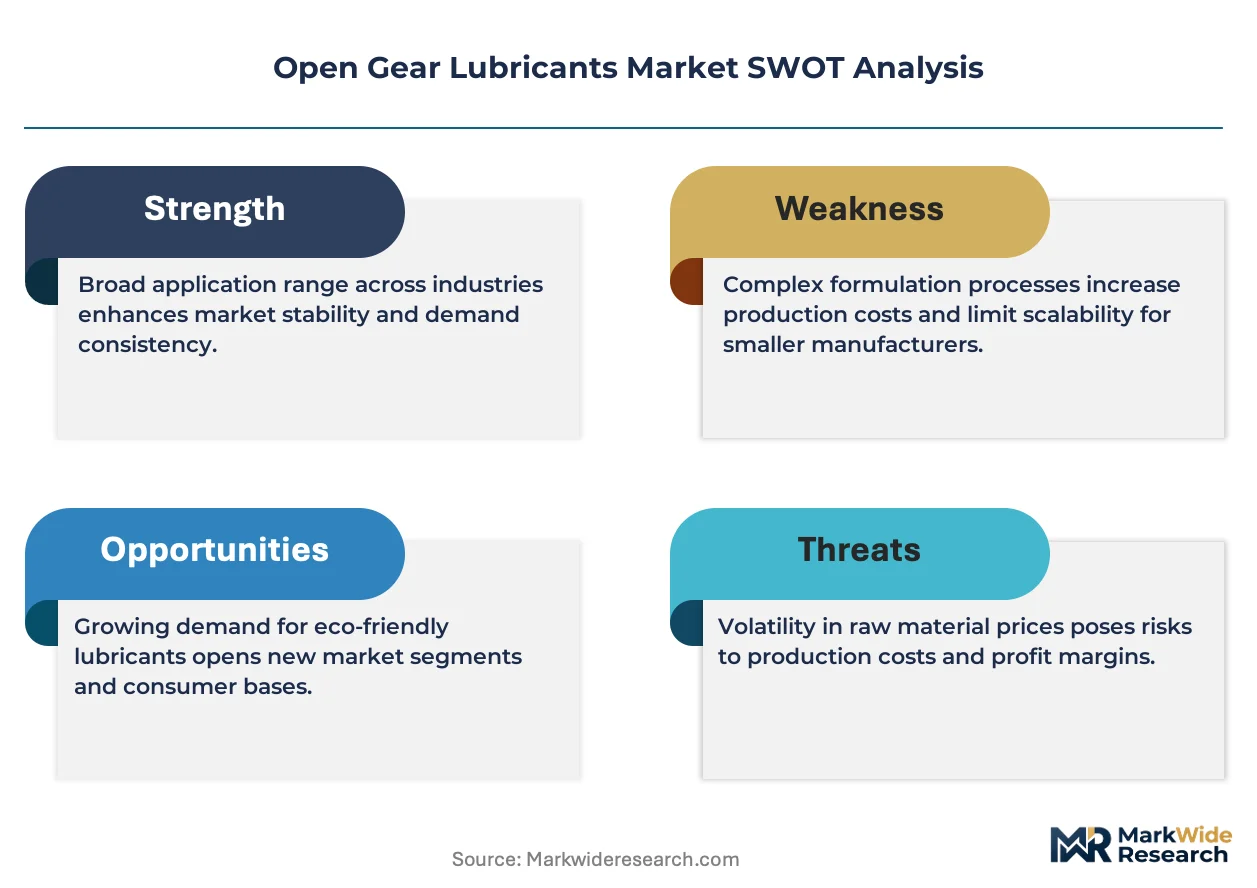
REACH reclassification of mineral base oils under ECHA hazard frameworks is forcing European formulators toward synthetic ester chemistry, compressing legacy product lifecycles while elevating input costs across the value chain.
Growth Catalysts
- Dragline fleet renewal:Australian mining operators are expanding high-viscosity lubricant consumption for shovel and dragline applications as open-pit operations deepen.
- REACH compliance deadlines:EU chemical hazard reclassifications are accelerating synthetic substitution timelines for mineral-oil-based open gear formulations.
- Kiln girth gear demand:China's northern industrial corridor hosts the world's largest installed base of open gear-driven cement kilns and steel mills.
Market Restraints
- Base oil supply concentration:Synthetic ester feedstock availability concentrates among specialty chemical producers in Germany and the Netherlands.
- Heavy metal disposal costs:US EPA regulations governing lubricants containing molybdenum disulfide or graphite additives raise end-of-life handling expenses.
- Solvent-based production constraints:China's MEE emission-linked manufacturing standards limit traditional processing methods for adhesive grease formulations.
Strategic Opportunities
- Drain interval extension:Synthetic polyalphaolefin chemistry enables service-life doubling in cement kiln applications, creating premium pricing headroom.
- Automatic lubrication retrofits:Aging mining shovels in Chile and Peru present upgrade potential for centralized grease delivery systems.
- Ester chemistry captive supply:Backward integration into bio-based feedstock refining secures formulation continuity under tightening EU substance restrictions.
Industry Challenges
- Tribology specialization shortage:Field application engineering expertise for high-load open gear systems remains concentrated among retiring specialists in heavy material handling.
- Specification alignment friction:OEM partnership requirements for girth gear warranty coverage demand multi-year certification timelines that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Gear Lubricants Market |
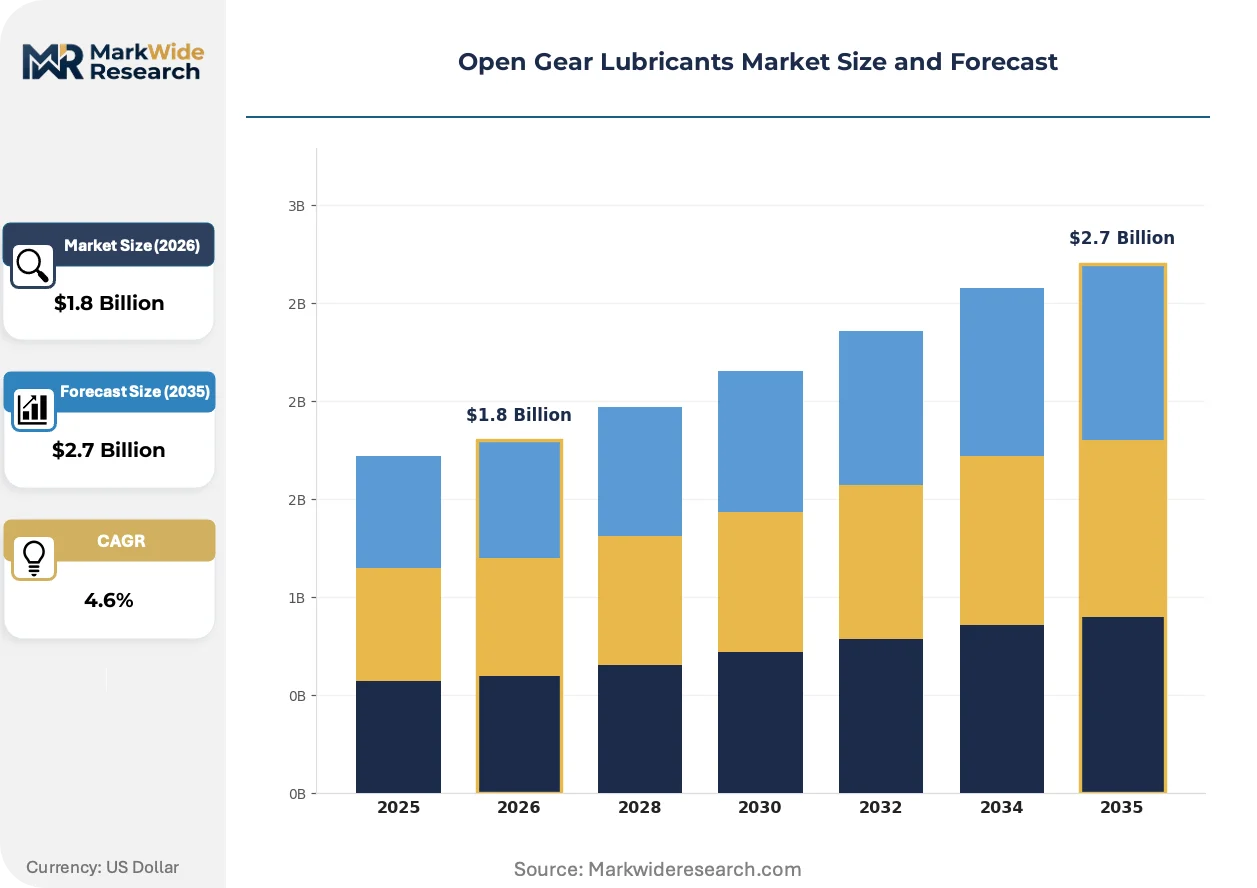
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grease, Oil, Semi-fluid Lubricants, Solid Lubricants Application: Mining Equipment, Marine Applications, Construction Machinery, Industrial Gearboxes End User: Manufacturing, Energy, Transportation, Agriculture Distribution Channel: Direct Sales, Retail, Online Platforms, Distributors |
| Companies Covered | FUCHS SE, Kluber Lubrications, Carl Bechem GmbH, CWS Industrials, Shell plc, Exxon Mobil Corporation, Chevron Corporation, TotalEnergies SE, Specialty Lubricants Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Gear Lubricants Market Strategic Shifts
Synthetic chemistry advances and regulatory hazard reclassifications are compressing traditional formulation architectures while opening premium positioning for bio-based alternatives. Three developments are restructuring competitive advantage.
Synthetic ester base stocks are overtaking mineral oils in European mining and cement applications as REACH-driven hazard reclassifications elevate compliance costs for legacy formulations. Cement producers in Germany and Poland are adopting these chemistries fastest to secure uninterrupted supply licensure. The shift is compressing margins on conventional products while rewarding early synthetic capacity investments.
EU ECHA substance restrictions under evolving REACH annexes are cascading into mandatory reformulation timelines for suppliers serving European mining sectors. Industrial consequence includes accelerated R&D redirection toward bio-derivable thickener systems and solid film additive alternatives. High-viscosity mining grades face the steepest transition curves given their reliance on historically exempt base oil classifications.
Buyer consolidation among multinational cement and mining operators is compressing supplier qualification cycles and unbundling after-sales technical service from product supply. Integrated procurement teams in China's northern industrial corridor now demand predictive maintenance data packages alongside lubricant delivery. This pattern is most visible in steel mill girth gear contracts where specification control has shifted from plant engineers to centralized technical purchasing functions.
Open Gear Lubricants Market Segmentation
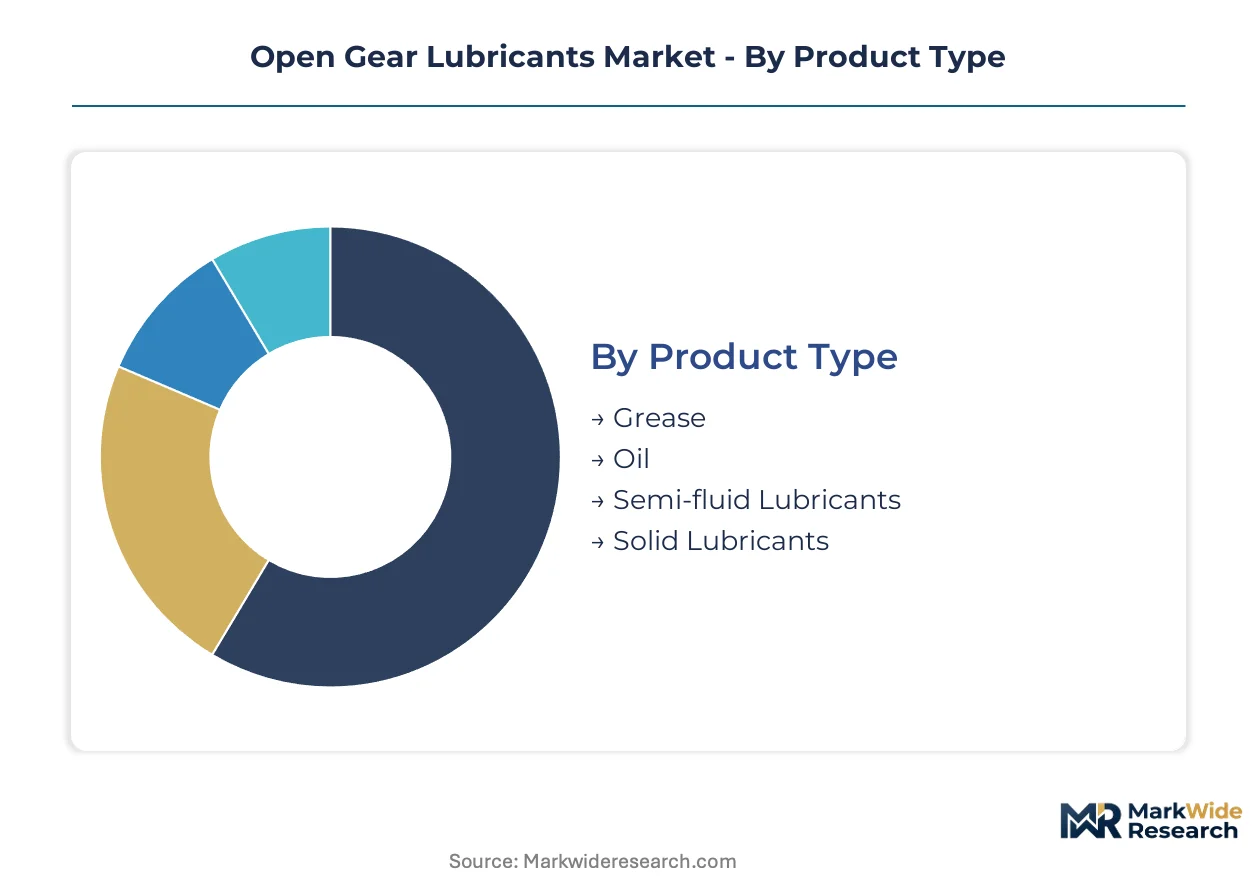
Open gear lubricant selection hinges on load severity, contamination exposure, and lubrication system architecture. Buyers across mining, cement, and marine sectors weight formulation viscosity, solid film additive content, and synthetic base stock compatibility against operational uptime economics.
Product Type:
Cost tier differentiation separates maintenance-intensive operations from capital-intensive automated systems.
- Grease:Thickened formulations incorporating graphite or molybdenum disulfide cling to slow-moving gear teeth under heavy contamination. Australia's open-pit mining operators consume high-viscosity greases for dragline and shovel maintenance, driven by equipment age and manual lubrication system prevalence.
- Oil:Fluid formulations based on polyalphaolefin or synthetic ester chemistry enable circulation through centralized spray systems. Cement producers in China's northern industrial corridor specify these for kiln girth gear drives, prioritizing drain interval extension under continuous operation schedules.
- Semi-fluid Lubricants:Intermediate viscosity grades bridge pumpability and adhesion requirements for aging gearboxes with mixed lubrication infrastructure.
- Solid Lubricants:Dry film coatings and bonded solids serve extreme-temperature or vacuum environments where liquid carriers degrade.
Volume sits with Grease; growth tilts toward Oil.
Application:
Margin concentration follows downtime cost severity across end-use sectors.
- Mining Equipment:Draglines, shovels, and grinding mills operate under abrasive dust loading and shock loads. Chilean copper operations specify premium formulations validated through OEM partnership protocols, accepting price premiums against unplanned outage costs.
- Marine Applications:Open gears on deck machinery and winches face saltwater corrosion and temperature cycling. Synthetic ester formulations with enhanced hydrolytic stability gain specification in European-flagged vessels under MARPOL discharge scrutiny.
- Construction Machinery:Cranes and excavator swing gears demand adhesive lubricants resisting washout from precipitation and site debris.
- Industrial Gearboxes:Steel mill pinion stands and cement kiln drives require high-load film strength with predictive maintenance compatibility.
Mining Equipment commands the deepest margin pools; Marine Applications show the steepest synthetic substitution trajectory.
End User:
Procurement centralization intensity varies by sector consolidation patterns.
- Manufacturing:Steel and cement producers with integrated procurement functions specify lubricants alongside predictive maintenance data packages.
- Energy:Power generation and renewables infrastructure operators prioritize biodegradability for hydroelectric and offshore wind applications.
- Transportation:Rail and port material handling systems specify open gear lubricants for stacker-reclaimers and ship loaders.
- Agriculture:Grain elevators and processing equipment represent fragmented demand with price-sensitive specification behavior.
Manufacturing concentrates volume; Energy segments expand fastest on sustainability-linked procurement criteria.
Distribution Channel:
Technical service bundling determines channel selection for complex applications.
- Direct Sales:Multinational mining and cement operators negotiate formulation customization and field engineering support through direct manufacturer relationships.
- Distributors:Regional industrial supply networks serve mid-tier manufacturing and construction accounts with inventory proximity advantages.
- Retail:Aftermarket channels address emergency maintenance needs for mobile construction and agricultural equipment.
- Online Platforms:E-procurement portals gain traction for standardized grades among buyers with established specification libraries.
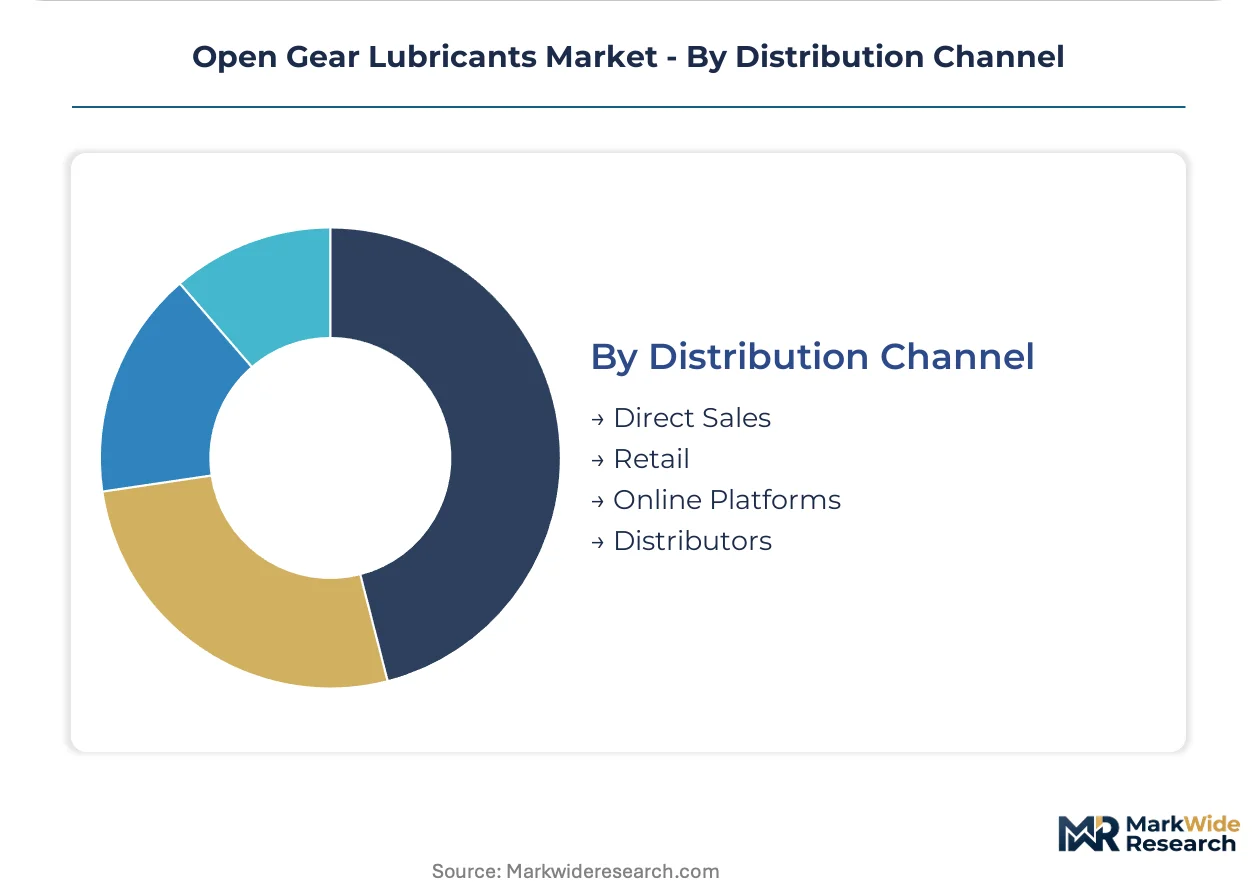
Direct Sales anchor high-value mining contracts; Distributors retain construction and agricultural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's northern industrial corridor concentrates the world's largest installed base of open gear-driven cement kilns and steel mills, while Australian and Chilean mining operations drive premium-grade consumption. Regulatory divergence across major jurisdictions is fragmenting formulation standards and reshaping supplier qualification requirements.
China
Steel and cement producers in Hebei and Shanxi provinces operate massive open gear installations requiring continuous lubrication under heavy contamination loads. The Ministry of Ecology and Environment enforces emission-linked manufacturing standards that constrain solvent-based grease production processes. Tangshan and Handan industrial clusters are retrofitting kiln girth gear drives with synthetic oil circulation systems to extend drain intervals.
Australia
Open-pit mining operators in Queensland and Western Australia consume high-viscosity greases for aging dragline and shovel fleets facing deeper excavation profiles. The Therapeutic Goods Administration has no direct jurisdiction, though national chemical standards align with OECD hazard classification frameworks. Bowen Basin coal operations and Pilbara iron ore districts represent concentrated demand nodes for field-proven mining formulations.
Germany
Cement producers in North Rhine-Westphalia and Bavaria are accelerating synthetic ester adoption ahead of REACH compliance deadlines for mineral base oil reclassification. The Federal Motor Transport Authority coordinates with EU-wide ECHA substance restrictions cascading into mining sector formulation requirements. Ruhr industrial corridor lubricant blenders are restructuring supply chains around captive bio-based feedstock refining.
Chile
Copper mining operations in Antofagasta and Atacama regions specify premium open gear lubricants validated through OEM partnership protocols against unplanned outage costs. The national mining regulator enforces environmental discharge standards affecting lubricant selection for girth gear and grinding mill applications. Calama and Antofagasta mining districts concentrate demand for high-load formulations with predictive maintenance compatibility.
United States
Cement manufacturers in Texas and California operate large rotary kiln installations requiring synthetic oil formulations for continuous duty cycles. The Environmental Protection Agency governs disposal pathways for lubricants containing molybdenum disulfide or graphite additives, elevating end-of-life handling costs. Mid-Atlantic and Great Lakes industrial corridors face compressed product lifecycles as hazard reclassifications tighten.
Open Gear Lubricants Market Competitive Environment
German producers anchor one tier; Anglo-Dutch and American energy majors hold scale positions; specialty formulators occupy technical niches. The market structures around three concentration nodes: integrated petrochemical conglomerates with captive base oil refining, independent lubricant specialists with application engineering depth, and regional blenders serving mining-sector procurement clusters. Competitive moves center on backward integration into synthetic ester feedstocks and multi-year OEM certification partnerships for girth gear warranty coverage.
Within the specialty formulation tier, FUCHS SE and Kluber Lubrications exemplify archetypes of application-engineered supply. FUCHS SE leverages captive production networks to secure formulation continuity under tightening EU substance restrictions. Kluber Lubrications anchors its position through technical service bundling with original equipment manufacturers in heavy material handling. Shell plc represents the integrated major tier, differentiating through specification control across viscosity grades via in-house base oil refining.
| Leading Market Players |
|---|
| FUCHS SE |
| Kluber Lubrications |
| Carl Bechem GmbH |
| CWS Industrials |
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| TotalEnergies SE |
| Specialty Lubricants Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialist tribology engineers concentrated in Germany's Ruhr industrial corridor command wage premiums that compress margins on standard-grade formulations while widening spreads between economy and premium tiers. Labor-cost differentials between captive ester production facilities and outsourced blending operations feed directly into pricing stratification across synthetic and mineral-oil-based product lines.
Pricing Analysis
Volume concentrates in thickened grease formulations serving manual lubrication systems on aging mining equipment; margins concentrate in synthetic oil grades for automated kiln girth gear drives. Three-tier pricing structure separates field-validated premium grades with OEM certification from standard mining formulations and economy-tier construction lubricants. Pricing pressure stems from REACH-driven base oil reclassification elevating input costs for legacy mineral formulations. Mining operators show lowest price sensitivity given outage cost severity; agricultural grain elevator buyers exhibit highest sensitivity with specification behavior driven by maintenance budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from multinational cement and mining operators requiring formulation customization and field engineering bundling. Synthetic ester feedstock production concentrates in Germany and the Netherlands among specialty chemical producers. Base oil supply draws from integrated refiners in the United States and Middle East, with solid film additives sourcing from graphite processors in China and molybdenum disulfide suppliers in Chile. Single-source vulnerability in high-viscosity synthetic base stocks presents structural risk given limited qualified producers. Distribution runs through regional industrial supply networks for mid-tier manufacturing accounts with inventory proximity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The open gear lubricants sector sits in a formulation-transition phase as synthetic ester chemistry displaces mineral-oil-based architectures under tightening EU hazard reclassifications.
For Market Incumbents: To counter synthetic feedstock supply concentration risk, secure backward integration into bio-based ester refining or long-term offtake agreements with German and Dutch specialty chemical producers. Prioritize multi-year OEM certification partnerships for girth gear warranty coverage to lock out reformulation-stage competitors. For New Entrants and Emerging Players: Capture automatic lubrication retrofit demand among aging dragline fleets in Chile and Peru where centralized grease delivery system upgrades outpace incumbent service capacity. Target marine applications under MARPOL discharge scrutiny with hydrolytically stable synthetic ester formulations as the most penetrable segment lacking established supplier relationships. For Investors and Strategic Acquirers: The window for entry favors specialty formulators with captive ester production and application engineering depth over commodity blenders exposed to input cost volatility. Acquisition targets should demonstrate established OEM partnership protocols and field validation in high-load mining grades. Monitor REACH annex expansion timelines as the critical inflection signal for mineral-oil-based product obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ester Feedstocks | Secures formulation continuity under ECHA substance restrictions cascading into mining sector requirements. |
| OEM Certification Partnership | Multi-year warranty coverage protocols with heavy material handling equipment manufacturers delay competitive entry. |
| Automatic Lubrication Retrofit Service | Centralized grease delivery upgrades on aging shovels in Chilean copper districts create recurring revenue streams. |
| Predictive Maintenance Data Packaging | Integrated procurement teams in China's northern industrial corridor now demand lubricant-plus-analytics bundles. |
| Bio-Based Thickener R&D Investment | EU ECHA restrictions on conventional additives accelerate demand for derivable solid film alternatives. |
Study Parameters
Independent corroboration across maintenance directors at Australian open-pit operations, procurement leads at Chinese cement producers, and technical R&D directors at German lubricant blenders underwrites the qualitative findings. Primary interviews with OEM partnership managers, aftermarket service heads at mining equipment distributors, and plant engineers at steel mills combined with secondary validation from customs trade data, SEC filings of integrated energy majors, and ECHA substance restriction announcements. Bottom-up volume modeling across product type and application segments triangulated with top-down market sizing from regional production cluster analysis.
Comparable-period anchoring to historical base oil price cycles and synthetic substitution trajectories structured the forecast framework across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, end-use equipment category, lubrication system architecture, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating dragline fleet renewal schedules and kiln girth gear retrofit timelines. Industry-specific inputs encompass REACH compliance deadline phasing and MEE emission standard enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to base oil reclassification scope under evolving ECHA hazard frameworks and synthetic ester feedstock capacity expansion delays. Periodic stress-testing of base assumptions against regulatory announcement timelines and OEM certification protocol changes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Automotive Engine Oils Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Hydro Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Thailand Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Power Steering Fluids Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Canada Commercial Vehicles Lubricants Market