
 Phenylacetonitrile Market | 2026-2036
Phenylacetonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Phenylacetonitrile Market Analysis
Capital-intensity divergence between large-scale chemical producers and boutique research suppliers is rotating competitive dynamics across the phenylacetonitrile landscape. Tokyo Chemical Industry Co., Ltd. leverages its integrated Japanese manufacturing base to sustain consistent bulk output for pharmaceutical clients. Alfa Aesar competes through specialized high-purity grades targeting research institutions. MolPort anchors its position with digital distribution infrastructure that extends reach to fragmented chemical buyers globally.
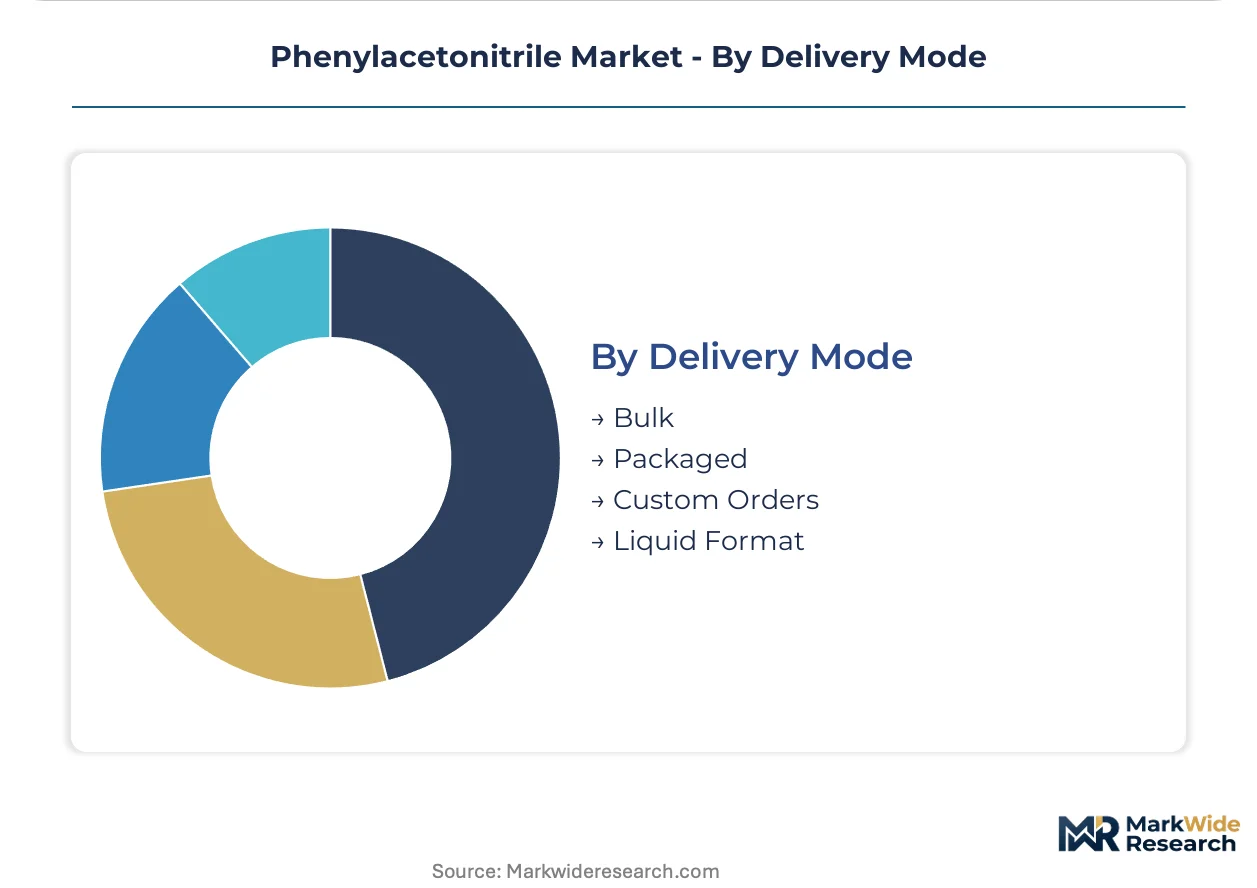
Phenylacetonitrile, also known as benzyl cyanide, is an organic nitrile compound with the formula C6H5CH2CN, typically manufactured through cyanation of benzyl chloride or ammoxidation of toluene derivatives, serving primarily as a versatile intermediate for pharmaceutical active ingredients and agrochemical synthesis. The intermediates segment dominates volume flows due to its position as the foundational chemical building block for downstream specialty applications. API production within the application dimension commands premium pricing structures as pharmaceutical manufacturers enforce stringent pharmacopeial compliance. Bulk delivery mode leads transaction volume while custom orders capture margin concentration from research institutions requiring tailored purity specifications.
EPA oversight in the United States governs phenylacetonitrile handling under toxic substances provisions, while REACH registration requirements in Europe mandate comprehensive safety dossiers for importers. China's MEE enforces emission controls on nitrile production facilities under national environmental standards. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions to anticipate supply chain reconfiguration requirements.
Market Dynamics
Pharmaceutical API manufacturers are consolidating their supplier bases to secure benzyl cyanide feedstock amid tightening pharmacopeial purity mandates across multiple jurisdictions. This concentration pressure is restructuring procurement relationships and elevating specification requirements for intermediate producers.
Growth Catalysts
- REACH registration dossiers:European importers must submit comprehensive safety documentation to ECHA, creating competitive moats for compliant suppliers with established regulatory infrastructure.
- Agrochemical synthesis pipelines:Herbicide and fungicide manufacturers are expanding nitrile intermediate consumption for next-generation crop protection molecules.
- China:Domestic chemical producers are scaling benzyl cyanide derivative capacity to serve regional pharmaceutical manufacturing clusters.
Market Restraints
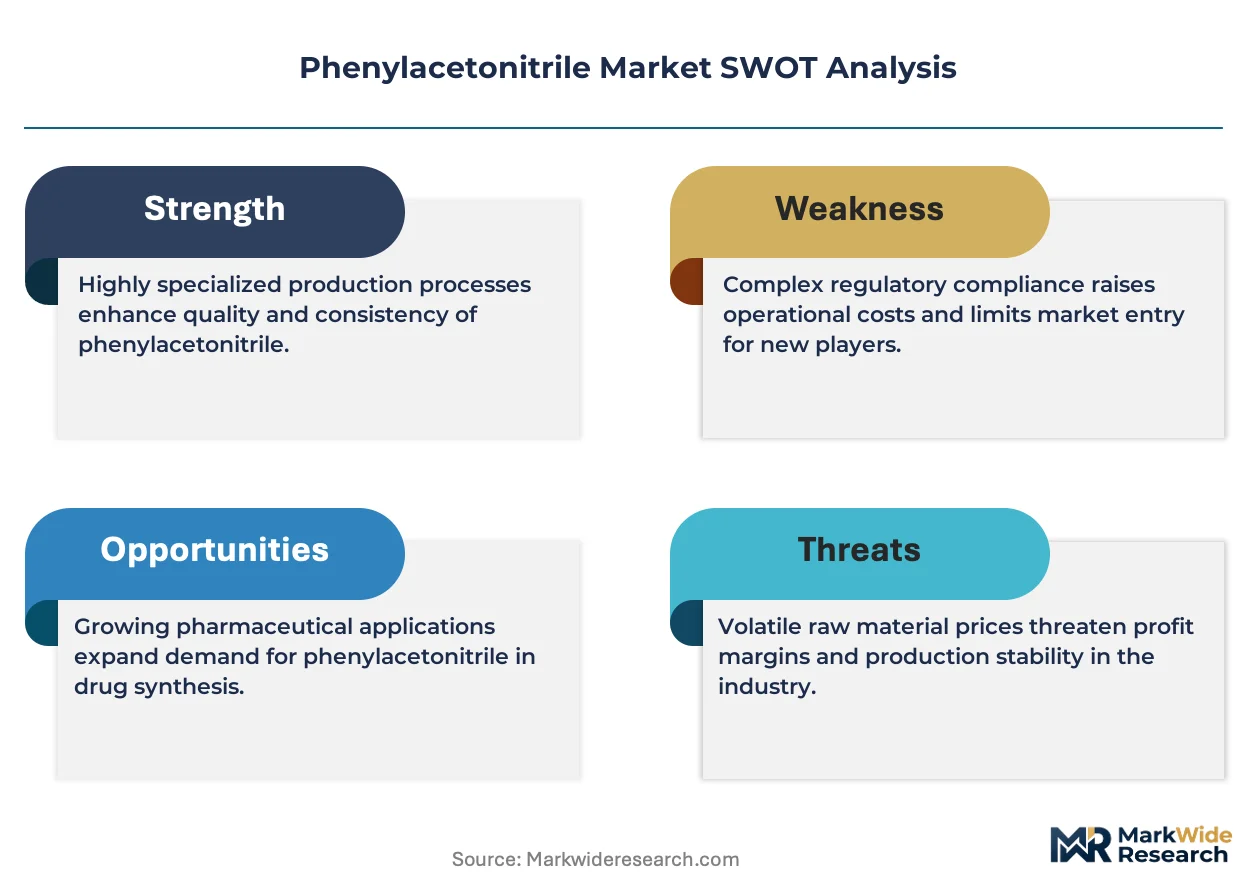
- Benzyl chloride feedstock volatility:Price swings in chlorinated toluene derivatives compress margin predictability for cyanation-based producers.
- Environmental compliance costs:China's MEE emission controls on nitrile facilities require continuous monitoring infrastructure and wastewater treatment upgrades.
- Substitution by phenylacetic acid routes:Some API manufacturers are exploring alternative synthetic pathways that bypass nitrile intermediates entirely.
Strategic Opportunities
- India:CDSCO's streamlined API manufacturing incentives are attracting contract research and manufacturing organizations seeking phenylacetonitrile supply partnerships.
- Continuous flow chemistry:Microreactor technology convergence with nitrile synthesis is enabling smaller-footprint production with enhanced safety profiles.
- Digital chemical marketplaces:Fragmented research buyers are migrating to platform-based procurement for gram-to-kilogram quantities with instant purity certification.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance documentation for pharmaceutical-grade material requires 18-24 month validation cycles that delay revenue recognition.
- Specialized chemical engineering talent:Nitrile process safety expertise is concentrated among aging workforces in traditional chemical manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenylacetonitrile Market |
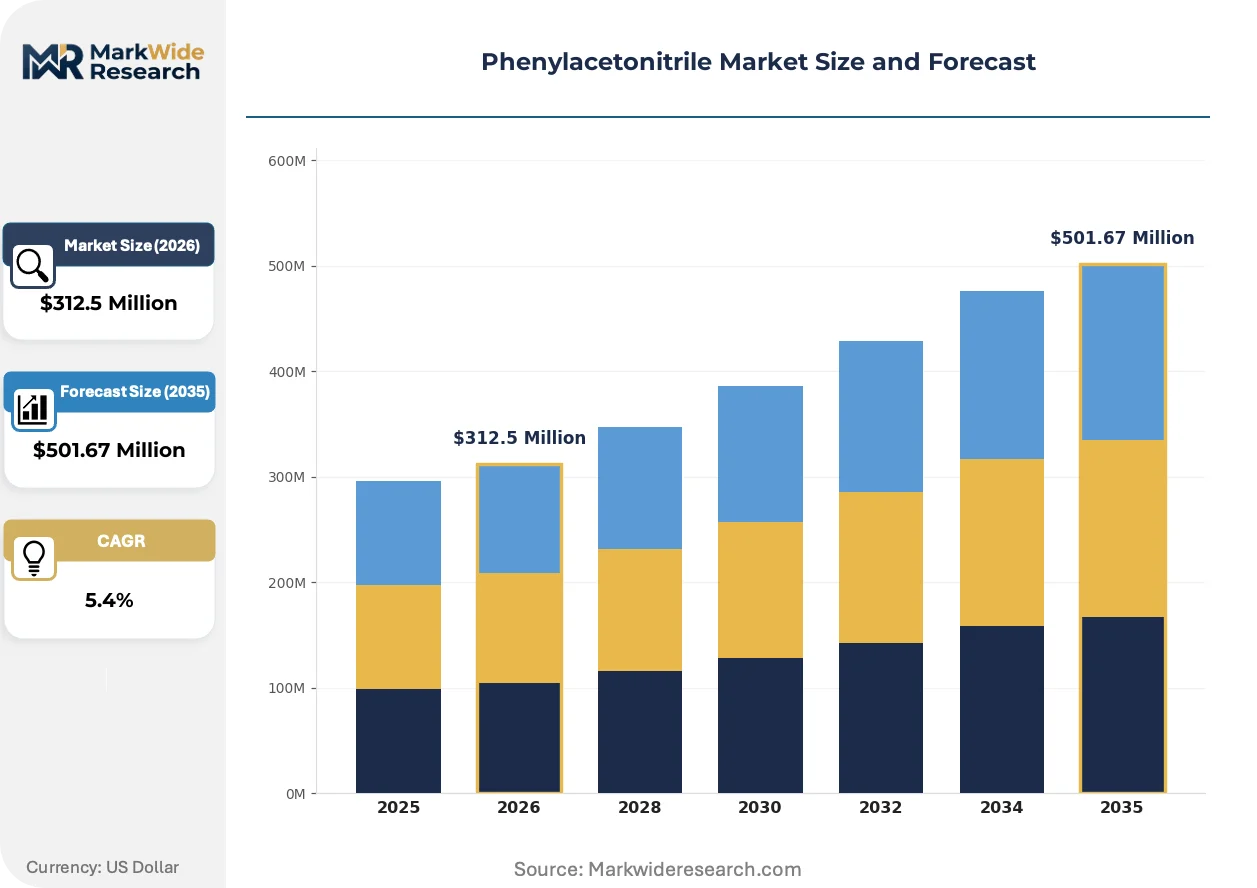
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Agrochemicals, Intermediates, Specialty Chemicals End User: Pharmaceutical Manufacturers, Agrochemical Companies, Research Institutions, Chemical Producers Application: Synthesis, API Production, Chemical Research, Industrial Applications Delivery Mode: Bulk, Packaged, Custom Orders, Liquid Format |
| Companies Covered | Tokyo Chemical Industry Co., Ltd., LGC Limited, Alfa Aesar, The Good Scents Company, MolPort, SynZeal, CHEM SERVICE, INC., Santa Cruz Biotechnology, Inc., Enamine Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenylacetonitrile Market Emerging Trajectories
Process intensification and regulatory digitization are compressing production timelines while elevating traceability requirements across the phenylacetonitrile value chain. These forces are reshaping how manufacturers compete on speed, documentation, and specification flexibility.
Continuous flow reactor technology for benzyl cyanide synthesis is miniaturizing production footprints while enhancing thermal safety control. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting these systems for captive intermediate supply. The technology is compressing batch cycle times from days to hours and enabling on-demand production that reduces working capital requirements for multi-step API synthesis.
ECHA's SCIP database requirements for Substances of Very High Concern are forcing downstream formulators to document phenylacetonitrile presence in articles placed on the EU market. Importers are now demanding extended safety data sheets with exposure scenario attachments. Pharmaceutical excipient suppliers are responding by segregating EU-bound inventory streams with enhanced chain-of-custody documentation.
Research institutions are consolidating chemical procurement through preferred supplier agreements that bundle phenylacetonitrile with complementary nitrile intermediates. This concentration is displacing spot-market purchasing for high-purity grades. University procurement offices in Germany and the Netherlands are most aggressively pursuing these framework contracts to simplify compliance auditing and reduce vendor management overhead.
Phenylacetonitrile Market Segmentation
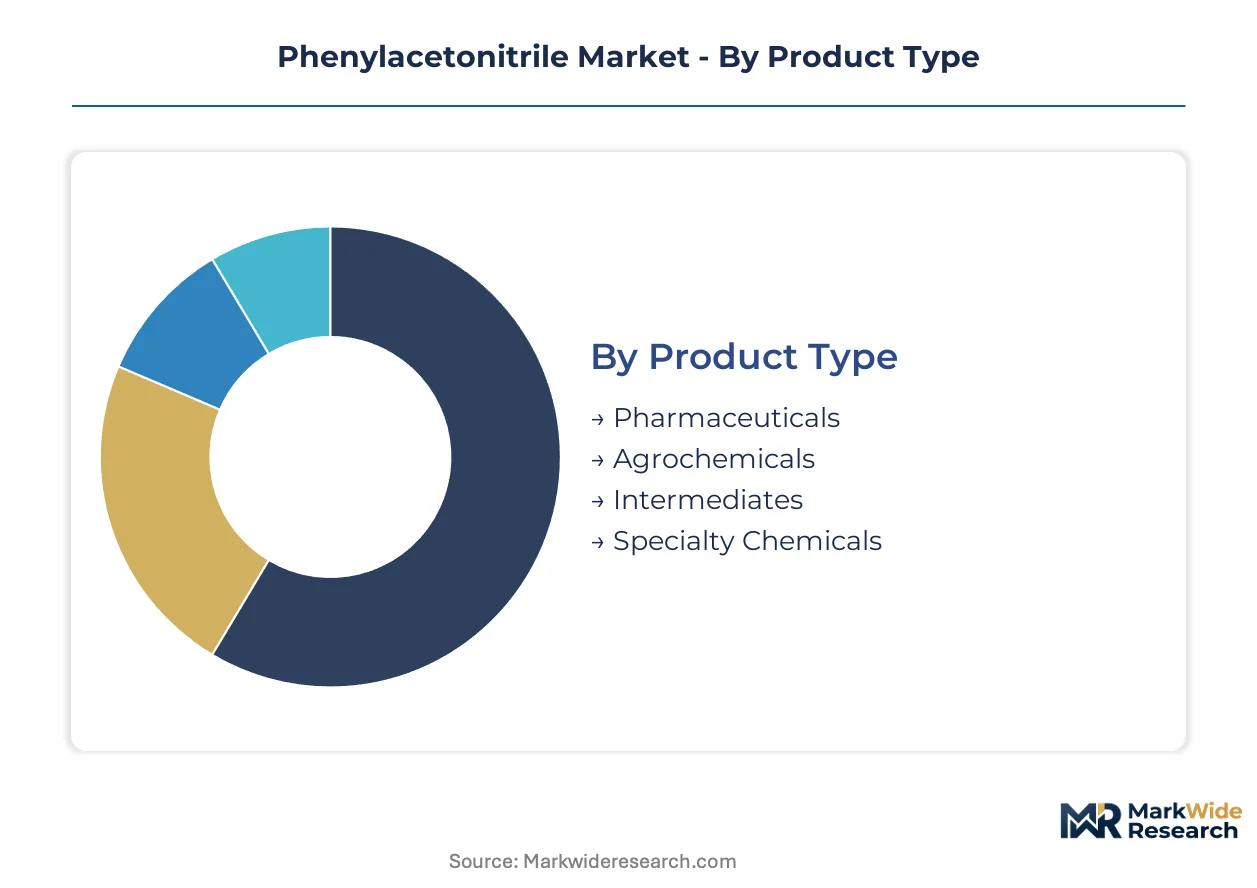
Phenylacetonitrile's value chain splits across fundamentally different procurement logics. Pharmaceutical buyers enforce pharmacopeial certification tiers that agrochemical clients rarely require, while research institutions fragment demand into gram-scale precision orders.
Product Type:
Channel mix varies sharply: intermediates flow through bulk chemical distributors, while pharmaceutical and specialty grades route through authorized dealer networks with audit trails.
- Intermediates:Technical-grade benzyl cyanide serves as the foundational building block for downstream nitrile derivatives. Demand concentrates in Chinese chemical manufacturing clusters where domestic producers scale benzyl cyanide derivative capacity for regional pharmaceutical supply chains.
- Pharmaceuticals:USP and EP-compliant material meets stringent pharmacopeial specifications for API synthesis workflows. European and North American pharmaceutical manufacturers drive specification escalation as they consolidate supplier bases under tightening purity mandates.
- Agrochemicals:Herbicide and fungicide manufacturers consume technical grades for crop protection molecule synthesis.
- Specialty Chemicals:High-purity variants target niche applications requiring custom specifications.
Intermediates dominates installed base. Pharmaceuticals is where expansion concentrates.
End User:
Cost tier stratification separates the market: multinational pharmaceutical manufacturers pay certification premiums while chemical producers optimize for unit economics.
- Pharmaceutical Manufacturers:Drive the most stringent specification requirements across the value chain. Procurement concentrates among CDSCO-registered facilities in India and FDA-inspected sites in the United States as these manufacturers secure benzyl cyanide feedstock amid pharmacopeial purity escalation.
- Chemical Producers:Scale-oriented buyers purchasing technical grades for derivative manufacturing.
- Agrochemical Companies:Volume purchasers of standard-grade material for synthesis pipelines.
- Research Institutions:Fragmented buyers of high-purity grades through digital marketplaces.
Pharmaceutical Manufacturers anchor revenue per ton. Chemical Producers is where volume expansion concentrates.
Application:
Margin structure inverts across applications: API production commands premium pricing while industrial applications compete on cost.
- API Production:Pharmaceutical-grade phenylacetonitrile undergoes multi-step synthesis into active pharmaceutical ingredients. Demand concentrates in Swiss and Singaporean contract manufacturing facilities adopting continuous flow reactor technology for captive intermediate supply with enhanced thermal safety control.
- Synthesis:General chemical transformation applications across multiple industries.
- Chemical Research:Academic and institutional R&D consumption of reference standards.
- Industrial Applications:Non-pharmaceutical manufacturing processes requiring nitrile intermediates.
API Production dominates value capture. Synthesis is where volume expansion concentrates.
Delivery Mode:
Supply concentration shapes fulfillment: bulk tanker deliveries serve integrated manufacturers while custom orders fragment to specialty distributors.
- Bulk:Tanker and drum deliveries to large-scale chemical and pharmaceutical facilities. Procurement concentrates among integrated producers in China and India where domestic manufacturing clusters minimize logistics costs for high-volume benzyl cyanide derivative production.
- Custom Orders:Tailored purity specifications and packaging for research clients.
- Packaged:Standard container formats for mid-volume chemical producers.
- Liquid Format:Specialized handling for continuous process integration.
Bulk dominates transaction volume. Custom Orders is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in Switzerland and Singapore absorb price premiums without volume elasticity, while agrochemical purchasers in India and Brazil negotiate aggressively on technical-grade shipments. Chinese chemical producers face margin compression from domestic environmental enforcement despite holding the largest installed derivative capacity.
China
Domestic pharmaceutical manufacturing clusters in Jiangsu and Zhejiang provinces drive benzyl cyanide derivative consumption for regional API supply chains. MEE emission controls on nitrile facilities require continuous monitoring infrastructure and wastewater treatment upgrades that elevate production costs. The Yangtze River Delta chemical manufacturing belt concentrates technical-grade capacity expansion as producers scale benzyl cyanide derivative output for captive pharmaceutical use.
United States
FDA-inspected pharmaceutical contract manufacturers consolidate supplier bases to secure pharmacopeial-grade feedstock amid tightening purity mandates. EPA toxic substances provisions govern phenylacetonitrile handling and transport documentation requirements. The New Jersey and Pennsylvania chemical corridor hosts specialty distributors serving research institutions with high-purity grades through authorized dealer networks.
India
CDSCO-registered API manufacturing facilities in Maharashtra and Gujarat attract contract research organizations seeking phenylacetonitrile supply partnerships under streamlined regulatory incentives. The national pharmaceutical regulator enforces progressive manufacturing practice standards that elevate import specification requirements. Hyderabad and Ahmedabad pharmaceutical clusters scale benzyl cyanide derivative consumption for export-oriented generic API production.
Germany
REACH registration dossiers submitted to ECHA create competitive moats for compliant suppliers serving European pharmaceutical manufacturers. The EU chemicals agency mandates comprehensive safety documentation with exposure scenario attachments for downstream formulators. The Frankfurt-Rhine-Main chemical distribution hub concentrates import logistics for pharmaceutical-grade material destined for Swiss and Dutch manufacturing sites.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing elevates pharmacopeial certification requirements for API synthesis intermediates. The national regulator enforces stringent quality system standards that propagate upstream to benzyl cyanide suppliers. Basel-area contract manufacturing organizations adopt continuous flow reactor technology for captive intermediate supply with enhanced thermal safety profiles.
Phenylacetonitrile Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across purity grades and delivery modes. Bulk chemical producers with cyanation or ammoxidation capabilities compete on unit economics and feedstock security, while research-grade suppliers differentiate through digital distribution infrastructure and instant certification. Strategic archetypes include scale-driven intermediate manufacturers, pharmacopeial-grade specialists with regulatory dossier depth, and platform-based distributors serving fragmented gram-scale buyers. Competitive moves concentrate on backward integration into benzyl chloride feedstock and geographic expansion toward Indian pharmaceutical manufacturing clusters.
Among Japanese chemical suppliers, Tokyo Chemical Industry Co., Ltd. exemplifies the integrated manufacturing archetype with consistent bulk output capabilities. Alfa Aesar and MolPort occupy distinct positions within the research-grade tier, representing alternative competitive vectors based on specialized purity grades versus digital marketplace infrastructure. These three companies illustrate how geographic origin and organizational structure map onto divergent strategic positioning across the phenylacetonitrile value chain.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd. |
| LGC Limited |
| Alfa Aesar |
| The Good Scents Company |
| MolPort |
| SynZeal |
| CHEM SERVICE, INC. |
| Santa Cruz Biotechnology, Inc. |
| Enamine Ltd. |
| Others |
Supply Flow & Price Mechanics
Scale economies in Chinese benzyl cyanide derivative manufacturing anchor global price floors as domestic producers absorb MEE-mandated environmental compliance costs. Pharmaceutical buyers in Switzerland and Singapore absorb pharmacopeial certification premiums without volume elasticity, while agrochemical purchasers in India and Brazil negotiate aggressively on technical-grade shipments.
Pricing Analysis
After-sales service bundling with pharmacopeial certification documentation drives lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across USP/EP-certified premium, technical-grade standard, and research-economy levels stratifies the market. Cost compression in technical grades intensifies because Chinese producers face MEE emission control investments. Pharmaceutical manufacturers show least price sensitivity due to pharmacopeial compliance requirements, while agrochemical companies exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Shanghai ports constrain margin recovery for European and Asian pharmaceutical formulators. Supply concentrates in China, India, and Germany as dominant production and distribution hubs. Benzyl chloride feedstock and cyanation reagent sourcing rests on chlorinated toluene derivative markets. Single-source vulnerability from Jiangsu and Zhejiang province concentration elevates disruption risk. Distribution runs through authorized dealer networks for pharmaceutical grades and bulk chemical distributors for technical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical manufacturers as they narrow supplier bases under tightening pharmacopeial mandates. This concentration elevates specification requirements and compresses viable vendor pools for intermediate producers.
For Market Incumbents: Consolidate backward integration into benzyl chloride feedstock to secure margin control against chlorinated toluene price volatility. Deepen pharmacopeial dossier investment for REACH and USP compliance to defend against substitute phenylacetic acid synthetic pathways. Lock long-term offtake agreements with Swiss and Singaporean contract manufacturers adopting continuous flow reactor technology.
For New Entrants and Emerging Players: CDSCO fast-track registration for Indian API manufacturing partnerships offers the most penetrable entry vector. Target Maharashtra and Gujarat pharmaceutical clusters with technical-grade supply positioned for generic API export production. Deploy digital marketplace infrastructure to capture fragmented research-institution procurement migrating from spot-market purchasing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmacopeial-grade specialists with established ECHA dossiers and multi-year pharmaceutical supply agreements. Five-to-ten year viability favors integrated producers with captive benzyl cyanide derivative capacity serving regional pharmaceutical clusters. Monitor continuous flow chemistry adoption rates as inflection signal for production cost structure disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzyl Chloride | Secures feedstock margin control against chlorinated toluene derivative volatility. |
| Pharmacopeial Certification Investment | REACH and USP dossiers create competitive moats for European pharmaceutical supply. |
| Continuous Flow Reactor Adoption | Swiss and Singaporean contract manufacturers compress batch cycle times from days to hours. |
| Digital Marketplace Infrastructure | MolPort-style platforms capture fragmented gram-to-kilogram research procurement migration. |
| Indian Pharmaceutical Cluster Expansion | CDSCO-registered facilities in Hyderabad and Ahmedabad scale benzyl cyanide derivative consumption. |
Methodological Framework
A standing panel of pharmaceutical procurement directors, nitrile plant managers, regulatory affairs leads, and chemical distribution channel partners provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA registration databases, CDSCO manufacturing facility records, customs trade flow data, and SEC filings of listed chemical producers. Bottom-up volume triangulation against top-down value estimates anchored forecast consistency.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, delivery mode, and regional production hub dimensions. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Continuous flow technology diffusion rates and MEE enforcement intensity served as industry-specific forecast inputs.
Underlying assumptions cover pharmacopeial certification timeline stability, benzyl chloride feedstock availability, and REACH regulatory continuity, with deviation risk concentrated in environmental enforcement escalation and synthetic pathway substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
1, 1-Difluoroethane Market
Solvents
Nitroglycerin Market
Solvents
N-Pentyl Chloride Market
Solvents
Isoamylene Market
Solvents
Hydrocarbon Solvents Market
Solvents
Global Glycol Market
Solvents
Global Solvent Dyes Market
Solvents
Trifluoroethanol Market
Solvents
Benzyl Alcohol Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
United States Acetonitrile Market
Solvents
Ethane Market
Solvents
1,2-Ethanedithiol Market
Solvents
Ortho-Xylene Market
Solvents
Dibutyl Ether Market
Solvents
Coating Solvents Market