
 Global Cyclosporine Market | 2026-2036
Global Cyclosporine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyclosporine Market Foresight
Hospital pharmacy procurement is reshaping cyclosporine access patterns as integrated delivery networks consolidate purchasing decisions across transplant centers and specialty clinics. Novartis leverages its established neoral franchise to sustain brand loyalty among transplant specialists despite generic erosion. Sun Pharmaceutical Industries anchors its position through aggressive generic pricing and deep formulary penetration across US hospital systems.
Cyclosporine is a cyclic undecapeptide immunosuppressant derived from Tolypocladium inflatum, typically formulated as soft gelatin capsules containing 25 mg or 100 mg of the active drug, and it functions by inhibiting calcineurin to block interleukin-2 production in T-lymphocytes. Oral capsules dominate volume as the standard maintenance therapy for renal and hepatic transplant recipients, while ophthalmic emulsion represents the fastest-expanding margin pool driven by dry eye disease prescriptions. Injectable solution occupies a narrower but critical niche in perioperative transplant protocols where immediate immunosuppression is essential.
The FDA enforces bioequivalence protocols under 21 CFR 320 that constrain generic cyclosporine interchangeability, while the EMA's Committee for Medicinal Products for Human Use reviews therapeutic equivalence claims for European market access. India's CDSCO mandates stability testing under accelerated conditions for domestic manufacturers exporting active pharmaceutical ingredients. Stakeholders must monitor evolving pharmacovigilance requirements for narrow therapeutic index drugs as regulators tighten post-market surveillance across major jurisdictions.
Market Dynamics
Integrated delivery networks now consolidate cyclosporine procurement across transplant centers, concentrating purchasing power and compressing supplier margins as formulary decisions migrate from individual hospitals to regional health systems.
Growth Catalysts
- Surgical volume expansion:Rising kidney and liver transplant procedures in the United States, Germany, and India generate sustained demand for perioperative immunosuppression protocols.
- EMA therapeutic equivalence pathways:Streamlined biosimilar review procedures accelerate generic cyclosporine access across European transplant centers.
- Ophthalmic emulsion uptake:Dry eye disease diagnosis rates climb as diagnostic thresholds tighten, expanding prescriptions beyond transplant indications.
Market Restraints
- Narrow therapeutic index constraints:FDA bioequivalence requirements under 21 CFR 320 limit interchangeable generic substitution, protecting branded pricing but constraining cost savings.
- Active pharmaceutical ingredient concentration:Fermentation-based cyclosporine production clusters in select Indian and Chinese manufacturing sites, creating supply vulnerability.
- Biologic immunosuppressant substitution:Tacrolimus and belatacept formulations displace cyclosporine in de novo transplant protocols at major US academic medical centers.
Strategic Opportunities
- Brazilian market penetration:ANVISA regulatory harmonization with ICH standards reduces entry barriers for generic manufacturers targeting Latin America's largest transplant program.
- Topical dermatology expansion:Psoriasis and atopic dermatitis applications remain underdeveloped relative to transplant and ophthalmology, offering white-space positioning.
- Direct-to-specialty pharmacy distribution:Bypassing wholesale intermediaries captures margin and improves cold-chain control for temperature-sensitive formulations.
Industry Challenges
- Calcineurin inhibitor therapeutic drug monitoring:Specialized pharmacokinetic expertise shortages constrain optimal dosing at community transplant programs.
- Post-approval pharmacovigilance compliance:FDA Risk Evaluation and Mitigation Strategy requirements impose ongoing surveillance costs that burden mid-scale generic entrants.
- Legacy formulation switching friction:Transplant recipients stabilized on specific cyclosporine brands resist conversion due to bioavailability variability concerns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyclosporine Market |
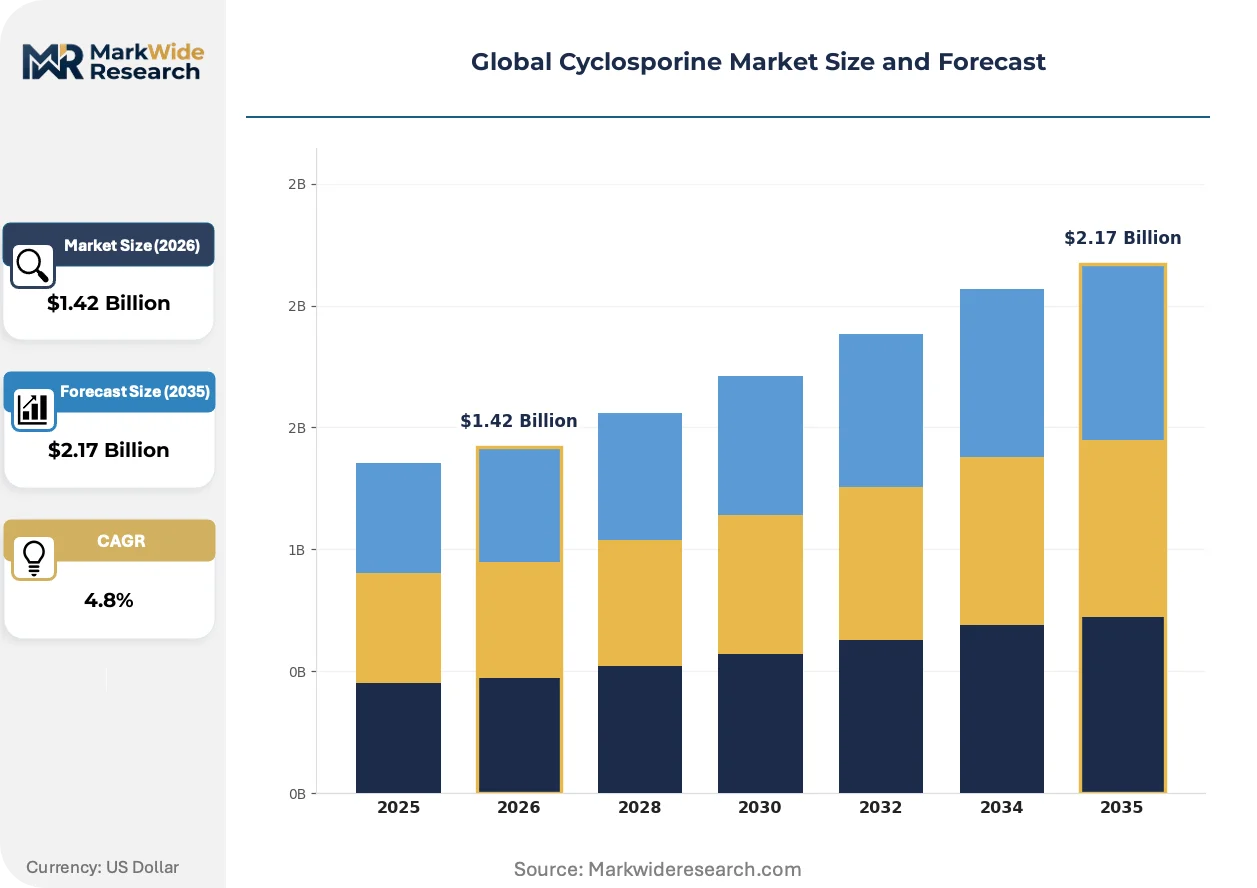
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Capsules, Injectable Solution, Topical Ointment, Ophthalmic Emulsion Therapy Area: Organ Transplantation, Autoimmune Disorders, Dermatological Conditions, Ophthalmic Diseases End User: Specialty Clinics, Transplant Centers, Eye Care Facilities, Rheumatology Practices Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | AbbVie, Novartis, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Santen Pharmaceutical, Viatris, Cipla, Apotex, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyclosporine Market Shifts & Advancements
Formulation science and distribution architecture are reshaping cyclosporine competitive dynamics. Three developments warrant particular attention: delivery technology evolution, regulatory framework adaptation, and procurement model transformation.
Nanosuspension oral formulations are rendering obsolete conventional soft-gelatin capsule absorption profiles. Novartis and select generic manufacturers now engineer particle-size distributions that improve bioavailability consistency. Transplant centers in the United States and Germany are adopting these formulations for patients with malabsorption syndromes or biliary complications. The technology is rendering obsolete historical concerns about food-effect variability that drove therapeutic drug monitoring intensity.
REACH authorization requirements for pharmaceutical intermediates are tightening documentation burdens on European cyclosporine API importers. The regulation mandates supply chain transparency down to fermentation-source Tolypocladium inflatum strains. German and Swiss finished-dose manufacturers now audit Indian API suppliers against expanded substance-of-very-high-concern criteria. Small-volume generic entrants without dedicated regulatory affairs teams are exiting the European market rather than absorbing compliance costs.
Specialty pharmacy carve-outs from medical benefit structures are concentrating cyclosporine dispensing authority. United States payers now mandate distribution through designated specialty pharmacies for oral immunosuppressants, displacing hospital outpatient dispensing. This channel shift compresses pharmacy reimbursement spreads while elevating data-reporting requirements. The phenomenon is most visible in Medicare Advantage plans covering renal transplant populations in Florida, Texas, and California.
Global Cyclosporine Market Segmentation
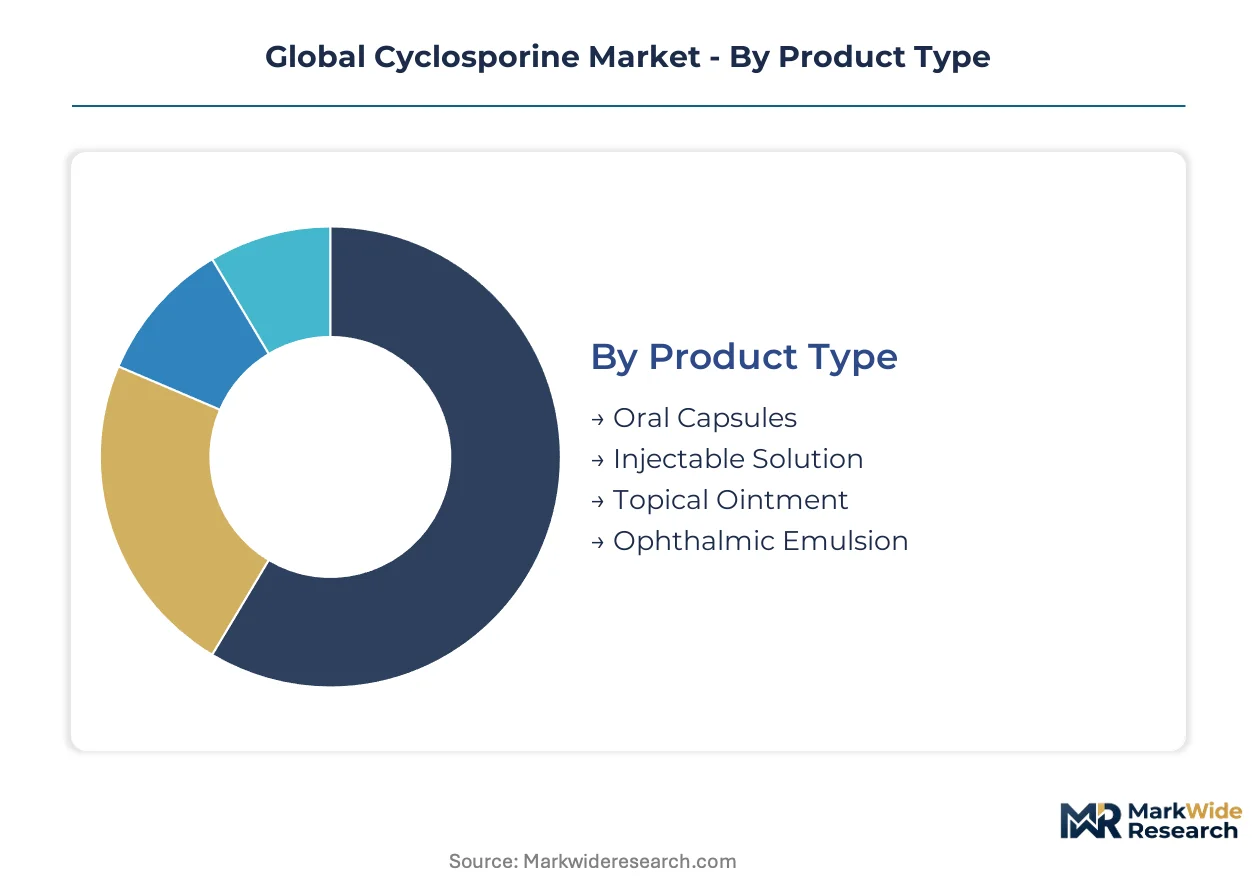
Cyclosporine's therapeutic breadth spans transplant medicine, autoimmune management, and ophthalmic care, with each application demanding distinct formulation specifications and distribution pathways. Segmentation reveals how procurement patterns diverge between acute surgical settings and chronic maintenance protocols across global markets.
Product Type:
The use-case spectrum stretches from immediate perioperative immunosuppression to decades-long outpatient maintenance, with formulation chemistry determining bioavailability profiles and storage requirements.
- Oral Capsules:Soft gelatin capsules containing 25 mg or 100 mg cyclosporine constitute the maintenance standard for renal and hepatic transplant recipients. Demand concentrates in the United States and Germany where Medicare and statutory health insurance systems sustain long-term patient access to branded and generic formulations.
- Ophthalmic Emulsion:Oil-in-water emulsion formulations deliver calcineurin inhibition to ocular surface tissues without systemic immunosuppression. Prescription volumes are climbing fastest in dry eye disease applications across United States specialty ophthalmology practices as diagnostic thresholds tighten.
- Injectable Solution:Intravenous formulations enable immediate calcineurin inhibition during organ reperfusion.
- Topical Ointment:Dermal preparations target localized psoriasis and atopic dermatitis with reduced systemic exposure.
Established volume favors oral capsules; emerging adoption favors ophthalmic emulsion.
Therapy Area:
Cost tier stratification separates acute surgical intervention from chronic disease management, with reimbursement intensity varying by clinical urgency and outcome measurability.
- Organ Transplantation:Perioperative and maintenance immunosuppression for kidney, liver, heart, and lung allografts represents the original and still-dominant commercial foundation. Procedure volumes in India and the United States generate sustained demand for protocol-standardized formulations.
- Ophthalmic Diseases:Dry eye disease and ocular surface inflammation now constitute the fastest-expanding prescription category. United States payers increasingly carve ophthalmic cyclosporine into specialty pharmacy benefits, concentrating dispensing authority.
- Autoimmune Disorders:Rheumatoid arthritis and systemic lupus erythematosus applications persist despite biologic displacement.
- Dermatological Conditions:Psoriasis and atopic dermatitis remain underdeveloped relative to transplant and ophthalmology indications.
Transplantation anchors revenue stability; ophthalmic diseases are gaining share fastest.
End User:
Customer type determines procurement sophistication, with integrated delivery networks consolidating purchasing for high-volume transplant centers while individual practices retain autonomy in ophthalmology and rheumatology.
- Transplant Centers:High-volume surgical programs in the United States, Germany, and India drive bulk procurement of oral and injectable formulations. These centers negotiate directly with manufacturers through group purchasing organizations, compressing supplier margins.
- Eye Care Facilities:Ophthalmology clinics and ambulatory surgery centers generate prescription demand for emulsion formulations. United States specialty pharmacy mandates are displacing traditional dispensing models in Florida, Texas, and California markets.
- Specialty Clinics:Multi-specialty immunology practices manage autoimmune indications.
- Rheumatology Practices:Individual practitioners prescribe for connective tissue disorders with declining frequency.
Transplant centers concentrate purchasing power; eye care facilities are expanding most quickly.
Distribution Channel:
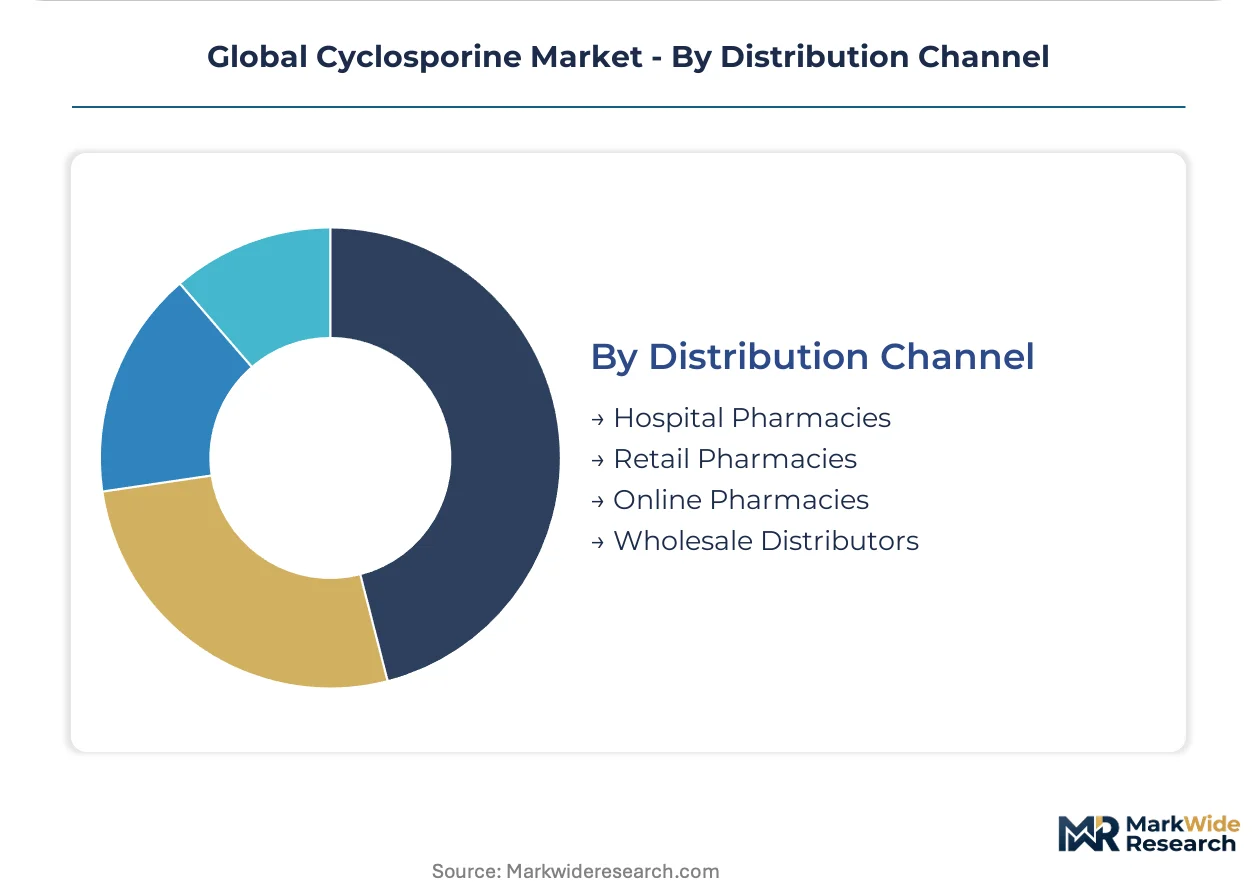
Supply concentration characterizes this dimension, with hospital pharmacy networks and specialty pharmacy carve-outs displacing traditional wholesale intermediaries for immunosuppressant distribution.
- Hospital Pharmacies:Inpatient and outpatient dispensing at transplant centers maintains immediate access for perioperative protocols. United States integrated delivery networks now consolidate cyclosporine procurement across regional health systems.
- Online Pharmacies:Direct-to-patient distribution is expanding for maintenance oral formulations where cold-chain requirements are less stringent. Regulatory compliance with FDA track-and-trace requirements constrains market entry.
- Retail Pharmacies:Community pharmacies serve stable maintenance patients with predictable refill patterns.
- Wholesale Distributors:Traditional intermediaries face margin compression as direct distribution models proliferate.
Hospital pharmacies dominate acute access; online pharmacies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European cyclosporine distribution efficiency, while Indian API fermentation clusters feed global finished-dose manufacturing networks across three continents.
United States
Medicare reimbursement policies sustain long-term patient access to both branded and generic cyclosporine formulations for renal transplant recipients. The FDA enforces bioequivalence protocols under 21 CFR 320 that constrain generic interchangeability for narrow therapeutic index drugs. Transplant centers in Florida, Texas, and California drive volume through consolidated procurement across integrated delivery networks.
Germany
Statutory health insurance systems maintain reimbursement for maintenance immunosuppression in renal and hepatic transplant populations. The EMA's Committee for Medicinal Products for Human Use reviews therapeutic equivalence claims for European market access. REACH authorization requirements for pharmaceutical intermediates now mandate supply chain transparency down to fermentation-source Tolypocladium inflatum strains for German finished-dose manufacturers.
India
Domestic transplant procedure volumes climb alongside expanding medical tourism for renal transplantation at tertiary centers. The CDSCO mandates stability testing under accelerated conditions for domestic manufacturers exporting active pharmaceutical ingredients. Fermentation-based cyclosporine production clusters in Hyderabad and Mumbai supply API to European and North American formulation facilities.
Brazil
Latin America's largest transplant program generates sustained demand for perioperative and maintenance immunosuppression protocols. ANVISA regulatory harmonization with ICH standards reduces entry barriers for generic manufacturers targeting the Brazilian market. São Paulo's transplant centers anchor regional procurement concentration for oral and injectable cyclosporine formulations.
Switzerland
Swissmedic maintains stringent pharmacovigilance requirements for narrow therapeutic index immunosuppressants distributed domestically. The country's pharmaceutical logistics infrastructure supports temperature-sensitive formulation distribution across Alpine transit corridors. Basel's concentration of specialty pharmaceutical operations includes finished-dose packaging for European export markets.
Global Cyclosporine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The cyclosporine market structures around established pharmaceutical conglomerates with transplant medicine franchises, mid-scale generic manufacturers with fermentation API capabilities, and ophthalmic-focused specialists with emulsion formulation expertise. Competitive moves concentrate on direct-to-specialty pharmacy distribution partnerships and nanosuspension oral formulation development for bioavailability differentiation.
Among research-based pharmaceutical conglomerates, Novartis anchors the branded maintenance therapy segment through its established neoral franchise. Sun Pharmaceutical Industries and Teva Pharmaceutical Industries occupy positions within the generic oral capsule tier, with Sun leveraging deep formulary penetration across United States hospital systems. Santen Pharmaceutical exemplifies the ophthalmic specialization archetype, concentrating on dry eye disease applications where emulsion formulations command premium positioning.
| Leading Market Players |
|---|
| AbbVie |
| Novartis |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Santen Pharmaceutical |
| Viatris |
| Cipla |
| Apotex |
| Dr. Reddy's Laboratories |
| Others |
Supply & Pricing Matrix
Fermentation-source concentration in Hyderabad and Mumbai API clusters determines both the three-tier pricing structure across branded, authorized generic, and commodity generic levels and the geographic vulnerability of finished-dose supply. Buyers face asymmetric exposure: integrated delivery networks leverage volume consolidation for tier-one pricing, while independent transplant programs absorb premium markups from distributor intermediaries.
Pricing Analysis
Volume-discount tiering separates Novartis-branded Neoral from authorized generics and deep-penetration commodity capsules. Price differentiation rests on FDA bioequivalence certification tier and formulary placement depth. Cost compression in the commodity generic tier is intensifying because Sun Pharmaceutical and Teva are competing for hospital system sole-source contracts. Community transplant programs show highest price sensitivity; academic medical centers with research funding demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with Sun Pharmaceutical, Cipla, and Dr. Reddy's Laboratories for oral capsule finishing, while Santen Pharmaceutical controls ophthalmic emulsion formulation capacity. Geographic supply concentration centers on India for API fermentation, Germany for finished-dose packaging, and the United States for distribution to transplant centers. Raw material dependencies include Tolypocladium inflatum fermentation biomass, pharmaceutical-grade gelatin for capsules, and purified soybean oil for emulsion vehicles. Single-source vulnerability characterizes the API tier, where REACH authorization requirements for pharmaceutical intermediates are tightening documentation burdens. Distribution runs through specialty pharmacy carve-outs for maintenance oral formulations and hospital pharmacy networks for perioperative injectable supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyclosporine market is approaching a platform-economics inflection as specialty pharmacy data integration creates interoperability between transplant center electronic health records and payer prior-authorization systems. This ecosystem shift will concentrate dispensing authority and reshape competitive access.
For Market Incumbents: Pre-empt biologic substitution threats by accelerating nanosuspension oral formulation development for malabsorption patients. Secure backward integration into fermentation capacity through long-term API supply agreements with Indian manufacturers. Channel control through direct-to-specialty pharmacy partnerships offers the strongest defensive lever against generic margin compression.
For New Entrants and Emerging Players: Pursue Brazilian market entry through ANVISA regulatory harmonization pathways, where Latin America's largest transplant program offers white-space positioning. Target topical dermatology applications for psoriasis and atopic dermatitis, which remain underdeveloped relative to transplant and ophthalmology. A go-to-market angle anchored in cold-chain logistics excellence can differentiate against incumbent distribution networks.
For Investors and Strategic Acquirers: FDA Risk Evaluation and Mitigation Strategy tightening reshapes the acquisition landscape by elevating compliance costs that burden mid-scale generic entrants. Long-term viability favors platform-integrated players with specialty pharmacy data capabilities and multi-therapeutic-area immunosuppressant portfolios. The signal to watch is EMA therapeutic equivalence pathway acceleration, which would unlock European market access for emerging generic manufacturers and shift competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanosuspension Oral Formulation Development | Novartis and select generic manufacturers engineer particle-size distributions that improve bioavailability consistency for malabsorption patients. |
| Direct-to-Specialty Pharmacy Distribution | Bypassing wholesale intermediaries captures margin and improves cold-chain control for temperature-sensitive ophthalmic emulsion formulations. |
| REACH Authorization Compliance Investment | German and Swiss finished-dose manufacturers audit Indian API suppliers against expanded substance-of-very-high-concern criteria. |
| Brazilian Market Regulatory Entry | ANVISA harmonization with ICH standards reduces entry barriers for generic manufacturers targeting Latin America's largest transplant program. |
| Topical Dermatology Indication Expansion | Psoriasis and atopic dermatitis applications remain underdeveloped relative to transplant and ophthalmology, offering white-space positioning. |
Research Methodology
Desk research of FDA bioequivalence filings, EMA therapeutic equivalence submissions, and hospital procurement databases preceded structured interviews with transplant center pharmacy directors, formulary managers at integrated delivery networks, regulatory affairs leads at generic manufacturers, and specialty pharmacy operations executives. Primary fieldwork validated secondary data on pricing tier spreads and supply chain configuration. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing were triangulated against Medicare reimbursement data and statutory health insurance claims.
Assumptions held transplant procedure volumes, regulatory bioequivalence standards, and specialty pharmacy carve-out penetration rates fixed across the analysis window, while varying generic substitution elasticity and biologic immunosuppressant displacement rates. Segmentation dimensions modeled include formulation type, therapy area, end-user concentration, and distribution channel. CAGRs were derived from procedure volume forecasts weighted by maintenance therapy duration and dosing intensity. Forecast inputs incorporated REACH authorization compliance cost trajectories and ophthalmic emulsion prescription growth patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-scale generic entrants or biologic immunosuppressant developers would shift outcomes. Regulatory tightening on narrow therapeutic index drugs and API supply concentration represent specific revision risks. Quarterly review of FDA bioequivalence approval cadence and specialty pharmacy market share shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Urinary Retention Drugs Market