
 Pharmaceutical Glycerine Market | 2026-2036
Pharmaceutical Glycerine Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glycerine Market Analytics
Capital-intensity divergence between oleochemical refiners and downstream blenders is reorganizing competitive tiers in pharmaceutical glycerine supply. KLK OLEO leverages integrated palm-oil refining complexes across Southeast Asia to sustain cost-advantaged USP-grade output. Emery Oleochemicals anchors its position through backward integration into fatty acid distillation, while Cargill, Inc. competes via global logistics networks that control multi-continental distribution to pharmaceutical manufacturers.
Pharmaceutical glycerine is a trihydric alcohol (propane-1,2,3-triol) refined to meet USP or EP monograph specifications for purity, typically exceeding 99.5% concentration with strict limits on diethylene glycol and related impurities, serving primarily as a humectant, solvent, and stabilizing excipient in oral dosage forms, topical preparations, and parenteral solutions. USP Grade commands the dominant value share due to pharmacopeial compliance requirements for drug applications, while Personal Care applications represent a structurally faster-growing adjacent pool as cosmeceutical formulations absorb glycerine at lower regulatory burden. Liquid form occupies the core volume position, though Powder glycerine is gaining traction in solid-dose manufacturing lines seeking moisture control without handling viscosity constraints.
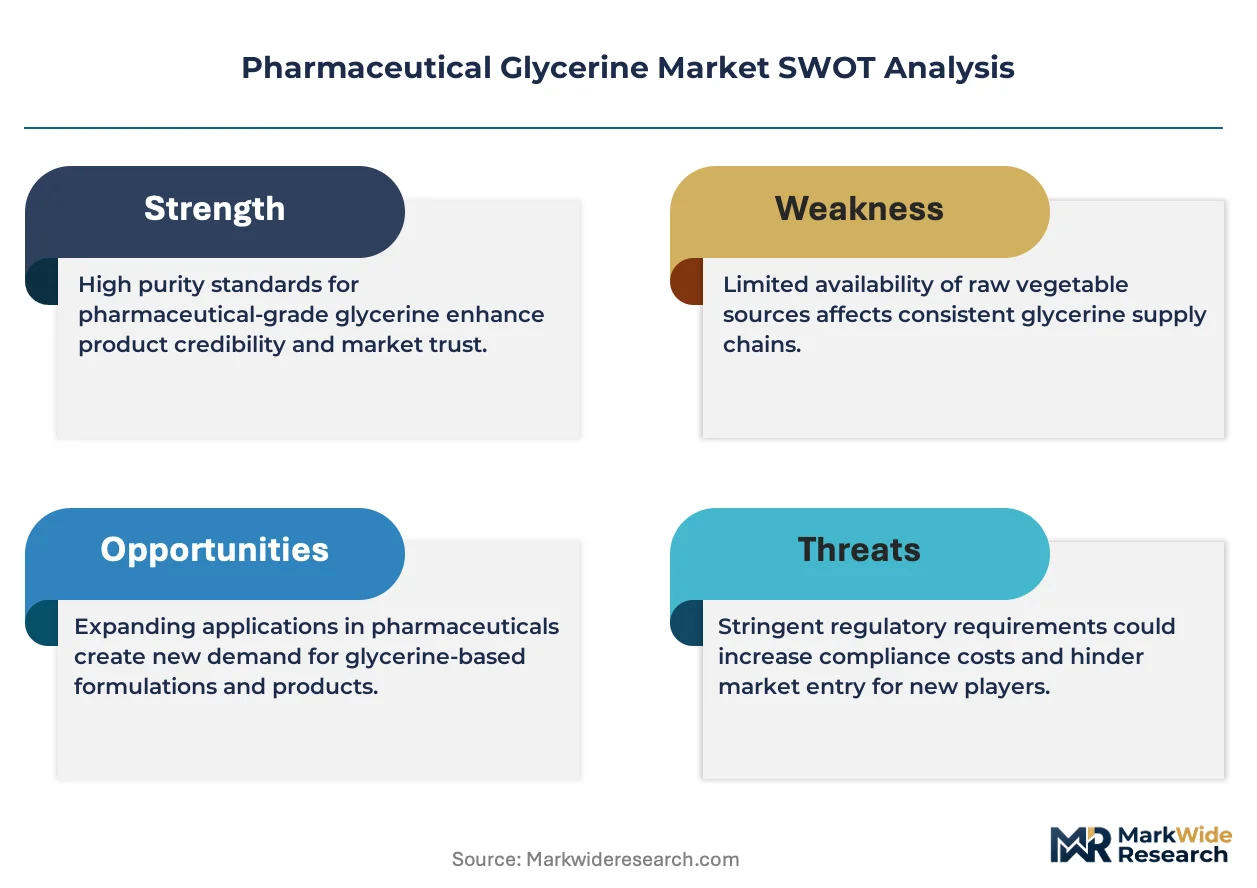
The US FDA enforces ICH Q3D elemental impurity limits and USP-NF monograph adherence, while the European EMA through the EP and REACH frameworks governs excipient registration and supply chain transparency; India's CDSCO aligns with these standards while adding BIS certification layers for imported glycerine. Compliance with this multi-jurisdictional regulatory lattice directly shapes supplier qualification timelines and capital allocation toward dedicated pharmaceutical-grade refining assets. Stakeholders must monitor evolving pharmacopeial harmonization debates and bio-based feedstock certification schemes to anticipate which refining configurations will retain premium access.
Market Dynamics
Pharmaceutical glycerine supply chains are restructuring around pharmacopeial convergence between USP-NF and EP monographs, forcing refiners to consolidate multi-jurisdictional certification under single production lines rather than maintaining parallel grade streams.
Growth Catalysts
- Pharmacopeial Harmonization:The US FDA and EMA are tightening alignment on elemental impurity limits under ICH Q3D, compelling pharmaceutical manufacturers to source certified USP-grade material from qualified refiners.
- India's PLI Scheme:Government production-linked incentives for domestic API manufacturing are drawing glycerine procurement toward local contract manufacturers and integrated pharmaceutical producers.
- Parenteral Formulation Expansion:Rising demand for sterile injectable drugs is accelerating consumption of high-purity glycerine as a stabilizing excipient in parenteral solutions.
Market Restraints
- Crude Glycerine Price Volatility:Biodiesel production fluctuations create feedstock cost instability that compresses refiner margins during oversupply cycles.
- Southeast Asian Supply Concentration:Palm-oil derived glycerine refining clusters in Malaysia and Indonesia create geographic risk exposure for pharmaceutical buyers seeking supply security.
- Diethylene Glygone Contamination Scrutiny:Zero-tolerance pharmacopeial limits on DEG impurities require capital-intensive molecular distillation that excludes smaller refiners from pharmaceutical qualification.
Strategic Opportunities
- Brazil's ANVISA Alignment:Latin America's largest pharmaceutical market is adopting USP-grade standards, opening qualification pathways for certified exporters.
- Solid-Dose Manufacturing Shift:Powder glycerine adoption in tablet production lines offers moisture control without liquid handling infrastructure.
- Cosmeceutical Channel Expansion:Personal care formulations with lower regulatory burden are absorbing pharmaceutical-grade material at premium pricing.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Simultaneous USP-NF, EP, and BIS compliance requires 18-24 month qualification cycles that strain working capital.
- Analytical Chemist Scarcity:Specialized expertise in ICP-MS elemental analysis and chromatographic impurity profiling remains concentrated among contract testing laboratories.
- Legacy Batch Record Systems:Pharmaceutical manufacturers face integration friction when connecting refiner electronic batch records to internal ERP traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glycerine Market |
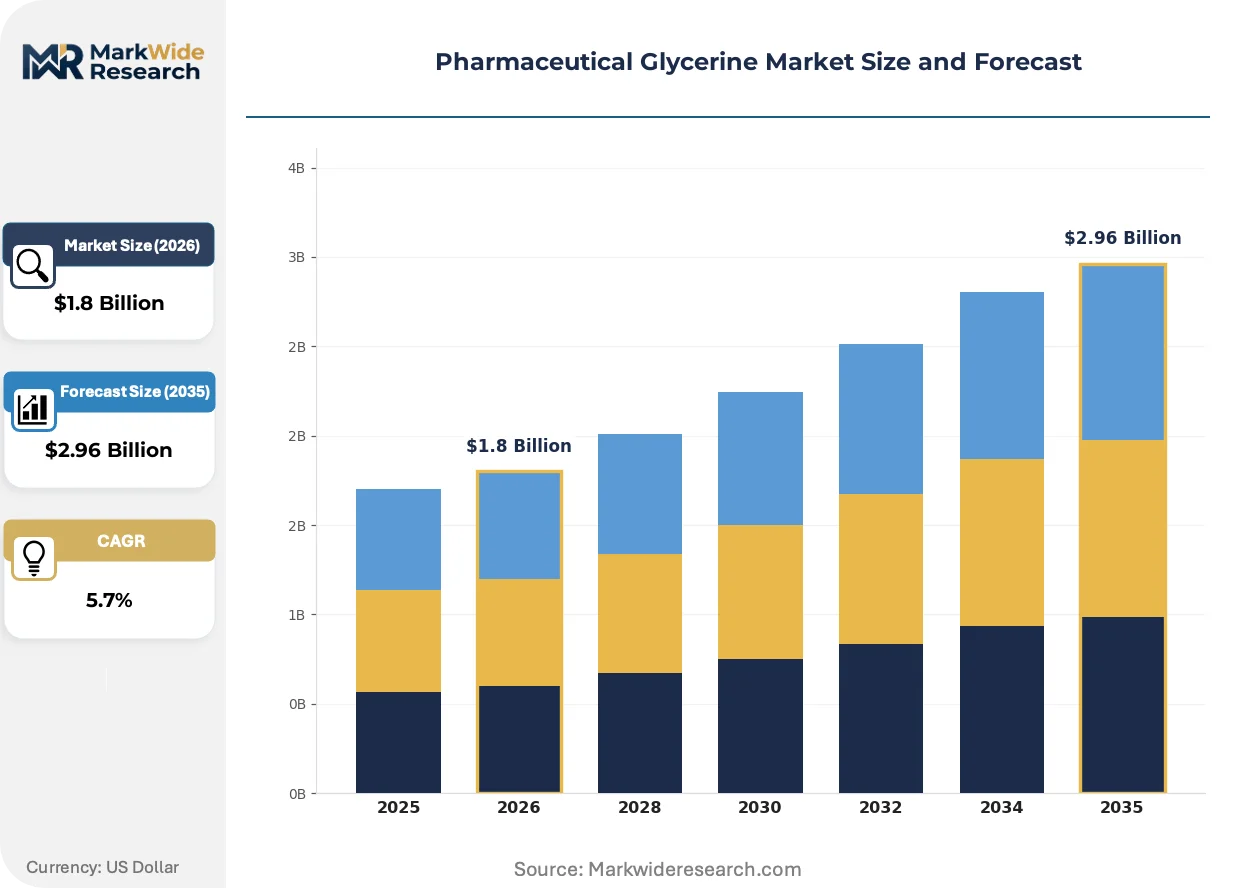
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USP Grade, Food Grade, Industrial Grade, Technical Grade Application: Pharmaceuticals, Personal Care, Food Processing, Tobacco Form: Liquid, Powder, Gel, Emulsion End User: Pharmaceutical Manufacturers, Contract Manufacturers, Retail Pharmacies, Hospitals |
| Companies Covered | Monarch Chemicals Ltd., Hangzhou Oleochemicals Co., Ltd., KLK OLEO, Emery Oleochemicals, Hunan Er-Kang Pharmaceutical Co., Ltd., P&G Chemicals, Munzer Bioindustrie GmbH, Cargill, Inc., Oleon NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glycerine Market Evolving Landscape
Continuous processing technologies and real-time release testing are displacing traditional batch refining in pharmaceutical glycerine production, compressing cycle times while tightening impurity control.
Membrane filtration systems with nanofiltration cascades are miniaturizing the purification footprint for USP-grade glycerine, enabling regional micro-refineries to serve pharmaceutical clusters without economies of scale. Mid-sized API manufacturers in India and Eastern Europe are adopting these systems to secure captive supply. This distributed model is compressing the historical advantage of integrated Southeast Asian palm-oil complexes.
REACH registration requirements under ECHA are extending supply chain transparency mandates to glycerine importers, forcing documentation of biodiesel feedstock origins and refining subcontractor qualifications. European pharmaceutical manufacturers now require extended-SDS disclosure through tier-3 suppliers. This regulatory weight falls heaviest on traders lacking direct refiner relationships, pushing procurement toward backward-integrated suppliers.
Buyer consolidation among contract development and manufacturing organizations is concentrating glycerine procurement under fewer pharmaceutical purchasing desks, shifting negotiation leverage toward volume-commitment contracts with indexed pricing. Large CDMOs are unbundling excipient sourcing from formulation services, creating dedicated procurement functions that qualify fewer, larger suppliers. This pattern is most pronounced in India's Hyderabad-Bengaluru pharmaceutical corridor and Germany's Rhine-Main manufacturing cluster.
Pharmaceutical Glycerine Market Segmentation
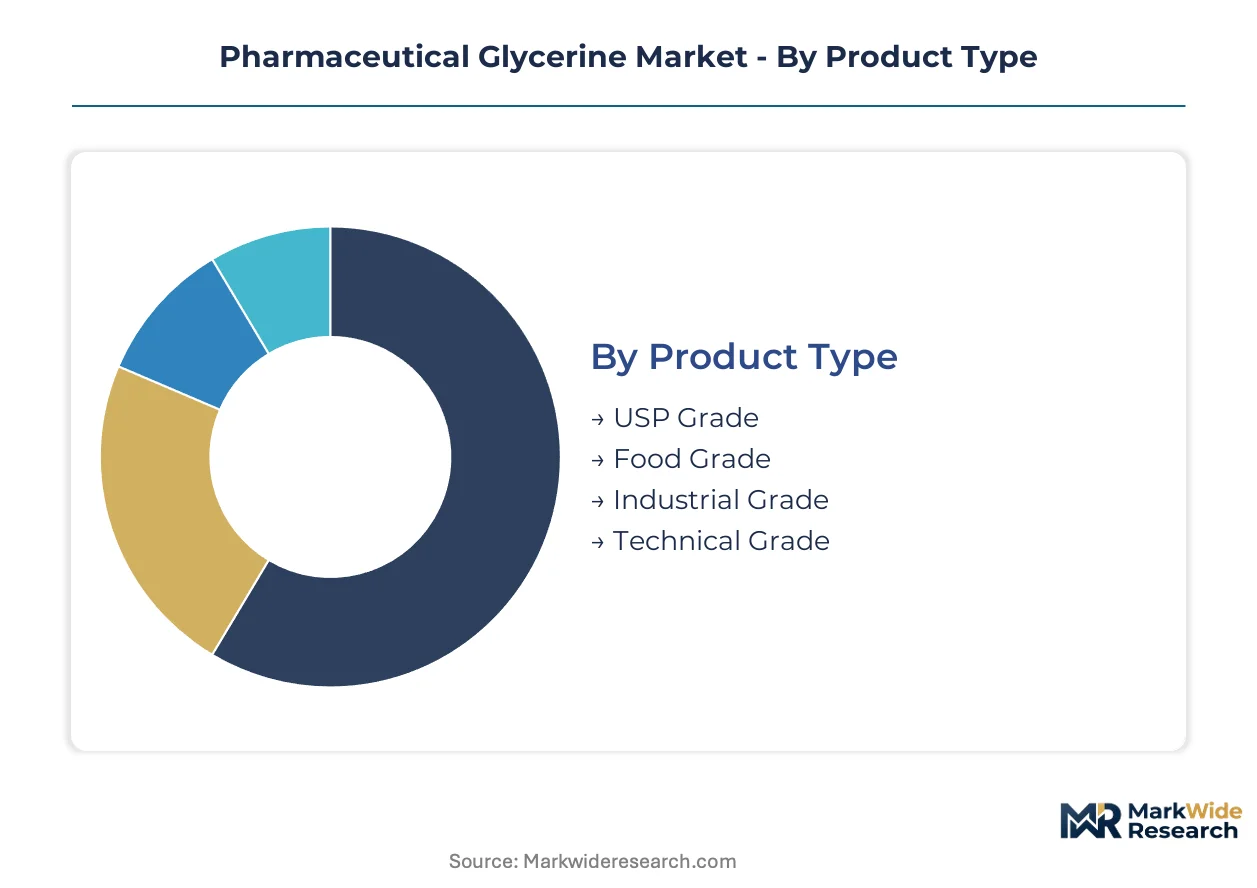
Segmentation in pharmaceutical glycerine separates pharmacopeial-certified material from commodity grades, determining pricing power and regulatory qualification burden. Each dimension—grade purity, end-use application, physical form, and customer type—carries distinct margin profiles and substitution vulnerabilities.
Product Type:
Substitution pressure intensifies downward through the grade hierarchy, with USP Grade protected by regulatory moats while Technical Grade faces direct competition from synthetic polyols and petroleum-derived alternatives.
- USP Grade:Refined to exceed 99.5% purity with strict ICH Q3D elemental impurity limits and zero-tolerance DEG thresholds. Pharmaceutical manufacturers in India and Germany concentrate procurement here as FDA and EMA pharmacopeial alignment tightens.
- Food Grade:Meets FCC and FSSAI specifications for edible applications with moderated purity requirements. Demand concentrates in confectionery and beverage processing where glycerine serves as humectant and sweetener carrier.
- Industrial Grade:Standard refining for adhesives, coatings, and chemical intermediates with minimal pharmacopeial compliance burden.
- Technical Grade:Basic refined glycerine for antifreeze, de-icing, and industrial solvents facing substitution by propylene glycol and synthetic alternatives.
USP Grade anchors the volume base in pharmaceutical channels while Food Grade gains share at the steepest rate as clean-label formulations absorb glycerine across beverage and nutraceutical applications.
Application:
Cost tier differentiation separates regulated pharmaceutical use from adjacent segments where certification requirements relax and margin compression accelerates.
- Pharmaceuticals:Oral dosage forms, parenteral solutions, and topical preparations requiring USP-NF or EP monograph compliance. Hyderabad-Bengaluru API clusters and Rhine-Main manufacturing corridors drive procurement concentration.
- Personal Care:Cosmeceutical formulations absorb pharmaceutical-grade material at reduced regulatory burden compared to drug applications. Moisturizers, serums, and anti-aging products in South Korea and France expand offtake.
- Food Processing:Humectant and stabilizer functions in baked goods, confectionery, and beverages operating under FSSAI and FDA food additive frameworks.
- Tobacco:Moisture retention in smokeless and traditional products facing secular decline in developed markets and regulatory pressure from WHO frameworks.
Pharmaceuticals commands premium pricing through certification barriers while Personal Care expands most quickly as cosmeceutical brands upgrade formulation specifications.
Form:
Volume economics favor liquid handling infrastructure, though powder adoption reshapes manufacturing footprints where viscosity constraints drive operational redesign.
- Liquid:Standard viscous state for bulk excipient supply, solvent applications, and continuous processing lines. Dominates contract manufacturing organization procurement in India and Eastern Europe.
- Powder:Spray-dried or crystallized glycerine enabling direct compression in tablet manufacturing without liquid handling systems. CDMOs in solid-dose production adopt for moisture control precision.
- Gel:Thickened preparations for topical and transdermal delivery systems requiring rheology modification.
- Emulsion:Stabilized dispersions for complex formulations demanding phase compatibility.
Liquid form retains volume dominance through established supply chains while Powder climbs the fastest as solid-dose manufacturers retrofit for glycerine inclusion without tank farm investment.
End User:
Customer consolidation among integrated pharmaceutical makers concentrates procurement leverage, fragmenting opportunity for smaller refiners serving dispersed retail and institutional channels.
- Pharmaceutical Manufacturers:Integrated API and formulation producers with captive excipient qualification teams and direct refiner relationships. India's PLI scheme beneficiaries and German generics specialists anchor demand.
- Contract Manufacturers:CDMOs unbundling excipient sourcing from formulation services, creating dedicated procurement functions that qualify fewer, larger suppliers. Hyderabad and Bavaria clusters concentrate activity.
- Retail Pharmacies:Compounding and specialty preparation channels with fragmented, small-batch requirements.
- Hospitals:Institutional procurement for parenteral nutrition, dialysis solutions, and sterile compounding with stringent batch documentation needs.
Pharmaceutical Manufacturers dominate value capture through scale commitments while Contract Manufacturers restructure procurement fastest toward supplier consolidation and indexed pricing frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India exhibit the highest price elasticity as domestic API producers source aggressively under PLI scheme pressures, while German and US pharmaceutical manufacturers prioritize pharmacopeial certification over unit cost, creating a two-tier procurement geography.
United States
FDA enforcement of ICH Q3D elemental impurity limits drives qualified refiner consolidation among parenteral solution manufacturers. The agency's USP-NF monograph alignment with EMA standards compresses supplier qualification timelines for domestic excipient buyers. New Jersey and North Carolina pharmaceutical corridors concentrate glycerine procurement under integrated API producers seeking captive supply security.
Germany
EMA pharmacopeial requirements through the EP framework govern excipient registration with REACH-mandated supply chain transparency. Rhine-Main manufacturing clusters anchor demand as CDMOs unbundle excipient sourcing from formulation services. Bavarian generics specialists are consolidating procurement under fewer qualified suppliers with indexed pricing frameworks.
India
CDSCO alignment with USP and EP standards combines with BIS certification layers for imported glycerine. Government PLI incentives for domestic API manufacturing draw procurement toward Hyderabad-Bengaluru contract manufacturers. Domestic refiners are capturing share from Southeast Asian palm-oil complexes as local production scales under import substitution pressure.
China
NMPA pharmacopeial standards tighten alongside GB standards for excipient purity as domestic formulation quality upgrades. Yangtze River Delta pharmaceutical clusters drive demand for USP-grade material in export-oriented API production. Shanghai-based refiners are investing in molecular distillation capabilities to meet zero-tolerance DEG impurity thresholds.
Brazil
ANVISA adoption of USP-grade standards opens qualification pathways for certified exporters serving Latin America's largest pharmaceutical market. São Paulo and Rio de Janeiro formulation hubs absorb glycerine for oral dosage and topical preparations. Local distributors are restructuring toward direct refiner relationships as supply chain transparency mandates intensify.
Pharmaceutical Glycerine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated palm-oil refiners commanding feedstock economics while specialized pharmaceutical-grade processors capture certification premiums. The market structures around three tiers: Southeast Asian oleochemical giants with backward integration into fatty acid distillation, regional micro-refineries deploying membrane filtration for captive supply, and global traders facing margin compression from REACH documentation requirements. Dominant competitive moves include capacity consolidation around pharmacopeial-certified production lines and geographic expansion into India's PLI-subsidized manufacturing corridors.
Among integrated oleochemical specialists, KLK OLEO and Emery Oleochemicals exemplify the scale-driven archetype with upstream control over refining assets, while Cargill, Inc. occupies a position within global logistics-intensive supply structures. These three anchors represent divergent strategic configurations: palm-oil integrated complexes, fatty acid distillation backward integration, and multi-continental distribution networks serving pharmaceutical qualification requirements.
| Leading Market Players |
|---|
| Monarch Chemicals Ltd. |
| Hangzhou Oleochemicals Co., Ltd. |
| KLK OLEO |
| Emery Oleochemicals |
| Hunan Er-Kang Pharmaceutical Co., Ltd. |
| P&G Chemicals |
| Munzer Bioindustrie GmbH |
| Cargill, Inc. |
| Oleon NV |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Southeast Asian palm-oil complexes anchors price floors across USP-grade glycerine tiers, with 85-90% operating rates at KLK OLEO and Emery Oleochemicals facilities sustaining margin discipline that smaller membrane-filtration micro-refineries cannot match. This scale concentration creates asymmetric pricing power where integrated oleochemical giants capture pharmacopeial certification premiums while regional players compete on logistics proximity to India's Hyderabad-Bengaluru corridor.
Pricing Analysis
After-sales revenue from multi-year qualification contracts and indexed supply agreements drives lifetime value for pharmaceutical-grade refiners. Three-tier pricing structure across USP-certified, food-grade, and technical-grade levels separates pharmacopeial-compliant material commanding premium positioning from commodity grades facing propylene glycol substitution. Cost compression in technical-grade tiers is intensifying because biodiesel feedstock volatility transmits directly to crude glycerine input costs. Contract manufacturing organizations in India exhibit highest price elasticity, while German parenteral solution manufacturers prioritize EP monograph adherence over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore container terminals elevates inbound logistics costs for European and Asian pharmaceutical manufacturers sourcing from Malaysian and Indonesian refining clusters. Supply concentrates in Malaysia, Indonesia, and India, with raw material dependencies spanning crude glycerine from biodiesel transesterification, palm fatty acid distillate, and molecular sieve adsorbents for DEG removal. Single-source vulnerability pervades the Southeast Asian palm-oil derivative network, where geopolitical disruption or El Niño weather patterns threaten feedstock security. Distribution runs through qualified refiner-direct relationships with large pharmaceutical manufacturers, bypassing traders facing REACH documentation compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical glycerine incumbents face substitution defense against synthetic polyols and petroleum-derived propylene glycol in technical-grade applications, requiring pharmacopeial certification moats to sustain premium positioning.
For Market Incumbents: Shield USP-grade market share by accelerating molecular distillation capacity additions in India's PLI-subsidized manufacturing corridors, while consolidating electronic batch record integration capabilities to meet CDSCO and EMA traceability mandates. Propylene glycol encroachment in topical formulations demands tighter FDA qualification timelines as defensive differentiation. For New Entrants and Emerging Players: CDSCO fast-track certification for BIS-compliant imported glycerine offers entry pathway into India's domestic API production expansion. White-space targets include powder glycerine supply to Eastern European solid-dose CDMOs retrofitting for direct compression, and membrane-filtration micro-refinery deployment near Brazil's ANVISA-aligned São Paulo formulation hubs. Go-to-market angle should emphasize captive supply security with 18-24 month qualification cycle compression. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated oleochemical specialists with dedicated pharmaceutical-grade refining assets and multi-jurisdictional pharmacopeial certifications. Long-term viability over the next decade hinges on feedstock diversification beyond palm-oil dependence and REACH-compliant supply chain transparency infrastructure. Acquisition target archetype: regional micro-refineries with membrane filtration technology and existing FDA or EMA qualification pathways. Signal to watch is ICH Q3D elemental impurity limit harmonization progress between FDA and EMA, which would accelerate supplier consolidation toward certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Investment | Multi-jurisdictional USP-NF, EP, and BIS alignment secures qualification access to India's PLI-subsidized API manufacturers. |
| Membrane Filtration Capacity Deployment | Nanofiltration cascade technology enables regional micro-refineries to serve pharmaceutical clusters without Southeast Asian scale economics. |
| Backward Integration into Fatty Acid Distillation | Upstream control over refining assets protects margin compression from crude glycerine biodiesel feedstock volatility. |
| Electronic Batch Record Integration | Direct ERP connectivity with pharmaceutical manufacturers' traceability platforms accelerates CDMO procurement consolidation. |
| Powder Glycerine Production Scale-Up | Spray-dried format adoption captures solid-dose manufacturing shift toward moisture control without liquid handling infrastructure. |
Research Methodology
The analysis maps USP-grade, food-grade, and technical-grade glycerine segments, each validated through procurement directors at Indian contract manufacturers, regulatory affairs leads at German generics specialists, and refinery operations managers at Southeast Asian oleochemical complexes. Primary interviews with CDMO sourcing executives, EMA qualified person designees, and BIS certification auditors combined with secondary validation from FDA warning letter databases, EP monograph revision notices, and CDSCO import inspection records. Bottom-up capacity modeling and top-down excipient demand estimation provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include pharmacopeial grade tier, end-use application across pharmaceuticals and personal care, physical form, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements, PLI scheme disbursement trajectories, and parenteral formulation growth patterns. Industry-specific forecast inputs encompassed ICH Q3D implementation timelines and biodiesel mandate-driven crude glycerine availability.
Decision-makers should treat outputs as directional under assumptions of sustained pharmacopeial harmonization and palm-oil feedstock availability; material deviation would warrant model refresh. Specific risk factors include DEG contamination detection triggering regulatory enforcement waves, and REACH supply chain transparency mandates extending to tier-3 suppliers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market