
 Pharmaceutical Packaging Market | 2026-2036
Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Packaging Market Analysis
Biologics manufacturing is recalibrating pharmaceutical packaging requirements toward temperature-assured formats and high-barrier materials. Gerresheimer AG specializes in glass primary packaging for injectable therapies, sustaining its position through controlled expansion of tubular glass capacity. Amcor plc leads flexible packaging for oral solid doses, leveraging polymer science to extend moisture and oxygen protection across tropical distribution corridors.
Pharmaceutical packaging encompasses the containment, preservation, and delivery systems for drug products, incorporating specifications such as oxygen transmission rates below 0.1 cc/m²/day for high-barrier films and child-resistant closure torque requirements measured in inch-pounds. Its primary purpose is to maintain drug stability, ensure patient safety, and enable regulatory compliance from manufacture through administration. Blister packs dominate oral solid dose dispensing in retail pharmacy channels, where unit-dose compliance packaging commands premium positioning. Plastic resins, particularly cyclic olefin polymers and multilayer polypropylene, are displacing glass in parenteral applications where break resistance and design flexibility outweigh traditional material preferences.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates are forcing packaging line investments in aggregation hardware and cloud-verified authentication layers. Health Canada and the EMA are aligning on tamper-evident standards for high-risk dosage forms, tightening market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions while deciding whether to standardize platforms globally or fragment production regionally.
Market Dynamics
Cold-chain serialization mandates are compressing packaging line economics, forcing capital deployment toward aggregation hardware and cloud-verified authentication layers that synchronize FDA Drug Supply Chain Security Act compliance with EU MDR traceability requirements.
Growth Catalysts
- Biologics Cold-Chain Expansion:Temperature-sensitive biologics manufacturing is recalibrating demand toward validated thermal shippers and phase-change materials that maintain 2-8°C stability across extended distribution corridors.
- EU MDR Traceability Mandates:The European Union's Medical Device Regulation is compelling line investments in unit-level serialization and tamper-evident features for high-risk dosage forms entering European markets.
- Cyclic Olefin Polymer Adoption:Parenteral drug manufacturers are migrating from glass to break-resistant cyclic olefin polymers and multilayer polypropylene for design flexibility in auto-injector and pre-filled syringe formats.
Market Restraints
- Aluminum and Resin Cost Volatility:Fluctuating petroleum-derived feedstock prices and aluminum tariff exposure are compressing margin structures for blister foil and rigid container producers.
- Glass Tubing Supply Concentration:Borosilicate glass tubing capacity concentrates among a limited supplier base in Germany and India, creating vulnerability for vial and ampoule manufacturers.
- Legacy Line Retrofit Friction:Existing packaging infrastructure requires substantial modification to accommodate aggregation hardware and vision systems, extending depreciation timelines.
Strategic Opportunities
- India Domestic Pharma Growth:CDSCO regulatory alignment with international standards is unlocking contract manufacturing opportunities for export-compliant packaging formats serving regulated markets.
- Sustainable Material Innovation:Bio-based barrier films and recyclable mono-material structures are capturing preference among European brand owners responding to EU Green Deal packaging waste directives.
- Home Healthcare Distribution:Direct-to-patient channels for chronic disease management are creating demand for patient-centric compliance packaging with integrated digital adherence monitoring.
Industry Challenges
- Serialization Engineering Talent Scarcity:Packaging line integration with cloud-based verification systems requires scarce expertise in pharmaceutical track-and-trace architecture.
- Multi-Jurisdiction Compliance Complexity:Divergent authentication timelines between FDA DSCSA and Health Canada requirements are fragmenting platform standardization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Packaging Market |
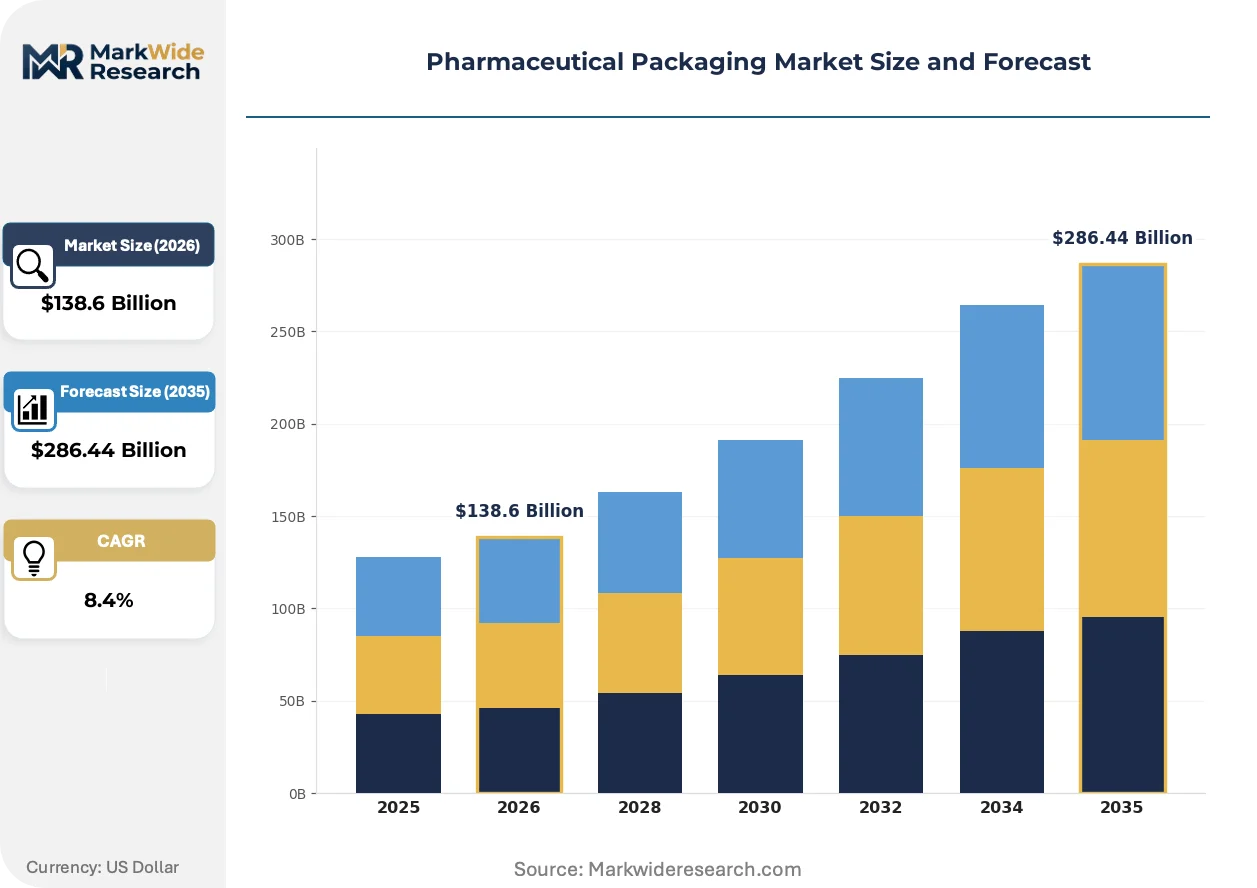
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $286.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Vials, Ampoules, Bottles Material: Glass, Plastic, Aluminum, Composite Form: Solid, Liquid, Semi-Solid, Gas End User: Pharmacies, Hospitals, Clinics, Contract Packagers |
| Companies Covered | Amcor plc, Gerresheimer AG, West Pharmaceutical Services, Inc., AptarGroup, Inc., Schott AG, Becton Dickinson, Berry Global, SGD Pharma, Comar, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Packaging Market Emerging Trajectories
Active and intelligent packaging systems are electrifying competitive positioning, embedding sensors and connectivity into primary and secondary formats that transcend passive containment functions.
Printed electronics with near-field communication and time-temperature indicators is electrifying cold-chain assurance capabilities. Biologics distributors in Germany and the United States are deploying these formats to capture real-time thermal excursion data. The technology is electrifying insurance and liability structures across high-value shipment categories.
The FDA Drug Supply Chain Security Act is mandating interoperable electronic systems for prescription drug traceability. Manufacturers must implement unit-level serialization with verification routing by November 2024 for compliance readiness. Oral solid dose producers with US market exposure are accelerating line aggregation investments to avoid distribution lockouts.
Self-administration trends are reshaping primary packaging specifications for injectable therapies. Pre-filled syringes and auto-injectors are displacing traditional vial-and-needle formats in rheumatology and diabetes care. Germany and the United States represent the most concentrated demand for these patient-centric delivery systems.
Pharmaceutical Packaging Market Segmentation
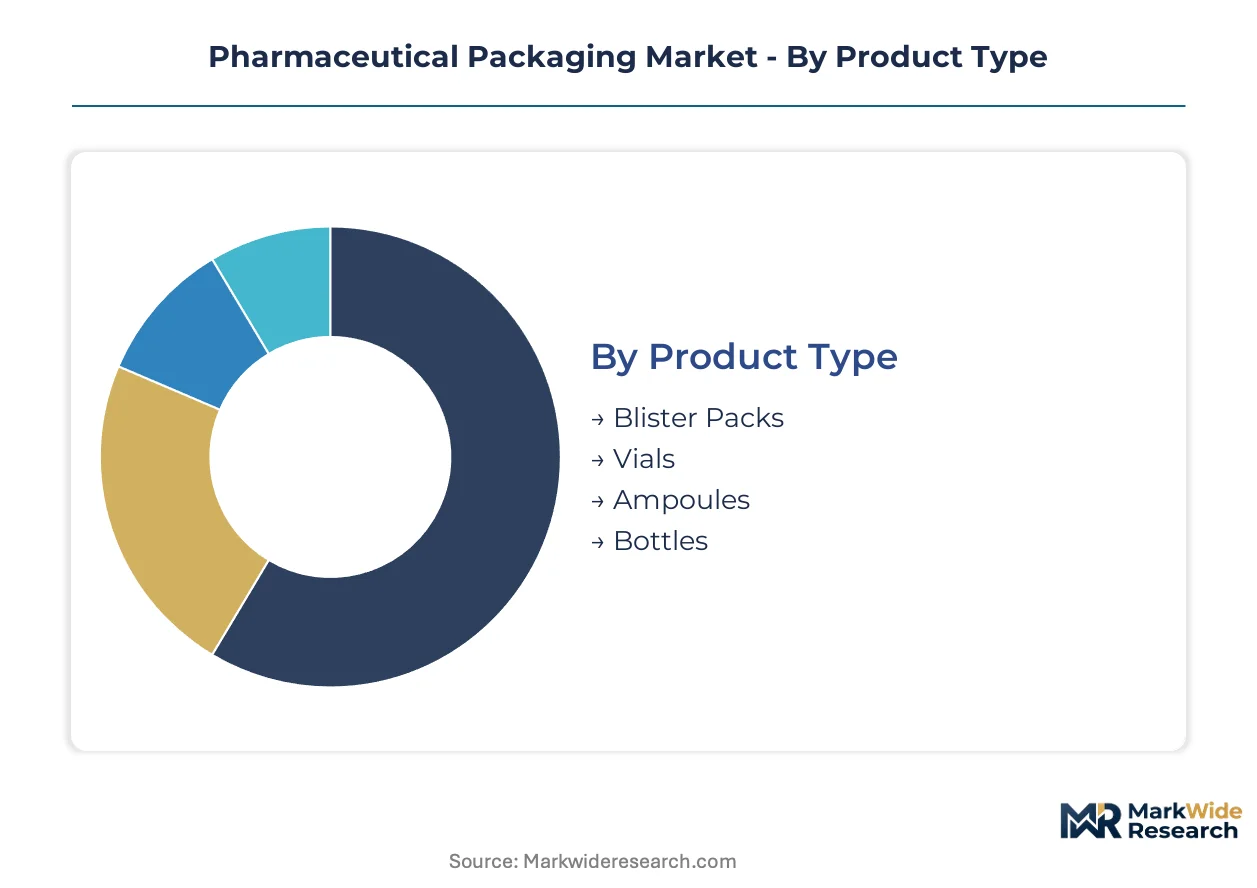
Packaging specification differences across product types, materials, and end-use channels determine capital allocation priorities for line equipment and regulatory compliance infrastructure. Segment boundaries are hardening as FDA DSCSA and EU MDR traceability mandates force format-specific serialization investments.
Product Type:
Capital intensity varies sharply across primary packaging formats, with cold-chain-validated formats demanding substantially higher upfront line investment than ambient-stable alternatives.
- Blister Packs:Thermoformed or cold-formed cavities sealed with lidding foil, specified for oxygen transmission rates below 0.1 cc/m²/day in tropical markets. Demand concentrates in retail pharmacy channels across Germany and the United States, where unit-dose compliance packaging commands premium positioning and drives foil-laminate specification upgrades.
- Vials:Borosilicate glass or cyclic olefin polymer containers for parenteral administration, requiring validated sterile filling lines and elastomeric closure integrity testing. Biologics manufacturers in India and Germany are expanding borosilicate tubing orders as CDSCO alignment with international standards unlocks export-compliant capacity.
- Ampoules:Single-dose glass containers with score-break or OPC (one-point-cut) neck designs, produced on dedicated forming lines with flame-sealing stations.
- Bottles:HDPE or PET containers for oral liquids and solid doses, molded with child-resistant closures meeting torque specifications measured in inch-pounds.
Blister packs absorb the bulk of installed capacity; vials are expanding most quickly.
Material:
Raw material selection governs barrier performance, break resistance, and recyclability positioning under EU Green Deal packaging waste directives.
- Glass:Borosilicate and soda-lime compositions for primary containment, specified for chemical durability and extractables testing. Schott AG and Corning Inc. concentrate borosilicate tubing supply in Germany and India, creating vulnerability for vial and ampoule manufacturers exposed to tariff and logistics friction.
- Plastic:Cyclic olefin polymers, multilayer polypropylene, and PET resins displacing glass in parenteral applications where break resistance and design flexibility enable auto-injector integration.
- Aluminum:Cold-rolled foil for blister lidding and rigid containers, with cost structures tied to LME pricing and tariff exposure.
- Composite:Multi-layer structures combining polymer, foil, and paper substrates for high-barrier applications requiring moisture and oxygen protection.
Glass retains the largest share of high-value biologics containment; cyclic olefin polymers are climbing the fastest on self-administration device integration.
Form:
Dosage form determines secondary packaging requirements for moisture protection, light blocking, and child resistance across distribution channels.
- Solid:Tablets and capsules requiring desiccant integration and light-protective secondary cartons for stability maintenance in tropical corridors.
- Liquid:Solutions and suspensions demanding seal integrity verification and graduated dosing accessories for pediatric and geriatric compliance.
- Semi-Solid:Creams, ointments, and gels packaged in tubes or jars with barrier coatings to prevent API migration into container walls.
- Gas:Inhalation products requiring pressure-resistant aluminum canisters with metered-dose valve systems.
Solid dose formats dominate volume throughput; liquid formulations are gaining share fastest on biologics pipeline expansion.
End User:
Channel-specific packaging requirements diverge on serialization depth, lot size flexibility, and direct-to-patient delivery capabilities.
- Pharmacies:Retail and mail-order dispensers requiring unit-dose compliance packaging with integrated digital adherence monitoring for chronic disease management programs.
- Hospitals:Acute care facilities demanding bulk sterile packaging with barcode medication administration compatibility and waste-minimizing designs.
- Clinics:Outpatient settings requiring mid-volume formats with simplified opening features for elderly patient populations.
- Contract Packagers:CDMOs and packaging service providers operating multi-client lines requiring rapid format changeover and aggregation hardware for DSCSA compliance.
Pharmacy channels command the largest packaging volume; contract packagers are expanding most quickly on biopharma outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and India while consumption concentrates in the United States and Western Europe, creating transatlantic and Asia-Europe trade corridors for temperature-assured packaging formats.
United States
FDA DSCSA serialization deadlines and biologics cold-chain expansion are driving packaging line investments. The Drug Supply Chain Security Act mandates interoperable electronic traceability systems for prescription drugs. New Jersey and Massachusetts pharmaceutical clusters are deploying aggregation hardware to synchronize compliance with verification routing requirements.
Germany
EU MDR traceability mandates and sustainable packaging directives are reshaping specification requirements. The European Medical Device Regulation compels tamper-evident features and unit-level serialization for high-risk dosage forms. Bavaria's glass tubing and pharmaceutical packaging corridor concentrates borosilicate capacity serving European biologics manufacturers.
India
CDSCO regulatory alignment with international standards is unlocking contract manufacturing for export markets. The Central Drugs Standard Control Organization harmonization enables packaging formats compliant with FDA and EMA requirements. Gujarat and Maharashtra pharmaceutical manufacturing zones are expanding cold-chain validation capabilities for biologics export.
China
Domestic biologics pipeline growth and NMPA serialization requirements are accelerating packaging infrastructure deployment. The National Medical Products Administration mandates traceability systems aligned with international standards. Yangtze River Delta pharmaceutical clusters are integrating cyclic olefin polymer capacity for auto-injector and pre-filled syringe formats.
Japan
PMDA quality standards and aging demographics are elevating patient-centric packaging specifications. The Pharmaceuticals and Medical Devices Agency maintains stringent barrier performance and extractables testing requirements. Kanto region pharmaceutical manufacturers are adopting compliance packaging with integrated digital adherence monitoring for chronic disease management.
Pharmaceutical Packaging Market Vendor Landscape
Top-tier vendors anchor premium barrier film and glass primary packaging, while mid-cap specialists occupy cyclic olefin polymer and sustainable material niches. The structure stratifies across three tiers: integrated multinationals with polymer science capabilities, regional glass tubing and conversion specialists, and contract packaging service providers with multi-client line flexibility. Two dominant competitive moves are reshaping positioning: backward integration into raw material production to secure resin and aluminum supply, and technology licensing partnerships for printed electronics and authentication layers.
Within the integrated packaging tier, Amcor plc and Gerresheimer AG exemplify divergent material strategies—flexible polymer systems versus glass primary containment. West Pharmaceutical Services, Inc. occupies a position bridging drug delivery and packaging integration. These three entities represent archetypes that smaller specialists emulate: polymer science scale, tubular glass concentration, and delivery system convergence.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| West Pharmaceutical Services, Inc. |
| AptarGroup, Inc. |
| Schott AG |
| Becton Dickinson |
| Berry Global |
| SGD Pharma |
| Comar, LLC |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum pricing cascades through pharmaceutical packaging supply chains, compressing margin structures for blister foil producers while concentrating pricing power among integrated resin compounders with captive petroleum-derived feedstock access.
Pricing Analysis
Margin tightening in standard-grade blister packaging reflects LME aluminum volatility and petroleum resin cost swings that compound tariff exposure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated serialization-ready formats from commodity ambient-stable alternatives. Cost-down pressure on economy-tier converters accelerates because CDSCO-aligned Indian contract manufacturers are capturing volume with export-compliant capacity. Hospital procurement committees exhibit lowest price sensitivity due to barcode medication administration compatibility requirements, while retail pharmacy channels drive hardest bargain on unit-dose compliance formats.
Supply Chain Analysis
Reverse-logistics flows for temperature-assured pharmaceutical shipments remain underdeveloped, with thermal shipper refurbishment and phase-change material recovery capturing minimal value from Germany-to-United States biologics corridors. Borosilicate glass tubing supply concentrates in Germany and India, creating single-source vulnerability for vial and ampoule manufacturers exposed to logistics friction. Raw material dependencies rest on Saudi petroleum feedstocks for cyclic olefin polymer production and Australian bauxite for aluminum foil conversion. Distribution runs through temperature-validated third-party logistics networks with 2-8°C chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical packaging is consolidating around serialization-capable incumbents as FDA DSCSA and EU MDR compliance deadlines force sub-scale converters into distressed exits.
For Market Incumbents: Deepen backward integration into borosilicate tubing production to neutralize Schott AG and Corning Inc. supply concentration risks in Germany and India. Expand cyclic olefin polymer compounding capacity in Bavaria to capture auto-injector format migration from glass. Serialization engineering talent scarcity threatens line integration timelines; acquire track-and-trace architecture specialists before verification routing deadlines lock in vendor relationships. For New Entrants and Emerging Players: Mid-tier Indian CDMOs represent the most penetrable buyer archetype as CDSCO alignment unlocks FDA and EMA export pathways. Target sustainable material innovation for European brand owners responding to EU Green Deal packaging waste directives. Establish technology licensing partnerships for printed electronics with near-field communication capabilities rather than competing on commodity barrier film conversion. For Investors and Strategic Acquirers: Distressed-cycle entries favor cyclic olefin polymer specialists with auto-injector device integration capabilities in China's Yangtze River Delta. Five-to-ten year viability hinges on capturing biologics pipeline expansion rather than oral solid dose commoditization. Monitor FDA DSCSA enforcement actions against non-compliant distributors as inflection indicator for serialization hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive supply from Germany and India neutralizes glass concentration vulnerability for vial manufacturers. |
| Cyclic Olefin Polymer Capacity Expansion | Break-resistant resin capture auto-injector and pre-filled syringe format migration from traditional glass containment. |
| Printed Electronics Technology Licensing | Near-field communication and time-temperature indicators electrify cold-chain assurance for high-value biologics shipments. |
| Serialization Hardware Aggregation Investment | Cloud-verified authentication layers synchronize FDA DSCSA compliance with EU MDR traceability mandates. |
| Sustainable Material Innovation Partnership | Bio-based barrier films capture preference among European brand owners under EU Green Deal directives. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging line engineers, regulatory affairs leads at CDMOs, hospital procurement managers, and pharmaceutical quality directors. FDA DSCSA guidance documents, EMA MDR technical specifications, CDSCO harmonization circulars, and borosilicate glass import manifests provided validation benchmarks. Bottom-up capacity modeling across tubular glass furnaces and polymer extrusion lines triangulated against top-down pharmaceutical production volume estimates.
Granularity-level modeling distinguished primary packaging formats by cold-chain validation requirements, serialization depth, and material barrier performance across the projection horizon. Segmentation dimensions included product type, material composition, dosage form, and end-user channel with regional regulatory cluster overlays. CAGRs derived from capacity expansion announcements, line investment disclosures, and biologics pipeline progression through clinical stages. Forecast inputs incorporated EU MDR enforcement timelines and FDA verification routing readiness assessments.
Revisions become necessary when aluminum tariff regimes shift, borosilicate tubing supply disruptions materialize, or serialization deadline extensions alter capital deployment patterns. Forecasts reflect assumptions about regulatory harmonization pace and cold-chain infrastructure buildout rates. Practitioners should monitor FDA DSCSA enforcement priorities and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market