
 Pharmaceutical Unit Dose Packaging Market | 2026-2036
Pharmaceutical Unit Dose Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Unit Dose Packaging Market Analysis
Child-resistant and senior-friendly specification tiers is collapsing the gap between premium safety features and standard unit dose formats. Gerresheimer AG leverages its glass and polymer expertise to dominate high-barrier vial segments for biologics. Amcor plc sustains broad geographic manufacturing scale across blister and pouch formats. West Pharmaceutical Services Inc. differentiates through integrated delivery system design that extends beyond primary packaging into administration.
Pharmaceutical unit dose packaging denotes individually sealed, single-administration containers—typically blister cavities, strip pouches, or pre-filled vials—engineered with precise barrier properties against moisture, oxygen, and light to maintain drug stability through end-user dispensing. Its core commercial purpose centers on eliminating dosing errors, ensuring tamper evidence, and enabling full traceability from manufacturer to patient bedside. Blister packs occupy the largest volume share due to decades of tooling amortization and universal pharmacy compatibility, while aseptic packaging technology commands the fastest expansion as sterile biologic and cell therapy portfolios multiply. Cold forming among material processes captures concentrated margin pools where aluminum-laminate structures protect highly sensitive moisture-critical formulations.
The FDA enforces unit dose labeling and child-resistant standards through 21 CFR packaging guidelines, while the EMA's EU MDR imposes Unique Device Identification on dose-delivery systems entering European markets. Health Canada's PMRA aligns with FDA serialization timelines, tightening North American compliance convergence for cross-border suppliers. Stakeholders must monitor evolving pharmacopeial barrier testing protocols and decide whether to absorb validation costs in-house or outsource to contract packaging partners with established regulatory dossiers.
Market Dynamics
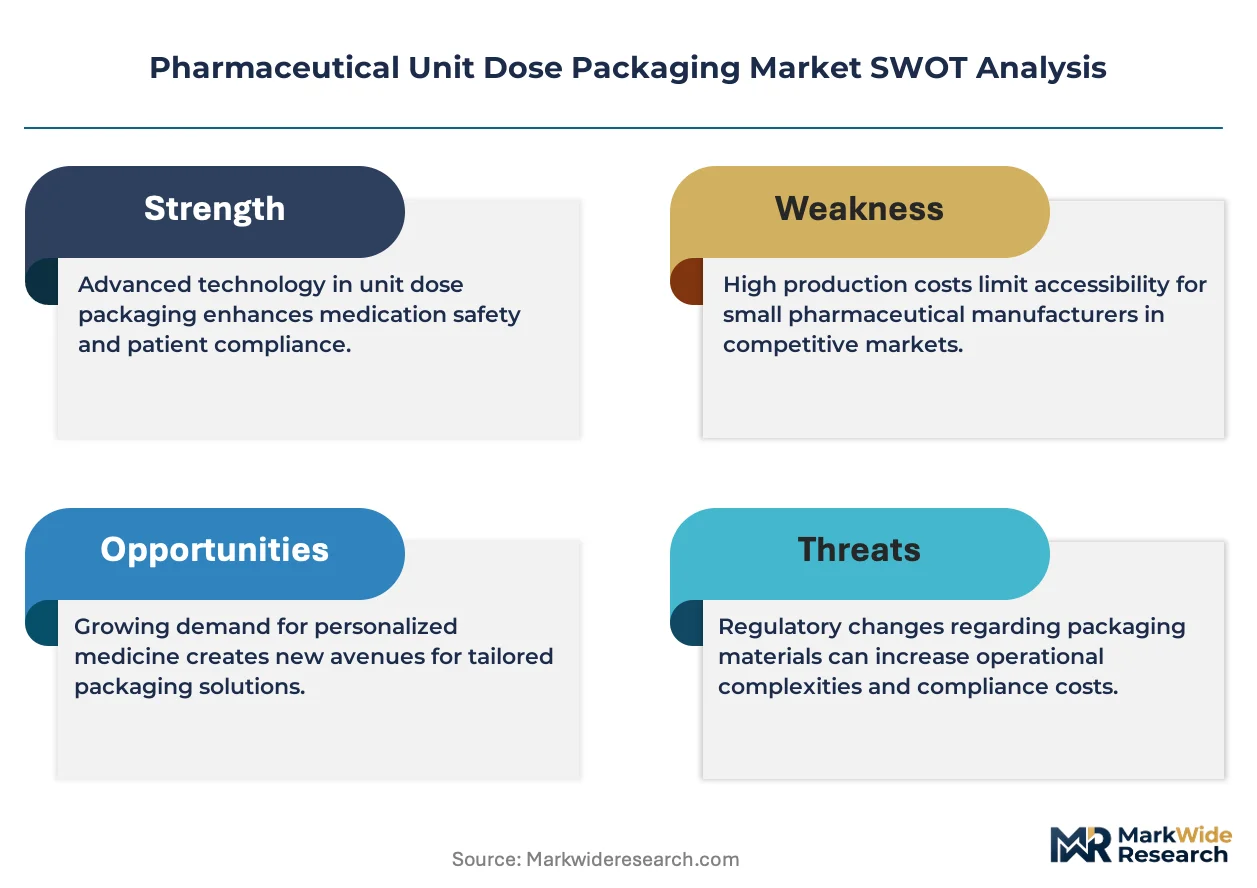
Serialization mandates from FDA and EU MDR are forcing pharmaceutical manufacturers to rebuild packaging lines with integrated track-and-trace infrastructure, compressing supplier selection criteria toward regulatory dossier depth rather than unit cost alone.
Growth Catalysts
- Biologics proliferation:Cell therapy and mRNA portfolios require aseptic unit dose formats with validated barrier integrity, pulling investment toward cold-form aluminum-laminate structures.
- EU MDR Unique Device Identification:The European mandate imposes full traceability on dose-delivery systems, compelling packaging suppliers to pre-validate serialization-ready formats.
- Germany:Hospital pharmacy consolidation in Bavaria and North Rhine-Westphalia is standardizing unit dose procurement across integrated delivery networks.
Market Restraints
- Aluminum-laminate supply concentration:Cold-form barrier substrates depend on a narrow base of European metallized film converters, exposing buyers to input volatility.
- 21 CFR validation timelines:FDA packaging guideline compliance requires 18-24 month stability protocols, freezing format selection early in drug development.
- Pre-filled syringe substitution:Parenteral biologics are migrating toward injection devices that bypass traditional blister and pouch unit dose formats entirely.
Strategic Opportunities
- Japan's PMDA serialization alignment:The regulator's 2025 traceability deadline creates first-mover advantage for suppliers with existing EU MDR dossiers.
- Oral solid dosage in India:Domestic generic manufacturers are retrofitting lines for export-compliant unit dose formats to access US and EU tender markets.
- Smart packaging convergence:Integration of printed electronics with cold-form blisters enables real-time cold chain monitoring for temperature-critical biologics.
Industry Challenges
- Serialization engineering talent scarcity:Packaging line integration with Level 3/4 traceability software requires hybrid mechanical-IT skill sets that contract packagers struggle to staff.
- Legacy ERP integration:Hospital pharmacy inventory systems often lack API connectivity to unit dose dispensing cabinets, forcing manual reconciliation workflows.
- Multi-site validation burden:Global pharmaceutical firms must replicate FDA 21 CFR packaging studies across manufacturing sites in Germany, the United States, and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Unit Dose Packaging Market |
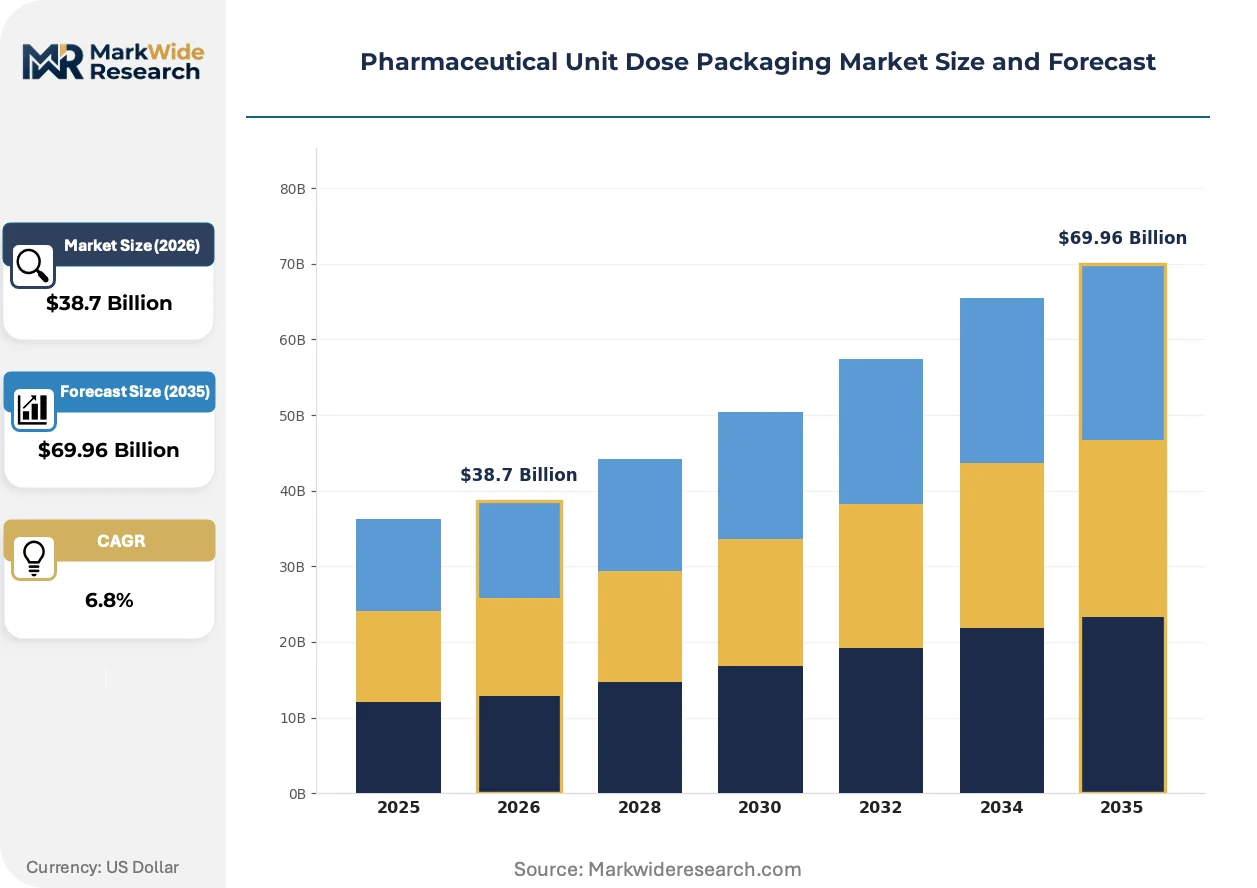
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Pouches, Bottles, Vials End User: Hospitals, Pharmacies, Clinics, Nursing Homes Material: Plastic, Aluminum, Glass, Paper Technology: Aseptic Packaging, Cold Forming, Active Packaging, Tamper-Evident |
| Companies Covered | Amcor plc, Gerresheimer AG, West Pharmaceutical Services Inc., Schott AG, Berry Global Inc., Stevanato Group, Becton, Dickinson and Company, Catalent Inc., AptarGroup Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Unit Dose Packaging Market Emerging Trajectories
Active pharmaceutical ingredient sensitivity is pushing barrier engineering toward material science frontiers, while regulatory convergence is standardizing what were once regional format preferences.
Printed electronics embedded in cold-form blister lidding is fragmenting the traditional division between primary packaging and diagnostic devices. Biologic manufacturers in Basel and Boston are piloting NFC-enabled blisters that log temperature excursions at the cavity level. This capability is fragmenting supplier tiers, separating metallized film converters with in-house printed electronics capability from commodity blister suppliers.
EU MDR's Unique Device Identification mandate is collapsing the grandfathering window for legacy packaging formats. Sterile barrier systems entering European markets must now carry device-level traceability, not just batch codes. Pre-filled vials and aseptic bags for cell therapies face the steepest compliance climb, with Swissmedic and TGA expected to mirror EMA requirements within 24 months.
Hospital pharmacy buying committees are consolidating supplier rosters to reduce qualification overhead. Integrated delivery networks in Texas and California now mandate single-source unit dose contracts spanning oral solids, injectables, and oncology kits. This concentration is visible most acutely in US health systems with captive specialty pharmacies, where formulary alignment with packaging format standardization reduces bedside dispensing errors.
Pharmaceutical Unit Dose Packaging Market Segmentation
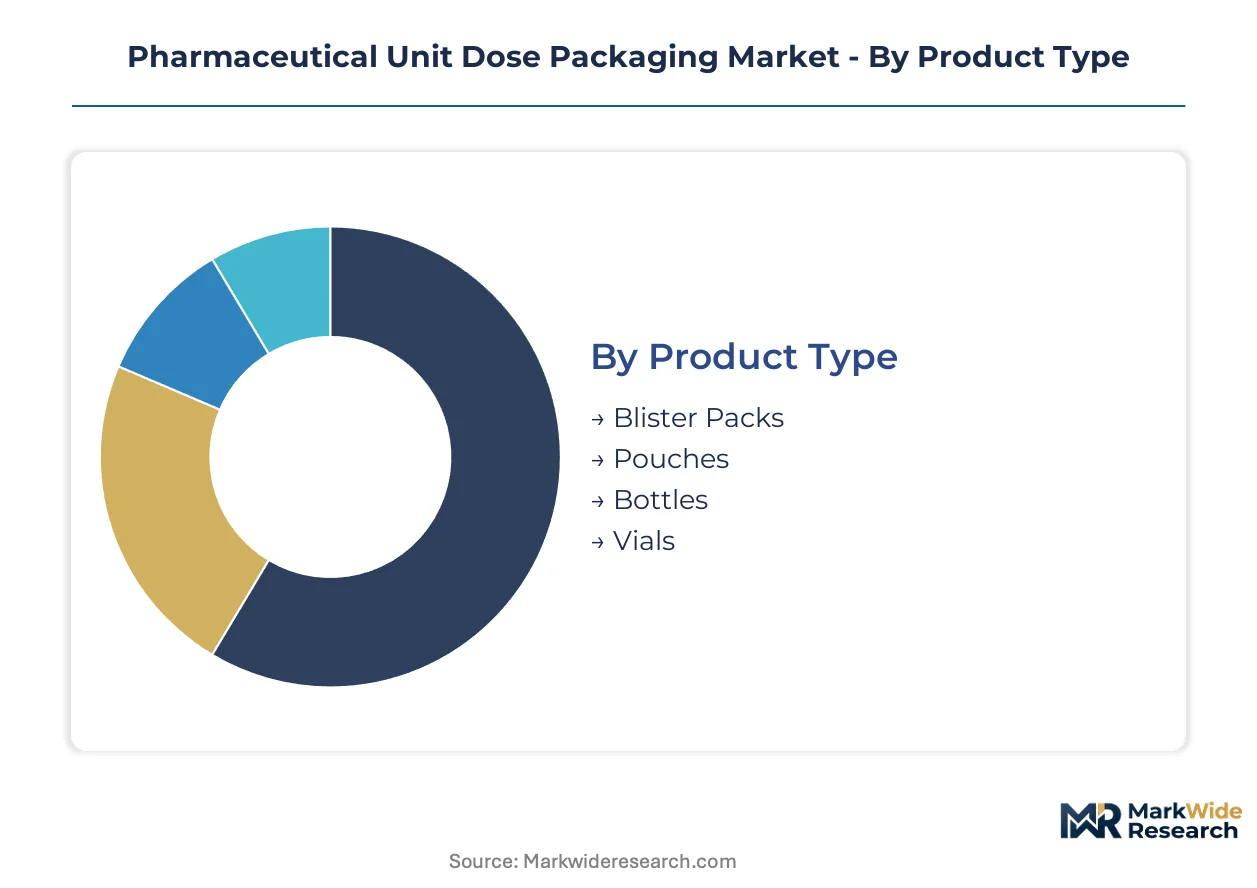
Segmentation in pharmaceutical unit dose packaging reveals how substitution pressures and regulatory mandates reshape competitive positioning across formats. Each dimension—product, end user, material, and technology—carries distinct margin profiles and compliance burdens that determine supplier selection criteria.
Product Type:
Pre-filled syringes and auto-injectors exert the strongest substitution pressure on traditional unit dose formats, particularly for parenteral biologics where administration convenience outweighs packaging cost.
- Blister Packs:Multi-cavity thermoformed or cold-form structures with lidding foil barriers dominate oral solid dosage. Hospital pharmacies in Germany and the United States specify blister formats for automated dispensing cabinet compatibility, though tooling amortization cycles now extend to 7-10 years.
- Pouches:Strip-style flexible laminates with resealable or tear-notch features serve powder sachets and liquid unit doses. Demand concentrates in Japan where PMDA serialization requirements favor compact formats with flat surface area for 2D code printing.
- Bottles:HDPE or PET containers with induction-sealed closures retain utility for high-volume generics. Indian contract manufacturers retrofit bottle lines for export markets.
- Vials:Glass or polymer single-dose containers with elastomeric closures protect sterile injectables. Swissmedic-aligned facilities in Basel drive specification for cell therapy applications.
Blister packs retain volume leadership; aseptic-ready vials hold the steepest expansion curve.
End User:
Procurement concentration varies sharply by care setting, with integrated delivery networks imposing format standardization that smaller independent buyers cannot match.
- Hospitals:Central pharmacy operations with automated dispensing infrastructure drive demand for barcoded, unit-of-use formats. Texas and California health systems mandate single-source contracts spanning multiple dosage forms.
- Pharmacies:Retail and specialty pharmacies prioritize patient adherence packaging with calendarized blister cards. Community pharmacies in Bavaria consolidate purchasing through regional cooperatives.
- Clinics:Ambulatory infusion centers require pre-mixed, ready-to-administer formats that minimize compounding steps. Oncology clinics in Boston specify tamper-evident pouches for cytotoxic agents.
- Nursing Homes:Long-term care facilities favor medication adherence packaging with senior-friendly opening features. CMS reimbursement policies influence format selection in US skilled nursing facilities.
Hospitals command the largest procurement volumes; specialty pharmacy channels expand most quickly.
Material:
Barrier performance requirements and sustainability pressures are fragmenting material selection criteria across therapeutic categories.
- Plastic:Multi-layer coextruded films and rigid PVC or PP structures offer cost-efficient barrier properties for moisture-stable actives. Polymer innovation centers in Germany develop bio-based alternatives.
- Aluminum:Cold-form laminates with aluminum oxide barriers provide near-zero moisture vapor transmission for hygroscopic formulations. European metallized film converters concentrate supply.
- Glass:Borosilicate and treated soda-lime vials deliver inert contact surfaces for biologics. Type I glass demand rises in Basel and Boston cell therapy clusters.
- Paper:Fiber-based substrates with polymer barriers serve sustainable packaging initiatives. Japanese pharmaceutical manufacturers pilot paper blister replacements.
Aluminum-laminate structures capture premium margins; polymer formats dominate volume.
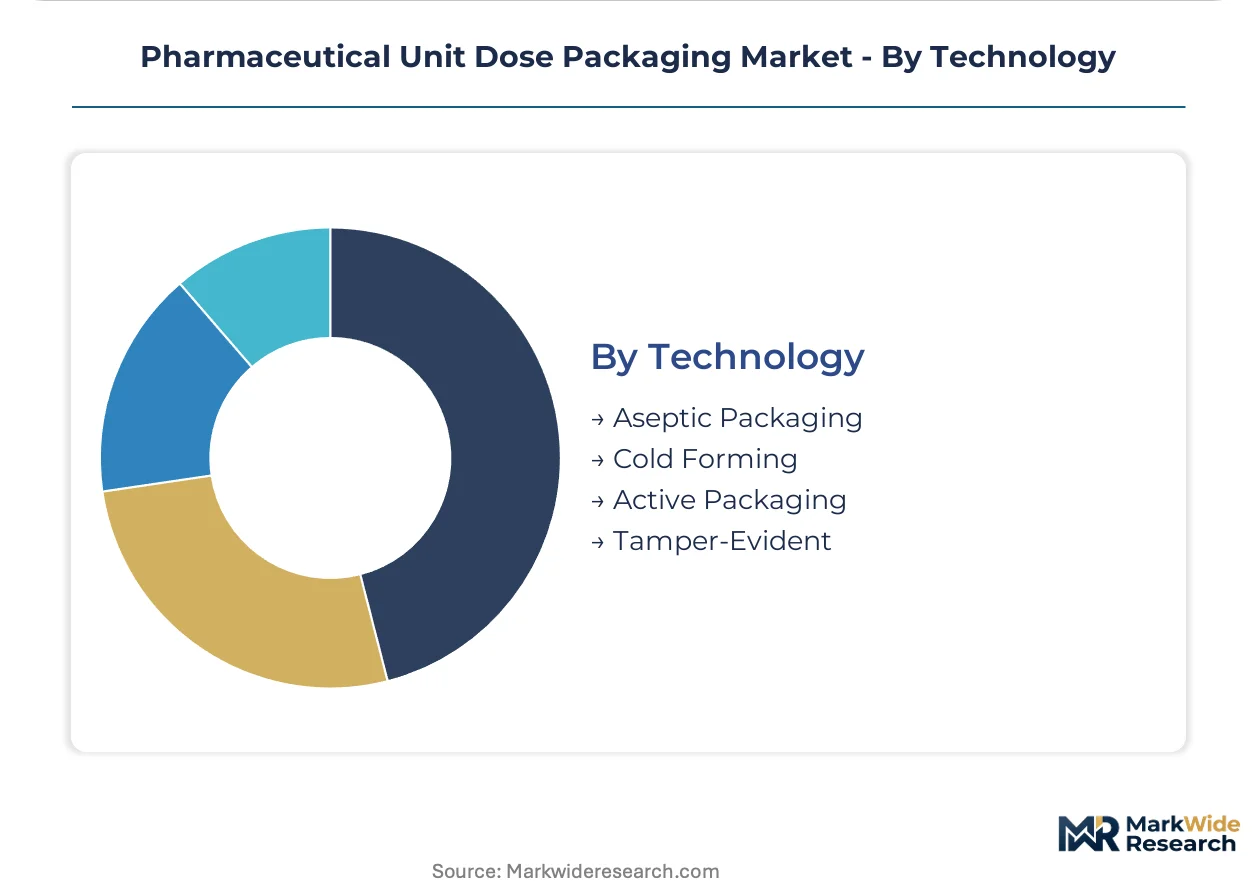
Technology:
Regulatory traceability mandates and biologic sensitivity requirements are elevating technology selection above unit cost considerations.
- Aseptic Packaging:Sterile barrier systems with validated fill-finish integration protect cell therapies and mRNA products. FDA 21 CFR compliance timelines extend 18-24 months.
- Cold Forming:Aluminum-laminate deep-draw processes create cavity-level moisture barriers without heating. Bavarian hospital pharmacies specify cold-form for critical care medications.
- Active Packaging:Desiccant-integrated or oxygen-scavenging systems extend shelf life for sensitive actives. Indian generic exporters adopt active formats for US tender markets.
- Tamper-Evident:Break-away caps, holographic seals, and frangible membranes satisfy FDA and EMA safety requirements. California health systems mandate tamper-evidence across all controlled substances.
Aseptic packaging climbs fastest; tamper-evident features approach universal requirement status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pharmaceutical unit dose packaging tilt toward regulatory compliance premiums rather than commodity arbitrage. Germany and the United States absorb the highest per-unit import values for serialized formats, while India and China supply volume generics through contract manufacturing networks.
United States
FDA 21 CFR packaging guidelines and DSCSA serialization deadlines drive hospital pharmacy automation investments. Texas and California health systems mandate single-source unit dose contracts spanning multiple dosage forms. The Greater Boston cell therapy cluster demands aseptic vial formats with validated cold-chain integrity.
Germany
Bavarian hospital pharmacy consolidation standardizes procurement across integrated delivery networks. The EU MDR Unique Device Identification mandate accelerates compliant packaging investments for dose-delivery systems. Cold-form aluminum-laminate production concentrates in Baden-Württemberg metallized film converter facilities.
Japan
PMDA's 2025 traceability deadline creates first-mover advantage for suppliers with existing EU MDR dossiers. Compact pouch formats with flat surface area dominate 2D code printing requirements. The Kanto region around Tokyo hosts pharmaceutical manufacturers piloting NFC-enabled blister technologies.
India
Domestic generic manufacturers retrofit lines for export-compliant unit dose formats to access US and EU tender markets. CDSCO alignment with FDA serialization timelines tightens compliance convergence for cross-border suppliers. Contract packaging clusters in Maharashtra and Gujarat specialize in active desiccant-integrated formats.
Switzerland
Swissmedic sterile barrier requirements for cell therapies drive specification for Type I glass vials and aseptic bags. Basel biologic manufacturers pilot printed electronics integration for cavity-level temperature monitoring. The country's national pharmaceutical regulator is expected to mirror EMA device-level traceability requirements within 24 months.
Pharmaceutical Unit Dose Packaging Market Vendor Landscape
Listed leaders compete with private specialists across regulatory dossier depth rather than unit cost alone. The supplier base stratifies into three tiers: diversified materials conglomerates with broad geographic manufacturing scale, glass and polymer specialists with barrier engineering expertise, and integrated delivery system designers extending beyond primary packaging. Consolidation pressures favor acquisition of contract packagers with established FDA and EMA validation histories over greenfield capacity expansion.
Among diversified packaging conglomerates, Amcor plc and Berry Global Inc. exemplify scale-driven archetypes with multi-format production footprints. Gerresheimer AG and Schott AG occupy positions within the glass-polymer specialist tier, anchoring high-barrier vial segments where material science capabilities determine competitive position. These named entities represent the structural divide between commodity volume suppliers and premium barrier technology providers.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| West Pharmaceutical Services Inc. |
| Schott AG |
| Berry Global Inc. |
| Stevanato Group |
| Becton, Dickinson and Company |
| Catalent Inc. |
| AptarGroup Inc. |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month FDA 21 CFR validation timelines compress supplier selection windows and concentrate pricing power with contract packagers holding established regulatory dossiers in Germany, the United States, and Japan. Hospital pharmacy buying committees exploit this scarcity by consolidating single-source contracts across oral solids, injectables, and oncology kits, forcing tiered pricing separation between serialization-ready formats and legacy blister structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in pharmaceutical unit dose packaging. Cold-form aluminum-laminate formats with integrated NFC-enabled temperature monitoring command premium positioning against commodity thermoformed blisters. Price differentiation rests on FDA and EU MDR certification depth plus geographic manufacturing proximity to Basel and Boston cell therapy clusters. Cost compression in standard blister tiers intensifies because Indian contract manufacturers retrofit lines for export-compliant formats. Retail and specialty pharmacies exhibit highest price sensitivity, while integrated delivery networks in Texas and California prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for metallized film converters dependent on Asian polymer feedstocks. Supply concentrates in Baden-Württemberg for aluminum-laminate cold-form substrates, Maharashtra and Gujarat for active desiccant-integrated formats, and Bavaria for serialization-ready pouch production. Raw material dependencies encompass aluminum oxide barrier films, multi-layer coextruded polymers, and Type I borosilicate glass. Single-source vulnerability pervades European metallized film conversion capacity for moisture-critical formulations. Distribution runs through hospital pharmacy central procurement, regional pharmacy cooperatives, and captive specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid mechanical-IT skill sets for Level 3/4 traceability software integration remain chronically undersupplied across contract packaging networks, constraining serialization line deployment velocity and amplifying acquisition premiums for qualified engineering teams.
For Market Incumbents: Compound regulatory dossier depth by acquiring contract packagers with validated FDA and EMA histories rather than greenfield capacity expansion. Pre-filled syringe substitution threatens traditional blister and pouch volumes for parenteral biologics; defend position by deepening backward integration into printed electronics capability for NFC-enabled cold-form blisters. Prioritize captive supply of metallized film conversion capacity in Baden-Württemberg to secure aluminum-laminate input stability. For New Entrants and Emerging Players: EU MDR dossier fast-track programs offer entry acceleration for suppliers with existing Health Canada PMRA alignments. White-space targets include Japan's PMDA 2025 traceability deadline compliance services and oral solid dosage retrofit opportunities for Indian generic exporters seeking US tender market access. Go-to-market through partnership with Maharashtra contract packaging clusters enables shared validation cost absorption. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capability compounding play because serialization mandates across FDA, EMA, and PMDA jurisdictions create durable moats around validated packaging formats. Acquisition target archetype: mid-cap contract packagers with 18-24 month FDA 21 CFR study completion and established hospital pharmacy single-source contracts. Signal to watch: Swissmedic and TGA adoption of EMA device-level traceability requirements triggering regional qualification surges.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization-Ready Format Pre-Validation | EU MDR Unique Device Identification mandates collapse grandfathering windows for legacy packaging structures. |
| Printed Electronics Integration | NFC-enabled cold-form blisters enable cavity-level temperature monitoring for Basel biologic manufacturers. |
| Backward Integration into Metallized Film | Captive aluminum-laminate supply secures margin pools for moisture-critical formulations in Baden-Württemberg. |
| Hospital System Single-Source Contracting | Texas and California integrated delivery networks consolidate supplier rosters to reduce qualification overhead. |
| Active Desiccant Format Development | Indian generic exporters adopt oxygen-scavenging systems for US tender market shelf-life extension. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital pharmacy procurement managers, regulatory affairs directors at contract packaging organizations, pharmaceutical formulation scientists, and integrated delivery network formulary committees and refined through secondary validation against FDA 21 CFR packaging guideline amendments, EMA MDR implementation guidance documents, PMDA traceability roadmap publications, and hospital pharmacy automation vendor technical specifications. Bottom-up demand modeling from dosage-form-specific packaging consumption combined with top-down pharmaceutical production value triangulation anchored market sizing.
Variance decomposition across product type, material barrier tier, end-user procurement concentration, and regional regulatory cluster segmentation shaped analytical framework development throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate pharmaceutical production forecasts. Forecast inputs encompassed biologics pipeline expansion rates, serialization infrastructure investment cycles, and cold-chain logistics capacity buildouts.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA and EU MDR enforcement continuity and aluminum-laminate supply stability; material deviation would warrant model refresh. Specific risk factors include pre-filled syringe substitution acceleration, metallized film converter consolidation, and legacy ERP integration failures in hospital pharmacy inventory systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market