
 Handheld Induction Cap Sealers Market | 2026-2036
Handheld Induction Cap Sealers Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Induction Cap Sealers Market Foresight
Subscription-based calibration and preventive maintenance is hardening into a standard revenue layer for handheld induction cap sealer vendors. Enercon Industries Corporation leverages its North American service network to anchor long-term contracts with pharmaceutical packaging lines. Lepel Corporation specializes in compact coil designs that dominate portable sealing applications where workspace flexibility matters. Dongguan Sammi Packing Machine Co., Ltd. competes on manufacturing scale, sustaining cost advantages across manual and semi-automatic handheld units shipped to emerging Asian markets.
Handheld induction cap sealers are portable electromagnetic devices that generate localized eddy currents through a conductive foil liner, bonding it to container rims at frequencies typically between 100 kHz and 300 kHz to create hermetic, tamper-evident seals. Their primary purpose is to deliver on-site sealing capability without conveyor infrastructure, serving laboratories, remote production facilities, and quality-control stations where mobility outweighs throughput. The handheld units segment occupies the premium tier of this equipment category, commanding higher margins due to specialized coil engineering and ergonomic design requirements. Electromagnetic technology leads the technology split, while pharmaceutical companies represent the most tightly regulated and fastest-growing end-user pool as traceability rules tighten across drug distribution chains.
FDA container closure integrity guidelines and EMA Annex 1 sterile manufacturing requirements shape product validation protocols, forcing sealer manufacturers to document electromagnetic field consistency and seal reproducibility. ISO 15378 standards for primary packaging materials and USP Chapter 1207 on package integrity testing further constrain design choices, particularly for pharmaceutical-grade handheld systems. Stakeholders must monitor how regional pharmaceutical regulators harmonize electromagnetic emission limits with seal performance benchmarks, as divergence between FDA and EMA technical expectations would fragment certification requirements and complicate cross-border equipment deployment.
Market Dynamics
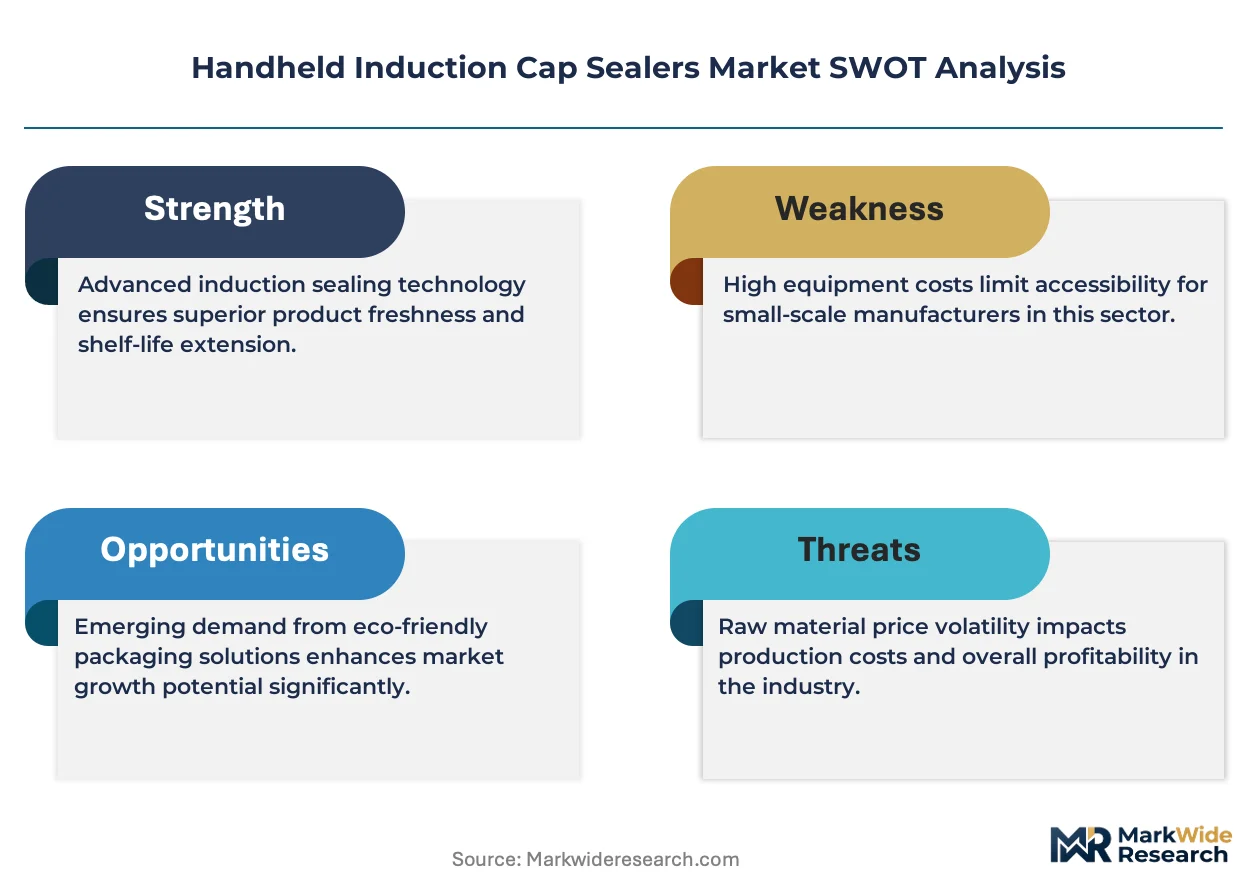
Portable sealing equipment manufacturers face intensifying pressure from FDA container closure integrity guidance, which mandates documented electromagnetic field consistency across distributed production environments and remote quality-control stations.
Growth Catalysts
- EMA Annex 1 sterile manufacturing requirements:Pharmaceutical contract packers in Europe are deploying handheld units to validate seal integrity at decentralized filling sites without fixed conveyor infrastructure.
- Laboratory-scale production:Biotech startups in the United States require mobile sealing capability for clinical trial material preparation where batch volumes preclude automated line investment.
- Copper coil miniaturization:Advances in compact electromagnetic coil engineering enable higher-frequency operation at reduced weight, expanding ergonomic viability for extended manual operation.
Market Restraints
- Specialized ferrite core supply:Concentrated sourcing of high-permeability magnetic materials from East Asian suppliers creates input cost volatility and extended lead times for coil assembly.
- Electromagnetic emission compliance:Divergent FCC Part 18 industrial equipment rules and EU electromagnetic compatibility directives force redundant testing protocols for cross-border equipment deployment.
- Fixed-line throughput economics:Automated conveyor-based induction sealers achieve unit costs below handheld alternatives above 5,000 units per hour, constraining addressable volume in high-throughput pharmaceutical packaging.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO export certification requirements for sterile liquid formulations are driving adoption of documented portable sealing among mid-tier manufacturers in Hyderabad and Ahmedabad clusters.
- Cell and gene therapy manufacturing:Personalized medicine production requires lot-size flexibility that handheld units provide for small-batch autologous therapies at point-of-care facilities.
- Calibration-as-a-service models:Subscription-based preventive maintenance contracts anchored to ISO 17025 accredited metrology services lock in recurring revenue and reduce customer switching.
Industry Challenges
- Electromagnetic field validation expertise:Shortage of technicians capable of documenting eddy current distribution patterns for FDA submission packages extends qualification timelines.
- Legacy serialization integration:Handheld units must interface with established track-and-trace infrastructure without disrupting existing aggregation workflows at contract packaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Induction Cap Sealers Market |
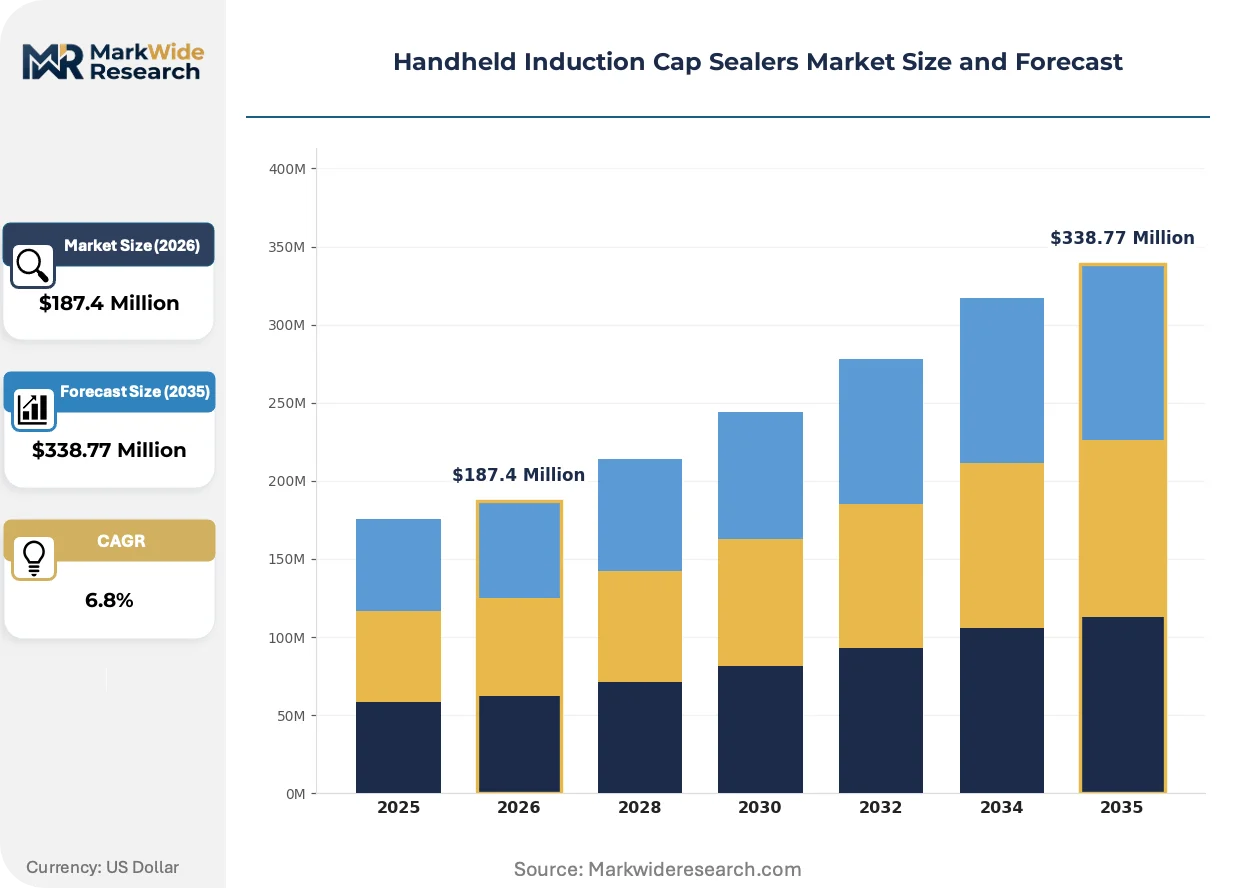
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sealers, Semi-Automatic Sealers, Fully Automatic Sealers, Handheld Units End User: Beverage Industry, Pharmaceutical Companies, Food Processing, Cosmetics Technology: Electromagnetic, Capacitive, High Frequency, Induction Heating Application: Capping, Packaging, Sealing, Quality Control |
| Companies Covered | Enercon Industries Corporation, Pillar Technologies, Lepel Corporation, Relco UK Ltd., Dongguan Sammi Packing Machine Co., Ltd., R-Technologies, The Cary Company, Parle Global, Daiichi Jitsugyo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Induction Cap Sealers Market Shifts & Advancements
Electromagnetic coil engineering and regulatory documentation protocols are converging to reshape competitive requirements, with manufacturers differentiating through validated field consistency rather than throughput specifications alone.
Variable-frequency inverter circuits are automating real-time power adjustment based on container material properties and foil liner thickness. Pharmaceutical quality-control laboratories in Germany and Switzerland are adopting these systems to eliminate manual recalibration between aluminum and polymer container runs. This automation compresses validation documentation burdens and reduces operator-dependent seal variability in multi-product facilities.
REACH restrictions on nickel alloy exposure in workplace environments are accelerating substitution of ferrite-dominant coil designs across European pharmaceutical packaging operations. The regulation forces redesign of legacy copper-nickel coil assemblies and triggers requalification of existing installed bases. Mid-sized contract packers in the Netherlands and Belgium are prioritizing equipment with pre-submitted ECHA compliance dossiers to accelerate procurement cycles.
Equipment leasing with bundled calibration services is displacing outright purchase models among North American biotech startups. These buyers prioritize operational expenditure flexibility over capital deployment, favoring vendors with ISO 17025-accredited service networks. The shift concentrates in Boston and San Diego clusters where venture-funded companies prioritize speed-to-clinic over asset ownership.
Handheld Induction Cap Sealers Market Segmentation
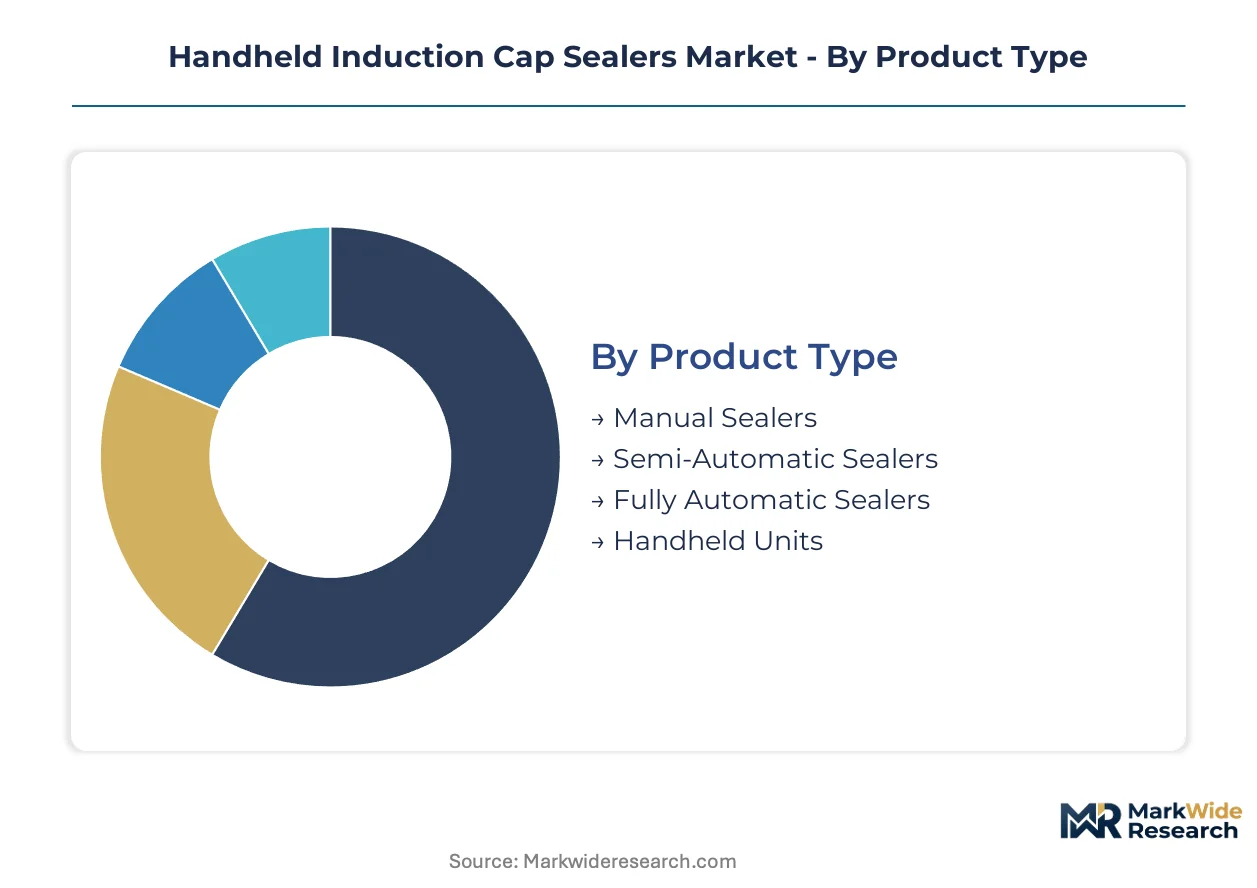
Handheld induction cap sealer procurement varies sharply across segment boundaries, with pharmaceutical-grade configurations demanding ISO 15378 validation and FDA electromagnetic field documentation that manual beverage units rarely require. Certification burdens fragment vendor portfolios and pricing tiers, creating distinct competitive arenas where technical compliance outweighs throughput specifications.
Product Type:
FDA container closure integrity guidance and EMA Annex 1 sterile manufacturing requirements impose tiered validation obligations, with pharmaceutical-bound units facing extensive electromagnetic field consistency documentation while beverage-focused alternatives operate under lighter industrial equipment standards.
- Manual Sealers:Basic lever-actuated units with fixed-frequency coil assemblies generate eddy currents through operator-controlled dwell time. Beverage contract packers in Mexico and Southeast Asia deploy these for low-volume seasonal runs where capital constraints preclude automated infrastructure. These units face minimal regulatory documentation but struggle with seal reproducibility across operator shifts.
- Semi-Automatic Sealers:Pneumatic or foot-pedal assisted systems integrate timer-controlled power delivery with reduced operator fatigue. Mid-sized pharmaceutical manufacturers in India's Hyderabad cluster favor these for clinical trial material preparation where batch documentation requirements outstrip pure manual capabilities but throughput remains below automated line thresholds.
- Fully Automatic Sealers:Conveyor-integrated systems with programmable logic controllers manage continuous sealing operations.
- Handheld Units:Battery or mains-powered portable devices with ergonomic coil housings enable point-of-use sealing without fixed infrastructure.
Manual Sealers sits at the top of the volume ranking, with Handheld Units climbing the fastest.
End User:
End-user concentration determines coil specification, frequency range, and validation depth, with sterile pharmaceutical applications commanding premium electromagnetic engineering that food-grade alternatives rarely justify.
- Pharmaceutical Companies:Tightly regulated manufacturers of liquid medications, vaccines, and biologics require tamper-evident hermetic seals with full batch traceability. FDA container closure integrity guidance and USP Chapter 1207 package integrity testing protocols force documented electromagnetic field mapping for every sealer deployment. Boston and San Diego biotech clusters drive premium-tier procurement for clinical trial material preparation.
- Beverage Industry:Producers of bottled water, juices, and alcoholic drinks prioritize throughput economics over validation depth. These buyers favor lower-frequency operation with simplified foil-polymer bonding for non-sterile applications. Cost pressure from private-label contract packers constrains equipment margin capture in this segment.
- Food Processing:Manufacturers of sauces, dressings, and condiments require moisture-resistant seals without pharmaceutical-grade documentation burdens.
- Cosmetics:Skincare and fragrance packers demand aesthetic seal consistency for premium positioning, with ECHA REACH compliance for nickel alloy exposure shaping European procurement.
Beverage Industry holds the largest installed base, though Pharmaceutical Companies is expanding most quickly as traceability mandates tighten.
Technology:
Technology selection locks in frequency range, coil materials, and regulatory testing protocols, with electromagnetic systems dominating pharmaceutical validation pathways while capacitive alternatives serve cost-sensitive industrial applications.
- Electromagnetic:Eddy current generation through copper or ferrite-core coils at 100-300 kHz bonds aluminum foil liners to container rims. This technology anchors pharmaceutical-grade handheld units due to precise field controllability and extensive FDA validation precedent. Swissmedic and TGA recognition of electromagnetic seal documentation accelerates deployment in Switzerland and Australia.
- Capacitive:Dielectric heating through electrode proximity generates localized thermal bonding without magnetic field generation. Food processing facilities in Brazil's São Paulo state favor these for high-moisture environments where electromagnetic interference with nearby instrumentation creates operational conflicts.
- High Frequency:Operation above 400 kHz enables rapid heating of thin foil liners with reduced thermal penetration into container contents.
- Induction Heating:Direct magnetic coupling between coil and conductive target materials generates resistive heating for specialized metal-capping applications.
Electromagnetic dominates current procurement volumes, with High Frequency gaining share fastest in precision pharmaceutical applications.
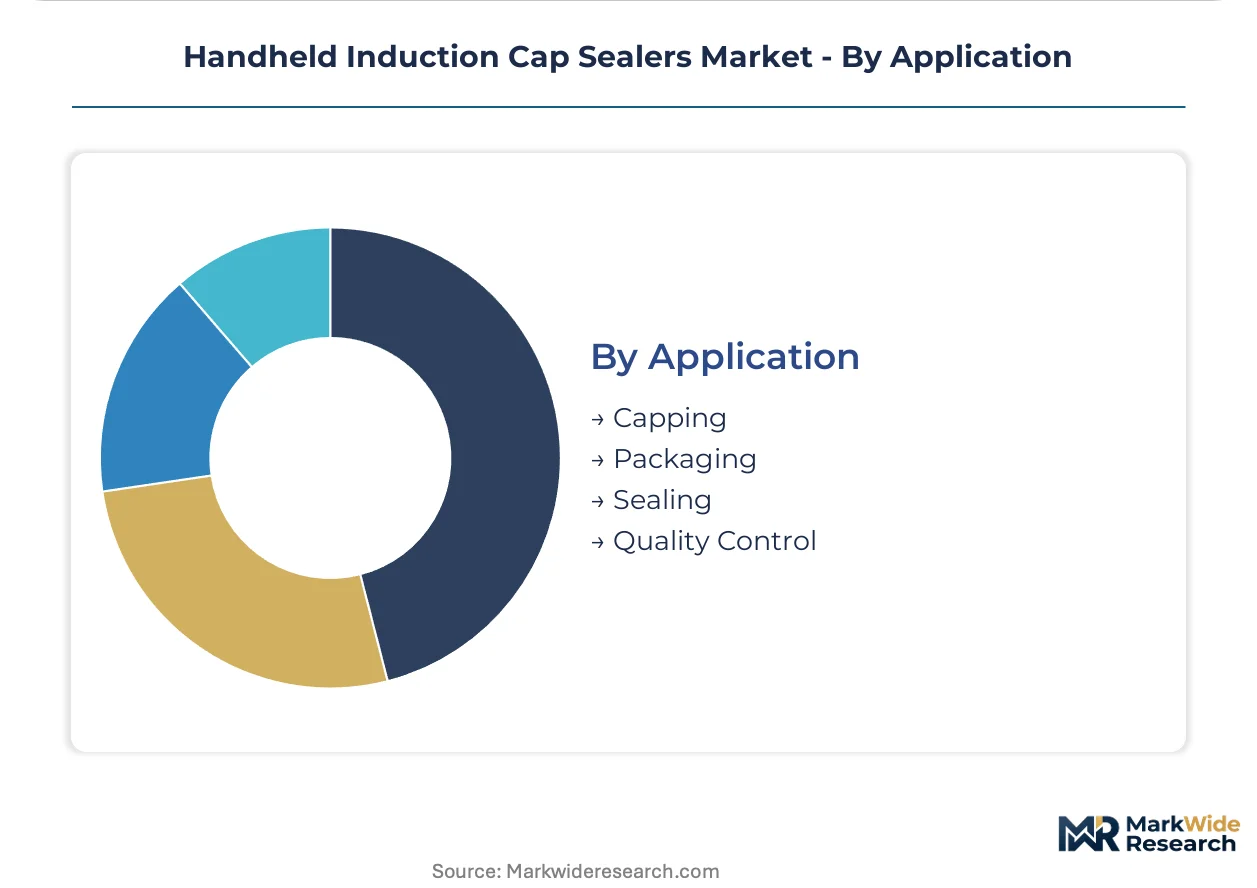
Application:
Application context determines mobility requirements, validation documentation depth, and integration complexity, with quality control stations demanding portable field consistency that high-speed capping lines rarely prioritize.
- Sealing:The core bonding operation between foil liner and container rim, requiring precise power calibration for material thickness variations. Pharmaceutical quality control laboratories in Germany and Switzerland deploy handheld units for seal validation at decentralized filling sites without conveyor infrastructure. Variable-frequency inverter circuits automate real-time adjustment between aluminum and polymer container runs.
- Quality Control:Destructive and non-destructive seal integrity testing, including electromagnetic field mapping for FDA submission packages. CDSCO export certification requirements for sterile liquid formulations drive adoption among Indian pharmaceutical exporters in Ahmedabad clusters. Technician scarcity for eddy current distribution documentation extends qualification timelines.
- Capping:Mechanical closure placement preceding or following induction seal application.
- Packaging:Broader container preparation workflows integrating sealing with labeling, serialization, and aggregation.
Sealing commands the highest equipment deployment volume, with Quality Control showing the steepest expansion trajectory as regulatory documentation burdens intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting portable sealing equipment procurement toward jurisdictions where compliance documentation costs less to fulfill. Manufacturers in lower-cost certification environments export validated units to premium markets, capturing margin spreads between FDA submission requirements and domestic regulatory burdens.
United States
Biotech startups in Boston and San Diego clusters drive premium-tier procurement for clinical trial material preparation. FDA container closure integrity guidance mandates documented electromagnetic field consistency, forcing contract packers to upgrade field-level sealing capabilities. Mid-sized pharmaceutical manufacturers in New Jersey and North Carolina are deploying handheld units for decentralized quality control stations.
Germany
Pharmaceutical quality-control laboratories in Munich and Basel-adjacent Baden-Württemberg adopt variable-frequency inverter circuits for multi-product facilities. EMA Annex 1 sterile manufacturing requirements push contract packers toward validated portable sealing at distributed filling sites. REACH restrictions on nickel alloy exposure accelerate ferrite-dominant coil redesigns across Rhineland packaging operations.
India
CDSCO export certification requirements for sterile liquid formulations drive adoption among mid-tier manufacturers in Hyderabad and Ahmedabad clusters. Pharmaceutical contract packers upgrade portable sealing capabilities to meet European and American import documentation standards. Domestic regulatory harmonization with ICH guidelines is compressing validation timelines for local equipment vendors.
Switzerland
Swissmedic recognition of electromagnetic seal documentation accelerates deployment in Basel and Zurich pharmaceutical corridors. Precision engineering traditions support premium coil manufacturing for high-frequency pharmaceutical applications. Geneva-based biotech multinationals specify handheld units for clinical material preparation across global trial sites.
China
Dongguan and Shenzhen manufacturing bases supply cost-optimized coil assemblies to global equipment integrators. NMPA pharmaceutical packaging standards are tightening traceability requirements for exported drug containers. Domestic biotech clusters in Shanghai and Suzhou are importing validated European handheld units for GMP-compliant operations.
Handheld Induction Cap Sealers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with validation-heavy pharmaceutical applications favoring established service networks while emerging markets absorb price-optimized alternatives. The vendor base organizes into three tiers: North American and European incumbents with ISO 17025-accredited calibration infrastructure, East Asian fabricators competing on manufacturing scale, and regional integrators serving price-sensitive industrial applications. Consolidation pressure concentrates among mid-tier players lacking either premium service capabilities or cost-advantaged production bases. Dominant competitive moves include geographic expansion through distributor partnerships and backward integration into ferrite core and copper coil supply.
Within the premium-tier service vector, Enercon Industries Corporation and Lepel Corporation exemplify the North American specialist archetype, anchoring long-term contracts through preventive maintenance networks. Dongguan Sammi Packing Machine Co., Ltd. occupies the scale-driven position, sustaining cost advantages across manual and semi-automatic units shipped to emerging Asian markets. These three entities represent the structural poles around which competitive positioning organizes: validation depth versus manufacturing efficiency versus regional accessibility.
| Leading Market Players |
|---|
| Enercon Industries Corporation |
| Pillar Technologies |
| Lepel Corporation |
| Relco UK Ltd. |
| Dongguan Sammi Packing Machine Co., Ltd. |
| R-Technologies |
| The Cary Company |
| Parle Global |
| Daiichi Jitsugyo |
| Others |
Supply & Pricing Matrix
Copper coil and ferrite core procurement costs cascade through three distinct pricing tiers, with pharmaceutical-grade handheld units commanding premiums anchored to FDA electromagnetic field documentation burdens while beverage-focused alternatives compete on manufacturing scale from Dongguan and Shenzhen production bases.
Pricing Analysis
Distributor margins compress most acutely at the economy tier where manual sealers from East Asian fabricators compete on landed cost. Pricing stratifies across pharmaceutical validation depth, ergonomic engineering grade, and bundled ISO 17025 calibration services. Cost compression in the mid-tier intensifies because contract packers in India and Mexico prioritize capital expenditure minimization over preventive maintenance contracts. Beverage contract packers exhibit highest price sensitivity, while Boston and San Diego biotech clusters accept premium positioning for clinical trial material preparation.
Supply Chain Analysis
Certification gating concentrates validated coil assembly in the United States, Germany, and Switzerland, where ISO 15378 documentation and FDA electromagnetic field mapping capabilities reside. High-permeability ferrite cores draw from concentrated East Asian suppliers, creating single-source vulnerability for specialty magnetic materials. Tariff exposure on Chinese-sourced coil assemblies is forcing redundant qualification of alternative suppliers in Taiwan and South Korea. Distribution runs through authorized service networks for pharmaceutical-grade units and direct OEM relationships for industrial equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in handheld induction cap sealers rests on copper coil miniaturization cost-down curves and the shift toward subscription-based calibration services that lock recurring revenue from pharmaceutical packaging lines.
For Market Incumbents: Cement long-term contract positioning by deepening backward integration into ferrite core supply and expanding ISO 17025-accredited service networks across North American biotech clusters. Emerging competition from Dongguan-based fabricators with cost-optimized manual units threatens mid-tier pricing. Certification investment in EMA Annex 1 validation protocols creates switching costs among European contract packers. For New Entrants and Emerging Players: Launch via equipment-leasing models with bundled calibration services targeting venture-funded biotech startups in Boston and San Diego that prioritize operational expenditure flexibility. Cell and gene therapy manufacturing presents the most penetrable white-space, with point-of-care facilities requiring lot-size flexibility that handheld units uniquely provide. Direct-to-clinic distribution partnerships bypass established channel gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because pharmaceutical manufacturers consolidate vendor relationships around accredited metrology networks. The five-to-ten year viability window favors platforms with captive coil engineering capabilities. Acquisition target archetype: mid-tier European specialists with pre-submitted ECHA REACH compliance dossiers. Watch for divergence between FDA and EMA electromagnetic emission limits as inflection indicator for certification fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Supply | Captive sourcing of high-permeability magnetic materials insulates coil assembly from East Asian supply volatility. |
| ISO 17025 Calibration Network Expansion | Accredited metrology services lock recurring revenue and reduce customer switching among pharmaceutical packers. |
| EMA Annex 1 Validation Protocol Investment | Pre-submitted compliance dossiers accelerate procurement cycles at European sterile manufacturing facilities. |
| Equipment Leasing with Bundled Services | Operational expenditure models align with venture-funded biotech startup capital constraints in Boston clusters. |
| Variable-Frequency Inverter Circuit Development | Real-time power adjustment eliminates manual recalibration between aluminum and polymer container runs. |
Research Methodology
Direct dialogue with pharmaceutical packaging engineers, contract manufacturing quality directors, induction sealer service technicians, and regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FDA container closure integrity guidance documents, EMA Annex 1 sterile manufacturing requirements, ISO 15378 primary packaging standards, and USP Chapter 1207 package integrity testing protocols. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical packaging line investment surveys.
Installed base projections and revenue estimates emerged from segment-level modeling across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from regression analysis of historical shipment data against regulatory compliance spending patterns and copper coil cost indices. Industry-specific inputs included CDSCO export certification timelines and REACH restriction implementation schedules for nickel alloy exposure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electromagnetic emission regulatory divergence or ferrite core supply disruption scenarios. Model outputs reflect assumptions regarding pharmaceutical traceability mandate adoption rates and contract packer consolidation patterns. A model refresh is warranted upon material change in FDA-EMA technical harmonization negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Indonesia Plastic Caps and Closures Market
Caps and Closures
China Plastic Caps and Closures Market