
 Cone Lined Caps Market | 2026-2036
Cone Lined Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Lined Caps Market Outlook
North American specialty resin compounders is recalibrating supply schedules after feedstock volatility disrupted liner-grade polymer availability. Berry Global Inc. leverages backward integration into resin compounding to buffer margin pressure across its closure portfolio. Silgan Holdings Inc. anchors North American food packaging contracts through automated capping line partnerships with regional bottlers. Amcor Limited competes on multi-material platform flexibility, offering aluminum-to-plastic conversion pathways for brand owners reformulating packaging sustainability profiles.
Cone lined caps are threaded closures incorporating a conical elastomeric or foam liner compressed against container finish to form a liquid-tight and gas-tight seal, typically specified with torque retention values between 15 and 35 inch-pounds depending on diameter and liner durometer. The liner composition—ranging from pulp-backed vinyl to induction-seal-compatible foamed polyethylene—determines chemical resistance and shelf stability for aggressive fill products. Plastic dominates product type volume due to injection-molded polypropylene economies, though aluminum retains premium positioning in spirits and pharmaceutical applications where oxidation barriers justify unit cost premiums. Screw cap closure mechanism leads across all end user segments, while flip top configurations gain share in cosmetics dispensing formats where single-hand operation drives consumer preference.
FDA 21 CFR regulations govern liner material migration limits for food and pharmaceutical contact, compelling compounders to maintain Drug Master Files and food-contact letters of guarantee. EPA hazardous substance labeling requirements under TSCA Section 6 shape chemical end user demand for chemically inert liner formulations resistant to solvent attack. EU REACH Annex XVII restrictions on phthalate plasticizers and emerging PFAS limitations under the EU Packaging and Packaging Waste Regulation are forcing reformulation timelines across European supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions often prefigure broader federal packaging material mandates that would cascade through closure specification standards.
Market Dynamics
Pharmaceutical packaging specifications are tightening as tamper-evident sealing becomes mandatory for prescription drug distribution, forcing closure manufacturers to recalibrate liner durometer and torque retention across entire product lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material compliance mandates across member states are accelerating replacement cycles for non-compliant liner formulations in food and chemical applications.
- Pharmaceutical cluster concentration:Germany's chemical and pharmaceutical manufacturing density generates precision procurement demand for induction-seal-compatible closures with validated torque specifications.
- FDA 21 CFR migration limits:Compounder investment in Drug Master Files and food-contact certifications is expanding addressable market for compliant liner suppliers.
Market Restraints
- Feedstock volatility:Liner-grade polymer availability disruptions from North American specialty resin compounders are compressing margins and extending lead times.
- REACH Annex XVII restrictions:Phthalate plasticizer bans and emerging PFAS limitations under EU regulations are forcing expensive reformulation timelines.
- Aluminum substitution pressure:Premium spirits and pharmaceutical oxidation barriers retain aluminum positioning despite polypropylene injection-molding economies.
Strategic Opportunities
- Flip-top cosmetics dispensing:Single-hand operation preferences in personal care are opening design contracts for ergonomic closure configurations.
- California extended producer responsibility:State-level packaging material mandates are prefiguring broader federal standards that would cascade through closure specifications.
- Induction-seal compatibility convergence:Foamed polyethylene liner technology paired with automated capping lines is creating integrated system sales opportunities.
Industry Challenges
- Multi-material platform integration:Brand owner sustainability reformulation demands require aluminum-to-plastic conversion pathway engineering without seal integrity degradation.
- TSCA Section 6 compliance timelines:EPA hazardous substance labeling requirements for chemically inert formulations are extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Lined Caps Market |
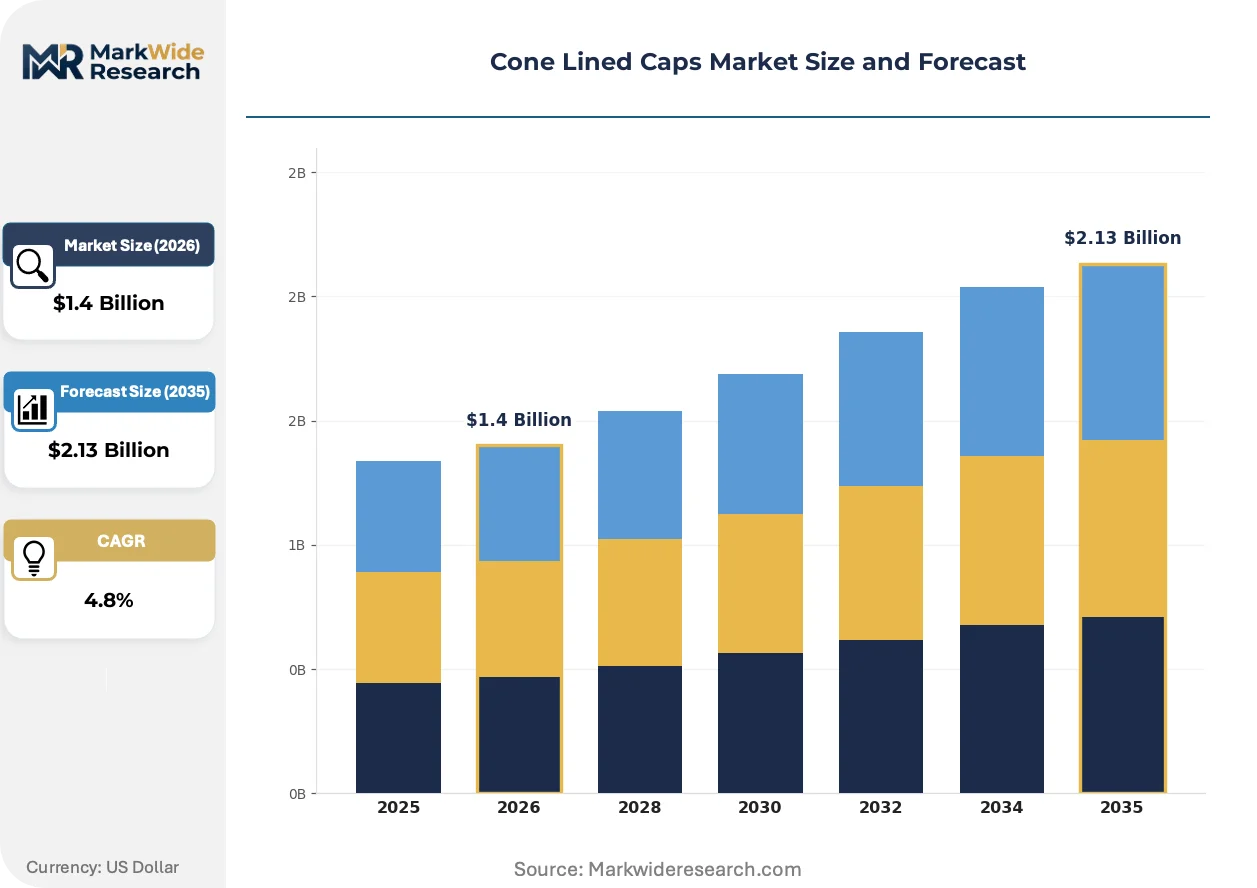
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Steel, Composite End User: Food & Beverage, Chemicals, Pharmaceuticals, Cosmetics Closure Mechanism: Screw Cap, Snap-On Cap, Flip Top Cap, Pull Tab Packaging Type: Bottles, Jars, Cans, Pouches |
| Companies Covered | Berry Global Inc., Silgan Holdings Inc., Amcor Limited, AptarGroup, Inc., Alpla-Werke Alwin Lehner GmbH & Co KG, Bericap GmbH & Co. KG, United Caps Luxembourg S.A., Gerresheimer AG, Guala Closures S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Lined Caps Market Strategic Shifts
Closure manufacturing is pivoting toward precision automation and regulatory pre-certification as pharmaceutical and food safety standards tighten across major economies.
Automated torque-controlled capping systems are automating seal validation in pharmaceutical bottling lines. Contract manufacturers in North America are deploying vision-inspection integration to eliminate manual torque testing. This compression of quality assurance labor is automating throughput gains while reducing seal-failure liability exposure.
REACH Annex XVII phthalate restrictions are forcing compounder reformulation across European supply chains. Liners incorporating bio-based plasticizers face eighteen-month validation cycles for food-contact approval. German chemical packaging buyers are responding by consolidating supplier panels to those with established ECHA pre-registration dossiers.
Brand owner sustainability scorecards are rotating procurement criteria toward circular material content. Spirits and pharmaceutical packagers in France and Switzerland now specify recycled aluminum content thresholds in closure tenders. This certification-driven preference shift is most visible in premium positioning where unit cost premiums absorb material traceability investments.
Cone Lined Caps Market Segmentation
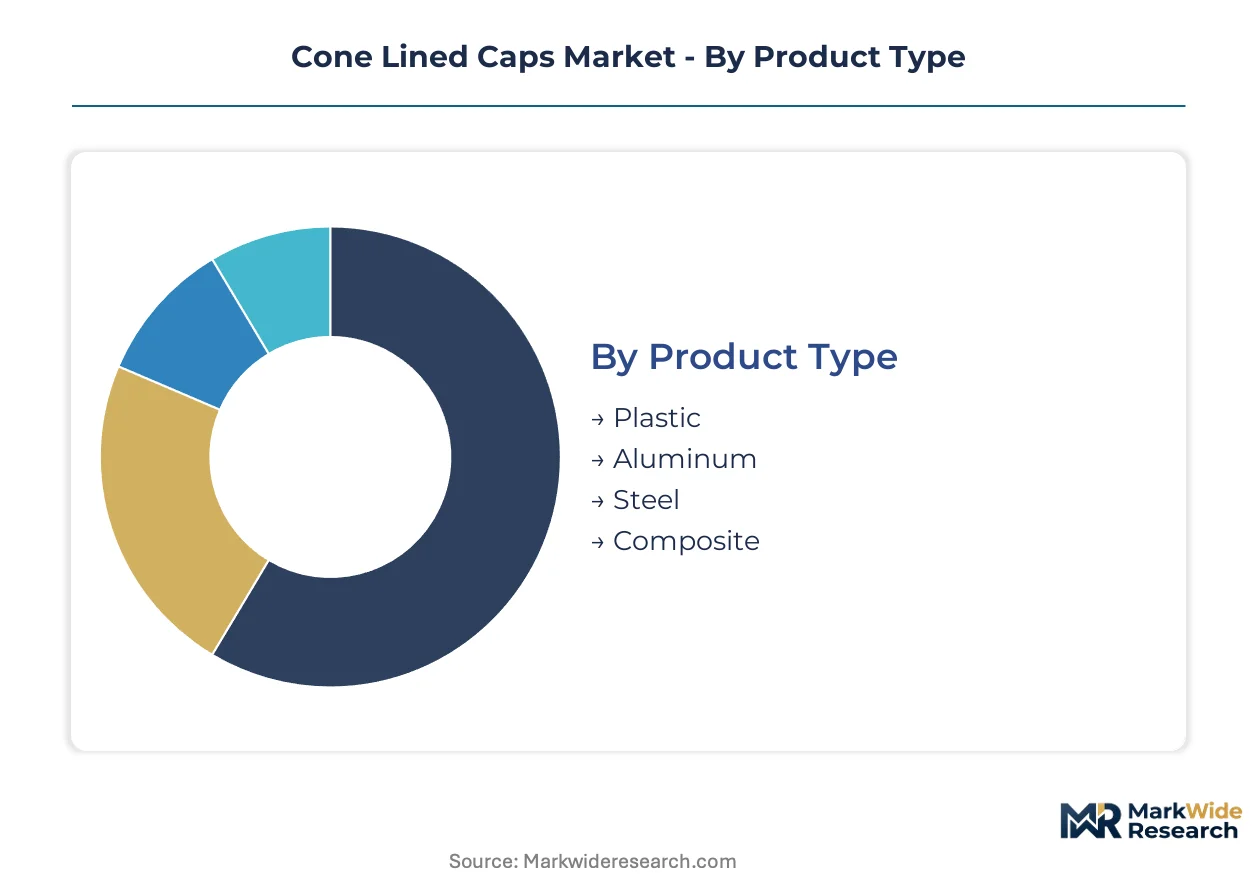
Cone lined caps require precise specification matching across material chemistry, regulatory compliance, and mechanical performance. Segmentation reveals how liner composition and closure geometry dictate procurement decisions across pharmaceutical, food, and chemical packaging verticals.
Product Type:
FDA 21 CFR migration limits and EU REACH Annex XVII substance restrictions create divergent certification burdens across material platforms.
- Plastic:Injection-molded polypropylene dominates unit economics with liner-grade polymer formulations meeting food-contact letters of guarantee. Pharmaceutical bottlers in Germany specify induction-seal-compatible foamed polyethylene liners for torque retention validation between 15 and 35 inch-pounds.
- Aluminum:Rolled aluminum shells with pulp-backed vinyl or elastomeric liners command premium positioning where oxidation barriers justify unit cost premiums. Spirits packagers in France and Switzerland now mandate recycled aluminum content thresholds in closure tenders.
- Steel:Tinplate constructions with compression-molded liners serve aggressive chemical fills requiring solvent resistance.
- Composite:Multi-layer structures combining aluminum barrier films with plastic torque bands address sustainability scorecard demands without seal integrity degradation.
Leading the category by volume: Plastic. Growing fastest: Composite.
End User:
End-use concentration determines torque specification precision and validation documentation requirements.
- Pharmaceuticals:Tamper-evident sealing mandates for prescription drug distribution force recalibration of liner durometer across entire product lines. FDA Drug Master File maintenance and validated torque specifications concentrate procurement among German chemical and pharmaceutical clusters.
- Food & Beverage:Pulp-backed vinyl liners face eighteen-month validation cycles for food-contact approval under bio-based plasticizer reformulations. EU Packaging and Packaging Waste Regulation compliance is accelerating replacement cycles for non-compliant liner formulations.
- Chemicals:EPA TSCA Section 6 hazardous substance labeling requirements shape demand for chemically inert formulations resistant to solvent attack.
- Cosmetics:Single-hand operation preferences drive flip-top configuration adoption in personal care dispensing formats.
Pharmaceuticals commands the steepest price premiums. Cosmetics exhibits the fastest design innovation cycle.
Closure Mechanism:
Automation compatibility and consumer ergonomics split procurement criteria across mechanism types.
- Screw Cap:Threaded compression against container finish delivers liquid-tight and gas-tight seals with measurable torque retention. Automated capping line partnerships in North American food packaging anchor volume contracts through vision-inspection integration.
- Flip Top Cap:Hinged single-hand operation meets cosmetics dispensing preferences where consumer convenience drives specification. Ergonomic design contracts are opening for regional bottlers and contract manufacturers.
- Snap-On Cap:Press-fit engagement suits high-speed filling lines with lower torque precision requirements.
- Pull Tab:Tamper-evident fracture mechanics serve pharmaceutical and chemical applications requiring immediate visual integrity confirmation.
Screw Cap retains dominant share. Flip Top Cap is expanding most quickly in personal care.
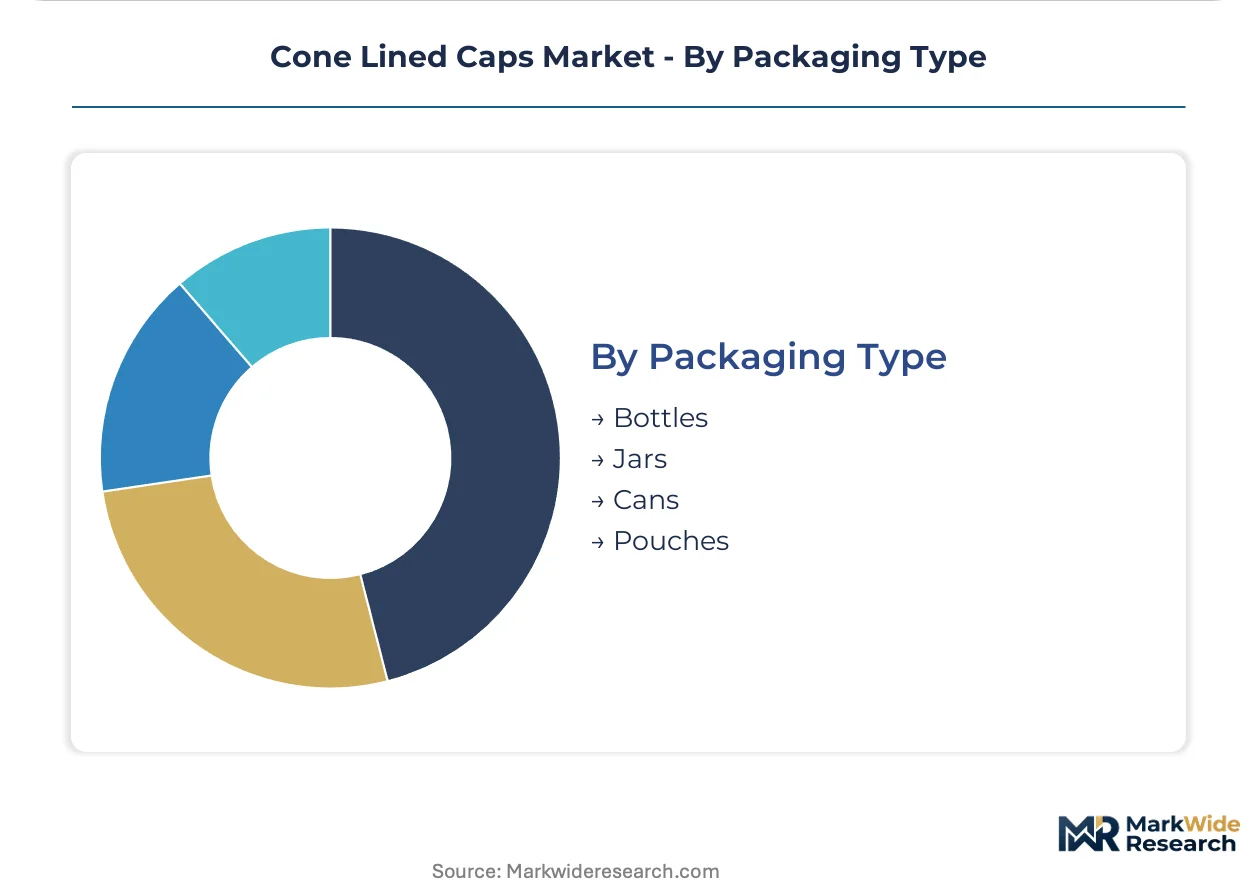
Packaging Type:
Container finish geometry and headspace requirements determine liner compression surface area and material selection.
- Bottles:Narrow-neck finishes with standardized thread profiles accommodate precision torque-controlled capping systems. Pharmaceutical bottling lines deploy automated seal validation with compression of conical elastomeric liners against glass or plastic finishes.
- Jars:Wide-mouth openings require larger diameter liners with adjusted durometer for consistent seal pressure across expanded surface area. Food packagers specify pulp-backed vinyl for shelf-stable aggressive fills.
- Cans:Metal container finishes demand liner formulations compatible with rolled steel or aluminum flange geometries.
- Pouches:Flexible packaging spout attachments create emerging specification territory for lightweight closure integration.
Bottles anchor the installed base. Jars show the strongest growth in premium food positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty resin compounders in Texas and Louisiana supply liner-grade polypropylene that anchors North American cone lined cap production. German chemical clusters consume precision closures for pharmaceutical bottling. Asian packaging converters in Zhejiang and Guangdong provinces scale composite closure manufacturing for export markets.
United States
Pharmaceutical bottlers in New Jersey and North Carolina specify induction-seal-compatible closures with validated torque retention. FDA 21 CFR migration limits compel compounders to maintain Drug Master Files for food-contact certification. The Gulf Coast petrochemical corridor supplies liner-grade polymer formulations to closure manufacturers buffering feedstock volatility.
Germany
Chemical and pharmaceutical manufacturing density in Ludwigshafen and Leverkusen generates precision procurement demand for tamper-evident sealing solutions. EU REACH Annex XVII phthalate restrictions force eighteen-month reformulation cycles for liner suppliers. Bavarian packaging converters consolidate supplier panels to compounders with established ECHA pre-registration dossiers.
China
Cosmetics brands in Shanghai and Guangzhou specify flip-top configurations for single-hand dispensing convenience. SAMR food-contact material standards align with GB testing protocols for liner migration limits. The Yangtze River Delta hosts automated capping line integration projects linking closure suppliers to regional bottlers.
France
Spirits packagers in Cognac and Champagne mandate recycled aluminum content thresholds in premium closure tenders. ANSM pharmaceutical packaging guidelines enforce tamper-evident requirements for prescription drug distribution. The Île-de-France region concentrates sustainability scorecard procurement for brand owner circular material commitments.
Switzerland
Pharmaceutical precision packaging in Basel demands validated torque specifications between 15 and 35 inch-pounds. Swissmedic device regulations extend to closure integrity for sterile fill applications. The country's chemical-pharmaceutical cluster sources induction-seal-compatible liners from certified European compounders.
Cone Lined Caps Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue composite material and automation integration specialties. The market structures around three tiers: multinational packaging conglomerates with backward resin integration, mid-cap closure specialists with regional bottler partnerships, and niche compounders serving pharmaceutical validation requirements. Competitive positioning crystallizes through M&A consolidation of liner-grade polymer supply and strategic partnerships for automated capping line integration.
Among North American packaging conglomerates, Berry Global Inc. exemplifies resin integration archetypes, while Silgan Holdings Inc. represents automated line partnership positioning. European specialists including Amcor Limited occupy multi-material platform flexibility tiers. These three anchors illustrate divergent strategic vectors: captive supply security, equipment integration lock-in, and sustainability conversion pathway engineering.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Amcor Limited |
| AptarGroup, Inc. |
| Alpla-Werke Alwin Lehner GmbH & Co KG |
| Bericap GmbH & Co. KG |
| United Caps Luxembourg S.A. |
| Gerresheimer AG |
| Guala Closures S.p.A. |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII phthalate restrictions gate qualified liner-grade polymer supply and premium-tier pricing access for pharmaceutical and food-contact compounders lacking ECHA pre-registration dossiers. German packaging buyers now consolidate procurement panels to certified suppliers, compressing margins for non-compliant competitors while elevating validated torque specification premiums.
Pricing Analysis
Warranty-bundled validation documentation separates premium pharmaceutical closures from unbundled standard-tier offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA Drug Master File maintenance and torque retention certification. Cost compression in standard-tier polypropylene injection molding intensifies as feedstock volatility extends lead times. Pharmaceutical bottlers exhibit lowest price sensitivity due to tamper-evident compliance mandates, while regional cosmetics contract manufacturers drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast petrochemical corridors supplying liner-grade polypropylene formulations to North American closure manufacturers. Production gravity centers on Texas and Louisiana specialty resin compounders, German chemical clusters in Ludwigshafen, and Zhejiang province packaging converters. Raw material dependencies encompass propylene feedstocks, pulp-backed vinyl substrates, and induction-seal-compatible foamed polyethylene. Tariff exposure on aluminum coil imports threatens rolled shell supply for spirits applications. Distribution runs through automated capping line partnerships linking closure suppliers to regional bottler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 21 CFR migration limits erect barrier-to-entry moats favoring compounders with maintained Drug Master Files and established food-contact certifications.
For Market Incumbents: Cement resin integration advantages through backward control over liner-grade polymer compounding in Gulf Coast corridors. Fortify pharmaceutical validation moats by accelerating ECHA pre-registration dossier completion ahead of REACH Annex XVII enforcement waves. Capacity addition in Bavaria addresses German chemical cluster procurement consolidation trends. For New Entrants and Emerging Players: Regional cosmetics contract manufacturers represent the most penetrable channel partner type for flip-top configuration specialization. White-space concentration sits with Shanghai and Guangzhou personal care brands seeking ergonomic single-hand dispensing solutions. Induction-seal compatibility convergence with automated capping line integration offers differentiated system sales positioning against incumbent commodity suppliers. For Investors and Strategic Acquirers: German packaging converter consolidation announcements are the leading indicator that European supply chain rationalization is accelerating toward oligopoly structure. Long-term viability favors compounders with dual FDA-EU certification portfolios and captive resin supply. Target acquisition archetype: mid-cap liner specialists with established pharmaceutical validation documentation and underutilized torque-controlled capping line partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply model buffers margin pressure from Gulf Coast feedstock volatility. |
| Automated Capping Line Partnership | Silgan's vision-inspection integration anchors North American food packaging volume contracts. |
| Multi-Material Platform Conversion | Amcor's aluminum-to-plastic pathway engineering captures brand owner sustainability scorecard procurement. |
| REACH Annex XVII Pre-Registration | ECHA dossier maintenance secures German pharmaceutical cluster supplier panel consolidation. |
| Flip-Top Ergonomic Design Contract | Cosmetics dispensing innovation opens regional bottler partnerships in China's Yangtze River Delta. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and pharmaceutical procurement platforms underwrites the qualitative findings in this study. Primary interviews with closure manufacturing executives, liner-grade polymer compounders, pharmaceutical packaging engineers, and automated capping line integrators combined with secondary validation from FDA Drug Master File repositories, ECHA registration databases, and SEC 10-K disclosures. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates across material platforms and end-use verticals.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline demand and post-regulatory-shift adjustment trajectories. Segmentation modeling incorporated product type chemistry, closure mechanism automation compatibility, end-use torque precision requirements, and regional regulatory cluster stringency across the projection horizon. CAGRs derived from installed base replacement cycles, pharmaceutical tamper-evident mandate adoption curves, and EU Packaging and Packaging Waste Regulation compliance timelines. Industry-specific forecast inputs encompassed liner durometer specification shifts and induction-seal technology penetration rates.
Caveats apply where feedstock volatility spikes, REACH Annex XVII enforcement acceleration, or state-level extended producer responsibility pre-emption could materially shift the outlook. Forecasts reflect documented assumptions regarding pharmaceutical cluster concentration stability and aluminum recycling content threshold adoption in premium spirits packaging. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Foamed End Caps Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Latin America Metal Caps and Closures Market
Caps and Closures
Brush Caps Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Cover Caps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Ring Pull Caps Market