
 Foam End Caps Market | 2026-2036
Foam End Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Foam End Caps Market Foresight
Asset-light leasing models for molding equipment are rewriting competitive entry barriers in foam end cap fabrication. Sealed Air Corporation leverages captive resin sourcing to sustain margin stability across volatile petrochemical cycles. Sonoco Products Company anchors its position through geographic density in North American automotive corridors. Pregis Corporation differentiates via R&D intensity in custom-engineered profiles for medical device shippers.
Foam end caps are molded or fabricated cellular polymer closures designed to absorb impact, distribute compressive loads, and seal cavity openings; manufacturers typically specify density between 2 and 10 pounds per cubic foot depending on cushioning duty. These components serve primarily as protective interfaces in transit packaging and finished goods assembly. Polyurethane foam commands the material tier due to established supply chains and tunable hardness grades, while XPE foam represents the fastest-expanding chemistry for moisture-sensitive electronics applications. Custom caps capture disproportionate margin pools because engineering services attach to each specification, whereas standard caps compete on throughput scale.
FDA material contact rules govern foam constituents in medical and food-contact packaging, compelling converters to maintain master file documentation for resin lots. EPA VOC emission thresholds for foam manufacturing reshape plant location decisions and abatement capital allocation. OSHA workplace exposure limits for isocyanates during polyurethane production elevate automation investment requirements. Stakeholders must monitor how evolving state-level extended producer responsibility laws in California and New York redistribute end-of-life collection costs across brand owners and packaging suppliers.
Market Dynamics
REACH chemical restrictions in Europe are forcing converters to reformulate polyurethane systems, while electronics manufacturers in China's coastal provinces drive precision-molded demand. These dual pressures compress formulation cycles and reshape supplier qualification protocols across the value chain.
Growth Catalysts
- Asia-Pacific electronics clustering:Appliance and automotive OEM concentration in China's coastal manufacturing provinces sustains high-volume demand for custom-engineered protective components.
- REACH low-VOC mandates:ECHA restrictions on isocyanate emissions push European converters toward water-blown polyurethane formulations with reduced environmental liability.
- XPE foam chemistry advances:Cross-linked polyethylene foam offers moisture resistance and dielectric stability that electronics shippers specify for semiconductor transit protection.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursors track crude oil and natural gas liquid indices, compressing converter margins during upstream price spikes.
- Isocyanate supply concentration:MDI and TDI production clusters in the US Gulf Coast and Northeast Asia expose foam fabricators to single-source disruption risk.
- End-of-life collection mandates:California and New York extended producer responsibility laws redistribute foam recovery costs to brand owners and packaging suppliers.
Strategic Opportunities
- Medical device packaging expansion:FDA master file documentation requirements for resin lots create service-attach revenue streams for converters with regulatory affairs capabilities.
- Asset-light equipment leasing:Molding machinery rental models lower capital barriers for regional fabricators entering custom cap specification work.
- Automotive lightweighting:EV battery pack protection specifications favor low-density foam cores that absorb collision energy without adding mass.
Industry Challenges
- Isocyanate exposure compliance:OSHA workplace limits for TDI and MDI vapors mandate automated dispensing systems and ventilation capital outlays at polyurethane production lines.
- Multi-jurisdiction certification lag:FDA, EPA, and state-level VOC rules require parallel compliance documentation that extends new product introduction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam End Caps Market |
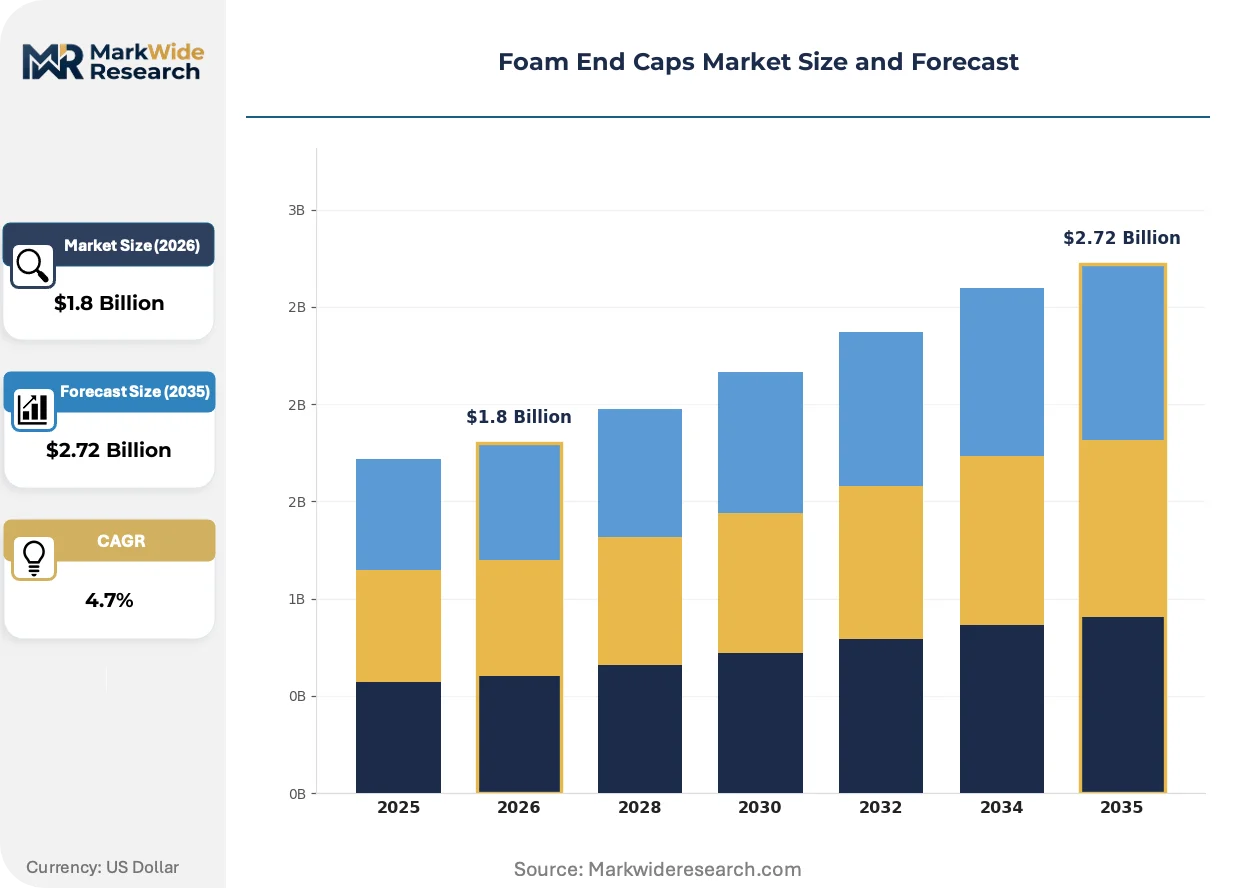
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Custom Caps, Reusable Caps, Disposable Caps Material: EVA Foam, Polyurethane Foam, XPE Foam, PE Foam Application: Packaging, Automotive, Construction, Sports Equipment End User: Retailers, Manufacturers, Wholesalers, Distributors |
| Companies Covered | Sealed Air Corporation, Sonoco Products Company, Pregis Corporation, Atlas Molded Products, ACH Foam Technologies, Plastifoam Company, Rogers Foam Corporation, Armacell, Zotefoams PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam End Caps Market Shifts & Advancements
Digital tooling and bio-based feedstocks are compressing development cycles while regulatory pressure on chemical constituents intensifies formulation complexity. These forces reward converters with in-house polymer science capabilities.
Water-blown polyurethane systems are collapsing the dominance of HCFC and HFC blowing agents in precision-molded end cap production. Electronics shippers in South Korea and Taiwan specify these formulations to meet corporate Scope 3 targets. The technology is collapsing the premium that fluorocarbon-based foams once commanded in moisture-sensitive applications.
EU F-Gas Regulation phase-down schedules are accelerating converter investment in alternative blowing agent infrastructure. The rule compresses availability of high-GWP propellants for foam expansion. Medical device and cold-chain packaging segments in Germany and the Netherlands are reformulating fastest to avoid supply interruption.
Direct specification relationships between appliance OEMs and foam fabricators are displacing distributor-mediated procurement in North American automotive corridors. Tier-1 suppliers now require lot-level resin traceability that distributors cannot provide. The shift concentrates volume with converters maintaining captive mixing and documentation systems.
Foam End Caps Market Segmentation
Foam end cap specifications diverge sharply across duty cycles, chemistry constraints, and procurement relationships. Understanding these fault lines exposes where margin pools concentrate and which converter capabilities command pricing power.
Product Type:
Cost tier determines whether converters compete on engineering services or throughput scale.
- Standard Caps:Off-the-shelf geometries with fixed density ratings serve high-volume appliance and electronics packaging. Demand concentrates with distributors serving China's Guangdong and Jiangsu manufacturing clusters where OEMs prioritize procurement efficiency over customization.
- Custom Caps:Engineered-to-order profiles with lot-level resin traceability attach design fees and qualification services. Medical device shippers in Germany and the Netherlands specify these for FDA master file compliance, while EV battery pack manufacturers require collision-energy absorption tuned to specific cell geometries.
- Reusable Caps:Durable closed-cell formulations withstand multiple return cycles in closed-loop automotive logistics. Tier-1 suppliers in Michigan and South Carolina specify these for just-in-time seating and trim component delivery.
- Disposable Caps:Single-use low-density designs dominate e-commerce fulfillment where cost-per-unit governs specification. Amazon and Walmart distribution centers in Texas and California drive volume through automated packaging lines.
Custom caps command the established margin base. The steepest expansion runs through reusable caps as automotive closed-loop logistics mature.
Material:
Chemistry selection tracks moisture sensitivity, dielectric requirements, and regulatory pressure on blowing agents.
- Polyurethane Foam:Tunable hardness grades from 2 to 10 pounds per cubic foot and established TDI/MDI supply chains sustain dominance in precision-molded applications. REACH low-VOC mandates are forcing European converters toward water-blown formulations that eliminate fluorocarbon propellants.
- XPE Foam:Cross-linked polyethylene delivers moisture resistance and dielectric stability that semiconductor shippers in South Korea and Taiwan specify for wafer transit protection. The chemistry gains share fastest as electronics OEMs pursue Scope 3 emission reductions.
- EVA Foam:Ethylene-vinyl acetate copolymers offer Shore A hardness flexibility for sports equipment padding and consumer goods. Nike and Adidas manufacturing partners in Vietnam specify these for athletic shoe midsole protection during ocean freight.
- PE Foam:Expanded polyethylene provides cost-efficient cushioning for non-critical consumer electronics and furniture. Mass retailers in India and Brazil source these for price-sensitive domestic appliance packaging.
Polyurethane formulations anchor current volume. XPE chemistry climbs the fastest as moisture-sensitive electronics expand protection specifications.
Application:
End-use duty cycles separate specification intensity from commodity procurement.
- Packaging:Transit protection for electronics, appliances, and medical devices demands density-graded cushioning with compression set resistance. E-commerce fulfillment centers in California and New York face extended producer responsibility laws that redistribute foam recovery costs.
- Automotive:EV battery pack collision protection and interior trim component interfaces favor low-density cores that absorb energy without adding mass. OEMs in Germany and Japan specify lot-level traceability that eliminates distributor intermediaries.
- Construction:Pipe insulation end caps and HVAC duct sealing require thermal stability across temperature cycling. Building codes in Texas and Florida drive specification for flame-retardant formulations.
- Sports Equipment:Helmet liner interfaces and protective gear padding prioritize impact absorption with repeated compression recovery. Premium brands in Italy and Switzerland specify custom densities for professional athlete equipment.
Packaging applications hold the revenue base. Automotive lightweighting specifications gain share fastest as EV production scales.
End User:
Procurement authority determines whether relationships run direct or through intermediaries.
- Manufacturers:Appliance, automotive, and electronics OEMs with captive quality systems specify direct converter relationships. These buyers require resin lot documentation and statistical process control data that distributors cannot provide.
- Distributors:Industrial supply houses aggregate demand from small and mid-sized fabricators. These intermediaries compete on inventory availability and consolidated freight economics across North American manufacturing corridors.
- Retailers:Big-box chains and e-commerce platforms specify packaging for private-label goods. Walmart and Target procurement teams in Arkansas and Minnesota negotiate volume-tier pricing with national foam converters.
- Wholesalers:Regional packaging resellers serve job shops and seasonal demand spikes. These buyers prioritize price and availability over technical specification depth.
Direct manufacturer relationships concentrate the premium tier. Distributor-mediated procurement is expanding fastest among small and mid-sized fabricators seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major foam end cap markets, with net exporters concentrated in petrochemical-advantaged economies while electronics-importing regions drive specification intensity. Trade flows reflect divergent regulatory pressure on blowing agents and end-use clustering in automotive and semiconductor corridors.
China
Guangdong and Jiangsu provinces host dense appliance and automotive OEM clusters that absorb precision-molded protective components at scale. MEE enforcement of dual carbon goals accelerates water-blown polyurethane adoption in coastal manufacturing zones. Shenzhen and Suzhou fabricators now supply semiconductor transit protection to South Korean and Taiwanese chipmakers under direct specification relationships.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify low-density foam cores for EV battery pack collision protection with lot-level resin traceability. ECHA REACH restrictions on isocyanate emissions force converters toward water-blown formulations that eliminate fluorocarbon propellants. Stuttgart and Munich industrial corridors concentrate medical device packaging demand tied to FDA master file compliance requirements.
United States
EPA VOC emission thresholds reshape plant location decisions across Texas and California, where e-commerce fulfillment centers drive disposable cap volume through automated packaging lines. OSHA workplace exposure limits for TDI and MDI vapors mandate automated dispensing systems at polyurethane production lines. Michigan and South Carolina automotive corridors specify reusable closed-cell formulations for closed-loop just-in-time logistics.
South Korea
Semiconductor shippers in Gyeonggi Province specify XPE foam chemistry for wafer transit protection with dielectric stability requirements. Corporate Scope 3 emission targets accelerate water-blown polyurethane adoption for moisture-sensitive electronics applications. Samsung and SK Hynix supply chain specifications now exclude fluorocarbon-based foams from qualified vendor lists.
Japan
METI industrial standards govern foam density specifications for automotive interior trim components manufactured in Aichi and Shizuoka prefectures. Precision-molded end cap demand concentrates around Toyota and Honda supply chain requirements for collision-energy absorption tuning. Nagoya-based fabricators maintain captive resin mixing systems to satisfy OEM lot-level documentation protocols.
Foam End Caps Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: multinational converters with captive resin sourcing, regional specialists with geographic density in automotive corridors, and asset-light fabricators leveraging equipment leasing models. Strategic archetypes include formulation-integrated players, custom-engineering specialists, and throughput-scale commodity suppliers. Dominant competitive moves involve backward integration into precursor chemicals and geographic expansion through distributor acquisition.
Within the multinational tier, Sealed Air Corporation, Sonoco Products Company, and Pregis Corporation exemplify contrasting strategic positions. Sealed Air represents the vertically integrated archetype with upstream control over petrochemical supply chains. Sonoco occupies a position anchored in North American automotive corridor density. Pregis sits within the R&D-intensive custom specification segment serving medical device and electronics shippers with regulatory affairs capabilities.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Sonoco Products Company |
| Pregis Corporation |
| Atlas Molded Products |
| ACH Foam Technologies |
| Plastifoam Company |
| Rogers Foam Corporation |
| Armacell |
| Zotefoams PLC |
| Others |
Supply & Pricing Matrix
Guangdong and Jiangsu manufacturing clusters anchor polyurethane precursor supply, with captive resin mixing capacity translating directly into pricing leverage for precision-molded custom caps. Water-blown formulation investments in Shenzhen and Suzhou compress fluorocarbon foam premiums while elevating qualification barriers for distributors lacking in-house polymer science capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with medical device shippers paying design fees for FDA master file compliance and lot-level resin traceability. Price differentiation stems from certification grade and volume scale, with automotive corridor contracts favoring converters maintaining statistical process control data. Cost compression in disposable caps is intensifying because Amazon and Walmart fulfillment centers negotiate automated packaging line economics. Small fabricators through industrial supply houses exhibit highest price sensitivity, while EV battery pack manufacturers prioritize collision-energy absorption tuning over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Sealed Air Corporation, Sonoco Products Company, and Pregis Corporation, each maintaining geographic density in distinct automotive and electronics corridors. Raw material dependencies draw from MDI and TDI precursors clustered on the US Gulf Coast and in Northeast Asia, plus cross-linked polyethylene resin supply from South Korean petrochemical complexes. Single-source vulnerability in isocyanate production exposes foam fabricators to disruption risk from Gulf Coast weather events. Distribution runs through direct specification relationships displacing intermediaries in North American automotive corridors, while distributor-mediated procurement persists among small and mid-sized fabricators in China's coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-blown polyurethane chemistry advances are disrupting fluorocarbon foam dominance as electronics OEMs pursue Scope 3 emission reductions, compressing formulation cycles and rewarding converters with regulatory affairs capabilities.
For Market Incumbents: Harden formulation-integrated positions by accelerating water-blown polyurethane capacity in European corridors ahead of EU F-Gas Regulation phase-down deadlines. Deepen backward integration into MDI precursor supply to mitigate petrochemical feedstock volatility exposure. Sealed Air Corporation's captive resin sourcing model demonstrates how upstream control insulates margin stability across crude oil price cycles. For New Entrants and Emerging Players: India's domestic appliance packaging corridors present underpenetrated white-space for expanded polyethylene foam supply to mass retailers seeking price-sensitive cushioning. Vietnam's athletic shoe manufacturing partnerships offer entry through ethylene-vinyl acetate copolymer specifications for ocean freight protection. Pursue asset-light equipment leasing models to lower capital barriers for custom cap specification work without committing to fixed molding infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-attachment play because REACH low-VOC mandates and FDA master file requirements continuously concentrate volume with converters maintaining compliance documentation systems. Target acquisition profiles center on regional specialists with geographic density in automotive corridors and in-house polymer science capabilities. Monitor Samsung and SK Hynix qualified vendor list exclusions of fluorocarbon-based foams as signal of accelerating chemistry transition.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Blown Formulation Transition | ECHA REACH restrictions on isocyanate emissions compel European converters toward fluorocarbon-free polyurethane systems. |
| Backward Integration into Precursor Chemicals | Captive MDI sourcing insulates Sealed Air Corporation from Gulf Coast petrochemical supply disruptions. |
| Medical Device Regulatory Affairs Investment | FDA master file documentation requirements attach service revenue to resin lot traceability capabilities. |
| Automotive Closed-Loop Logistics Expansion | Michigan and South Carolina corridors specify reusable closed-cell formulations for just-in-time seating delivery. |
| XPE Chemistry Scale-Up | Samsung and SK Hynix supply chain specifications now exclude fluorocarbon-based foams from qualified vendor lists. |
Research Methodology
A spread of perspectives from foam fabrication plant managers, procurement leads at appliance OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings for packaging converters. Bottom-up demand modeling across product type, material chemistry, application duty cycle, and end-user procurement authority triangulated against top-down petrochemical feedstock consumption patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning standard versus custom versus reusable versus disposable product tiers, polyurethane versus XPE versus EVA versus PE material chemistry, and packaging versus automotive versus construction versus sports equipment applications. CAGRs derived from elasticity-adjusted volume projections incorporating electronics OEM clustering in China's coastal provinces and EV battery pack protection specification intensity. Industry-specific forecast inputs included REACH reformulation timelines and automotive lightweighting content-per-vehicle trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed petrochemical conglomerates or accelerated EU F-Gas Regulation enforcement would shift outcomes beyond modeled ranges. Quarterly review of water-blown polyurethane adoption rates in South Korean semiconductor transit applications and extended producer responsibility law implementation in California and New York is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Spray Caps Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Linerless Closures Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Heat Shrink Bands Market
Caps and Closures
Twist Caps Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Fez Caps Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Global Die Cut Lids Market
Caps and Closures
Canada Plastic Caps and Closures Market