
 Casein and Casein Derivatives Market | 2026-2036
Casein and Casein Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Casein and Casein Derivatives Market Outlook
Direct procurement between ingredient suppliers and sports nutrition manufacturers is narrowing as large dairy cooperatives consolidate volume contracts. Fonterra Co-operative Group leverages its New Zealand milk pool to anchor premium micellar casein supply chains across Asia-Pacific. Groupe Lactalis dominates European caseinate production through backward integration into industrial cheesemaking. Kerry Group differentiates on hydrolyzed casein functionality for medical nutrition applications.
Casein and casein derivatives comprise phosphoprotein fractions extracted from skim milk through acid or rennet precipitation, typically containing 80-82% protein on a dry basis with bound calcium and phosphorus micelles that enable gelation and emulsification. These proteins serve primarily as structural agents in processed foods and as slow-release amino acid sources in clinical and sports nutrition. Caseinates retain the largest share of value generation due to their solubility versatility across beverages and meat analogues. Micellar casein captures the fastest growth trajectory within the product type dimension, driven by its native protein structure appeal in premium sports nutrition. Within applications, infant nutrition commands concentrated margin pools as manufacturers prioritize hypoallergenic and minimally processed ingredient credentials.
The FDA oversees GRAS status and labeling requirements for casein ingredients in US food and supplement channels, while EFSA establishes maximum residue limits and novel food assessments across European member states. BIS certification requirements in India constrain import flows and shape local sourcing strategies for multinational formulators. Stakeholders must monitor evolving protein content verification protocols and regional allergen labeling mandates to secure formulation partnerships and avoid customs detention.
Market Dynamics
Consolidation among New Zealand and European dairy cooperatives is compressing supplier margins while concentrating micellar casein availability around vertically integrated milk pool operators. This supply-side concentration is reshaping procurement negotiations for sports nutrition and infant formula manufacturers.
Growth Catalysts
- Clean-label formulation mandates:Sports nutrition brands reformulate with native protein structures to meet consumer transparency expectations. Micellar casein's unaltered micelle configuration satisfies this credential requirement without functional compromise.
- FDA GRAS pathway streamlining:Accelerated self-affirmed GRAS determinations for hydrolyzed casein variants reduce time-to-market for medical nutrition entrants. This regulatory efficiency expands addressable indications for clinical peptide formulations.
- China infant formula localization:Domestic Chinese manufacturers accelerate captive micellar casein sourcing to reduce import dependency. SAMR registration requirements favor established suppliers with localized quality documentation.
Market Restraints
- Skim milk powder price volatility:Casein extraction economics tether directly to SMP commodity cycles, squeezing processor margins during peak dairy input periods. New Zealand auction price swings transmit rapidly through derivative pricing.
- European supply concentration:Groupe Lactalis and FrieslandCampina control majority European caseinate capacity, creating single-source risk for meat analogue and beverage formulators. Alternative sourcing requires qualification timelines exceeding 18 months.
- Plant protein substitution:Pea and fava protein isolates achieve functional parity in select emulsification applications at lower cost-in-use. Bakery and processed meat segments increasingly trial these alternatives in cost-sensitive formulations.
Strategic Opportunities
- India BIS certification arbitrage:Domestic casein manufacturers meeting BIS IS 11921 standards capture share from detained import shipments. Local production investments align with FSSAI enforcement tightening on unlabeled dairy derivatives.
- Geriatric medical nutrition:Sarcopenia-targeted enteral formulas incorporating slow-digesting micellar casein address aging demographics in Japan and South Korea. PMDA and MFDS reimbursement pathways for clinical nutrition support this application expansion.
- EU Green Deal dairy processing incentives:Farm to Fork Strategy grants for low-carbon casein extraction technologies subsidize membrane filtration upgrades. Cooperatives capturing these funds differentiate on carbon footprint credentials for ESG-mandated buyers.
Industry Challenges
- Protein content verification complexity:Kjeldahl and Dumas method discrepancies create specification disputes between suppliers and infant formula manufacturers. AOAC harmonization efforts remain incomplete across major testing laboratories.
- Allergen labeling fragmentation:EFSA, FDA, and FSSAI maintain divergent casein allergen threshold and precautionary labeling requirements. Multi-territory brands face reformulation or dual-SKU complexity to achieve compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein and Casein Derivatives Market |
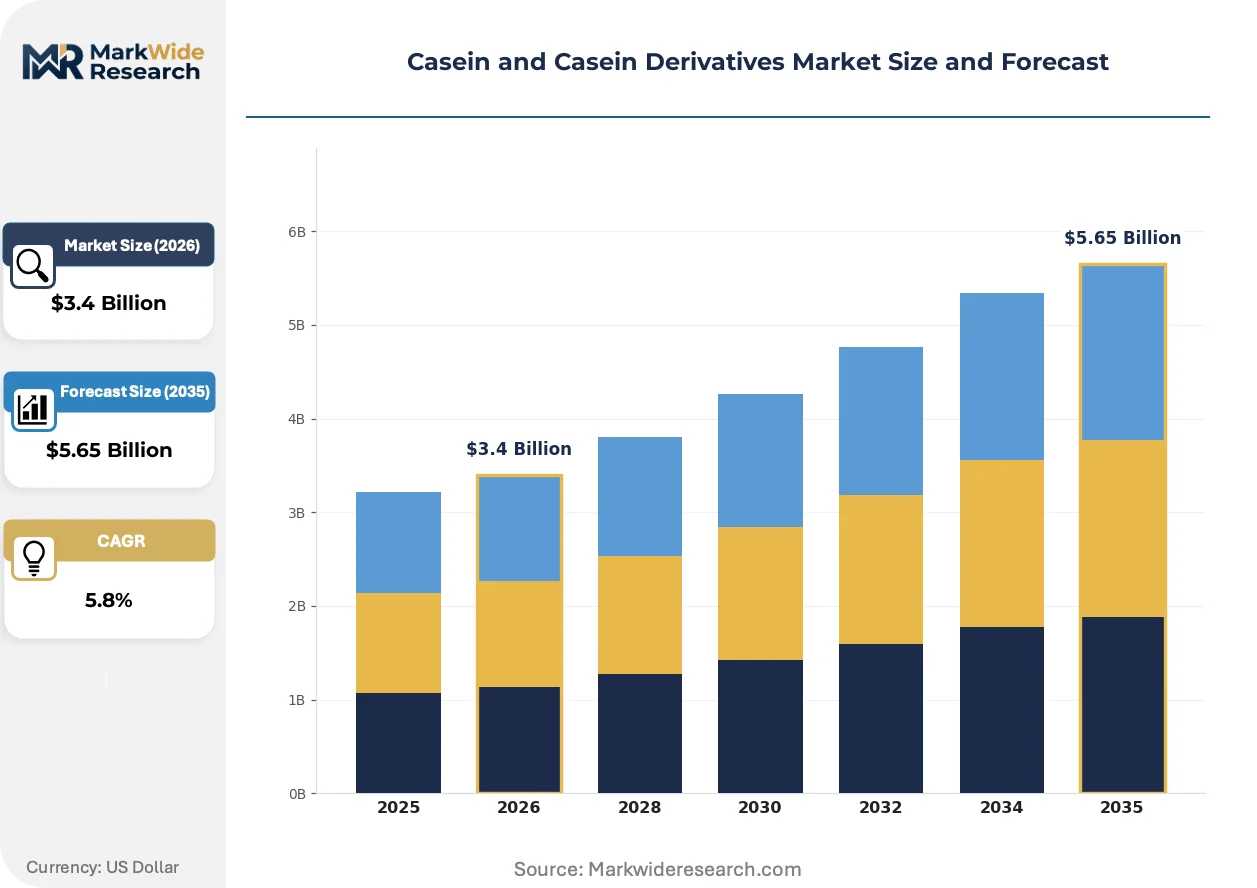
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Caseinates, Hydrolyzed Casein, Micellar Casein Application: Dairy Products, Bakery Products, Dietary Supplements, Infant Nutrition End User: Food & Beverage Industry, Nutraceuticals, Pharmaceuticals, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Nestlé, Fonterra Co-operative Group, Arla Foods, Royal FrieslandCampina, Groupe Lactalis, Kerry Group, Saputo, Danone, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein and Casein Derivatives Market Strategic Shifts
Membrane filtration advances and precision fermentation are disrupting traditional acid/rennet precipitation methods. These technologies promise cleaner protein structures while reducing wastewater and mineral acid consumption in dairy processing operations.
Microfiltration ceramic membrane systems are virtualizing conventional casein isolation by separating native micelles without chemical denaturation. Premium sports nutrition brands in Germany and Australia adopt these ingredients for "undenatured" label claims. This technology is virtualizing the premium tier of the protein ingredient market, compressing price premiums for acid-precipitated alternatives.
EFSA's 2023 updated guidance on novel protein safety assessments tightens requirements for fermentation-derived dairy proteins. Precision fermentation entrants must now submit comprehensive allergenicity data comparable to extracted casein benchmarks. Infant formula applicants face extended evaluation timelines, advantaging incumbent dairy processors with established safety dossiers.
Direct contracting between ingredient suppliers and contract manufacturers is displacing traditional distributor intermediaries in North American sports nutrition. Bulk buyers consolidate purchase volumes to secure lot traceability and custom micellar casein specifications. This pattern concentrates most visibly in Utah and Arizona production clusters serving direct-to-consumer protein brands.
Casein and Casein Derivatives Market Segmentation
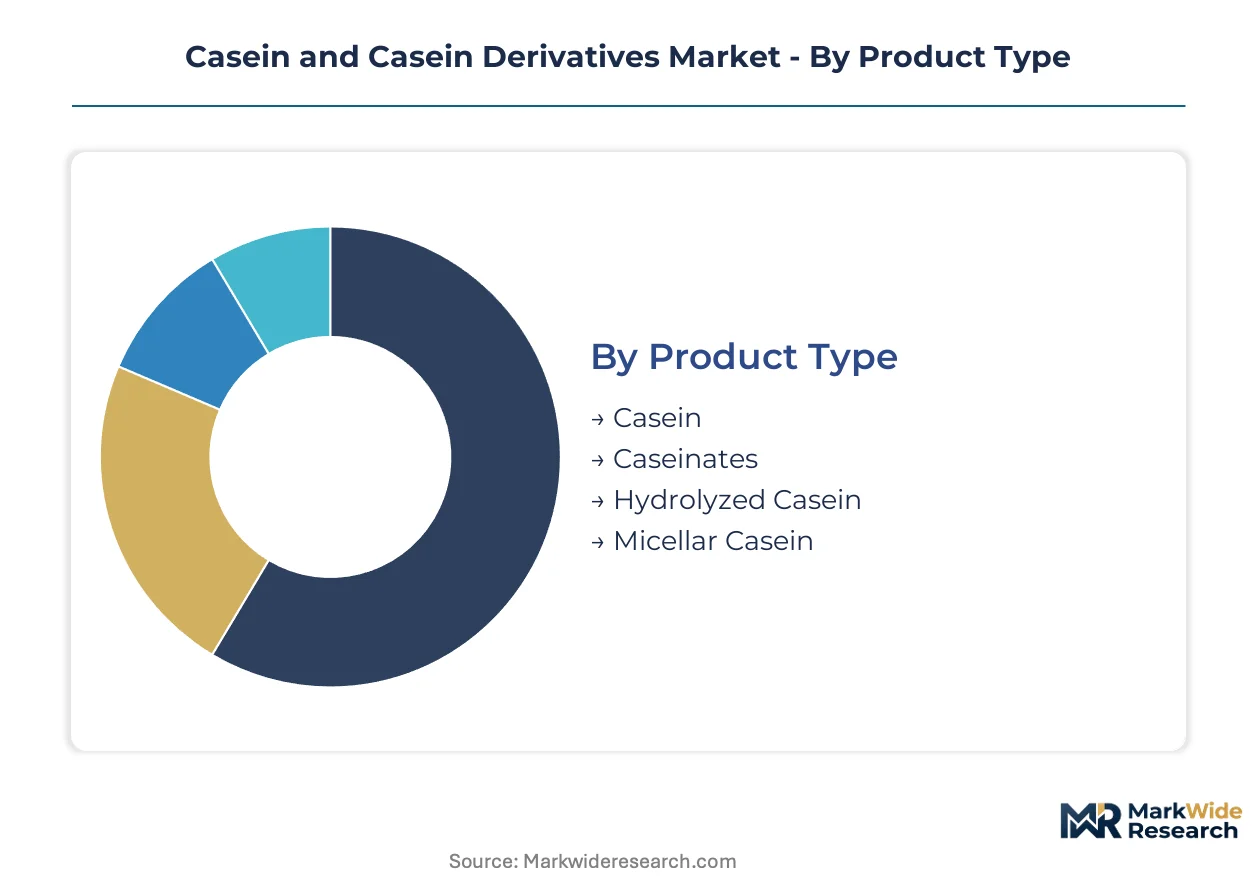
Segmentation in the casein market reveals divergent margin structures and procurement rhythms across protein fractions. Product type determines extraction complexity and pricing tiers, while application segments impose distinct regulatory qualification timelines that reshape supplier-customer relationships.
Product Type:
Casein derivatives rotate through inventory at markedly different velocities, with hydrolyzed variants turning fastest due to medical nutrition spot-buying, while micellar casein ties up working capital through long-term sports nutrition contracts.
- Casein:Acid or rennet-precipitated protein containing 80-82% protein on a dry basis with bound calcium-phosphorus micelles. Demand concentrates in industrial cheesemaking and processed meat applications across Germany and Italy, constrained by skim milk powder price volatility that compresses processor margins during peak dairy input cycles.
- Micellar Casein:Native protein structure preserved through membrane filtration without chemical denaturation, enabling slow-release amino acid delivery. Sports nutrition manufacturers in Australia and Germany prioritize this grade for clean-label formulation mandates, with direct contracting displacing traditional distributor channels in Utah and Arizona production clusters.
- Caseinates:Soluble salts of casein (sodium, calcium, potassium) valued for emulsification versatility across beverages and meat analogues.
- Hydrolyzed Casein:Enzymatically broken peptide fractions optimized for hypoallergenic infant formula and clinical enteral nutrition applications.
Caseinates dominate installed base through decades of industrial formulation integration. Micellar casein is where expansion concentrates as premium sports nutrition brands reformulate around native protein credentials.
Application:
Margin pools stratify sharply across these four end-uses, with infant nutrition commanding qualification-intensive premium pricing while bakery applications compete on cost-in-use against plant protein substitutes.
- Infant Nutrition:Hypoallergenic and minimally processed ingredient specifications dominate procurement criteria, with SAMR registration requirements in China favoring established suppliers with localized quality documentation. Domestic Chinese manufacturers accelerate captive micellar casein sourcing to reduce import dependency.
- Dietary Supplements:Direct-to-consumer protein brands in North America consolidate purchase volumes to secure lot traceability and custom specifications, compressing distributor intermediaries.
- Dairy Products:Processed cheese and yogurt applications leveraging casein for texture and meltability.
- Bakery Products:Emulsification and water-binding functions increasingly contested by pea and fava protein isolates at lower cost-in-use.
Infant nutrition anchors value generation through concentrated margin pools. Dietary supplements represent the segment gaining share fastest as direct procurement patterns reshape supplier relationships.
End User:
Customer type determines technical service intensity and contract structure, with pharmaceutical buyers demanding batch documentation that sports nutrition brands rarely require.
- Sports Nutrition:Reformulation cycles accelerate around clean-label mandates, with micellar casein's unaltered micelle configuration satisfying transparency expectations without functional compromise.
- Pharmaceuticals:Enteral and clinical peptide formulations requiring FDA GRAS pathway streamlining for hydrolyzed casein variants to expand addressable indications.
- Food & Beverage Industry:Processed meat, dairy, and beverage applications prioritizing emulsification stability and cost predictability.
- Nutraceuticals:Functional health products incorporating slow-digesting protein for satiety and metabolic management claims.
Sports Nutrition leads volume absorption through reformulation velocity. Pharmaceuticals is where contract value concentrates due to qualification barriers and reimbursement-linked pricing.
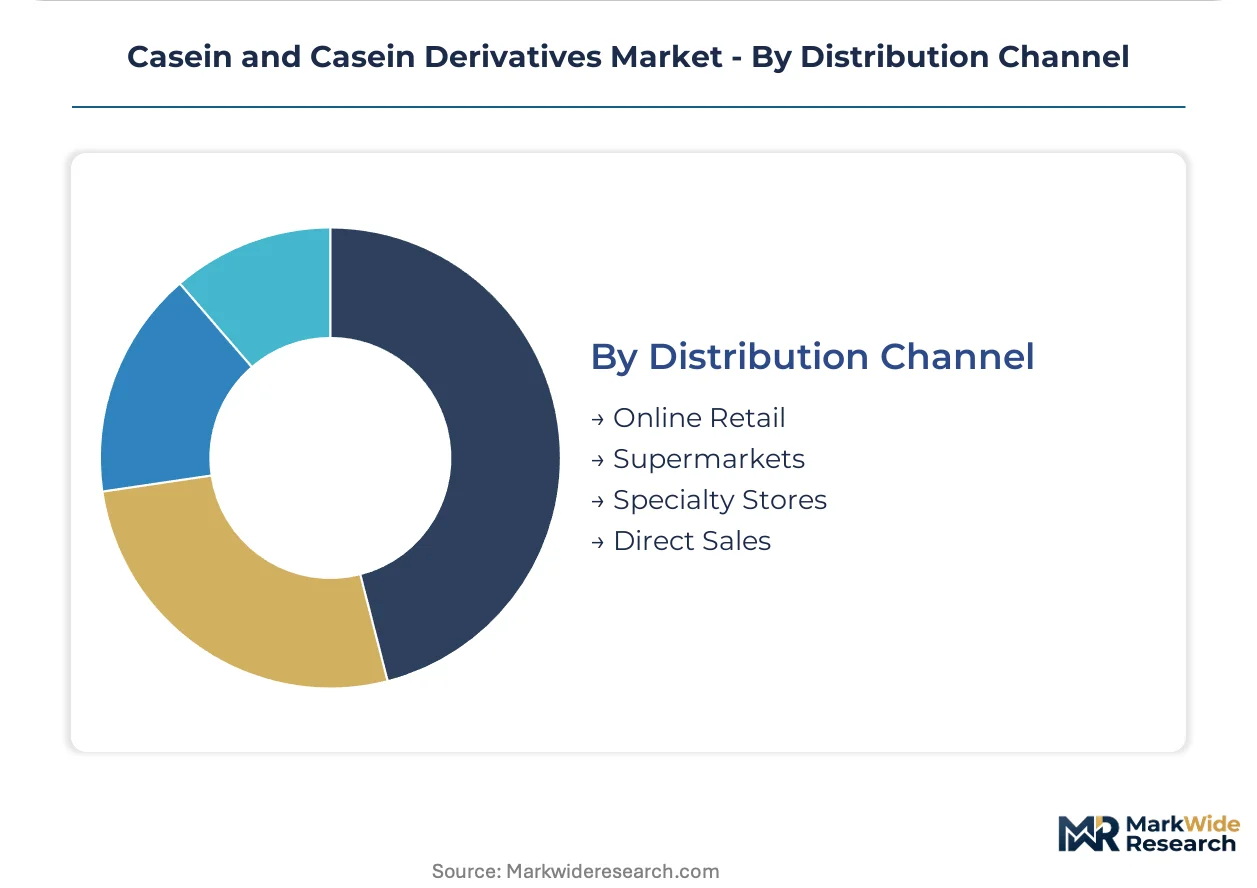
Distribution Channel:
Channel selection correlates directly with buyer scale and specification complexity, fragmenting across four distinct service models.
- Direct Sales:Bulk ingredient procurement consolidating around vertically integrated dairy cooperatives, with lot traceability and custom micellar casein specifications as table stakes for sports nutrition contract manufacturers.
- Online Retail:E-commerce platforms serving small-batch formulators and regional brands with standardized caseinate grades and rapid fulfillment.
- Supermarkets:Mass-market consumer packaged goods leveraging established dairy ingredient distribution networks.
- Specialty Stores:Niche organic and clean-label channels catering to premium positioned regional brands.
Direct Sales captures the majority of volume value. Online Retail is expanding most quickly as small-brand proliferation outpaces traditional distributor reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork Strategy is redirecting capital toward low-carbon dairy processing infrastructure. National regulators across major producing regions are tightening protein content verification protocols while infant formula manufacturers accelerate captive sourcing strategies.
United States
Sports nutrition contract manufacturers in Utah and Arizona production clusters consolidate direct procurement volumes for lot traceability. The FDA oversees GRAS status and labeling requirements for casein ingredients in food and supplement channels. Direct-to-consumer protein brands bypass traditional distributor intermediaries through bulk purchasing agreements with vertically integrated suppliers.
China
Domestic infant formula manufacturers accelerate micellar casein sourcing to reduce import dependency amid supply security priorities. SAMR registration requirements favor established suppliers with localized quality documentation. Processing capacity concentrates in coastal provinces serving premium hypoallergenic formulation demand.
Germany
Premium sports nutrition brands adopt microfiltration-derived ingredients for clean-label "undenatured" protein claims. EFSA establishes maximum residue limits and novel food assessments across European member states. Industrial cheesemaking clusters in Bavaria and Baden-Württemberg anchor backward-integrated caseinate production.
India
BIS certification requirements under IS 11921 standards constrain import flows and shape local sourcing strategies. FSSAI enforcement tightens on unlabeled dairy derivatives entering food manufacturing channels. Domestic casein manufacturers capture share from detained shipments through compliant production investments.
New Zealand
Fonterra Co-operative Group leverages its milk pool to anchor premium micellar casein supply chains across Asia-Pacific. Auction price volatility for skim milk powder transmits rapidly through derivative pricing structures. Processing cooperatives consolidate volume contracts with multinational infant formula manufacturers.
Casein and Casein Derivatives Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated dairy cooperatives with captive milk pool access. Large processors compress supplier margins while concentrating micellar casein availability. Three archetypes dominate: cooperative-owned processors with upstream milk control, diversified dairy multinationals with backward integration, and specialized ingredient suppliers with hydrolyzed protein expertise. Competitive moves center on membrane filtration capacity expansion and direct contracting displacement of distributor channels.
Within the cooperative processor tier, Fonterra Co-operative Group and Royal FrieslandCampina exemplify milk-pool-anchored supply chain control. Groupe Lactalis occupies a position representing diversified dairy conglomerate integration across European caseinate production. These three entities anchor the supply concentration reshaping procurement negotiations for sports nutrition and infant formula manufacturers.
| Leading Market Players |
|---|
| Nestlé |
| Fonterra Co-operative Group |
| Arla Foods |
| Royal FrieslandCampina |
| Groupe Lactalis |
| Kerry Group |
| Saputo |
| Danone |
| Glanbia |
| Others |
Value Chain & Pricing Dynamics
New Zealand's Waikato dairy processing cluster concentrates micellar casein membrane filtration capacity, translating upstream milk pool control into pricing leverage over Asia-Pacific infant formula manufacturers negotiating long-term offtake agreements.
Pricing Analysis
Certification level creates the primary spread between premium micellar casein and standard acid-precipitated grades, with FDA GRAS-affirmed and EFSA novel-food-cleared variants commanding substantial premiums over commodity caseinates. Pricing stratifies across premium, standard, and economy tiers based on protein content verification method and lot traceability documentation. Cost compression in standard caseinates is intensifying because pea protein isolates achieve functional parity in emulsification applications at lower cost-in-use. Sports nutrition contract manufacturers in Utah and Arizona production clusters demonstrate the highest price sensitivity, while pharmaceutical enteral nutrition buyers prioritize qualification documentation over unit economics.
Supply Chain Analysis
Single-source vulnerability dominates supply chain risk as Groupe Lactalis and FrieslandCampina control majority European caseinate capacity, forcing meat analogue formulators into 18-month qualification timelines for alternative sourcing. Geographic supply concentrates in New Zealand, France, and the Netherlands, with membrane filtration equipment dependencies resting on German and Italian engineering suppliers. Raw material economics draw from skim milk powder auction cycles, with Fonterra's GlobalDairyTrade price discovery transmitting rapidly through derivative pricing structures. Distribution runs through vertically integrated dairy cooperatives consolidating volume contracts directly with multinational infant formula manufacturers, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as dairy input prices normalize from peak commodity cycles and infant formula manufacturers rebuild inventory positions following supply security disruptions.
For Market Incumbents: Insulate margin structures by deepening backward integration into captive milk pool operations and accelerating membrane filtration capacity expansion in New Zealand and European coastal processing zones. Fonterra Co-operative Group's supply chain anchoring demonstrates how upstream control neutralizes skim milk powder price volatility threats. Certification investment in FDA GRAS self-affirmation and EFSA novel food dossiers creates switching costs that protect contract renewal rates against precision fermentation entrants. For New Entrants and Emerging Players: Pursue India BIS certification arbitrage opportunities as FSSAI enforcement tightening on unlabeled dairy derivatives creates share capture potential from detained import shipments. Domestic production investments meeting IS 11921 standards address the most penetrable geography for localized casein manufacturing. Geriatric medical nutrition in Japan and South Korea offers a defensible go-to-market angle, with PMDA and MFDS reimbursement pathways supporting sarcopenia-targeted enteral formulations that established dairy cooperatives have underdeveloped. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative processor tier concentration will accelerate as membrane filtration capital requirements exclude sub-scale competitors. Acquisition targets should prioritize specialized hydrolyzed casein manufacturers with established infant formula safety dossiers and medical nutrition regulatory clearances. The signal to watch is precision fermentation-derived dairy protein EFSA approval timelines, which would compress extraction-based pricing premiums and trigger distressed asset opportunities among traditional processors.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Microfiltration ceramic systems enable "undenatured" label claims that command premium positioning in German and Australian sports nutrition. |
| Backward Integration into Milk Pool Control | Captive supply of raw skim milk insulates processor margins from GlobalDairyTrade auction volatility transmitted through derivative pricing. |
| FDA GRAS Self-Affirmation Investment | Accelerated regulatory pathways for hydrolyzed casein variants expand addressable indications in clinical peptide formulations. |
| Direct Sales Channel Consolidation | Bulk procurement agreements with Utah and Arizona contract manufacturers displace distributor intermediaries and secure lot traceability. |
| India BIS Certification Compliance | IS 11921 standards alignment captures share from detained import shipments as FSSAI enforcement tightens on unlabeled derivatives. |
Study Parameters
A standing panel of dairy cooperative procurement directors, sports nutrition contract manufacturing executives, infant formula regulatory affairs leads, and membrane filtration equipment engineers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from Fonterra GlobalDairyTrade auction data, EFSA novel food safety assessments, FDA GRAS notification databases, and BIS IS 11921 certification records. Bottom-up volume modeling triangulated against top-down dairy protein trade flow analysis.
Scenario-bracketing framed projections across the analysis window, with base, upside, and downside cases reflecting skim milk powder price cycle positions and precision fermentation regulatory approval trajectories. Segmentation dimensions modeled included product type hierarchy, application margin pools, end-user technical service intensity, and distribution channel service models. CAGRs derived from fitted growth curves applied to validated baseline estimates, with infant formula localization rates and sports nutrition direct procurement penetration as key forecast inputs.
Sensitivities concentrate around EFSA precision fermentation guidance revisions, China SAMR registration requirement changes, and New Zealand dairy cooperative consolidation announcements. Forecasts reflect documented assumptions regarding membrane filtration technology adoption curves and plant protein substitution elasticity in bakery applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market