
 Rizatriptan Market | 2026-2036
Rizatriptan Market Size, Share, and Industry Trends Forecast 2026-2036
Rizatriptan Market Insights
Indian pharmaceutical exporters is broadening output of rizatriptan active pharmaceutical ingredients to serve regulated markets. Merck leverages its original brand equity in the triptan class through sustained physician outreach programs. Teva anchors the generic segment with vertically integrated manufacturing across API and finished dosage forms. Sun Pharma competes on cost structure through its Mumbai-based formulation facilities.
Rizatriptan functions as a selective 5-HT1B/1D receptor agonist with a molecular weight of 269.4 g/mol, formulated for acute migraine relief through vasoconstriction of cranial blood vessels and inhibition of pro-inflammatory neuropeptide release. Tablet formulations dominate current prescription volumes due to established reimbursement codes and patient familiarity, while orally disintegrating tablets represent the fastest-expanding category among pediatric and geriatric populations who experience dysphagia. Retail pharmacies capture the largest margin pool through direct-to-patient dispensing and insurance adjudication services.
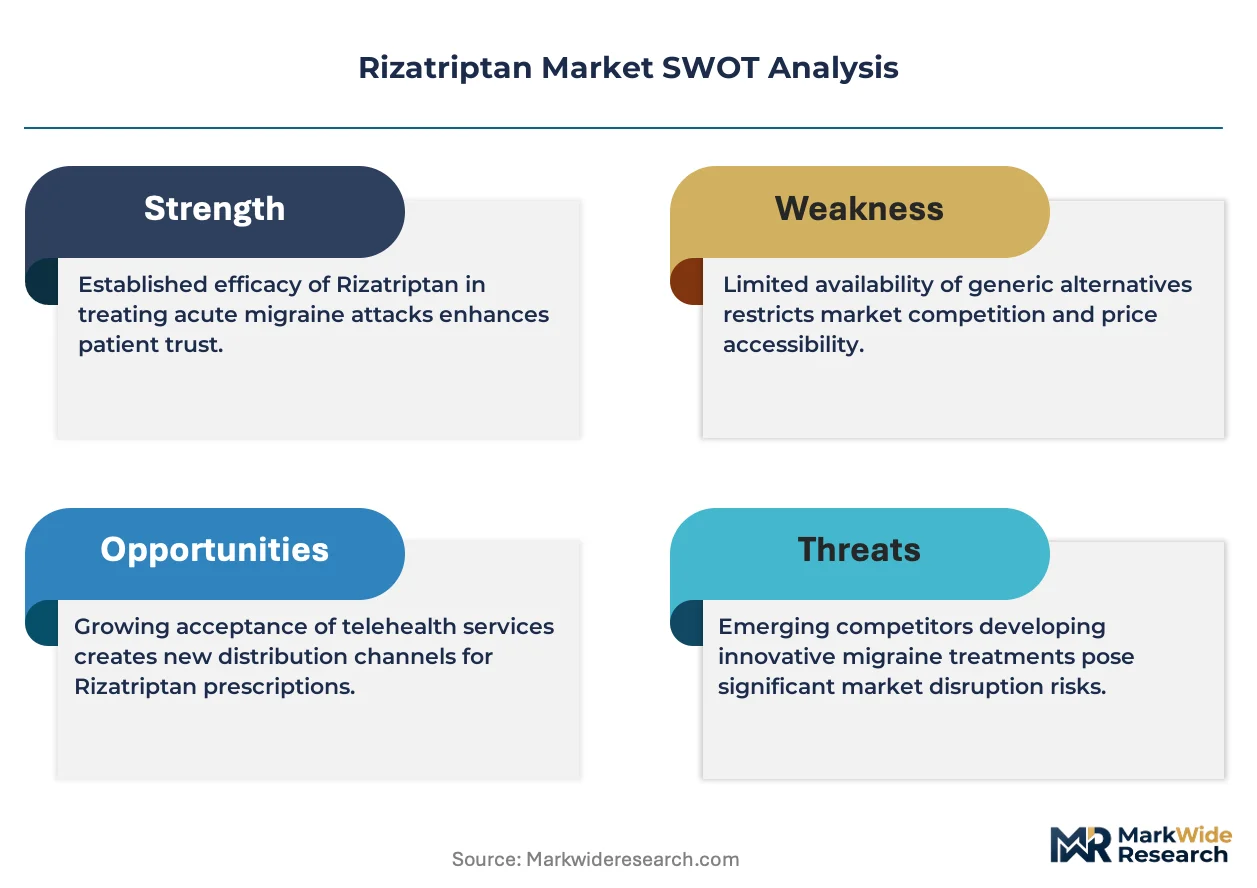
The FDA regulates rizatriptan through its Center for Drug Evaluation and Research under new drug application and abbreviated new drug application frameworks, while the EMA enforces centralized marketing authorization requirements across EU member states. India's CDSCO mandates bioequivalence studies for generic triptan approvals, shaping the competitive landscape for export-oriented manufacturers. Stakeholders must monitor patent cliff dynamics and therapeutic substitution policies as payers tighten migraine management formularies.
Market Dynamics
The rizatriptan market pivots on generic substitution acceleration, where FDA abbreviated new drug application pathways compress approval timelines and erode originator brand persistence in acute migraine therapy.
Growth Catalysts
- FDA ANDA Pathway:The abbreviated new drug application framework truncates generic market entry timelines, enabling rapid therapeutic substitution in retail pharmacy channels.
- Pediatric Dysphagia Demand:Orally disintegrating tablet formulations address swallowing difficulties in geriatric and pediatric populations, expanding addressable prescription volumes.
- Indian API Manufacturing:CDSCO-mandated bioequivalence studies for export markets position Indian active pharmaceutical ingredient producers to serve regulated jurisdictions.
Market Restraints
- API Supply Concentration:Rizatriptan active pharmaceutical ingredient production clusters in select Indian and Chinese manufacturing zones, creating single-source vulnerability.
- Reimbursement Compression:Payer formulary tightening and therapeutic substitution policies squeeze retail pharmacy margins on generic triptan dispensing.
- Sumatriptan Substitution:First-generation triptan alternatives with deeper generic penetration and lower acquisition costs threaten rizatriptan volume retention.
Strategic Opportunities
- EU Centralized Authorization:EMA marketing authorization requirements create a unified pathway for generic manufacturers to access 27 member state markets simultaneously.
- Direct-to-Patient Channels:Telehealth-integrated pharmacy platforms bypass traditional retail intermediaries, capturing margin and adherence data.
- Pediatric Indication Expansion:Regulatory submissions for adolescent migraine populations unlock prescriber segments with limited acute therapeutic options.
Industry Challenges
- Bioequivalence Study Backlogs:CDSCO and other national regulators face capacity constraints in reviewing generic triptan bioequivalence protocols, delaying market entry.
- Formulation Complexity:Orally disintegrating tablet manufacturing requires specialized lyophilization and taste-masking capabilities that constrain supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rizatriptan Market |
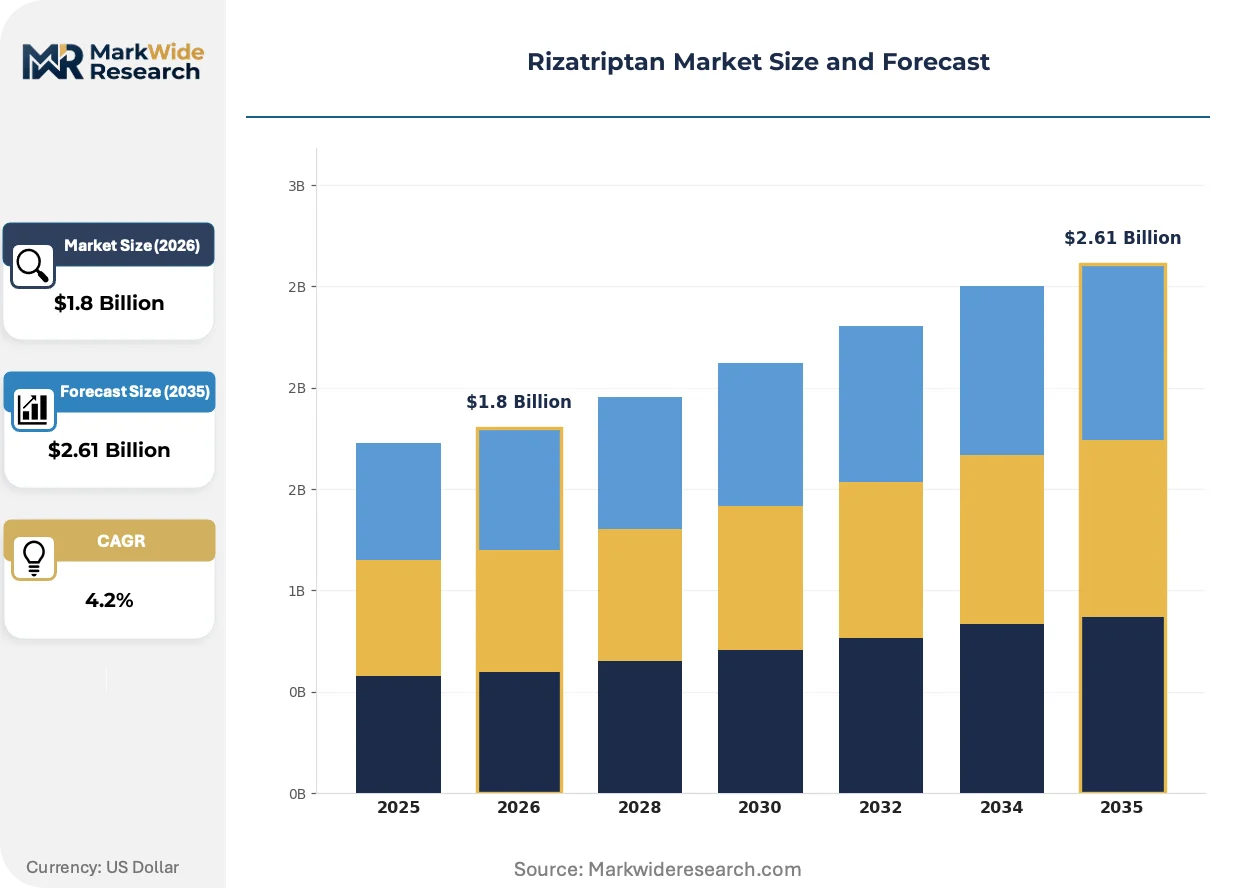
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Orally Disintegrating Tablets, Injectable, Nasal Spray Therapy Area: Migraine, Headaches, Tension-Type Headaches, Neuropathic Pain End User: Hospitals, Clinics, Homecare, Retail Pharmacies Distribution Channel: Online Pharmacies, Hospital Pharmacies, Retail Outlets, Wholesale Distributors |
| Companies Covered | Merck, Teva, Pfizer, Novartis, Mylan, Sun Pharma, Hubei Ouly Pharmaceutical, GSK, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rizatriptan Market Trends and Innovations
Formulation science and regulatory pathway optimization are compressing development cycles while reshaping competitive entry patterns in acute migraine therapeutics.
Continuous manufacturing technologies are automating solid dosage form production, enabling real-time release testing and reducing batch-to-batch variability. Generic manufacturers in India and China are retrofitting facilities with these platforms to meet FDA process analytical technology expectations. This automation is compressing cost structures and accelerating response to spot shortages in retail pharmacy supply chains.
The FDA's Quality Management Maturity program rewards manufacturers demonstrating advanced quality systems with abbreviated inspection frequencies and expedited review designations. Generic rizatriptan producers investing in these frameworks gain competitive positioning in contract negotiations with pharmacy benefit managers. Facilities with mature quality ratings secure preferred supplier status in United States retail channel procurement.
Patients are consolidating prescription fulfillment through integrated health system pharmacies and mail-order channels, fragmenting traditional independent retail pharmacy triptan volumes. Pharmacy benefit managers are steering acute migraine therapy toward preferred formulary tiers with mandatory generic substitution. This consolidation is most pronounced in United States metropolitan markets where vertical health plan-pharmacy integration dominates local dispensing.
Rizatriptan Market Segmentation
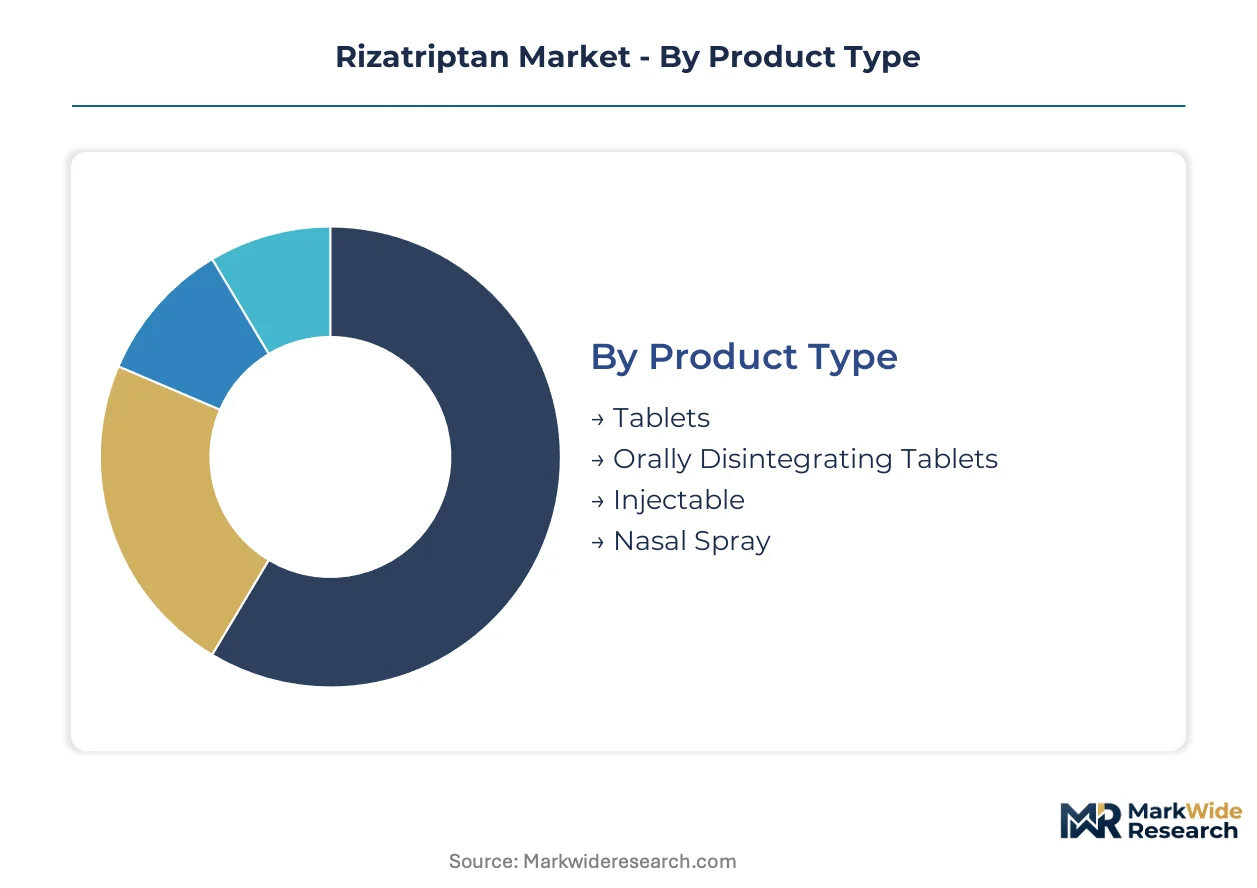
Rizatriptan prescribing patterns fragment across formulation technologies, clinical settings, and fulfillment channels. Each segmentation axis reveals distinct margin structures, regulatory pathways, and competitive entry barriers that shape manufacturer strategy.
Product Type:
Formulation upgrades drive replacement cycles as patients and payers balance onset speed against convenience and reimbursement access.
- Tablets:Compressed solid dosage forms containing rizatriptan benzoate or free base, stabilized with standard excipients. United States retail pharmacies dispense tablets for the majority of acute migraine prescriptions due to established insurance adjudication codes and patient familiarity with oral administration.
- Orally Disintegrating Tablets:Lyophilized wafer formulations utilizing taste-masked active pharmaceutical ingredient complexes that dissolve on the tongue without water. Pediatric and geriatric populations with dysphagia drive demand concentration here, expanding addressable volumes among patients who cannot swallow conventional solids during acute migraine attacks.
- Injectable:Sterile parenteral solutions for subcutaneous administration requiring cold chain distribution and clinical supervision.
- Nasal Spray:Metered-dose aqueous formulations delivering rapid systemic absorption through nasal mucosa.
Volume placements concentrate in Tablets; the faster expansion belongs to Orally Disintegrating Tablets.
Therapy Area:
Cost tier differentiation separates acute rescue therapy from chronic prophylactic regimens, with reimbursement intensity varying by diagnostic code specificity.
- Migraine:FDA-approved indication for acute treatment of migraine with or without aura, supported by extensive clinical trial data establishing 5-HT1B/1D receptor agonist efficacy. United States neurologists and primary care physicians prescribe rizatriptan predominantly for this indication, with prior authorization requirements tightening for non-migraine headache diagnoses.
- Headaches:Off-label utilization for severe headache presentations lacking formal migraine diagnosis, often facing reimbursement denial.
- Tension-Type Headaches:Non-indicated use limited by payer formulary restrictions and competing analgesic alternatives.
- Neuropathic Pain:Experimental and compassionate-use applications outside established guidelines.
Prescription volumes cluster in Migraine; Headaches claims the steepest expansion trajectory among off-label categories.
End User:
Customer type determines procurement sophistication, with integrated health systems negotiating directly against fragmented independent practice purchasing.
- Hospitals:Acute care facilities managing status migrainosus and emergency department presentations requiring rapid therapeutic intervention. United States hospital formularies stock rizatriptan for discharge prescribing, though inpatient administration is rare given oral bioavailability and outpatient appropriateness.
- Clinics:Outpatient neurology and headache specialty practices providing diagnosis and ongoing management.
- Homecare:Self-administered acute therapy following initial prescription and patient education.
- Retail Pharmacies:Community and chain pharmacy dispensing with direct-to-patient fulfillment and insurance processing.
Volume concentrates in Retail Pharmacies; Homecare is expanding most quickly as telehealth prescribing normalizes.
Distribution Channel:
Supply concentration in wholesale distribution creates margin pressure, while direct channels capture adherence data and reduce intermediation costs.
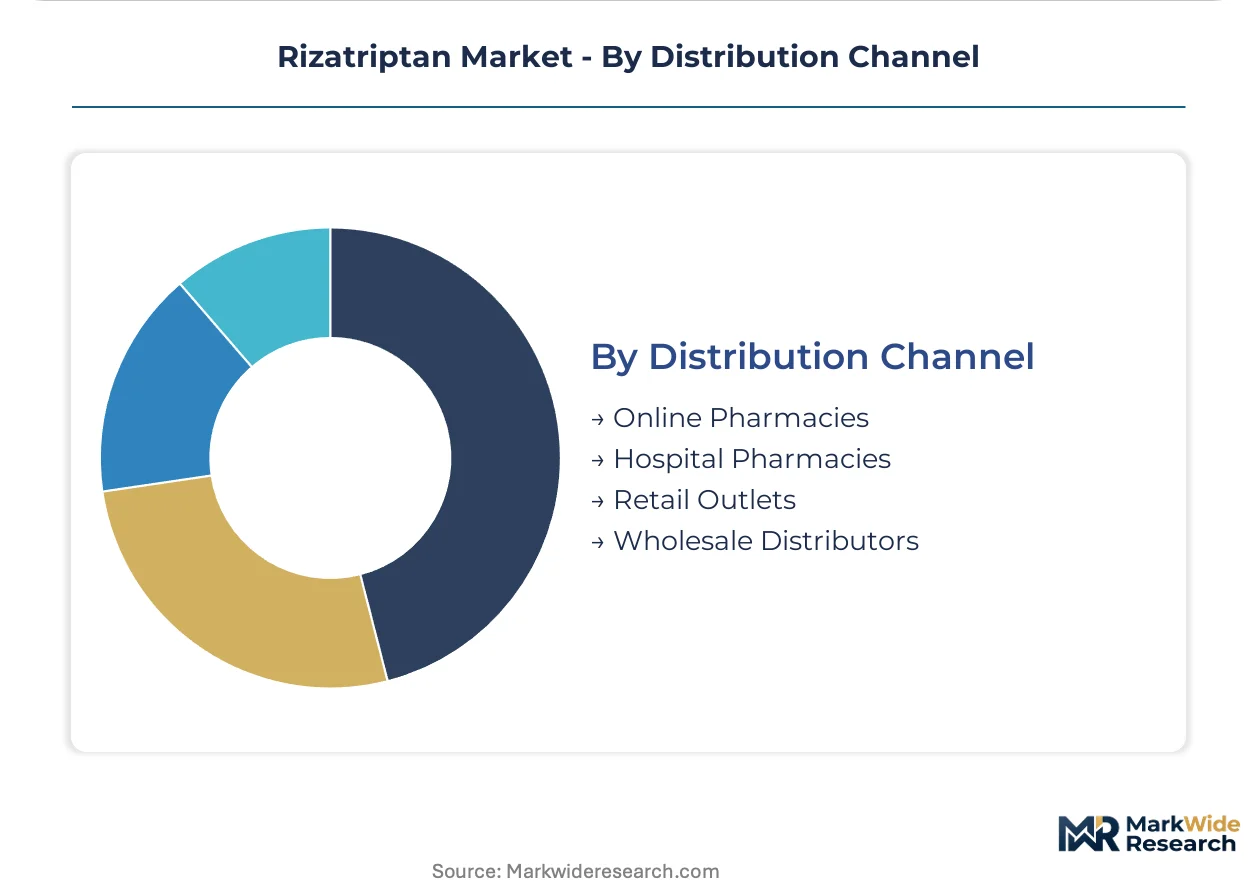
- Online Pharmacies:Digital fulfillment platforms integrating telehealth consultation with mail-order dispensing. United States pharmacy benefit managers are steering volume here through mandatory mail-order mandates for maintenance medications, though acute migraine therapy remains partially exempt due to immediacy requirements.
- Hospital Pharmacies:Captive dispensing operations serving inpatient and emergency department populations.
- Retail Outlets:Brick-and-mortar community pharmacies with immediate patient access and face-to-face counseling.
- Wholesale Distributors:McKesson, AmerisourceBergen, and Cardinal Health intermediating manufacturer-to-pharmacy logistics.
Volume placements concentrate in Retail Outlets; Online Pharmacies gains share fastest as digital health integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for rizatriptan clusters in Gujarat and Maharashtra, where CDSCO-registered facilities export intermediates to regulated markets. United States retail pharmacies absorb the majority of finished dosage imports.
United States
Retail pharmacy chains and integrated health systems drive prescription volumes through formulary-tier placement negotiations. FDA ANDA pathways compress generic entry timelines, accelerating therapeutic substitution. New Jersey and North Carolina host major distribution hubs for finished triptan products.
Germany
Specialty headache clinics and neurologist networks sustain demand for acute migraine therapeutics. EMA centralized marketing authorization requirements shape generic manufacturer entry strategies. The Rhine-Main pharmaceutical corridor concentrates formulation science expertise for orally disintegrating tablet technologies.
India
Export-oriented API manufacturers scale output to serve United States and European generic markets under CDSCO bioequivalence mandates. Mumbai-Pune formulation clusters produce finished dosage forms for regulated jurisdictions. Hyderabad-based contract research organizations support ANDA documentation.
China
Domestic migraine diagnosis rates rise with neurology specialty expansion in tier-one hospitals. NMPA marketing authorization pathways align with ICH guidelines for generic triptan approvals. Zhejiang and Jiangsu provinces concentrate API synthesis capacity for 5-HT receptor agonists.
United Kingdom
NHS formulary placement decisions determine reimbursement access for acute migraine therapies. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards for generic entry. London and Southeast England concentrate specialist headache service provision.
Rizatriptan Market Competitive Landscape
Global majors compete with regional champions across formulation complexity and regulatory pathway expertise. The market structure tiers between originator brand equity holders and vertically integrated generic manufacturers. Three archetypes dominate: multinational pharmaceutical conglomerates with legacy triptan portfolios, Indian and Chinese API-to-dosage integrators, and specialty generic firms focused on complex formulations. Competitive moves concentrate on bioequivalence study acceleration and lyophilization capacity expansion for orally disintegrating platforms.
Within the originator-tier, Merck anchors brand persistence through sustained physician outreach. Among vertically integrated generic manufacturers, Teva and Sun Pharma occupy positions spanning API synthesis through finished dosage distribution. These firms exemplify the cost-structure competition shaping retail pharmacy procurement.
| Leading Market Players |
|---|
| Merck |
| Teva |
| Pfizer |
| Novartis |
| Mylan |
| Sun Pharma |
| Hubei Ouly Pharmaceutical |
| GSK |
| Glenmark Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
FDA Quality Management Maturity program certification gates both qualified supply and premium-tier pricing access, as manufacturers demonstrating advanced quality systems secure abbreviated inspection frequencies and preferred supplier status in United States retail channel procurement negotiations.
Pricing Analysis
Warranty and service bundling separates qualified suppliers from commodity competitors, with FDA-registered facilities commanding premium positioning through validated quality documentation and expedited review designations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and bioequivalence study completeness. Cost compression in the standard tier intensifies because Indian and Chinese manufacturers scale API output for regulated markets. Hospital procurement committees demonstrate highest price sensitivity due to formulary tightening, while specialty headache clinics show lowest sensitivity when clinical outcomes justify acquisition costs.
Supply Chain Analysis
Freight cost volatility from Gujarat and Maharashtra API clusters to United States distribution hubs shapes inventory positioning strategies for generic manufacturers. Rizatriptan active pharmaceutical ingredient production draws from India, China, and select European synthesis facilities. Key inputs include 5-HT receptor agonist intermediates, benzoate salt precursors, and lyophilization excipients for orally disintegrating formulations. Single-source vulnerability concentrates in select Indian manufacturing zones. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health wholesale networks to retail pharmacy and hospital pharmacy endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with players pursuing captive API supply to defend margin structure against generic substitution acceleration.
For Market Incumbents: Deploy lyophilization capacity expansion to defend orally disintegrating tablet positioning against emerging Indian formulation specialists. Secure preferred supplier contracts with United States pharmacy benefit managers before bioequivalence study backlogs clear. Backward integration into 5-HT agonist intermediate synthesis reduces exposure to API supply concentration in Gujarat manufacturing zones. For New Entrants and Emerging Players: Launch via telehealth-integrated pharmacy platforms to bypass wholesale distributor intermediation and capture adherence data. Target adolescent migraine populations with pediatric indication submissions, a prescriber segment with limited acute therapeutic options. White-space exists in EU centralized authorization pathways for generic manufacturers seeking simultaneous 27-member-state market access. For Investors and Strategic Acquirers: CDSCO bioequivalence study clearance acceleration is the leading indicator that Indian API-to-dosage integrators are achieving regulatory maturity for regulated market entry. Over the projection horizon, vertically integrated manufacturers with captive supply of 5-HT receptor agonist intermediates present superior acquisition profiles than standalone formulation facilities. Monitor EMA marketing authorization submission volumes as the inflection signal for European generic entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Enables orally disintegrating tablet production for dysphagia populations in United States retail channels. |
| CDSCO Bioequivalence Study Investment | Positions Indian manufacturers for FDA ANDA pathway entry into regulated generic markets. |
| Telehealth Pharmacy Platform Integration | Bypasses traditional wholesale intermediaries while capturing patient adherence data streams. |
| EMA Centralized Authorization Filing | Unlocks simultaneous 27-member-state market access for generic triptan manufacturers. |
| 5-HT Agonist Intermediate Backward Integration | Reduces single-source vulnerability in Gujarat and Maharashtra API supply clusters. |
Research Methodology
Document review covered FDA ANDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov migraine therapy protocols, and United States pharmacy benefit manager formulary databases, complemented by interviews with generic drug development executives, CDSCO regulatory affairs leads, hospital pharmacy procurement managers, and retail chain formulary directors. Secondary validation drew from SEC 10-K pharmaceutical disclosures, Indian pharmaceutical export statistics, and European customs trade data. Bottom-up prescription volume modeling triangulated against top-down market value estimates.
Market size outputs across the analysis window reflect segment-level modeling by formulation type, therapy indication, and distribution channel, with CAGRs derived from historical generic substitution rates and projected FDA approval timelines. Forecast inputs incorporated pharmacy benefit manager therapeutic substitution policy trajectories, pediatric indication expansion probabilities, and continuous manufacturing technology adoption curves.
Regulatory approval delays, API supply disruptions, and payer formulary tightening are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Oxycodone Drugs Market