
 Healthcare Blister Packaging Market | 2026-2036
Healthcare Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Blister Packaging Market Analytics
Germany is narrowing its position as a European hub for pharmaceutical packaging conversion, with Klöckner Pentaplast leveraging its PVC and PET film capacity to serve regional drug makers. Constantia Flexibles sustains a differentiated cold-form foil portfolio that anchors high-barrier applications for moisture-sensitive compounds. Amcor Plc dominates flexible healthcare packaging through integrated film-to-blister manufacturing networks across multiple European production sites.
Healthcare blister packaging comprises pre-formed plastic cavities sealed with lidding foil to protect individual doses from moisture, oxygen, and tampering, typically using PVC, PVDC, or aluminum laminates formed through thermoforming or cold-forming processes. The primary purpose is ensuring dose integrity, patient compliance, and child-resistant accessibility for oral solid dosage forms. Cold formed blisters command premium positioning due to superior barrier properties for hygroscopic APIs, while thermal formed variants occupy volume leadership in standard oral drug applications. Contract packaging organizations represent the fastest-growing end user channel as pharmaceutical outsourcing accelerates and specialized serialization requirements intensify.
FDA serialization mandates under the Drug Supply Chain Security Act and EU MDR traceability requirements are reshaping material certification and line-integration investments across manufacturing networks. REACH compliance for PVC additives and EMA guidance on extractables and leachables further constrain substrate selection and supplier qualification timelines. Stakeholders must monitor evolving pharmacopeial standards for plastic packaging materials and calibrate capacity investments against regional regulatory divergence in serialization deadlines and barrier-performance testing protocols.
Market Dynamics
Pharmaceutical serialization mandates under the Drug Supply Chain Security Act and EU MDR are forcing packaging converters to rebuild production lines around track-and-trace integration, compressing supplier qualification timelines and favoring integrated film-to-blister manufacturers with captive serialization capability.
Growth Catalysts
- FDA DSCSA serialization deadlines:Unit-dose formats with embedded traceability layers capture preference as drug makers pre-empt compliance requirements for 2023-2028 phased implementation.
- Contract packaging organizations:Pharmaceutical outsourcing accelerates demand for specialized cold-formed blister capacity with integrated serialization and quality release functions.
- PVDC-coated PVC films:Intermediate barrier solutions bridge cost-performance gaps for moisture-sensitive generics, expanding addressable substrate volumes.
Market Restraints
- Aluminum cold-form foil supply concentration:European rolling mill capacity constraints create input volatility for high-barrier applications.
- REACH additive restrictions:Phthalate plasticizer phase-outs in PVC formulations force reformulation cycles and supplier requalification.
- Extractables testing burdens:EMA guidance on leachables extends validation timelines for new material combinations.
Strategic Opportunities
- India pharmaceutical export packaging:CDSCO-aligned contract packagers seek cold-form capacity for hygroscopic API export formulations.
- Paper-based blister alternatives:Fiber-derived substrates converge with barrier coating technologies to serve EU Green Deal procurement preferences.
- Direct-to-pharmacy distribution:Hospital and retail pharmacy chains consolidate purchasing, creating channel leverage for integrated packaging suppliers.
Industry Challenges
- Serialization engineer scarcity:Line integration specialists with combined mechanical and software validation skills command premium compensation.
- Legacy thermoformer retrofit complexity:Brownfield sites face downtime risk when embedding vision systems and aggregation hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Blister Packaging Market |
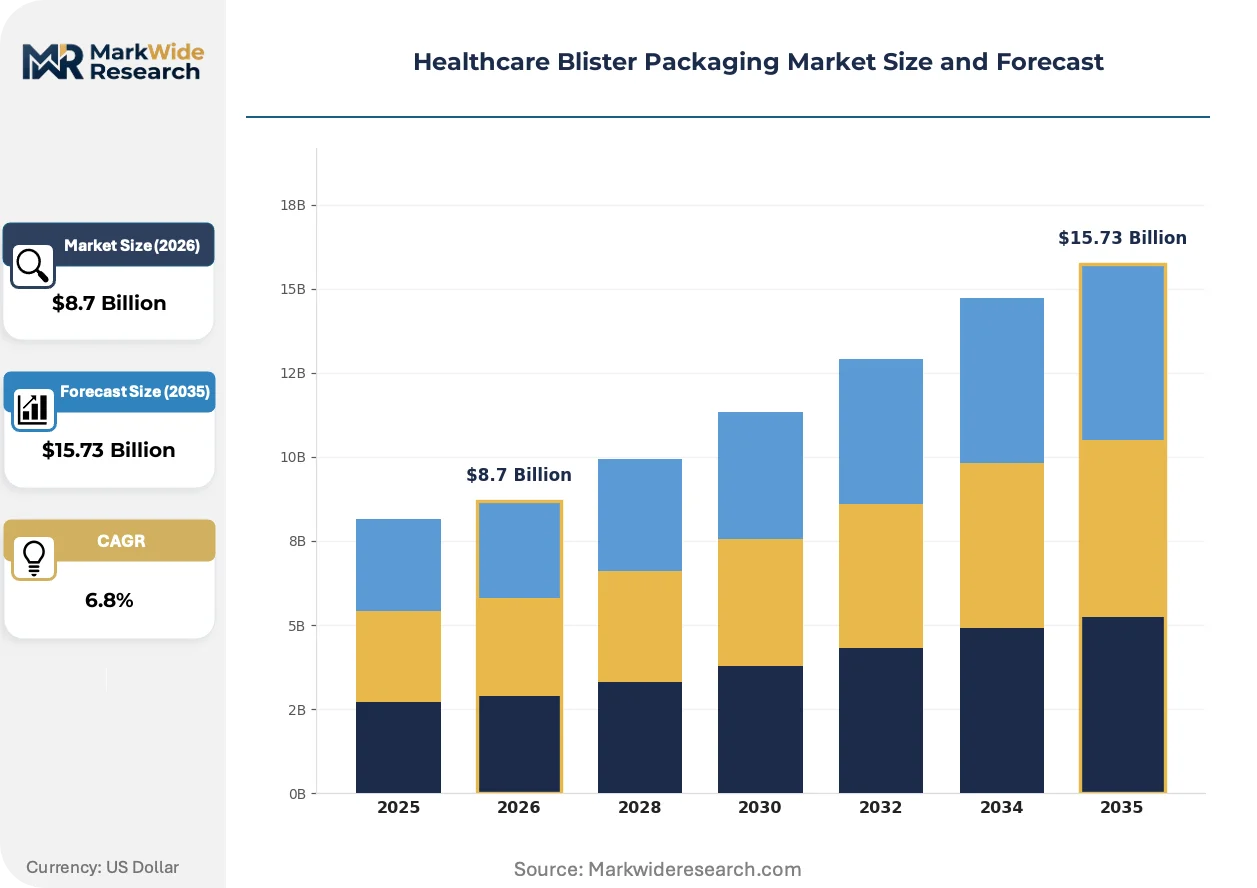
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Formed Blisters, Cold Formed Blisters, Push-Through Blisters, Standard Blisters Material: Polyvinyl Chloride, Polyethylene, Aluminum Foil, Paperboard End User: Pharmaceutical Companies, Medical Device Manufacturers, Contract Packaging Organizations, Retail Pharmacies Packaging Type: Single Dose Packs, Multi-Dose Packs, Child-Resistant Packs, Blister Cards |
| Companies Covered | Amcor Plc, Constantia Flexibles, Klöckner Pentaplast, Sonoco Products Company, WestRock Company, UFlex Limited, Winpak Ltd., TekniPlex, CCL Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Blister Packaging Market Evolving Landscape
Active pharmaceutical ingredient sensitivity profiles and sustainability procurement criteria are simultaneously pulling substrate selection toward higher-performance barriers and lower-carbon footprints, creating tension between functional requirements and material substitution timelines.
Multi-layer coextruded films with discrete ethylene vinyl alcohol barrier cores are hybridizing traditional PVC and aluminum laminate structures. Generic drug manufacturers in Central Europe adopt these substrates at accelerating pace for moisture-sensitive tablet lines. The technology is hybridizing cost structures across mid-tier barrier applications, compressing pricing premiums previously captured by cold-form foils.
EU MDR traceability requirements now mandate Unique Device Identification-equivalent serialization for pharmaceutical packaging at the item level. Manufacturers must integrate aggregation software with physical line hardware before November 2025 deadlines. High-volume oral solid dosage facilities in Germany and the Netherlands face the steepest compliance capital requirements.
Hospital procurement consortia are consolidating blister packaging specifications across therapeutic categories, unbundling legacy supplier relationships. Regional pharmacy buying groups in France and Italy now specify barrier performance tiers rather than substrate brands. This concentration is most visible in oncology and cardiovascular therapeutic verticals where compliance packaging carries reimbursement implications.
Healthcare Blister Packaging Market Segmentation
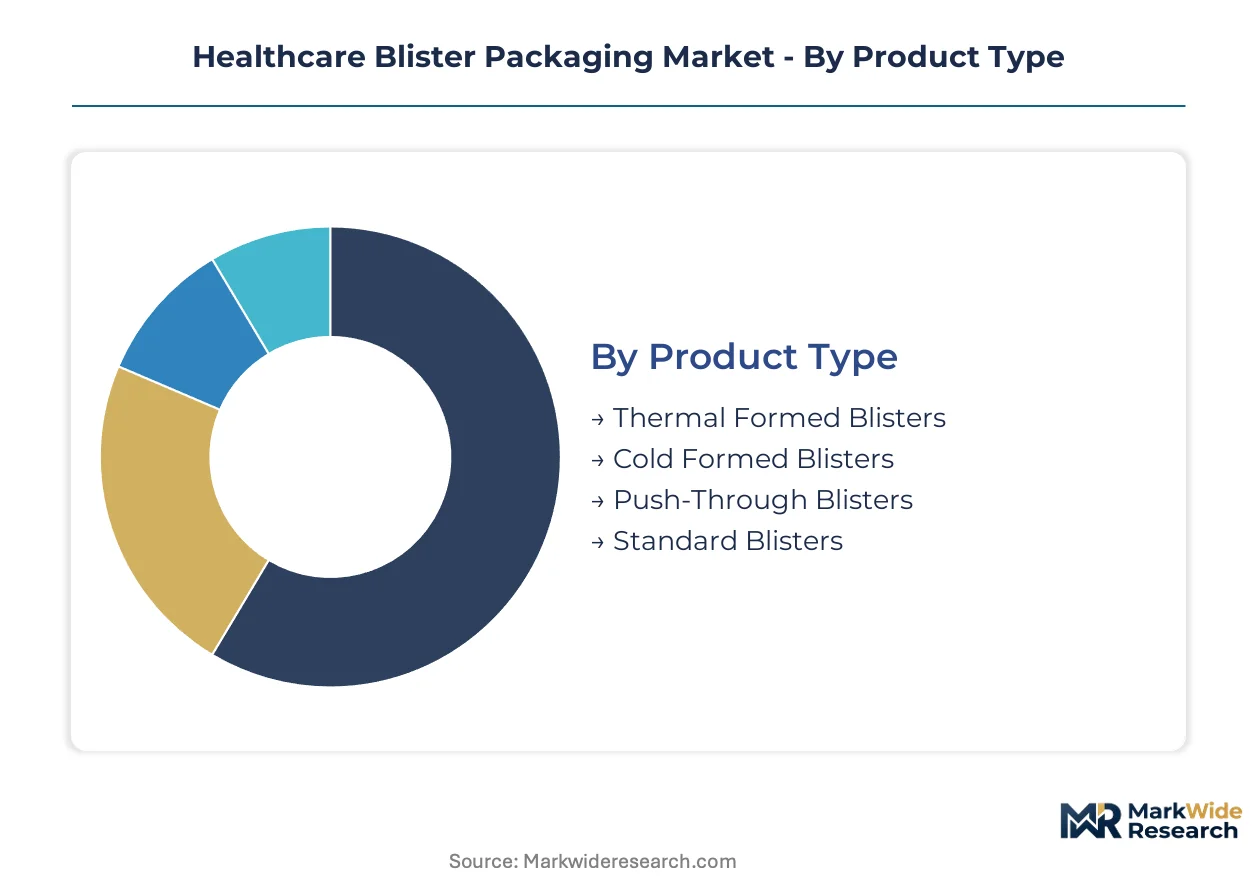
Healthcare blister packaging segmentation reflects divergent barrier requirements across oral solid dosage forms and tightening regulatory mandates for traceability. Material selection and forming technology choices determine compliance pathways for moisture-sensitive APIs versus standard generics.
Product Type:
Mature thermoforming technologies dominate volume production while cold-forming processes capture premium positioning for hygroscopic compounds.
- Thermal Formed Blisters:PVC or PET films heated and vacuum-formed into cavities, then heat-sealed with lidding foil. Demand concentrates in high-volume oral solid dosage lines across Germany and the Netherlands where standard barrier performance suffices for non-hygroscopic tablets.
- Cold Formed Blisters:Aluminum-based laminate structures mechanically formed at ambient temperatures without heat exposure. Pharmaceutical companies in Switzerland and Austria specify these for moisture-sensitive APIs where oxygen and water vapor transmission rates must remain below critical thresholds.
- Push-Through Blisters:Standard lidding foil designed for manual tablet extraction through finger pressure.
- Standard Blisters:Basic cavity-and-foil configuration without specialized child-resistance or senior-friendly features.
Thermal Formed Blisters handle the majority of throughput; Cold Formed Blisters is the fastest mover on share.
Material:
Cost tier stratification separates commodity substrates from specialized barrier laminates with EMA extractables certification.
- Polyvinyl Chloride:Baseline thermoforming substrate offering clarity, processability, and established pharmacopeial compliance. REACH additive restrictions on phthalate plasticizers are forcing reformulation cycles at European compounders.
- Aluminum Foil:Impermeable barrier layer in cold-form laminates and lidding structures. Rolling mill capacity constraints in Germany and France create input volatility for converters serving moisture-critical drug lines.
- Polyethylene:Alternative thermoforming substrate with lower barrier properties than PVC but simplified recycling streams under EU Green Deal procurement criteria.
- Paperboard:Emerging fiber-derived substrate for outer blister card structures and sustainability-focused packaging redesigns.
Polyvinyl Chloride remains the workhorse substrate by volume; Aluminum Foil commands the steepest expansion trajectory as high-barrier demand intensifies.
End User:
Customer type determines serialization integration depth and quality release responsibility allocation.
- Contract Packaging Organizations:Third-party packagers offering integrated serialization, aggregation, and regulatory release functions. CDSCO-aligned facilities in India are expanding cold-form capacity for European and North American pharmaceutical export markets.
- Pharmaceutical Companies:In-house packaging operations at originator and generic drug manufacturers with captive thermoforming lines.
- Medical Device Manufacturers:Packagers of combination products requiring sterile barrier systems with pharmaceutical-grade traceability.
- Retail Pharmacies:Hospital and community pharmacy chains consolidating purchasing through procurement consortia in France and Italy.
Contract Packaging Organizations are expanding most quickly as pharmaceutical outsourcing accelerates; Pharmaceutical Companies retain the largest installed base.
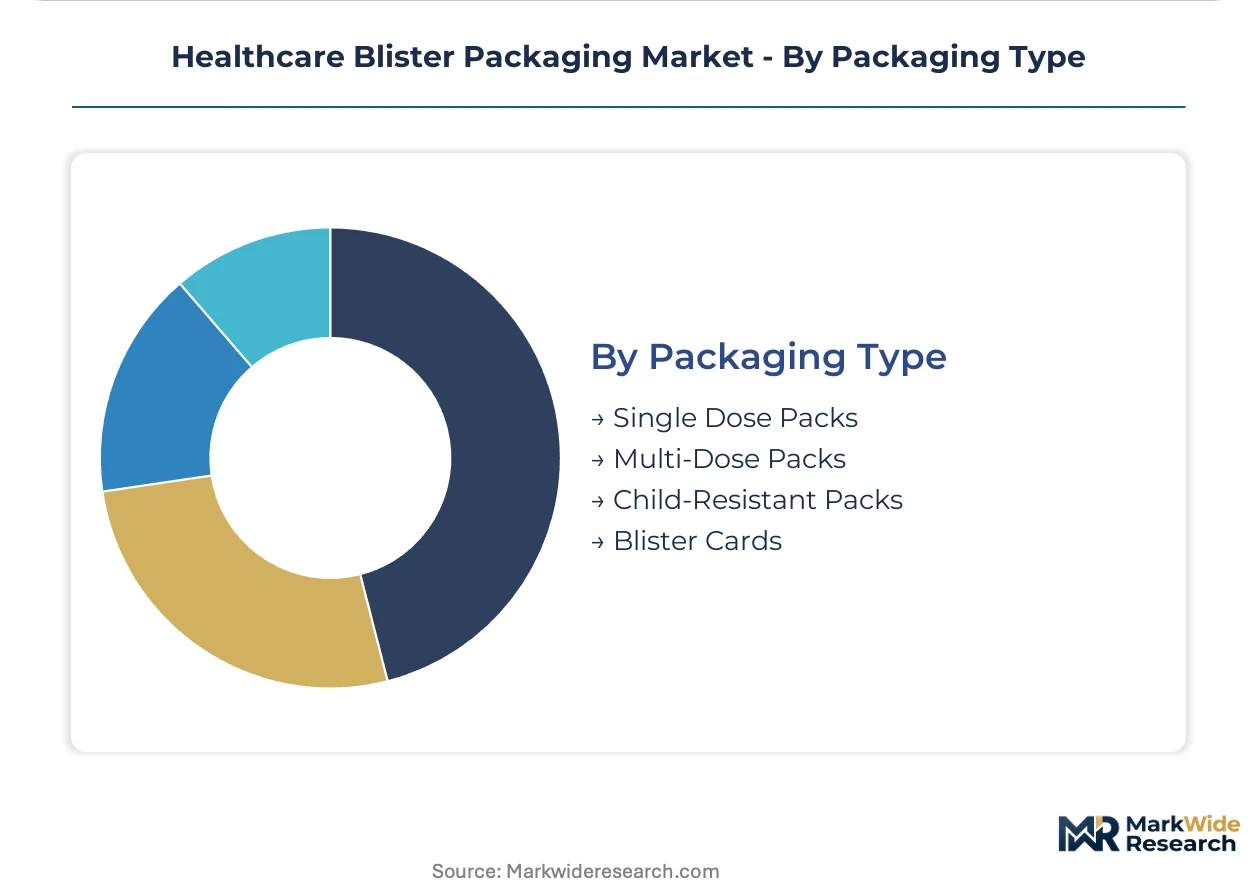
Packaging Type:
Application-driven specifications align with patient compliance requirements and reimbursement-linked dispensing protocols.
- Child-Resistant Packs:Senior-friendly yet tamper-evident designs with peel-push or slide mechanisms. Oncology and cardiovascular therapeutic verticals in France specify these where compliance packaging carries direct reimbursement implications.
- Single Dose Packs:Individual cavity isolation for unit-dose dispensing in hospital settings and clinical trial supplies. FDA DSCSA deadlines are accelerating preference for item-level traceability in this format.
- Multi-Dose Packs:Multiple cavities arranged for chronic medication adherence programs.
- Blister Cards:Calendarized or weekly dosing layouts with paperboard backing for retail pharmacy distribution.
Single Dose Packs lead volume in institutional channels; Child-Resistant Packs is climbing the fastest as safety regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites the Netherlands' distribution dominance for European blister packaging flows. Cold-chain warehousing clusters at Rotterdam-Europoort handle inbound aluminum foil from German rolling mills and outbound finished blisters to UK and Nordic markets.
Germany
Contract packaging organizations in Baden-Württemberg and North Rhine-Westphalia drive specialized cold-formed blister demand for moisture-sensitive APIs. REACH phthalate restrictions force PVC compounders in Hesse into accelerated reformulation cycles. The Rhine-Main logistics cluster around Frankfurt anchors serialization-equipment distribution networks serving pharmaceutical manufacturers across Central Europe.
United States
FDA DSCSA 2023-2028 phased deadlines compress supplier qualification timelines for unit-dose formats with embedded traceability. The Drug Supply Chain Security Act mandates item-level serialization that packaging converters must integrate before verification deadlines. New Jersey and Pennsylvania pharmaceutical corridors concentrate thermoforming capacity serving generic drug manufacturers with high-volume oral solid dosage lines.
India
CDSCO-aligned contract packagers in Gujarat and Maharashtra expand cold-form capacity for hygroscopic API export formulations to European and North American markets. The Pharmaceutical Export Promotion Council's quality certification requirements tighten material traceability standards for overseas shipments. Hyderabad's bulk drug-to-formulation corridor anchors integrated packaging operations serving ANDA-filing generic manufacturers.
Switzerland
Swissmedic's stringent extractables and leachables guidance extends validation timelines for new barrier material combinations in Basel's pharmaceutical cluster. Originators in the Lake Geneva region specify aluminum cold-form laminates for moisture-critical compounds requiring oxygen transmission rates below 0.01 cc/m²/day. The country's precision manufacturing heritage supports specialized tooling suppliers serving Alpine pharmaceutical packaging operations.
China
NMPA serialization requirements under the Drug Administration Law accelerate track-and-trace line integration at packaging converters serving domestic pharmaceutical manufacturers. Yangtze River Delta thermoforming operations supply PVC and PVDC-coated films for standard oral solid dosage applications. Zhejiang and Jiangsu provinces concentrate lidding foil lamination capacity feeding both export markets and domestic generic drug producers.
Healthcare Blister Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with substrate and tooling supply. The market structures around three tiers: integrated film-to-blister manufacturers with captive serialization capability, regional converters with thermoforming specialization, and raw material suppliers with pharmacopeial certification. Strategic moves concentrate on backward integration into aluminum rolling capacity and geographic expansion through contract packaging acquisitions.
Among European-based integrated packaging groups, Amcor Plc, Constantia Flexibles, and Klöckner Pentaplast occupy positions spanning film extrusion through finished blister supply. Amcor exemplifies the platform-integrator archetype with multi-site European manufacturing networks. Constantia Flexibles represents specialized cold-form foil capability for high-barrier applications. Klöckner Pentaplast anchors PVC and PET film supply serving regional drug manufacturers from German production assets.
| Leading Market Players |
|---|
| Amcor Plc |
| Constantia Flexibles |
| Klöckner Pentaplast |
| Sonoco Products Company |
| WestRock Company |
| UFlex Limited |
| Winpak Ltd. |
| TekniPlex |
| CCL Healthcare |
| Others |
Value Network & Pricing Analysis
German aluminum rolling mill concentration for cold-form foil feedstock anchors margin capture at the laminate converter tier, while REACH-driven PVC reformulation costs cascade through thermoforming substrate pricing to generic drug manufacturers in Central Europe.
Pricing Analysis
FDA DSCSA and EU MDR serialization mandates dictate the pricing tier structure across the Healthcare Blister Packaging Market. Three-tier pricing stratifies across cold-form premium barriers, PVDC-coated intermediate solutions, and standard PVC economy substrates. Price differentiation centers on EMA extractables certification grade and integrated serialization capability rather than base material cost. Pricing pressure intensifies in the thermoforming segment as multi-layer coextruded films with ethylene vinyl alcohol barrier cores compress premiums previously captured by aluminum laminates. Contract packaging organizations exhibit highest price sensitivity due to competitive tendering for pharmaceutical outsourcing contracts, while originator drug manufacturers in Switzerland demonstrate lowest sensitivity given API stability requirements.
Supply Chain Analysis
Aluminum ingot and PVC resin feedstocks draw from German, French, and Chinese upstream chemical complexes. Cold-form foil laminates rest on European rolling mill capacity concentrated in Germany's Rhine-Ruhr industrial belt, while thermoforming films source from compounders in Hesse and Zhejiang province. Single-source vulnerability concentrates in pharmaceutical-grade aluminum rolling capacity, where mill qualification timelines extend 18-24 months for extractables compliance. Distribution runs through the Port of Rotterdam's pharmaceutical logistics corridor, with finished blisters consolidating at Europoort cold-chain warehouses for UK and Nordic market dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare blister packaging is fundamentally a service-attach opportunity, with integrated serialization, aggregation software, and regulatory release functions expanding faster than commodity substrate supply as pharmaceutical outsourcing accelerates.
For Market Incumbents: Pre-empt margin compression in standard thermoforming by embedding track-and-trace software layers that capture recurring revenue from DSCSA compliance deadlines. Backward integration into aluminum rolling capacity in Germany or France defends supply security against mill concentration risk. Certification investment in EMA extractables testing protocols creates switching costs that lock in originator drug relationships against PVDC-coated film substitutes. For New Entrants and Emerging Players: India's CDSCO-aligned contract packaging corridors in Gujarat and Maharashtra represent underpenetrated white-space for cold-form capacity serving European ANDA-filing generic manufacturers. Paper-based blister alternatives with barrier coating technologies offer a second entry vector into EU Green Deal procurement specifications at French and Italian hospital consortia. Go-to-market execution should anchor on pharmaceutical outsourcing tender participation rather than direct drug manufacturer sales. For Investors and Strategic Acquirers: Capital is best deployed toward integrated film-to-blister manufacturers with captive serialization capability and established pharmacopeial certification. Long-term viability across the projection horizon hinges on regulatory compliance depth rather than commodity scale. The signal to watch is consolidation velocity among European contract packaging organizations as pharmaceutical outsourcing accelerates and specialized quality release functions become scarce.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | German mill capacity constraints create captive supply advantages for cold-form laminate converters. |
| Serialization Software Platform Development | FDA DSCSA deadlines drive recurring revenue attachment to physical blister manufacturing lines. |
| EMA Extractables Certification Investment | Swissmedic and EMA guidance extends validation timelines, creating certification moats for qualified suppliers. |
| Contract Packaging Organization Acquisition | Pharmaceutical outsourcing acceleration concentrates purchasing power with integrated packagers in Baden-Württemberg. |
| Paper-Based Blister Alternative R&D | EU Green Deal procurement preferences in France and Italy open fiber-derived substrate substitution pathways. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging converters, pharmaceutical quality assurance directors, and hospital procurement managers at GPOs, combined with secondary validation against FDA DSCSA guidance documents, EMA extractables guidance, and customs trade data for aluminum foil and PVC resin flows. Bottom-up and top-down triangulation cross-checked capacity estimates from German film extruders against pharmaceutical packaging demand projections from ANDA filing trends.
Forecast inputs span thermal formed versus cold-formed technology splits, PVC versus aluminum laminate material shares, and contract packaging organization versus in-house pharmaceutical packaging end-use segmentation across the analysis window. CAGRs derive from regression analysis of historical pharmaceutical production volumes, regulatory deadline phasing, and substrate substitution elasticities. Specific inputs include REACH phthalate restriction implementation timelines and CDSCO quality certification expansion rates for Indian export packagers.
Practitioners should monitor aluminum rolling mill capacity utilization, REACH additive restriction enforcement intensity, and serialization deadline extension announcements for early signals of forecast revision. Cross-checking against pharmaceutical production indices and hospital procurement consortium tender awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Paper Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Blister Packs Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market