
 Europe Blister Packaging Market | 2026-2036
Europe Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blister Packaging Market Foresight
The divergence between premium pharmaceutical blisters and commodity food-grade formats is repositioning investment priorities across European converters. Amcor PLC leverages its integrated film-to-package pipeline to dominate high-barrier pharmaceutical contracts. Constantia Flexibles GmbH sustains margin leadership through specialized cold-form aluminum operations for sensitive biologics. Klockner Pentaplast Group anchors volume scale in thermoformed PET, competing aggressively on recycled-content specifications.
Blister packaging in Europe denotes a pre-formed plastic or aluminum cavity sealed to a backing card or foil, typically manufactured through thermoforming or cold-forming processes with cavity depths ranging from 0.5 mm to 12 mm, designed to protect unit-dose products from moisture, oxygen, and mechanical damage. Thermoformed PVC and PET blisters occupy the largest volume share, though cold-form aluminum blisters command superior margins due to their extended moisture-barrier performance for hygroscopic drugs. By material, PET and PP segments are gaining structural prominence as EFSA-aligned recyclability mandates and EU Green Deal targets pressure converters away from multi-layer PVC constructions.
The European Medicines Agency (EMA) enforces strict child-resistance and senior-friendly opening standards under the EU Medical Devices Regulation (MDR), while REACH and RoHS frameworks restrict phthalate plasticizers and heavy-metal additives in blister films. These compliance layers elevate technical barriers for new entrants and concentrate supply relationships among converters with certified quality-management systems. Stakeholders must monitor forthcoming Packaging and Packaging Waste Regulation revisions, as extended producer responsibility thresholds will likely force faster substrate transitions than current plant configurations allow.
Market Dynamics
EU Green Deal mandates and EMA child-resistance standards are compressing converter margins while forcing substrate transitions from multi-layer PVC toward recyclable mono-material PET and PP formats across pharmaceutical and food-grade applications.
Growth Catalysts
- EMA Medical Devices Regulation:Child-resistance and senior-friendly opening standards elevate technical barriers, concentrating supply relationships among certified converters with quality-management systems.
- Cold-chain pharmaceutical distribution:Biologics and temperature-sensitive vaccines drive adoption of high-barrier aluminum-laminate formats with extended moisture protection.
- Germany's medical device clusters:Precision drug delivery systems in Baden-Württemberg and Bavaria anchor premium blister consumption for hygroscopic drugs.
Market Restraints
- Aluminum price volatility:Cold-form aluminum substrates face input cost pressure from energy-intensive smelting operations, compressing margins for high-barrier pharmaceutical formats.
- REACH phthalate restrictions:Plasticizer bans in PVC films force formulation overhauls, creating technical friction during substrate qualification cycles.
- Flexible pouch substitution:Strip packaging and stick-pack formats displace unit-dose blisters in over-the-counter nutraceutical segments.
Strategic Opportunities
- Poland and Romania manufacturing:Underpenetrated converter capacity in Eastern Europe offers cost-competitive locations for thermoformed PET volume production serving EU-wide distribution.
- Extended Producer Responsibility thresholds:Pending Packaging and Packaging Waste Regulation revisions create first-mover advantage for converters with certified recyclable mono-material platforms.
- Smart blister integration:Convergence of printed electronics with thermoformed cavities enables adherence monitoring for clinical trial and chronic disease management applications.
Industry Challenges
- Multi-layer delamination expertise:Shortage of process engineers capable of managing high-barrier aluminum-laminate bonding without compromising seal integrity.
- Legacy thermoforming line retrofit:Reconfiguring existing PVC-optimized equipment for PET and PP processing requires substantial capital outlay and extended downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blister Packaging Market |
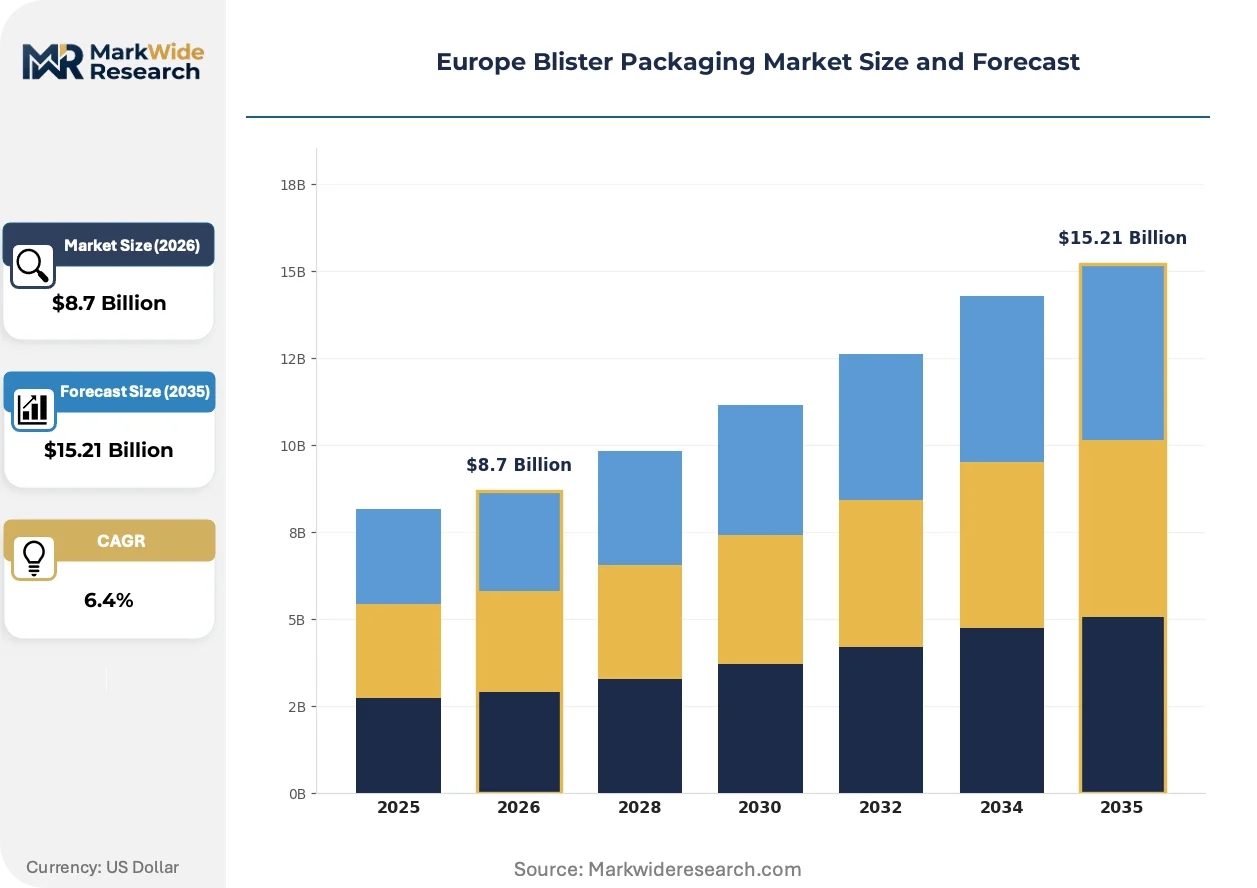
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoformed Blisters, Cold Form Blisters, Constant Heat Seal Blisters, Elastic Blisters Material: PVC, PET, Aluminum, PP End User: Pharmaceuticals, Consumer Electronics, Food Industry, Cosmetics Technology: Forming Technology, Coating Technology, Sealing Technology, Barrier Technology |
| Companies Covered | Amcor PLC, Constantia Flexibles GmbH, Westrock Company, Sonoco Products Company, Honeywell International Inc., Klockner Pentaplast Group, Tekni-Plex, Inc., Gerresheimer AG, Perlen Packaging AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blister Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are restructuring competitive advantage around circularity credentials and barrier performance rather than scale economics alone.
Mono-material PET blisters with EFSA-aligned recyclability certifications are overtaking multi-layer PVC constructions in pharmaceutical applications. German and Swiss drug manufacturers are accelerating qualification timelines for these substrates. The shift is compressing demand for legacy PVC converters while rewarding integrated film-to-package pipelines with certified recycling streams.
REACH and RoHS frameworks now restrict heavy-metal additives and phthalate plasticizers across all blister film categories. Converters must reformulate masterbatches and resubmit technical documentation for existing drug packaging approvals. Pediatric and geriatric drug segments face the steepest compliance timelines as EMA reviews updated child-resistance test protocols.
Hospital and pharmacy buyers are consolidating supplier panels around converters offering combined barrier performance and carbon footprint verification. Long-term framework agreements now specify recycled-content minimums and mass-balance certification. Nordic healthcare procurement organizations have pioneered these integrated sourcing criteria, with German hospital networks adopting similar specifications.
Europe Blister Packaging Market Segmentation
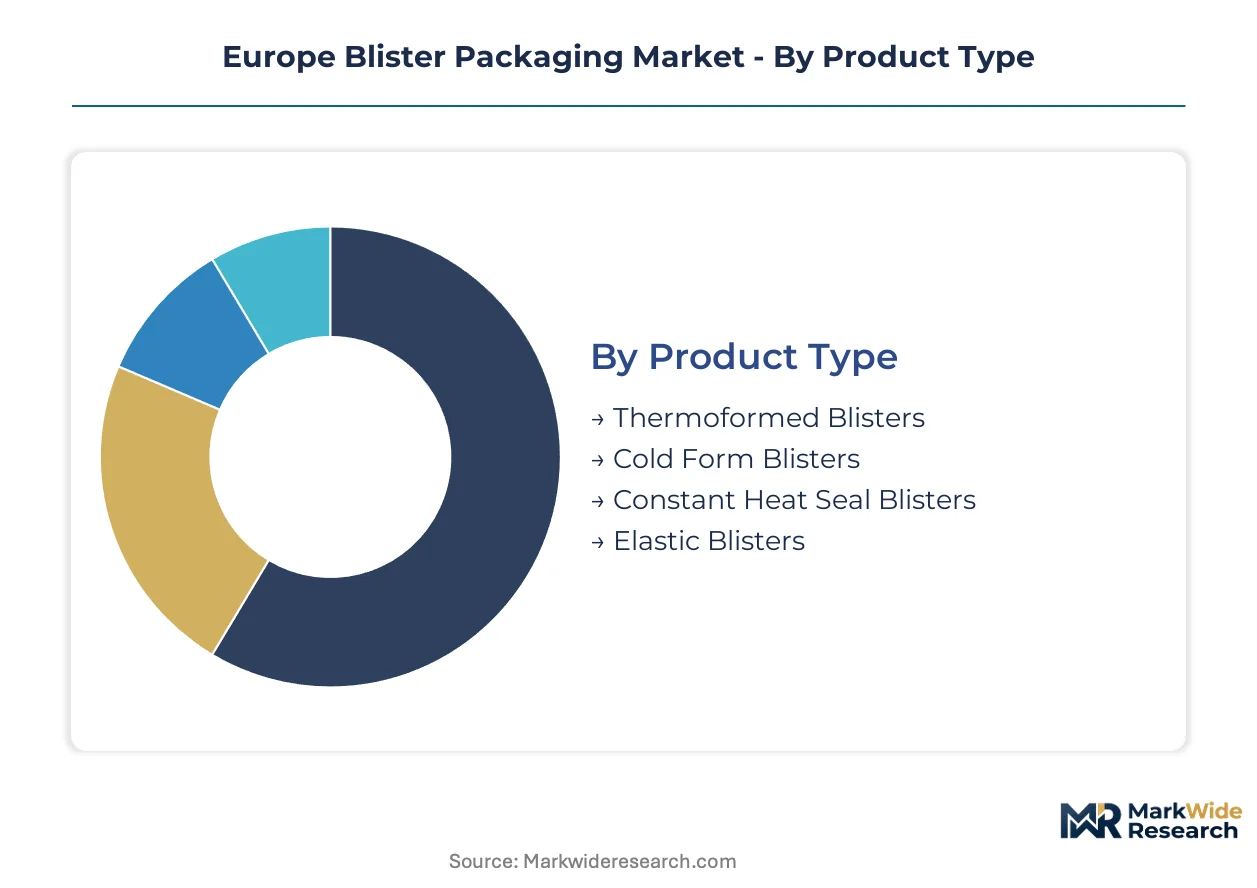
Segmentation in the European blister packaging market reveals how substrate choices and forming technologies map to distinct margin structures and regulatory compliance burdens. Understanding these divisions clarifies where converters can defend premium positioning versus where scale economies dominate procurement decisions.
Product Type:
Thermoformed formats serve as standalone packaging solutions for standard moisture protection, while cold-form variants embed into high-barrier pharmaceutical distribution systems requiring extended shelf stability.
- Thermoformed Blisters:Manufactured through heat-softening of PVC or PET sheets followed by vacuum or pressure forming into cavity depths of 0.5 mm to 12 mm. Volume concentrates in German and Polish pharmaceutical packaging for oral solid dose medications where EMA child-resistance standards mandate specific opening force specifications.
- Cold Form Blisters:Constructed through deep-drawing of aluminum-laminate webs without heat application, creating hermetic seals against moisture and oxygen ingress. Bavarian precision drug delivery clusters in Germany anchor demand for these formats in biologics and hygroscopic drug applications where barrier performance outweighs unit cost considerations.
- Constant Heat Seal Blisters:Deploy temperature-controlled sealing jaws for repeatable seal integrity across high-speed production lines. French and Italian converters favor this technology for cosmetic and nutraceutical applications requiring aesthetic presentation consistency.
- Elastic Blisters:Utilize elastomeric films that conform to irregular product geometries without permanent deformation. Swiss medical device manufacturers specify these formats for implantable device packaging where mechanical shock absorption complements barrier protection.
Volume placements concentrate in Thermoformed Blisters; the faster expansion belongs to Cold Form Blisters.
Material:
Substrate selection in European blister packaging stratifies across cost tiers, with legacy materials facing displacement pressure from recyclability mandates while premium barriers command specialized procurement relationships.
- PVC:Polyvinyl chloride films dominate installed thermoforming capacity across European converters, offering clarity and forming ease at low unit cost. REACH phthalate restrictions and EU Green Deal circularity targets are compressing demand in German pharmaceutical applications where mono-material alternatives now qualify faster.
- PET:Polyethylene terephthalate delivers EFSA-aligned recyclability certifications and comparable clarity to PVC without plasticizer dependencies. Nordic healthcare procurement organizations specify minimum recycled-content PET in long-term framework agreements, accelerating converter qualification timelines.
- Aluminum:Cold-form aluminum laminates provide moisture vapor transmission rates below 0.01 g/m²/day for hygroscopic drug protection. Energy-intensive smelting operations create input cost volatility that converters pass through via indexed pricing in Swiss and German biologics contracts.
- PP:Polypropylene offers thermal stability and chemical resistance for autoclave-sterilized medical device packaging. Romanian and Polish converters are expanding PP thermoforming capacity to serve EU-wide distribution with lower carbon footprint credentials than PVC alternatives.
Procurement volume still favors PVC; PET is climbing the fastest as EMA-aligned recyclability specifications harden.
End User:
End-use segmentation distributes across application maturity, with established pharmaceutical demand contrasting against emerging electronics and cosmetics adoption where barrier specifications vary substantially.
- Pharmaceuticals:Unit-dose oral medications, injectables, and biologics require child-resistant senior-friendly opening mechanisms under EU MDR. German precision drug delivery systems in Baden-Württemberg generate concentrated demand for high-barrier formats with extended moisture protection.
- Consumer Electronics:Memory cards, batteries, and small accessories utilize blisters for retail theft deterrence and product visibility. Electronics manufacturing clusters in Hungary and Czechia source thermoformed PET for point-of-sale presentation with EPR-compliant recyclability.
- Food Industry:Confectionery and portion-controlled snacks employ blisters for portion integrity and shelf appeal. Italian and Spanish food processors specify mono-material PP formats to meet pending Packaging and Packaging Waste Regulation extended producer responsibility thresholds.
- Cosmetics:Single-use samples and premium gift sets leverage blister clarity for brand differentiation. French cosmetics houses in the Île-de-France region drive specification of aesthetic-grade PET with mass-balance certified recycled content.
Revenue concentration sits with Pharmaceuticals; Cosmetics is expanding most quickly as premium sampling formats proliferate.
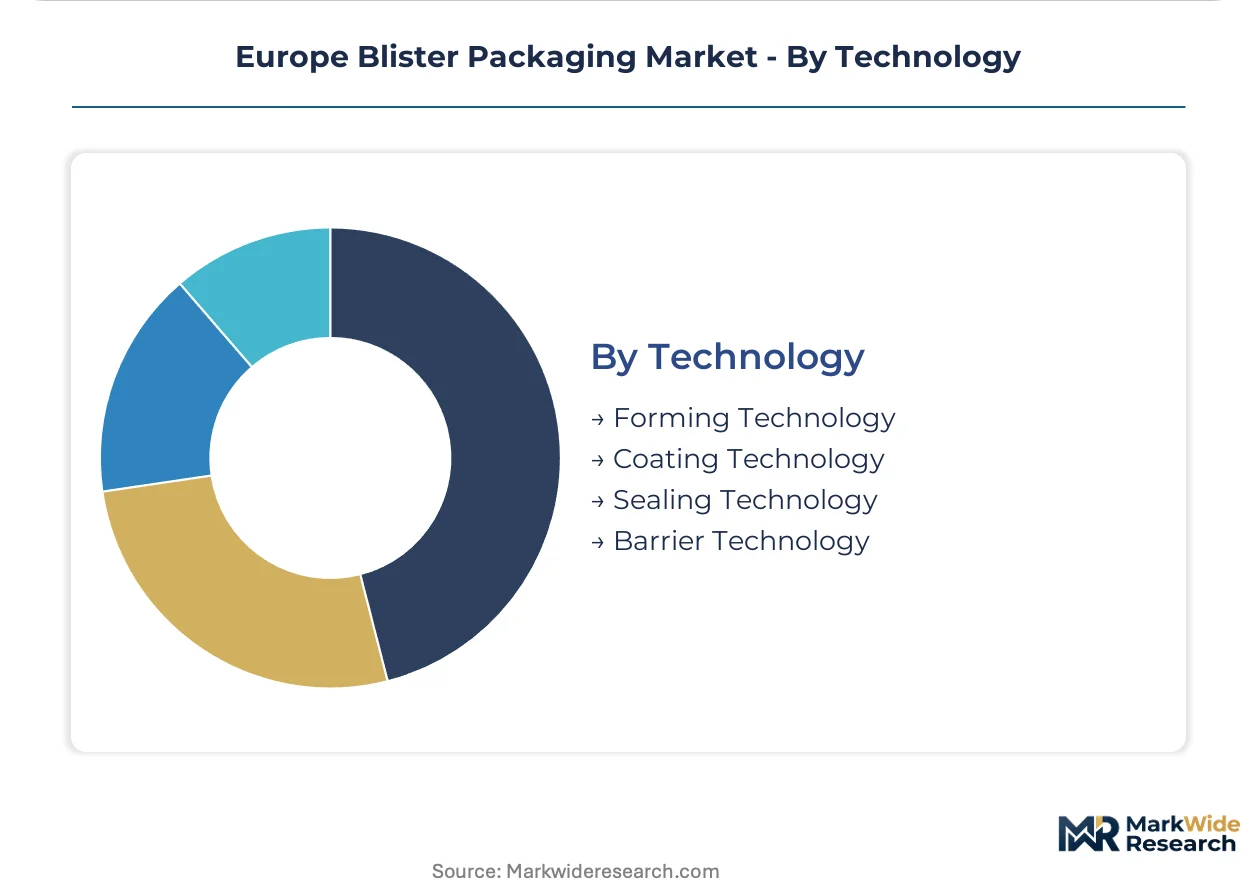
Technology:
Technology segmentation reflects capability depth, with basic forming and sealing operations separating from specialized coating and barrier engineering that commands technical premium in converter selection.
- Forming Technology:Thermoforming and cold-forming equipment configurations determine cavity precision and production throughput. German and Swiss machinery builders supply servo-controlled forming stations that Baden-Württemberg pharmaceutical converters specify for tight dimensional tolerances.
- Coating Technology:SiOx and AlOx vapor-deposited barriers enhance base film performance without multi-layer lamination complexity. Austrian and Dutch coating specialists are qualifying these technologies for EFSA food-contact approvals in barrier-enhanced PET applications.
- Sealing Technology:Heat-seal, cold-seal, and ultrasonic welding methods bond lidding materials to formed cavities with varying speed and integrity profiles. High-speed pharmaceutical lines in Poland and Romania favor constant heat seal systems for output consistency at scale.
- Barrier Technology:Multi-layer laminates and metallized structures deliver targeted protection against moisture, oxygen, and light degradation. Swiss biologics manufacturers specify aluminum-laminate barrier technology for temperature-sensitive vaccine distribution where cold-chain integrity extends beyond primary packaging to secondary containment.
Equipment investment concentrates in Forming Technology; Barrier Technology is gaining share fastest as biologics cold-chain requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision drug delivery clusters anchor European blister packaging demand, with Stuttgart and Tübingen hosting medical device manufacturers that specify high-barrier aluminum-laminate formats for hygroscopic drugs.
Germany
Bavarian biologics manufacturers and Baden-Württemberg precision drug delivery systems drive premium cold-form blister consumption. EMA Medical Devices Regulation enforces child-resistance and senior-friendly opening standards that elevate technical barriers for converters. Munich and Stuttgart clusters concentrate demand for aluminum-laminate formats with moisture vapor transmission rates below 0.01 g/m²/day.
France
Île-de-France cosmetics houses and Paris-region pharmaceutical headquarters specify aesthetic-grade PET blisters with mass-balance certified recycled content. REACH phthalate restrictions force PVC formulation overhauls across French converters. Lyon and Strasbourg packaging specialists qualify mono-material alternatives for EFSA-aligned recyclability mandates.
Switzerland
Swiss biologics manufacturers in Basel and Zurich specify aluminum-laminate barrier technology for temperature-sensitive vaccine distribution. Swissmedic enforces strict quality-management system certifications that concentrate supply relationships among accredited converters. Geneva and Lausanne medical device clusters demand elastomeric elastic blisters for implantable device packaging.
Poland
Warsaw and Kraków converters expand thermoformed PET capacity to serve EU-wide distribution with cost-competitive production. EU Green Deal circularity targets accelerate substrate transitions from multi-layer PVC toward recyclable mono-material formats. Łódź packaging specialists leverage underpenetrated converter capacity for high-speed pharmaceutical lines with constant heat seal systems.
Italy
Emilia-Romagna food processors and Lombardy cosmetics manufacturers specify mono-material PP formats to meet pending Packaging and Packaging Waste Regulation extended producer responsibility thresholds. EFSA-aligned recyclability certifications drive qualification timelines for PET alternatives. Bologna and Milan industrial districts concentrate thermoforming equipment investment for barrier-enhanced applications.
Europe Blister Packaging Market Competitive Landscape
Capital-heavy integrated film-to-package producers compete with asset-light specialized converters across European blister packaging. The market structure concentrates around three tiers: multinational material-science conglomerates with captive resin production, mid-cap regional specialists with certified barrier-laminate expertise, and commodity thermoformers competing on recycled-content specifications. Dominant competitive moves include backward integration into resin and film production to secure mass-balance certification, plus strategic equipment retrofits for PET and PP processing to outpace regulatory substrate mandates.
Among integrated packaging conglomerates, Amcor PLC and Constantia Flexibles GmbH exemplify divergent strategic archetypes. Amcor represents the film-to-package pipeline model with global resin sourcing capabilities. Constantia Flexibles occupies the specialized cold-form aluminum segment with European-focused barrier-laminate operations. Klockner Pentaplast Group anchors the scale-driven thermoformed PET tier, competing aggressively on recycled-content specifications and EPR-compliant recyclability credentials.
| Leading Market Players |
|---|
| Amcor PLC |
| Constantia Flexibles GmbH |
| Westrock Company |
| Sonoco Products Company |
| Honeywell International Inc. |
| Klockner Pentaplast Group |
| Tekni-Plex, Inc. |
| Gerresheimer AG |
| Perlen Packaging AG |
| Others |
Supply & Pricing Matrix
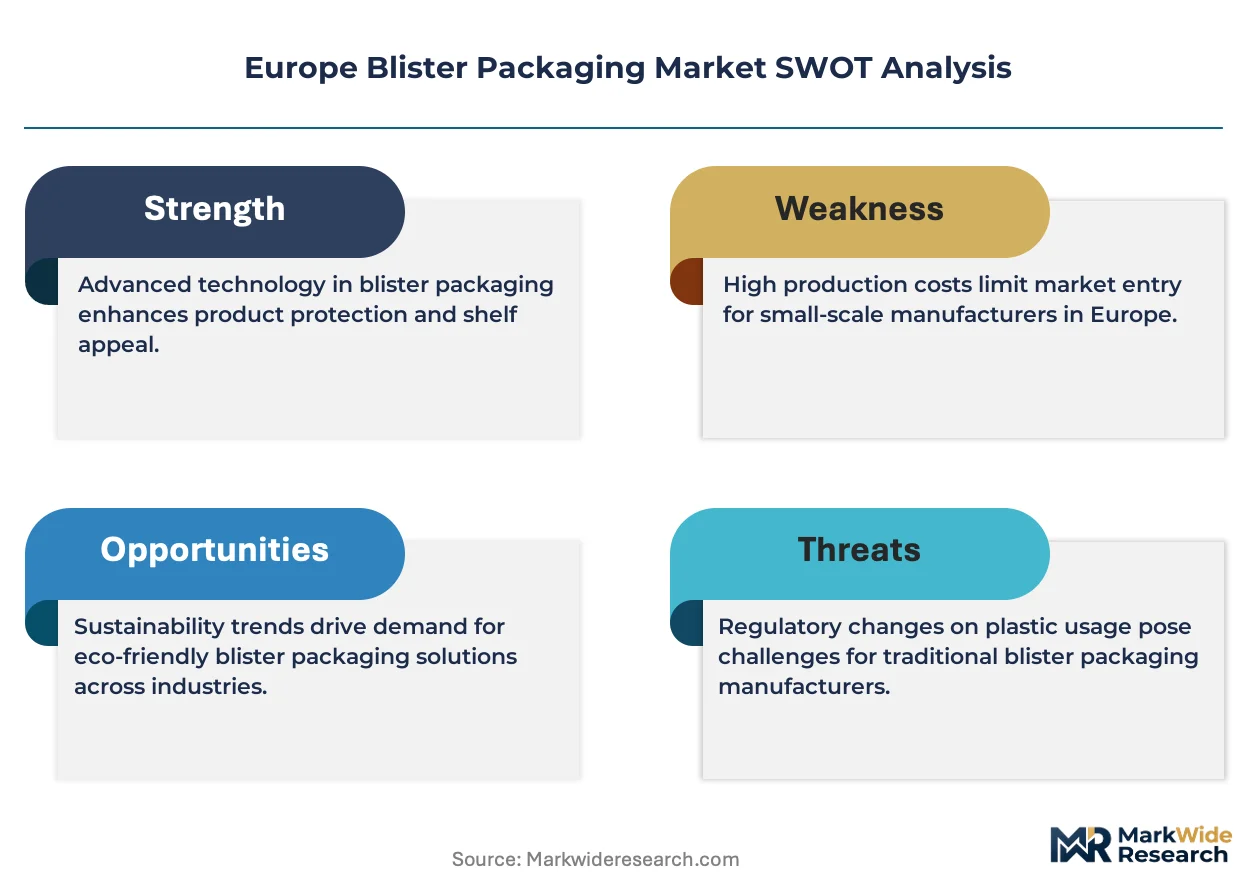
German hospital network procurement panels concentrate demand for high-barrier pharmaceutical blisters, anchoring value-based pricing models that tie contract rates to verified moisture-barrier performance and EMA compliance certification tiers rather than commodity resin costs.
Pricing Analysis
Barrier-performance guarantees anchor value-based pricing for cold-form aluminum-laminate formats serving Bavarian biologics manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified high-barrier contracts from food-grade thermoformed PET and commodity PVC volumes. Cost compression in standard-tier PET is intensifying because Romanian and Polish converters compete aggressively on recycled-content specifications. Hospital procurement panels exhibit lowest price sensitivity for child-resistant senior-friendly formats, while Italian food processors drive hardest bargaining on mono-material PP conversions.
Supply Chain Analysis
Direct-to-pharma channels handle high-barrier aluminum-laminate demand from German and Swiss biologics clusters, while distributor-mediated routes serve volume thermoformed PET across European food and cosmetics segments. Raw material supply concentrates in Germany, Austria, and Poland for film extrusion and barrier coating operations. The converter base draws from aluminum smelters in Norway and Iceland, plus PET resin producers in the Netherlands and Belgium. Single-source vulnerability in cold-form aluminum bonding expertise creates supply risk for EMA-certified pharmaceutical contracts. Distribution runs through certified logistics partners with temperature-controlled capabilities for cold-chain pharmaceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cold-form aluminum-laminate capacity operates near full utilization across German and Swiss converter bases, propping pricing power for certified barrier specialists as EMA child-resistance mandates compress available supply.
For Market Incumbents: Deploy backward integration into certified recycled-content PET resin production to outpace EU Green Deal substrate mandates. Incumbent converters must secure mass-balance certification ahead of Packaging and Packaging Waste Regulation thresholds while defending high-barrier pharmaceutical relationships against emerging Polish and Romanian thermoforming scale. Capacity addition in Eastern European locations offers cost-competitive positioning for standard-tier volume contracts. For New Entrants and Emerging Players: Digital-channel qualification platforms enable rapid technical documentation submission for EMA-aligned recyclability certifications, accelerating market entry timelines. New entrants should target underpenetrated elastic blister demand from Swiss medical device manufacturers seeking elastomeric formats for implantable device packaging. Cosmetics sampling formats in France present accessible white-space with lower barrier-performance thresholds than pharmaceutical applications. For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with certified cold-form aluminum expertise and established EMA quality-management systems. Long-term viability hinges on substrate-transition readiness as PVC displacement accelerates across the analysis window. Investors should monitor EFSA-aligned recyclability qualification timelines as the inflection signal for converter valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Resin | Secures mass-balance certification ahead of EU Green Deal mandates for converters. |
| EMA Quality-Management System Certification | Concentrates supply relationships among accredited converters for child-resistant formats. |
| Eastern European Capacity Expansion | Captures cost-competitive thermoformed PET production serving EU-wide distribution networks. |
| Smart Blister Technology Integration | Enables adherence monitoring convergence with printed electronics for clinical trials. |
| Mono-Material PP Qualification | Positions converters for Italian food processor EPR compliance under pending regulations. |
Research Methodology
Independent corroboration across converter operations managers, pharmaceutical packaging procurement leads, and EMA regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork encompassed technical directors at German and Swiss barrier-laminate specialists, plus hospital pharmacy buyers in Nordic procurement organizations. Secondary validation drew from EMA Medical Devices Regulation guidance documents, EU Green Deal policy releases, EFSA food-contact material approvals, and REACH restriction updates. Bottom-up volume estimates from individual converter capacity disclosures were triangulated against top-down pharmaceutical packaging demand projections.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-regulation-shift qualification timelines. The analytical framework modeled segmentation across forming technology, material substrate, end-use vertical, and geographic production cluster dimensions. CAGRs were derived from fitted growth curves applied to converter capacity expansion announcements and pharmaceutical cold-chain distribution trends. Forecast inputs included aluminum price volatility indices and EMA child-resistance test protocol revision schedules.
The model holds under stable EMA regulatory enforcement and gradual EU Green Deal implementation; deviation in accelerated PVC restriction timelines or aluminum supply disruption would shift substrate transition speeds. Forecasts reflect documented assumptions regarding converter retrofit capex cycles and pharmaceutical qualification lead times. Periodic stress-testing of base assumptions is recommended against forthcoming Packaging and Packaging Waste Regulation revision drafts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market