
 Asia Pacific Blister Packaging Market | 2026-2036
Asia Pacific Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Blister Packaging Market Outlook
Pharmaceutical contract packagers are bifurcating from consumer electronics buyers as the dominant demand archetype across Asia Pacific. Amcor Limited leverages its integrated film extrusion network to supply high-barrier PVC and Aclar laminates to Japanese and Australian drug manufacturers. Uflex Limited anchors its position through backward integration into polyester and aluminum foil production, serving Indian generic pharmaceutical exporters with cost-optimized cold formed solutions.
Asia Pacific blister packaging denotes thermoformed or cold-formed cavity-and-lidding assemblies, typically constructed from PVC, PET, or aluminum foil with heat-seal coatings ranging from 6 to 25 micrometers in thickness, engineered to provide unit-dose protection, tamper evidence, and shelf-life extension for oral solid dosage forms and small-format devices. Thermoformed blisters occupy the volume base across ASEAN markets due to lower tooling costs and faster cycle times, while cold formed aluminum blisters capture premium positioning in Japan and South Korea where moisture and oxygen ingress specifications approach zero. Multi-cell blisters represent the fastest-growing geometry segment as combination therapies and dose-escalation regimens expand across oncology and cardiovascular portfolios.
Japan's PMDA enforces moisture vapor transmission rate thresholds below 0.5 g/m²/day for hygroscopic drug categories, compelling converters toward aluminum-cold-form dominance. India's CDSCO and BIS have aligned blister packaging standards with ICH Q1A stability guidelines, accelerating domestic certification investments. Australia's TGA maintains parallel equivalence requirements that filter market access for imported blister films and foils. Stakeholders must monitor evolving pharmaceutical serialization mandates across ASEAN member states, where fragmented regulatory timelines will reshape supplier qualification burdens and regional inventory deployment strategies.
Market Dynamics
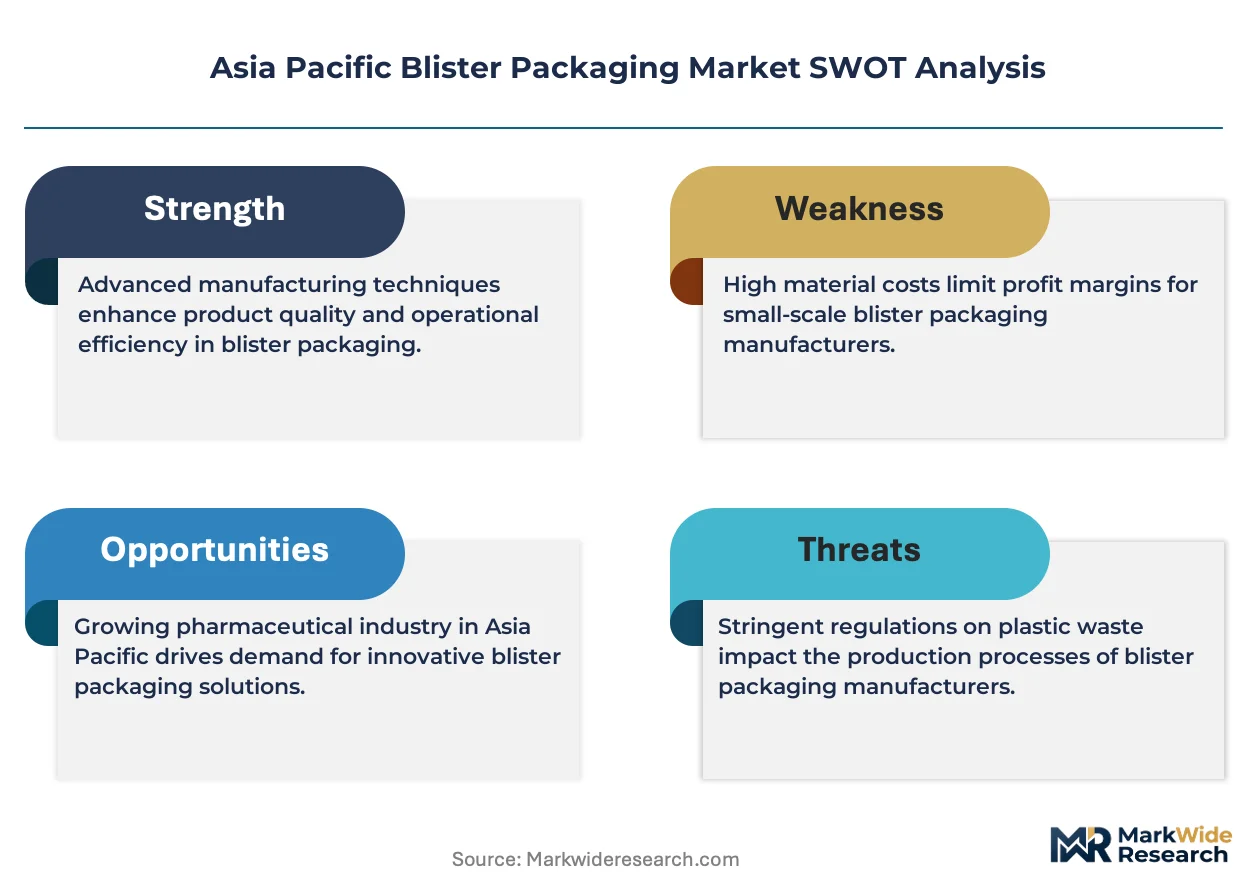
Regulatory divergence across Asia Pacific is fragmenting supplier qualification pathways, forcing converters to maintain parallel certification portfolios for Japan's PMDA moisture thresholds, India's CDSCO stability alignment, and Australia's TGA equivalence requirements.
Growth Catalysts
- Child-resistance mandates:Southeast Asian national regulators are tightening unit-dose safety standards, accelerating pharmaceutical orders for cold formed aluminum blisters with push-through and peel-open mechanisms.
- Combination therapy expansion:Oncology and cardiovascular portfolios are driving multi-cell blister geometries for dose-escalation regimens, creating specialized cavity configurations.
- Contract packaging hub concentration:Gujarat and Maharashtra in India are aggregating demand through integrated contract packaging facilities serving export markets.
Market Restraints
- Aluminum foil price volatility:Cold formed blister dependence on pharmaceutical-grade aluminum creates margin compression when raw material costs spike.
- Japanese converter oligopoly:High-barrier film and laminate supply concentrates among integrated players with captive extrusion capacity, limiting new entrant access.
- PVC environmental friction:Chlorinated polymer restrictions in select Australian jurisdictions are complicating thermoformed blister deployment for generic manufacturers.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing:Greenfield API and formulation facilities are creating first-mover advantages for blister converters establishing local technical service.
- Serialization integration:ASEAN member states' fragmented pharmaceutical track-and-trace timelines are opening qualification windows for packaging-IT convergence specialists.
- Aclar laminate adoption:Japanese and Australian manufacturers are specifying high-performance fluoropolymer films for ultra-hygroscopic compounds, displacing standard PVC-PVDC.
Industry Challenges
- Validation engineer scarcity:Pharmaceutical packaging qualification protocols require specialized expertise in moisture vapor transmission testing and heat-seal optimization that outpaces regional training pipeline output.
- Dual-cavity tooling complexity:Multi-cell blister formats for combination therapies demand precision thermoforming dies with tighter tolerance bands, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Blister Packaging Market |
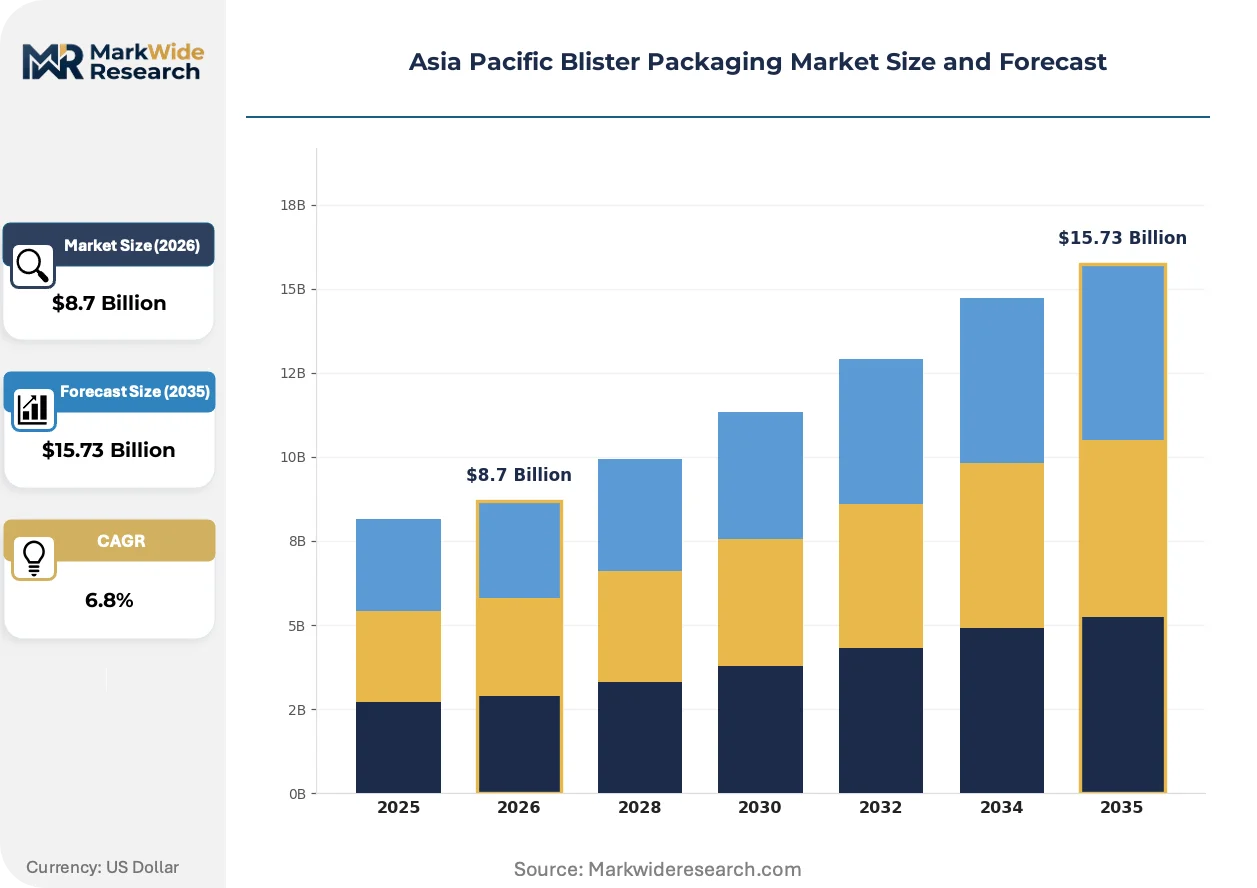
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoformed Blisters, Cold Formed Blisters, Bubble Blisters, Die-cut Blisters Material: Plastic, Aluminum, Paperboard, Fiberboard End User: Pharmaceuticals, Consumer Electronics, Food Packaging, Medical Devices Geometry: Standard Blisters, Custom Shaped Blisters, Multi-cell Blisters, Combo Blisters |
| Companies Covered | Amcor Limited, Uflex Limited, WestRock Company, Klockner Pentaplast Group, Sonoco Products Company, Constantia Flexibles, Tekni-Plex Inc, Getpac India, Perlen Packaging (Suzhou) Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Blister Packaging Market Strategic Shifts
Material science advances and regulatory precision are reconfiguring competitive advantage around barrier performance tiers rather than commodity volume, with converters investing in specialized laminates and cavity geometries.
Cold formed aluminum technology is bifurcating the Asia Pacific blister landscape. This cavity-forming approach uses deep-drawn aluminum foil with nylon and PVC laminates to create near-zero moisture transmission enclosures. Japanese and Korean pharmaceutical manufacturers specify these structures for hygroscopic drug categories requiring PMDA-compliant MVTR below 0.5 g/m²/day. The technology is bifurcating converter capabilities into high-barrier specialists versus commodity thermoformers.
PMDA moisture vapor transmission thresholds are compressing design freedom for hygroscopic drug packaging. Japanese regulators enforce sub-0.5 g/m²/day specifications that eliminate standard PVC-PVDC options from consideration. Domestic and export-oriented drug manufacturers are responding by qualifying aluminum-cold-form structures and Aclar laminates, shifting procurement toward integrated film suppliers with barrier testing capabilities.
Pharmaceutical buyers are consolidating supplier relationships around technical service proximity rather than pure unit cost. Multi-national drug manufacturers operating across ASEAN markets are reducing approved vendor lists to converters with regional laboratory networks for seal-strength validation and accelerated stability testing. This pattern is most visible in Singapore and Sydney, where headquarters procurement functions are mandating local technical support for packaging change controls.
Asia Pacific Blister Packaging Market Segmentation
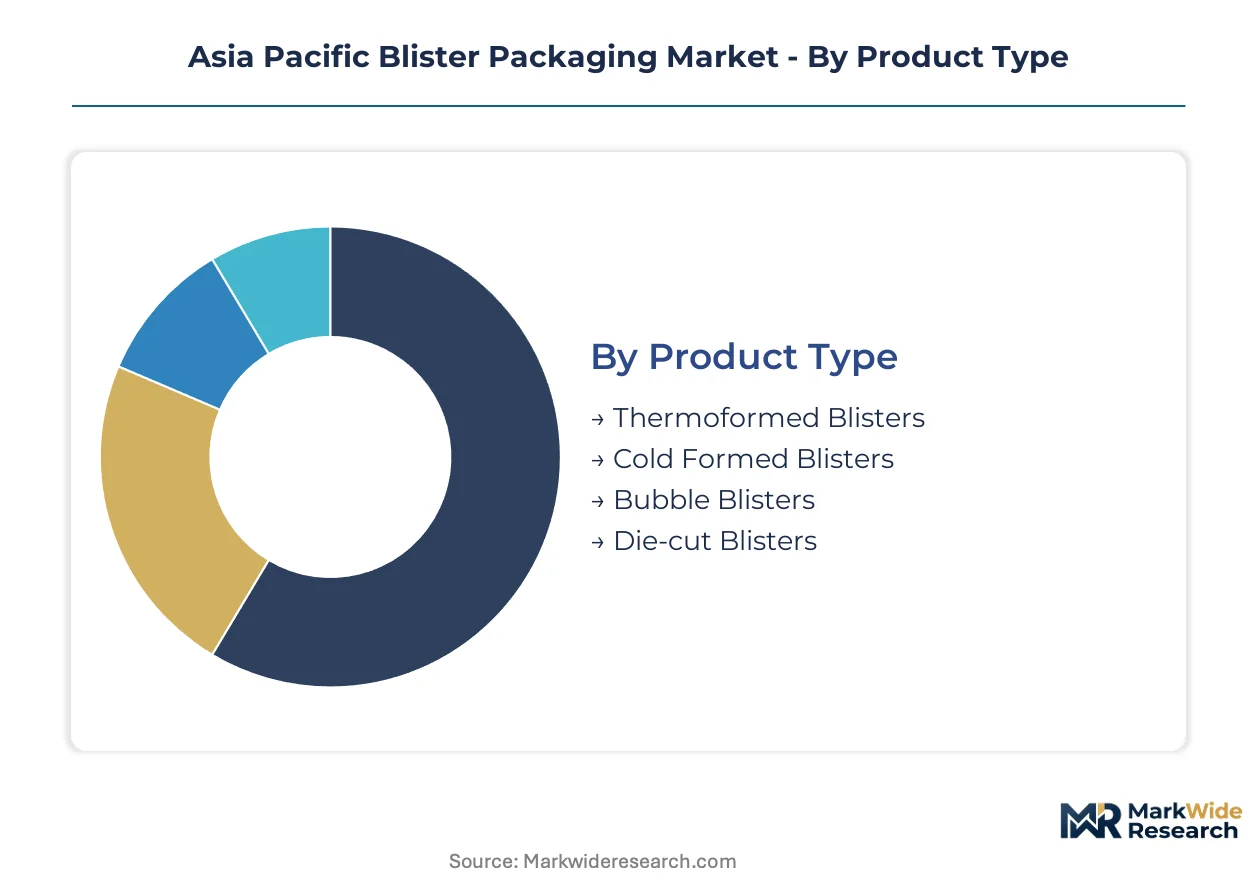
Blister packaging segmentation in Asia Pacific reflects divergent barrier performance requirements across pharmaceutical, electronics, and food applications. Material selection and cavity geometry determine qualification pathways for converters serving regulated industries across Japan, India, and Southeast Asian manufacturing hubs.
Product Type:
Thermoformed formats face mounting substitution pressure from cold formed aluminum as moisture barrier specifications tighten across Japanese and Korean pharmaceutical markets.
- Thermoformed Blisters:PVC and PET-based cavity structures dominate ASEAN generic pharmaceutical packaging due to sub-dollar tooling costs and 300+ cycles per minute throughput. Indian contract packagers in Gujarat and Maharashtra specify these formats for domestic oral solid dosage forms where moisture sensitivity remains moderate.
- Cold Formed Blisters:Deep-drawn aluminum foil with nylon-PVC laminates achieves near-zero moisture vapor transmission rates. Japanese drug manufacturers mandate these structures for PMDA-compliant hygroscopic categories, displacing standard thermoformed alternatives in premium oncology and cardiovascular portfolios.
- Bubble Blisters:Single-cavity dome structures serve over-the-counter analgesic and vitamin segments across Australian retail pharmacy chains.
- Die-cut Blisters:Precision-cut carded formats anchor consumer electronics accessory packaging throughout Shenzhen and Dongguan manufacturing corridors.
Thermoformed Blisters anchor the volume base while Cold Formed Blisters gain share at the steepest rate.
Material:
Raw material cost tiers stratify converter margins, with pharmaceutical-grade aluminum commanding premium positioning against commodity PVC.
- Plastic:PVC and PVDC laminates constitute the thermoformed substrate base across Southeast Asian volume production. Australian jurisdictions are restricting chlorinated polymer deployment, forcing converters toward PET and PP alternatives for generic drug exports.
- Aluminum:Pharmaceutical-grade cold form foil with 45-60 micrometer thickness enables sub-0.5 g/m²/day moisture barriers. Japanese and Korean buyers specify these laminates for stability-critical compounds, with procurement concentrating among integrated suppliers with captive rolling capacity.
- Paperboard:Lidding and backing substrates support child-resistant peel-push mechanisms across Indian pediatric and geriatric drug packaging.
- Fiberboard:Sustainable backing materials are penetrating Australian nutraceutical and organic supplement segments as PVC environmental friction intensifies.
Plastic dominates unit volume while Aluminum expands most quickly in value terms.
End User:
Customer concentration patterns separate pharmaceutical qualification intensity from electronics commodity procurement.
- Pharmaceuticals:Unit-dose oral solid dosage forms drive precision cavity specifications across Japanese, Australian, and Indian regulatory jurisdictions. CDSCO alignment with ICH Q1A stability guidelines is accelerating domestic certification investments for export-oriented contract packagers.
- Consumer Electronics:Earbud, cable, and accessory packaging prioritizes visual clarity and theft deterrence over barrier performance. Shenzhen and Bangkok electronics assemblers specify these formats for retail display efficiency.
- Food Packaging:Confectionery and portion-control applications utilize thermoformed PET structures across ASEAN retail modernization.
- Medical Devices:Sterile barrier requirements for surgical instruments and diagnostic consumables demand Tyvek-lidded formats in Singapore and Sydney healthcare procurement.
Pharmaceuticals command the premium tier while Consumer Electronics generates the highest unit volumes.
Geometry:
Cavity configuration complexity escalates with combination therapy proliferation across oncology and cardiovascular treatment protocols.
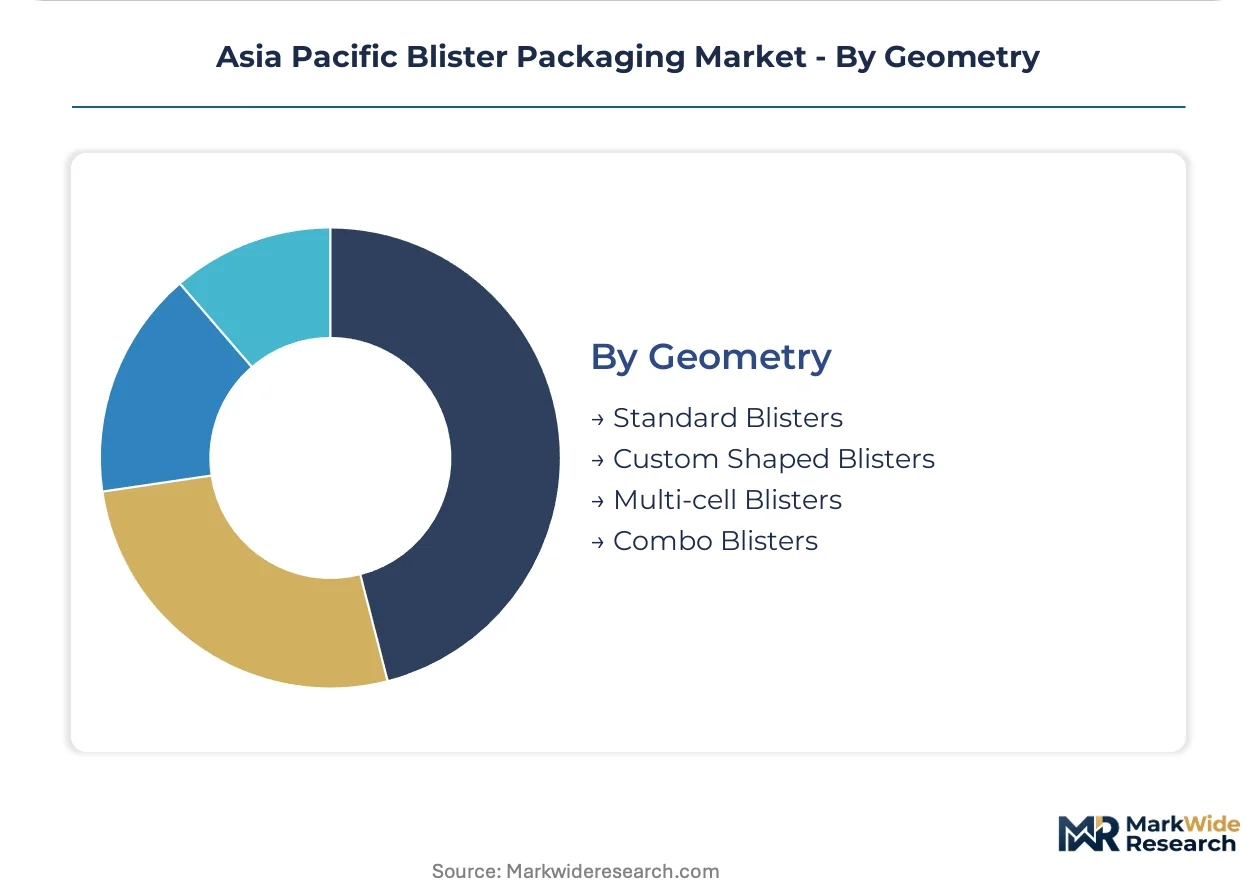
- Standard Blisters:Single-cavity rectangular formats serve commodity generic pharmaceuticals across Indian and Southeast Asian volume markets.
- Custom Shaped Blisters:Brand-differentiated cavity contours accommodate distinctive tablet geometries for patented drug portfolios in Japanese and Australian markets.
- Multi-cell Blisters:Sequential or concurrent dose arrangements enable combination therapies and dose-escalation regimens. Precision thermoforming dies with tighter tolerance bands extend commissioning cycles for these oncology-focused formats.
- Combo Blisters:Integrated device-drug configurations serve inhaler and auto-injector markets across South Korean and Australian specialty pharmaceutical manufacturing.
Standard Blisters retain volume leadership while Multi-cell Blisters climb the fastest on combination therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's blister packaging exports flow predominantly to regulated markets in Japan, Australia, and Southeast Asia, with contract packagers in Gujarat and Maharashtra serving as the primary consolidation nodes for outbound pharmaceutical packaging.
Japan
PMDA moisture vapor transmission thresholds below 0.5 g/m²/day compel domestic drug manufacturers toward aluminum-cold-form dominance. Japanese pharmaceutical converters maintain captive extrusion networks to supply high-barrier Aclar laminates for hygroscopic oncology compounds. The Kanto region around Tokyo concentrates integrated film suppliers with in-house barrier testing laboratories serving both domestic and export-oriented drug makers.
India
CDSCO alignment with ICH Q1A stability guidelines accelerates certification investments among export-oriented contract packagers. BIS standards enforcement drives domestic converters toward upgraded heat-seal coating specifications for oral solid dosage forms. Gujarat and Maharashtra host integrated contract packaging hubs that aggregate demand from generic pharmaceutical exporters targeting regulated markets.
Australia
TGA equivalence requirements filter market access for imported blister films and foils, compelling regional converters to maintain parallel qualification portfolios. PVC environmental restrictions in select jurisdictions force thermoformed blister producers toward PET and PP alternatives. Sydney and Melbourne concentrate headquarters procurement functions mandating local technical support for packaging change controls.
South Korea
MFDS pharmaceutical serialization mandates reshape supplier qualification burdens for blister converters serving domestic and export drug manufacturers. Near-zero moisture and oxygen ingress specifications approach Japanese PMDA thresholds, favoring cold formed aluminum structures for stability-critical compounds. The Seoul Capital Area anchors demand from specialty pharmaceutical manufacturers producing combination therapies requiring multi-cell blister geometries.
Vietnam
Greenfield API and formulation facilities create first-mover advantages for blister converters establishing local technical service capabilities. Fragmented pharmaceutical track-and-trace timelines across ASEAN member states open qualification windows for packaging-IT convergence specialists. Ho Chi Minh City and Hanoi corridors attract contract packaging investments serving both domestic retail pharmacy modernization and regional export markets.
Asia Pacific Blister Packaging Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and barrier technology tiers. The Asia Pacific blister packaging structure concentrates among integrated film suppliers with captive extrusion capacity, particularly in Japan and India, while fragmented regional converters serve commodity thermoformed segments. Three archetypes dominate: backward-integrated polymer and aluminum producers, specialized high-barrier laminate specialists, and regional contract packaging aggregators. Competitive moves center on M&A to secure extrusion assets and strategic partnerships to access pharmaceutical serialization capabilities.
Within the integrated materials tier, Amcor Limited and Uflex Limited exemplify contrasting geographic anchoring strategies. Amcor leverages Australian-listed capital markets to supply Japanese and Australian drug manufacturers, while Mumbai-listed Uflex anchors through in-house polyester and aluminum foil production serving Indian generic exporters. WestRock Company represents the North American-listed packaging conglomerate archetype competing for electronics and pharmaceutical share across Southeast Asian manufacturing corridors.
| Leading Market Players |
|---|
| Amcor Limited |
| Uflex Limited |
| WestRock Company |
| Klockner Pentaplast Group |
| Sonoco Products Company |
| Constantia Flexibles |
| Tekni-Plex Inc |
| Getpac India |
| Perlen Packaging (Suzhou) Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Sixty-day aluminum foil inventory cycles at Japanese pharmaceutical-grade rolling mills concentrate pricing power among integrated suppliers with captive extrusion networks, while Indian contract packagers in Gujarat and Maharashtra face margin compression from spot-market PVC volatility. This lead-time asymmetry between premium cold-form substrates and commodity thermoformed films stratifies converter margins across the Asia Pacific blister packaging landscape.
Pricing Analysis
Current-generation cold formed aluminum structures command substantial premiums over prior-generation PVC-PVDC thermoformed formats, while next-generation Aclar fluoropolymer laminates sit at the apex of the value pyramid. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance certification tiers, with PMDA-compliant sub-0.5 g/m²/day MVTR specifications driving the widest spreads. Cost compression in commodity thermoformed segments is intensifying because Indian generic exporters prioritize unit-dose cost over stability margins. Consumer electronics buyers exhibit the highest price sensitivity, while Japanese oncology drug manufacturers demonstrate minimal elasticity for hygroscopic-compound packaging.
Supply Chain Analysis
Sixty-day aluminum foil inventory cycles tether Japanese and Korean pharmaceutical manufacturers to integrated domestic rolling capacity with limited spot-market flexibility. Supply concentrates in Japan, India, and South Korea for high-barrier laminates, while China and Thailand anchor commodity thermoformed film production. Raw material dependencies center on pharmaceutical-grade aluminum ingots, PVC resin, and nylon barrier films. Single-source vulnerability pervades the Aclar fluoropolymer supply chain, where specialty polymer production rests on two global chemical conglomerates. Distribution runs through regional contract packaging hubs that aggregate demand from generic pharmaceutical exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for seal-strength validation and accelerated stability testing are expanding faster than base film and foil supply, converting blister packaging from a commodity procurement into a recurring-revenue service relationship. This service-attach dynamic rewards converters with regional laboratory networks over pure manufacturing scale.
For Market Incumbents: Compound defensive positioning through backward integration into pharmaceutical-grade aluminum rolling capacity and captive Aclar laminate extrusion to neutralize Japanese converter oligopoly threats. Prioritize certification investments for CDSCO and TGA alignment to maintain approved vendor status as ASEAN serialization mandates fragment supplier qualification pathways. Channel control through exclusive technical service partnerships with Mumbai and Sydney headquarters procurement functions secures multi-year offtake commitments. For New Entrants and Emerging Players: Anchor in Vietnam's greenfield API corridor, where first-mover technical service capabilities for local pharmaceutical manufacturing create qualification windows before incumbent laboratory networks establish presence. Target the multi-cell blister geometry segment for combination therapy packaging, where precision thermoforming die complexity extends commissioning cycles and delays incumbent response. A packaging-IT convergence go-to-market angle captures fragmented ASEAN track-and-trace implementation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pharmaceutical packaging divisions lacking barrier testing laboratory assets. Long-term viability hinges on converter transitions from commodity volume to specialized high-barrier laminate and multi-cell geometry capabilities. Watch for PMDA moisture threshold tightening as the inflection signal accelerating aluminum-cold-form substitution beyond Japanese borders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive pharmaceutical-grade foil supply neutralizes raw material volatility for Japanese and Korean drug manufacturers. |
| Regional Laboratory Network Expansion | Local seal-strength validation capabilities satisfy Sydney and Mumbai procurement mandates for technical service proximity. |
| Aclar Fluoropolymer Laminate Qualification | Ultra-hygroscopic compound compatibility displaces standard PVC-PVDC in Australian oncology packaging specifications. |
| Multi-cell Thermoforming Die Investment | Precision cavity configurations for combination therapies command premium positioning in cardiovascular portfolios. |
| Serialization-IT Platform Partnership | Packaging-IT convergence capabilities capture fragmented ASEAN pharmaceutical track-and-trace implementation windows. |
Study Parameters
Desk research of customs trade databases, pharmaceutical regulatory filings with PMDA and CDSCO, and aluminum industry capacity disclosures preceded structured interviews with blister packaging procurement managers at multinational drug manufacturers, validation engineers at contract packaging facilities, and technical directors at integrated film suppliers. Primary fieldwork with these stakeholders combined with secondary validation against BIS standards documentation and TGA equivalence guidelines. Bottom-up demand modeling from oral solid dosage form production data triangulated with top-down market sizing from converter capacity assessments.
Variance decomposition across material type, end-user segment, cavity geometry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated pharmaceutical serialization mandate timelines across ASEAN member states and moisture barrier specification evolution in Japanese PMDA guidance.
Material uncertainties — aluminum price volatility, regulatory timeline delays, and validation engineer scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about continued CDSCO alignment with ICH stability guidelines and sustained PMDA moisture threshold enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Blister Paper Market