
 North America Veterinary Healthcare Market | 2026-2036
North America Veterinary Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
North America Veterinary Healthcare Market Analytics
The capital-intensity divergence between biologics manufacturers and generic pharmaceutical suppliers is reorganizing competitive tiers in North America veterinary healthcare. Zoetis leverages its vertically integrated vaccine production network across multiple U.S. manufacturing sites. Boehringer Ingelheim anchors its position through sustained R&D investment in monoclonal antibody therapies for companion animals. IDEXX Laboratories dominates the diagnostics layer with proprietary reference laboratory infrastructure and in-clinic analyzer placements.
North America veterinary healthcare encompasses the prevention, diagnosis, and treatment of disease in companion animals, livestock, and wildlife through pharmaceuticals, biologicals, medical devices, and clinical services. Vaccines typically require cold-chain distribution between two and eight degrees Celsius, while diagnostic assays depend on enzyme-linked immunosorbent and polymerase chain reaction methodologies for pathogen detection. Pharmaceuticals and diagnostics command the deepest margin pools, with the former benefiting from patent-protected biologics and the latter from recurring consumable revenue tied to instrument placements. Companion animals generate the fastest-growing demand segment as pet humanization trends elevate willingness-to-pay for specialty therapeutics and advanced imaging.
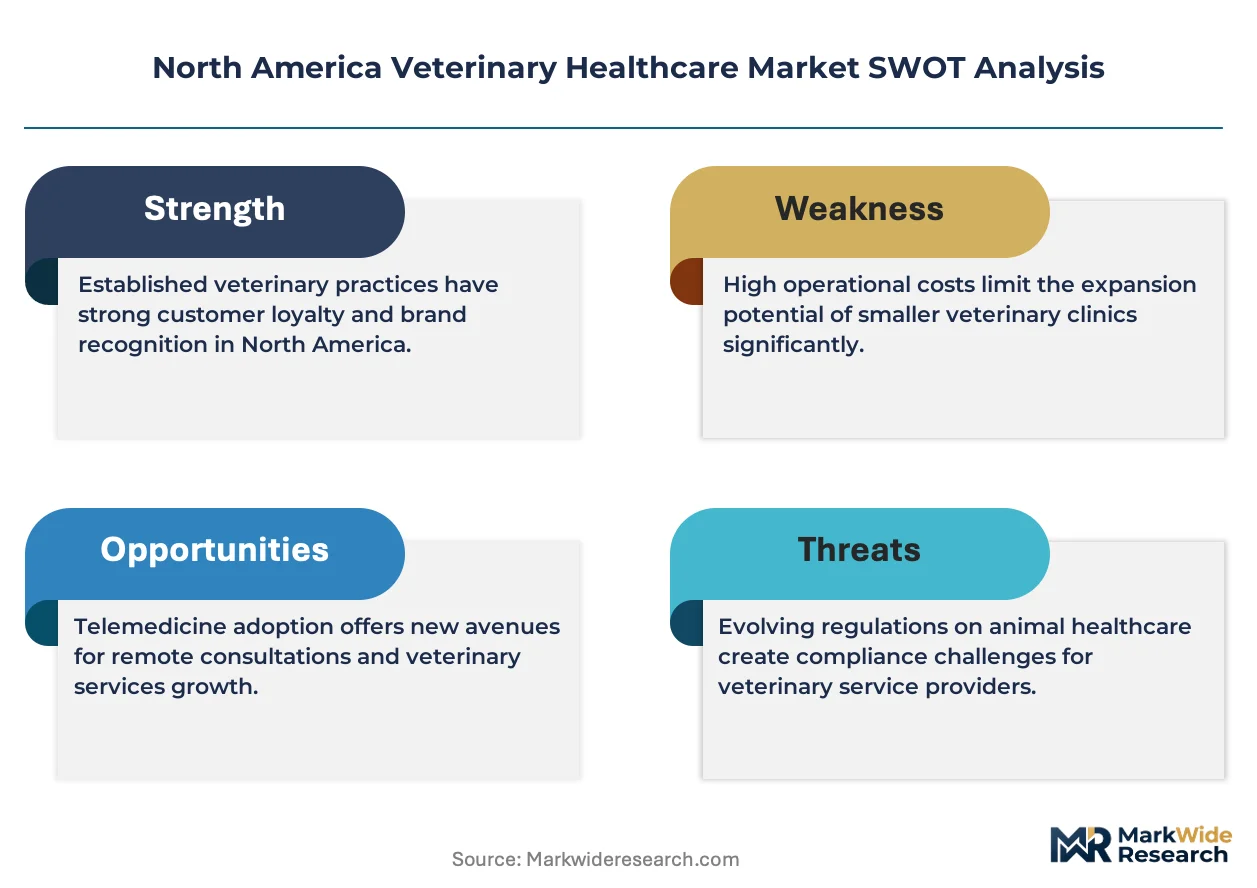
The FDA Center for Veterinary Medicine governs new animal drug approvals, while the USDA Animal and Plant Health Inspection Service regulates veterinary biologics manufacturing and interstate distribution. State veterinary medical boards across California, Texas, New York, and Florida impose continuing education requirements and scope-of-practice boundaries that shape telehealth expansion and mobile clinic licensing. The Drug Enforcement Administration schedules controlled substances used in veterinary anesthesia and pain management, creating compliance costs that favor larger hospital networks over independent practitioners. Stakeholders must monitor evolving state-level telehealth parity legislation and DEA telemedicine prescribing rules to determine capital allocation between physical infrastructure and digital service platforms.
Market Dynamics
The FDA Center for Veterinary Medicine's accelerated approval pathway for monoclonal antibody therapies is compressing development timelines for companion animal biologics and reshaping capital allocation across the sector.
Growth Catalysts
- USDA APHIS Streamlined Licensing:The revised veterinary biologics licensing framework reduces approval timelines for novel vaccines, enabling faster commercialization of recombinant DNA products targeting emerging zoonotic pathogens.
- Telehealth Parity Legislation:State-level mandates in Texas, California, and Florida require reimbursement parity for virtual veterinary consultations, expanding service reach into rural and underserved metropolitan peripheries.
- Companion Animal Diagnostic Panels:Polymerase chain reaction-based pathogen detection is displacing culture-based methods in specialty and emergency clinics, driving recurring consumable demand tied to analyzer placements.
Market Restraints
- Cold-Chain Infrastructure Concentration:Vaccine distribution depends on third-party logistics networks concentrated in the Great Lakes and Northeast corridor, creating vulnerability to regional weather disruptions and capacity constraints.
- Veterinarian Workforce Density:The American Veterinary Medical Association documents persistent shortages of board-certified specialists in diagnostic imaging and oncology across the Mountain West and Central Plains states.
- DEA Scheduling Friction:Controlled substance regulations for veterinary anesthesia impose inventory tracking and disposal compliance costs that disproportionately burden independent practices versus consolidated hospital networks.
Strategic Opportunities
- Wildlife Disease Surveillance:Federal and state agencies in Alaska and the Pacific Northwest are expanding funding for chronic wasting disease and avian influenza monitoring, creating demand for field-deployable diagnostic platforms.
- One Health Data Integration:Convergence of veterinary electronic medical records with public health surveillance systems is enabling predictive outbreak modeling for zoonotic pathogens at the human-animal interface.
- Direct-to-Consumer Preventive Testing:At-home sample collection kits for genetic screening and microbiome analysis are bypassing traditional clinic channels, capturing wellness-oriented companion animal owners in suburban Toronto and Vancouver markets.
Industry Challenges
- Specialized Technician Recruitment:Veterinary technician specialization in anesthesia and dental procedures faces training pipeline constraints, extending staffing timelines for emergency and specialty hospitals in high-cost metropolitan markets.
- Interoperability Standards Lag:Absence of unified data exchange protocols between competing practice management software platforms complicates referral workflows and continuity-of-care documentation across multi-site networks.
- Biologics Manufacturing Scale-Up:Cell culture capacity for veterinary monoclonal antibodies remains constrained, with contract development and manufacturing organizations quoting 18-to-24-month lead times for new production slots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Veterinary Healthcare Market |
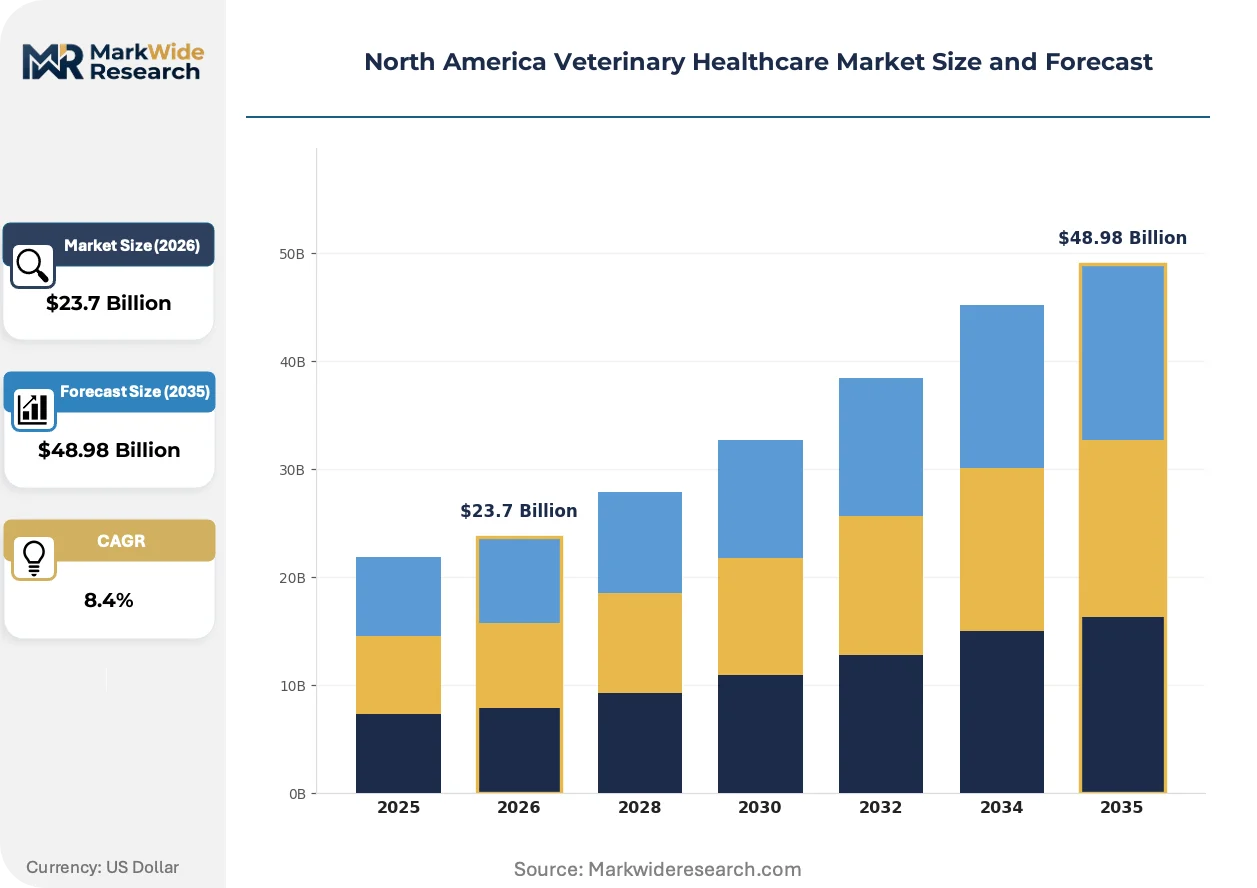
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Medical Devices, Surgical Instruments, Diagnostics Service Type: In-Hospital Services, Telehealth, Mobile Clinics, Preventive Services Animal Type: Companion Animals, Livestock, Exotic Animals, Wildlife End User: Veterinary Hospitals, Clinics, Referral Hospitals, Academic Institutions |
| Companies Covered | Boehringer Ingelheim, Ceva Sante Animale, Zoetis, Neogen Corporation, Dechra Pharmaceuticals, Merck Animal Health, IDEXX Laboratories, Vetoquinol, Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Veterinary Healthcare Market Evolving Landscape
Artificial intelligence-enabled imaging interpretation and point-of-care molecular diagnostics are compressing diagnostic turnaround times and redistributing clinical decision-making authority between specialists and general practitioners.
Next-generation sequencing platforms are displacing targeted PCR panels for infectious disease diagnosis in referral hospitals. Specialty clinics in Boston and San Diego are adopting metagenomic workflows that identify novel pathogens without prior hypothesis. This capability is compressing the diagnostic odyssey for complex cases and reducing empirical antibiotic prescribing.
The FDA Center for Veterinary Medicine's revised guidance on substantial evidence for effectiveness is elevating the evidentiary bar for new animal drug approvals. Sponsors must now demonstrate clinical relevance rather than statistical significance alone, extending development timelines but improving label claims for chronic disease therapeutics. Large animal pharmaceutical divisions are restructuring clinical trial designs to incorporate client-reported outcomes.
Subscription-based wellness plans are displacing fee-for-service billing in companion animal general practice. Corporate veterinary groups in Texas and Ontario are bundling preventive diagnostics, unlimited examinations, and discounted therapeutics into monthly memberships. This model captures lifetime value from pet owners while smoothing revenue cyclicality for practice operators.
North America Veterinary Healthcare Market Segmentation
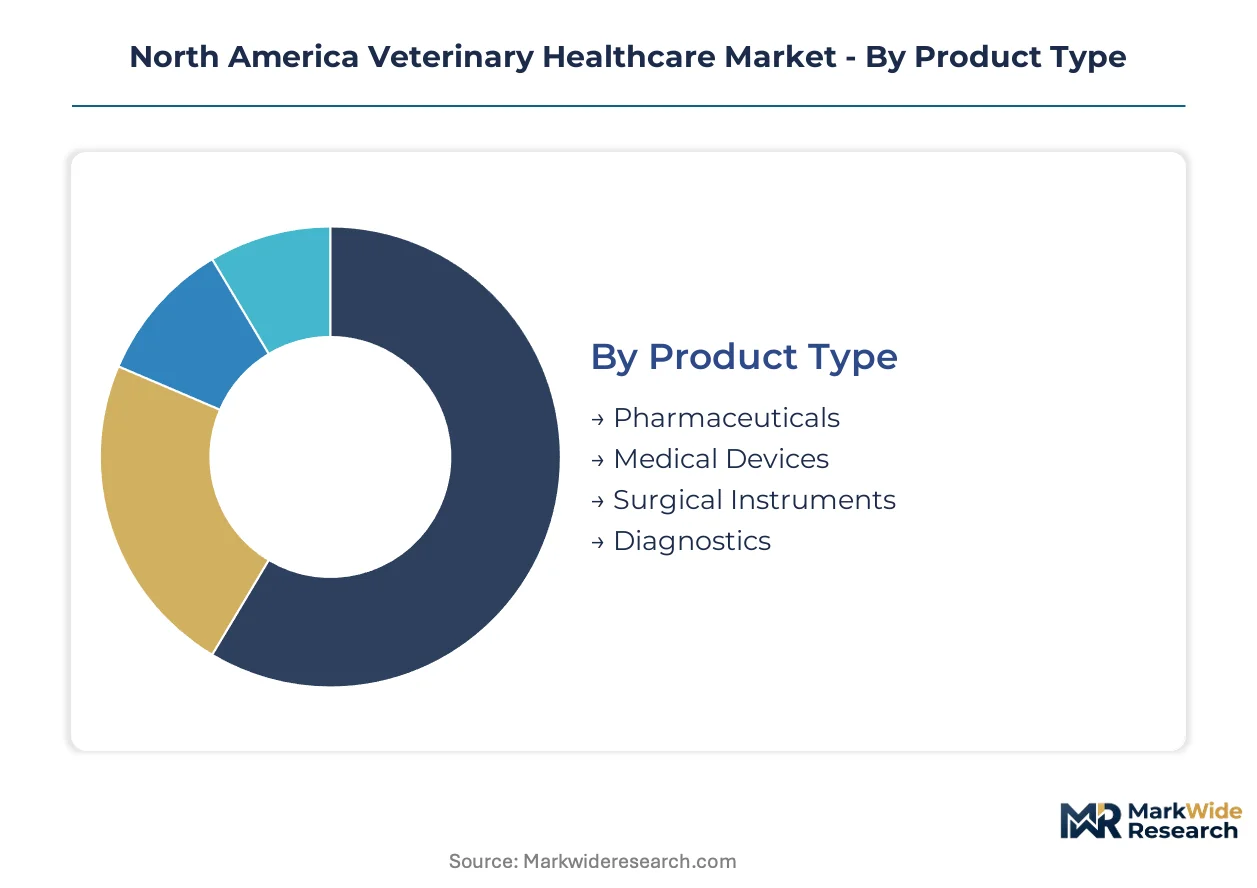
Segmentation in North American veterinary healthcare reveals how regulatory pathways, reimbursement structures, and clinical workflows shape procurement decisions across distinct stakeholder groups. Understanding these divisions enables suppliers to align product development with FDA approval timelines and state-level practice regulations.
Product Type:
FDA Center for Veterinary Medicine approval pathways vary substantially across product categories, with biologics requiring USDA APHIS licensing and pharmaceuticals following New Animal Drug Application protocols.
- Pharmaceuticals:Patent-protected small-molecule drugs and monoclonal antibody therapies for chronic disease management. Demand concentrates in specialty oncology and dermatology practices across Texas and California, where DEA scheduling for controlled substances creates compliance barriers for independent clinics.
- Diagnostics:Enzyme-linked immunosorbent assays, polymerase chain reaction platforms, and reference laboratory services. Urban referral hospitals in Boston and Toronto drive placement of next-generation sequencing instruments, with recurring consumable revenue tied to analyzer installations.
- Medical Devices:Imaging systems, anesthesia machines, and patient monitoring equipment. Academic veterinary medical centers in Ontario and Colorado anchor procurement for high-capital modalities.
- Surgical Instruments:Orthopedic implants, soft tissue staplers, and minimally invasive laparoscopic sets. Emergency and specialty hospitals in Florida metropolitan corridors sustain replacement cycles.
Pharmaceuticals handle the majority of throughput; diagnostics is expanding most quickly on share.
Service Type:
Reimbursement parity mandates in Texas, California, and Florida are redistributing service delivery between physical infrastructure and digital platforms.
- In-Hospital Services:Surgery, emergency stabilization, and intensive care requiring specialized equipment and board-certified specialists. Corporate veterinary networks in Ontario and Texas leverage scale to amortize fixed costs across multi-site operations.
- Telehealth:Virtual consultations and remote monitoring enabled by state-level parity legislation. Rural peripheries of the Mountain West and Central Plains access specialty expertise without geographic relocation of patients.
- Mobile Clinics:Vaccination and wellness services delivered via modified vehicle platforms. Municipal licensing requirements in California and Florida create operational friction for independent operators.
- Preventive Services:Vaccination, parasite control, and nutritional counseling bundled into subscription plans. Suburban Toronto and Vancouver markets capture wellness-oriented companion animal owners through direct-to-consumer channels.
In-hospital services dominate revenue contribution; telehealth is climbing the fastest on volume.
Animal Type:
Species-specific regulatory frameworks and disease surveillance priorities segment procurement and service delivery across veterinary practice types.
- Companion Animals:Dogs, cats, and small mammals receiving preventive and specialty care. Metropolitan clusters in California, Texas, and Ontario drive willingness-to-pay for advanced imaging and monoclonal antibody therapies.
- Livestock:Cattle, swine, and poultry production systems requiring herd health management. USDA APHIS regulations for interstate movement certificates shape service delivery in Great Plains feedlot corridors.
- Exotic Animals:Avian, reptile, and small mammal species demanding specialized anesthesia and surgical expertise. Zoological institutions and private collections in Florida and California sustain niche practice viability.
- Wildlife:Free-ranging populations subject to federal and state surveillance programs. Alaska and Pacific Northwest agencies fund chronic wasting disease and avian influenza monitoring through field-deployable diagnostics.
Companion animals command the deepest revenue pools; wildlife is gaining share fastest on federal surveillance investment.
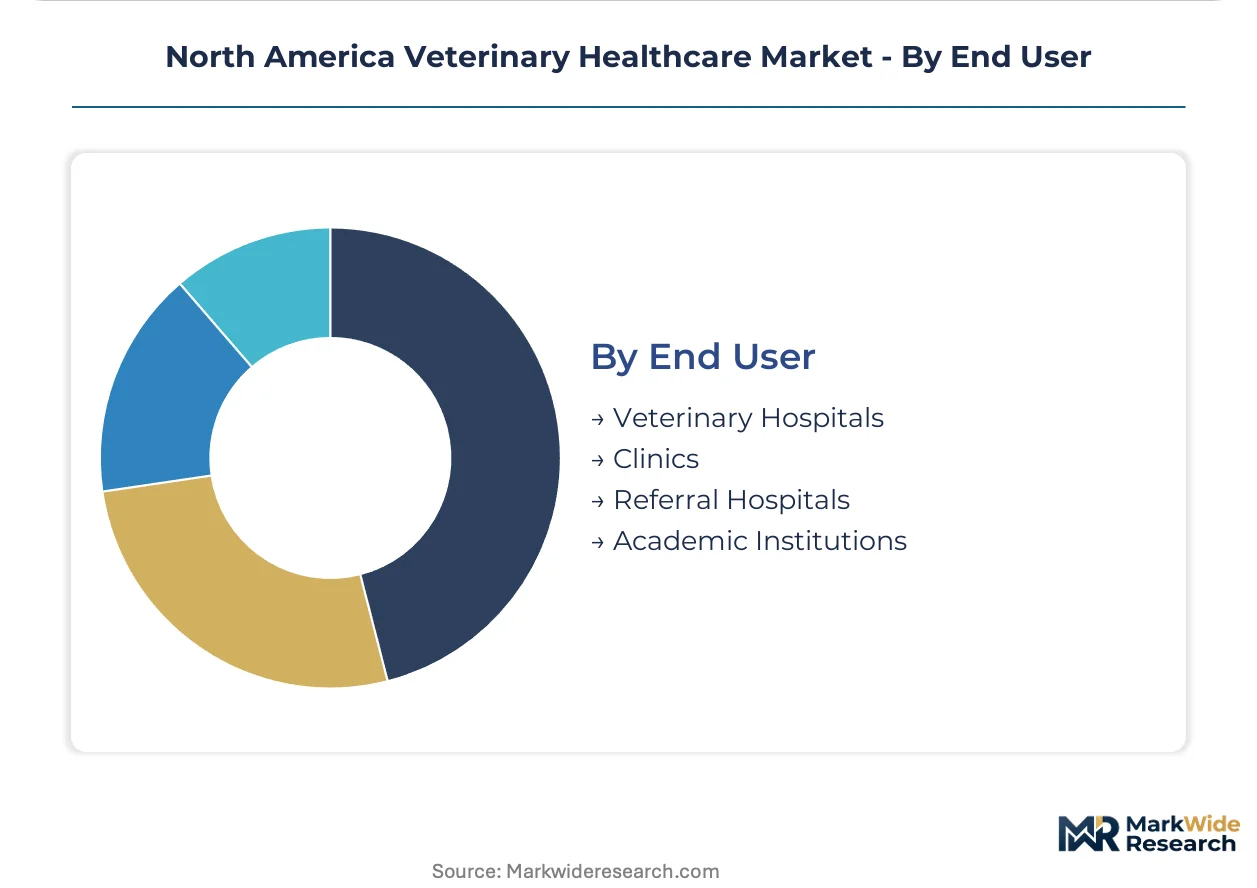
End User:
Capital intensity and regulatory compliance requirements stratify procurement authority across institutional types.
- Veterinary Hospitals:Multi-doctor practices with in-house surgical and imaging capabilities. Corporate consolidation in Texas and Ontario creates centralized purchasing leverage for pharmaceutical and diagnostic contracts.
- Clinics:General practice settings emphasizing preventive care and primary diagnostics. Independent operators in California face DEA compliance costs that favor membership in larger networks.
- Referral Hospitals:Specialty centers for oncology, cardiology, and advanced surgery. Board-certified specialist density in Boston and San Diego concentrates demand for next-generation sequencing and monoclonal antibody access.
- Academic Institutions:Veterinary medical schools integrating research, teaching, and clinical service. Colorado State University and University of Guelph anchor clinical trial recruitment for FDA-substantiated effectiveness studies.
Veterinary hospitals process the highest transaction volumes; referral hospitals are expanding most rapidly on specialty service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in veterinary biologics, exporting recombinant vaccines to Mexico and Canada while importing specialized diagnostic instruments from European suppliers. Cross-border regulatory harmonization through the USMCA veterinary chapter reduces friction for pharmaceutical shipments. Metropolitan veterinary clusters concentrate procurement authority and shape regional demand patterns.
United States
Companion animal owners in California and Texas drive spending on monoclonal antibody therapies and advanced imaging modalities. The FDA Center for Veterinary Medicine maintains accelerated approval pathways for novel biologics, compressing development timelines for sponsors. The Dallas-Fort Worth metroplex anchors corporate veterinary consolidation, with multi-site networks centralizing pharmaceutical purchasing contracts.
Canada
Suburban markets around Toronto and Vancouver capture wellness-oriented pet owners through direct-to-consumer genetic testing and microbiome analysis kits. Health Canada and the Pest Management Regulatory Agency coordinate with USDA APHIS on veterinary biologics import protocols. The University of Guelph veterinary medical center anchors clinical trial recruitment for FDA-substantiated effectiveness studies in large animal therapeutics.
Mexico
Livestock producers in Jalisco and Nuevo León demand herd health management services tied to USDA APHIS interstate movement certificate requirements for cattle exports. The national pharmaceutical regulator oversees import licensing for veterinary pharmaceuticals from U.S. manufacturers. Guadalajara's veterinary service corridor concentrates diagnostic laboratory capacity serving Pacific coast feedlot operations.
California
Specialty oncology and dermatology practices in Los Angeles and San Francisco command premium pricing for chronic disease therapeutics and allergy immunotherapy. State veterinary medical boards impose continuing education requirements that shape telehealth expansion and mobile clinic licensing protocols. The San Diego metropolitan area drives adoption of next-generation sequencing platforms for infectious disease diagnosis in referral hospitals.
Texas
Corporate veterinary groups in Houston and Dallas bundle preventive diagnostics into subscription-based wellness plans, capturing lifetime value from companion animal owners. State-level telehealth parity mandates require reimbursement parity for virtual veterinary consultations, expanding service reach into rural peripheries. The Austin-San Antonio corridor anchors field-deployable diagnostic platform development for wildlife disease surveillance programs.
North America Veterinary Healthcare Market Competitive Landscape
Concentration sits with vertically integrated biologics manufacturers and diagnostics platform specialists. The sector organizes into three tiers: multinational pharmaceutical conglomerates with captive vaccine production networks, reference laboratory operators with proprietary analyzer placements, and regional distributors serving independent practice networks. Competitive dynamics center on M&A-driven consolidation of emergency and specialty hospital networks, plus strategic partnerships between diagnostics manufacturers and corporate veterinary groups for exclusive analyzer placements.
Within the integrated pharmaceutical tier, Zoetis and Boehringer Ingelheim occupy positions exemplifying backward integration into vaccine production and sustained R&D commitment to companion animal biologics. IDEXX Laboratories anchors the diagnostics layer through reference laboratory infrastructure and in-clinic analyzer ecosystems. These three entities represent distinct competitive archetypes: captive manufacturing scale, monoclonal antibody specialization, and diagnostic consumable recurring revenue models.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Ceva Sante Animale |
| Zoetis |
| Neogen Corporation |
| Dechra Pharmaceuticals |
| Merck Animal Health |
| IDEXX Laboratories |
| Vetoquinol |
| Elanco Animal Health |
| Others |
Value Network & Pricing Analysis
FDA Center for Veterinary Medicine approval tiers simultaneously gate supplier qualification and stratify price levels across the North American veterinary healthcare landscape. Biologics manufacturers bearing USDA APHIS licensing investments command premium positioning against unlicensed commodity suppliers, while DEA registration requirements for controlled substances create additional compliance cost barriers that reshape competitive tiers.
Pricing Analysis
Corporate veterinary networks anchor pricing power through centralized pharmaceutical purchasing contracts that extract volume discounts from manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected monoclonal antibody therapies from authorized generics and commodity parasiticides. Cost compression in the generic pharmaceutical tier intensifies because independent distributors consolidate purchasing leverage. Independent practitioners in rural markets exhibit highest price sensitivity, while specialty referral hospitals in Boston and San Diego demonstrate lowest elasticity for novel biologics.
Supply Chain Analysis
Cold-chain infrastructure concentration in the Great Lakes and Northeast corridor underwrites vaccine distribution reliability for temperature-sensitive biologics. Cell culture media, sterile filtration assemblies, and chromatography resins draw from suppliers anchored in the United States, Germany, and Japan. Single-source vulnerability in contract manufacturing organization capacity for veterinary monoclonal antibodies creates 18-to-24-month production slot constraints. Distribution runs through third-party logistics networks with regional hub-and-spoke configurations serving metropolitan veterinary clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages. FDA and USDA licensing requirements impose switching costs that protect incumbent positions against unqualified entrants.
For Market Incumbents: Shield market position through backward integration into cell culture manufacturing capacity in Texas and California manufacturing corridors. Lock in exclusive analyzer placement contracts with corporate veterinary groups to secure recurring consumable revenue streams against emerging diagnostics platform competitors. Prioritize R&D investment in companion animal monoclonal antibody pipelines to exploit FDA accelerated approval pathway advantages.
For New Entrants and Emerging Players: USDA APHIS streamlined licensing for recombinant DNA vaccines offers the fastest certification fast-track for novel biologics targeting emerging zoonotic pathogens. White-space opportunity concentrates in field-deployable diagnostic platforms for wildlife disease surveillance programs in Alaska and the Pacific Northwest. Direct-to-consumer preventive testing kits for genetic screening and microbiome analysis bypass traditional clinic channels in suburban Toronto and Vancouver markets. Go-to-market execution should prioritize veterinary telehealth platforms enabled by state-level parity legislation in Texas, California, and Florida.
For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine revised guidance on substantial evidence for effectiveness reshapes the acquisition landscape by elevating development timelines and capital requirements for new animal drug approvals. Long-term viability favors targets with established USDA APHIS licensing infrastructure and proprietary reference laboratory networks. Acquisition target archetype: diagnostics platform specialists with installed base analyzer placements and recurring consumable revenue models. Monitor DEA telemedicine prescribing rule evolution as the critical inflection signal for digital service platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA APHIS Streamlined Licensing Pursuit | Accelerates recombinant vaccine commercialization timelines for emerging zoonotic pathogens. |
| Reference Laboratory Network Expansion | Captures recurring consumable revenue tied to proprietary analyzer placements in specialty clinics. |
| Corporate Veterinary Group Partnership | Secures exclusive diagnostics platform access through multi-site network purchasing contracts. |
| Cell Culture Manufacturing Scale-Up | Addresses 18-to-24-month production slot constraints for veterinary monoclonal antibody capacity. |
| Telehealth Platform Development | Exploits state-level parity mandates in Texas, California, and Florida for virtual consultation reimbursement. |
Research Methodology
Operator-level perspectives from veterinary practice owners, pharmaceutical regulatory affairs leads, reference laboratory operations directors, and corporate veterinary group procurement managers anchored the qualitative base. Primary interviews combined with secondary validation drawn from FDA Center for Veterinary Medicine approval databases, USDA APHIS veterinary biologics licensing records, and state veterinary medical board continuing education requirements. Bottom-up and top-down triangulation cross-referenced product-level demand signals with macroeconomic indicators across the North American region.
Sensitivity analysis across multiple scenario assumptions tested forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, service delivery mode, animal species category, and end-user institutional archetype. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments. Key inputs incorporated FDA approval pathway timelines, DEA scheduling friction impacts on independent practice economics, and telehealth parity legislative adoption curves.
Underlying assumptions cover regulatory pathway stability, cold-chain infrastructure reliability, and veterinarian workforce density trends, with deviation risk concentrated in DEA telemedicine prescribing rule changes and state-level scope-of-practice boundary shifts. Practitioners should keep alternative scenarios live as federal and state regulatory frameworks for veterinary service delivery evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Antibiotics Market
Veterinary
Veterinary Excipients Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Veterinary Scales Market
Veterinary
Canine Flu Therapeutics Market
Veterinary
Isoxazoline Market
Veterinary
Veterinary Supplements Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Pet Veterinary Diet Market
Veterinary
France Veterinary Healthcare Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Global Veterinary Monitoring Equipment Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Bovine Collagen Market
Veterinary
Pet DNA Testing Market