
 Veterinary Disinfectants Market | 2026-2036
Veterinary Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Disinfectants Market Analytics
The EU Green Deal is pivoting veterinary disinfectant procurement toward biodegradable actives and reduced-residue chemistries. Kersia Group leverages its European manufacturing footprint to supply peracetic acid blends compliant with REACH-descending substance restrictions. Lanxess AG anchors its position through captive bromine chemistry and veterinary-specific phenolic formulations. Ecolab competes on bundled hygiene programs that integrate disinfectants with dosing equipment and audit services.
Veterinary disinfectants are antimicrobial formulations designed to eliminate or inactivate pathogenic microorganisms on surfaces, equipment, and animal housing; quaternary ammononium compounds typically deliver 99.9% bacterial kill at 500–1000 ppm active concentration within ten minutes of contact time, while hydrogen peroxide-based systems decompose to water and oxygen, leaving no tissue-accumulating residues. Liquid formulations dominate volume throughput due to compatibility with existing spray and fogging infrastructure across veterinary clinics and farm operations. Powder and foam formats are gaining share in animal shelter and laboratory settings where extended surface cling and controlled dilution improve coverage economics. Chlorine compounds retain cost-sensitive farm penetration despite corrosion limitations on metal equipment.
EPA registration requirements in the United States, REACH compliance obligations under ECHA in Europe, and FSSAI sanitation standards for veterinary facilities in India collectively elevate barrier costs for new market entrants and force continuous reformulation cycles among incumbent suppliers. The EU F-Gas Regulation and descending MEE discharge limits in China are further narrowing the acceptable chemistry set for large-scale livestock operations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which active ingredients will retain multi-region registration eligibility.
Market Dynamics
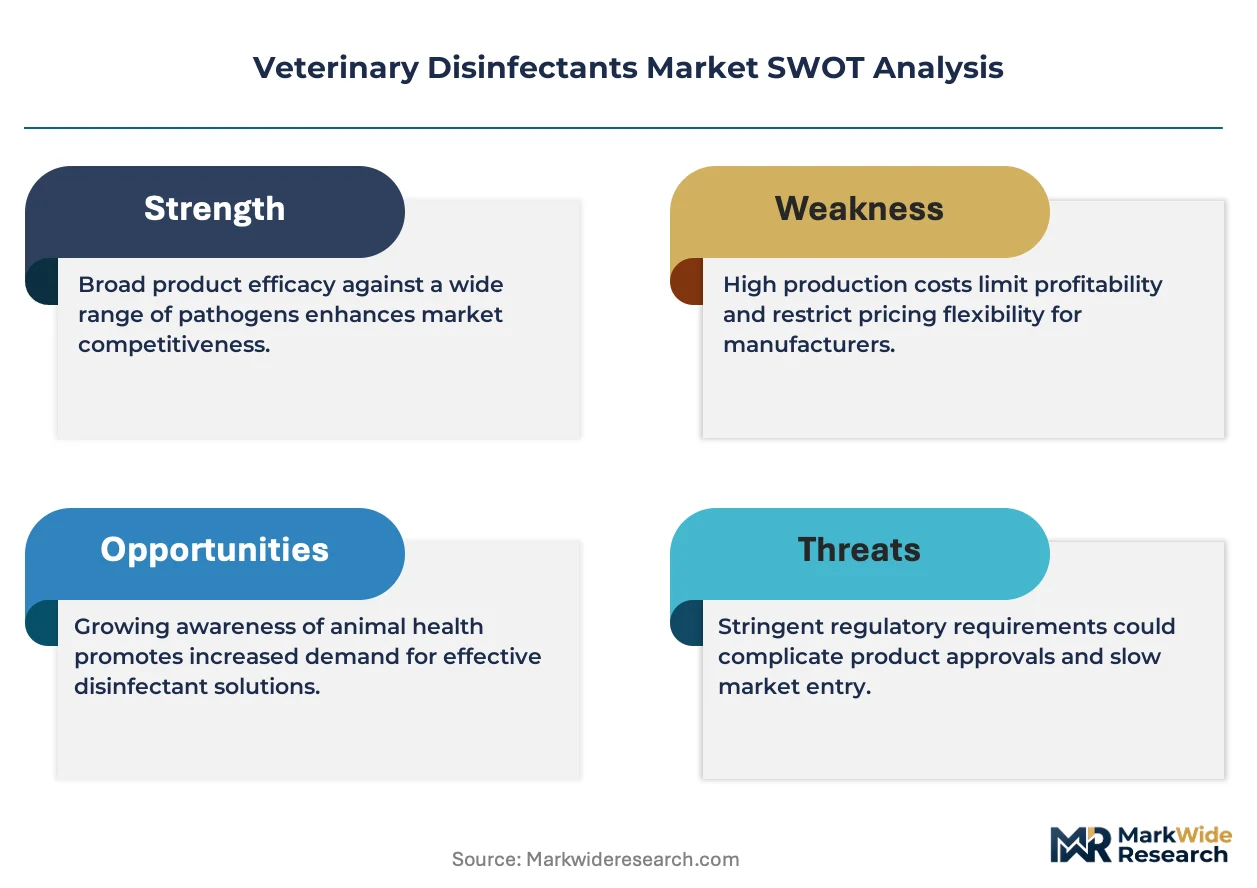
REACH-descending substance restrictions are compressing the chemistry set available to formulators, forcing continuous reformulation cycles and elevating barrier costs for new entrants while advantaging European manufacturers with captive active ingredient production.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Biodegradable active requirements are redirecting procurement toward peracetic acid and hydrogen peroxide systems in livestock operations across Germany, France, and the Netherlands.
- Intensifying livestock biosecurity protocols:Commercial poultry and dairy farms in Brazil's Paraná and Minas Gerais states are mandating documented disinfection regimens, expanding recurring chemical consumption.
- Peracetic acid blend technology:Sporicidal efficacy at ambient temperatures without corrosion damage to aluminum equipment is displacing chlorine in automated fogging systems.
Market Restraints
- Bromine feedstock concentration:Captive bromine chemistry controlled by Dead Sea and Arkansas brine operations creates supply vulnerability for phenolic disinfectant manufacturers.
- Corrosion limitations of chlorine compounds:Metal equipment degradation in high-humidity poultry houses restricts sodium hypochlorite application despite cost advantages.
- EPA registration timelines:New active ingredient approvals require multi-year toxicology studies and efficacy dossiers, freezing formulation innovation cycles.
Strategic Opportunities
- India's FSSAI veterinary facility standards:Sanitation mandates for large-animal hospitals and dairy cooperatives in Maharashtra and Gujarat are opening formal distribution channels previously served by informal chemical suppliers.
- Powder format penetration:Controlled dilution economics and extended surface cling are gaining adoption in animal shelter and laboratory settings where coverage precision matters.
- EU F-Gas Regulation chemistry narrowing:Descending acceptable substance lists are creating first-mover advantage for formulators with pre-validated biodegradable actives.
Industry Challenges
- Reformulation talent scarcity:Chemists with combined veterinary efficacy and REACH compliance expertise command premium compensation, constraining mid-tier manufacturer R&D bandwidth.
- Legacy spray infrastructure incompatibility:Hydrogen peroxide-based systems require nozzle material upgrades and recalibrated dosing pumps, complicating farm-level adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Disinfectants Market |
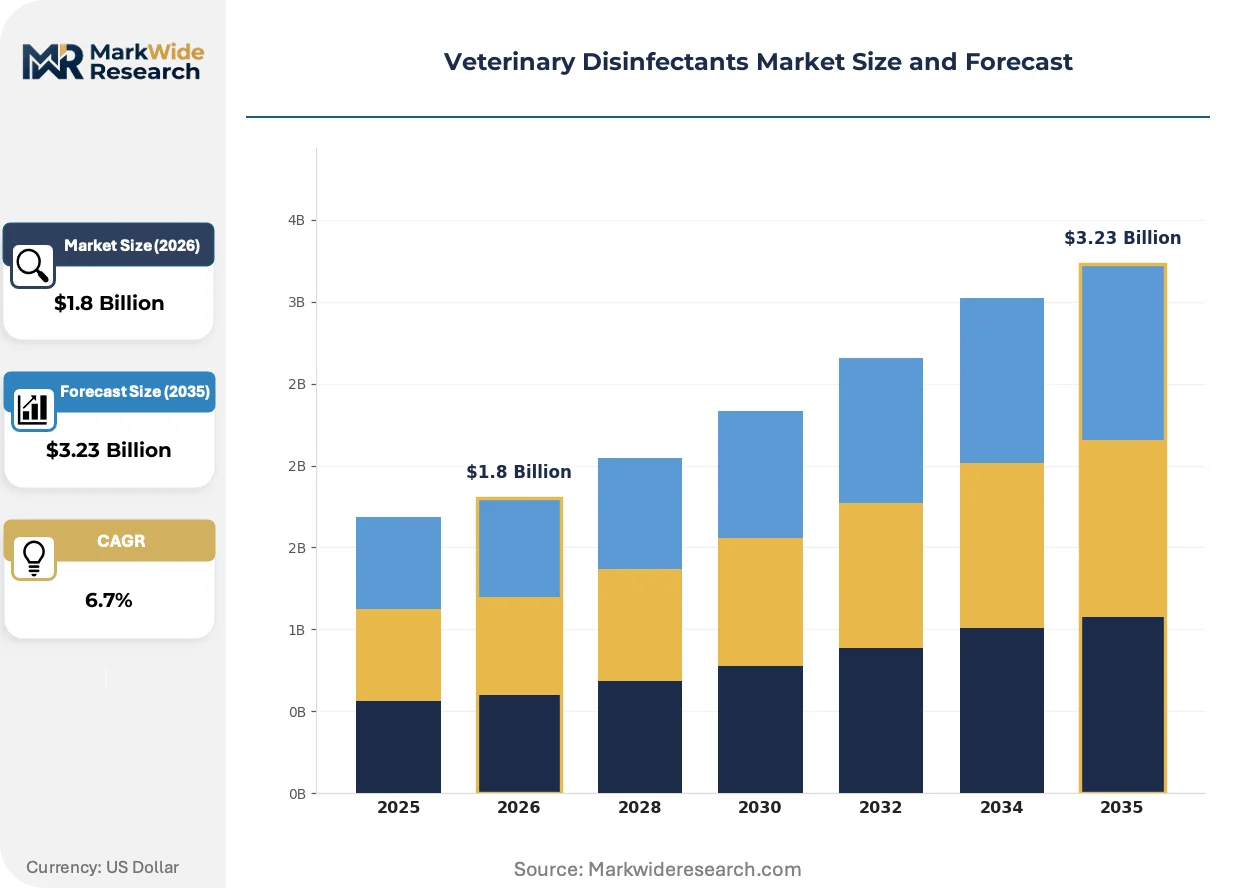
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Phenolic Compounds, Chlorine Compounds, Hydrogen Peroxide Application: Veterinary Clinics, Animal Shelters, Farms, Laboratories Form: Liquid, Powder, Foam, Wipes End User: Veterinarians, Animal Care Facilities, Research Institutes, Distributors |
| Companies Covered | Kersia Group, Lanxess AG, Ecolab, Evonik Industries AG, Zoetis Inc., GEA Group, Neogen Corporation, Virbac SA, Ceva Santé Animale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Disinfectants Market Evolving Landscape
Formulation chemistry is pivoting toward residue-free decomposition pathways as regulatory pressure intersects with veterinary tissue safety requirements, reshaping how actives are selected, validated, and dosed across livestock and companion animal settings.
Electrolyzed water systems are absorbing capital investment from large-scale broiler operations seeking to eliminate chemical storage liability and drum disposal costs. Brazilian integrators in Santa Catarina are piloting on-site generation units that produce hypochlorous acid at point of use. This technology is absorbing margin pressure from bulk chlorine procurement while creating new equipment-service bundling requirements for chemical suppliers.
REACH authorization sunset dates for quaternary ammonium compound precursors are forcing European formulators to submit substitution dossiers or secure time-limited derogations. The industrial consequence is accelerated validation of alternative actives including lactic acid blends and accelerated hydrogen peroxide. Veterinary clinics in France and Germany are most affected, responding by consolidating purchases with suppliers holding pre-validated multi-active portfolios.
Integrated hygiene service contracts are displacing transactional chemical procurement in North American dairy operations. Large cooperatives in Wisconsin and California are unbundling equipment, audit, and chemical spend into single-source agreements with performance guarantees. This pattern is most visible in regions with consolidated milk processing infrastructure where biosecurity documentation supports export market access.
Veterinary Disinfectants Market Segmentation
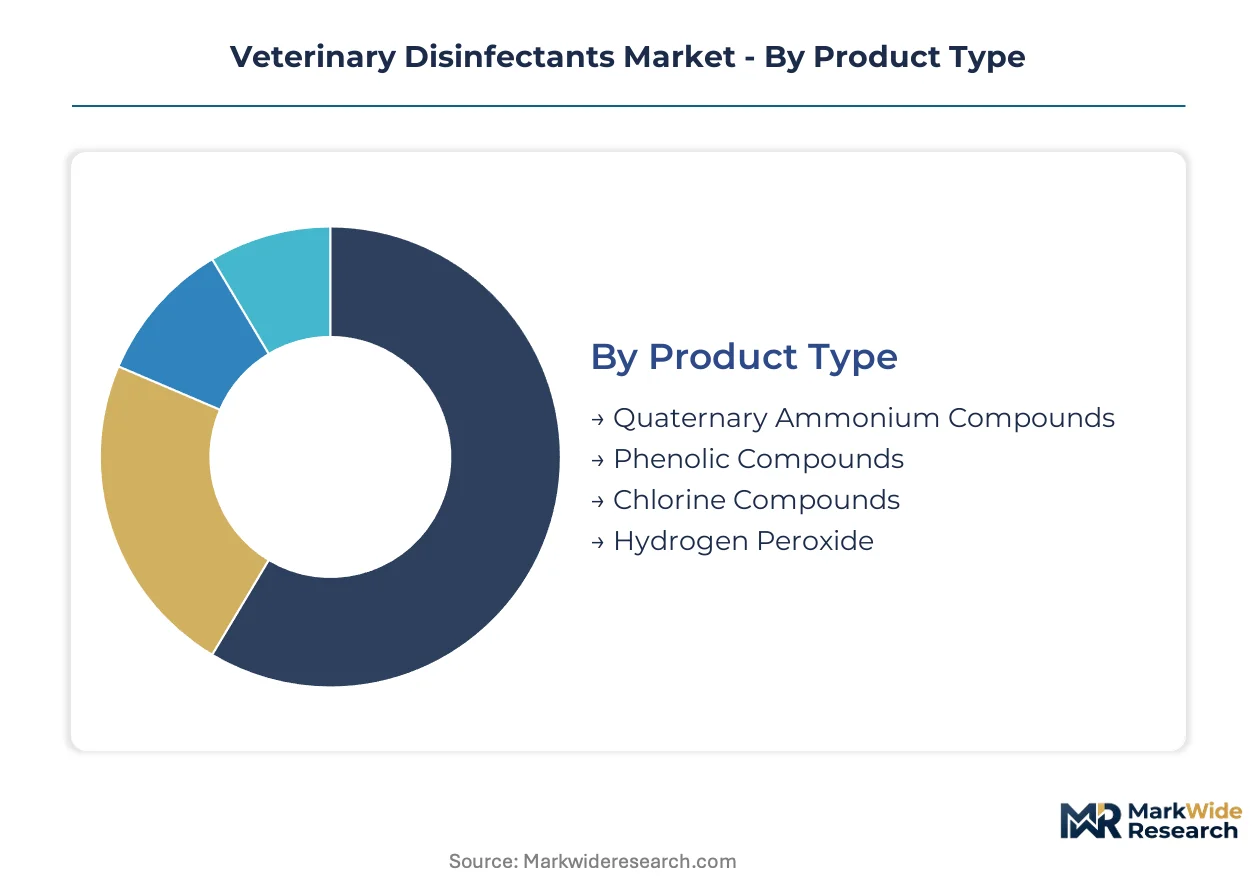
Veterinary disinfectant procurement splits sharply between high-throughput livestock operations seeking cost efficiency and specialized facilities demanding validated efficacy documentation. Formulation chemistry, application setting, and delivery format each create distinct margin tiers and regulatory exposure profiles for suppliers.
Product Type:
Volume throughput concentrates in legacy chemistries with established supply chains, while premium positioning migrates toward residue-free actives facing steeper regulatory compliance burdens.
- Quaternary Ammonium Compounds:Cationic surfactants disrupt microbial cell membranes at 500–1000 ppm active concentration, delivering 99.9% bacterial kill within ten minutes. Demand clusters in veterinary clinics across Germany and France where surface compatibility with examination tables and stainless steel equipment matters. REACH authorization sunset dates for precursor substances are forcing European formulators to submit substitution dossiers or secure time-limited derogations.
- Hydrogen Peroxide:Accelerated formulations decompose to water and oxygen, eliminating tissue-accumulating residues that complicate livestock export certification. Brazilian poultry integrators in Santa Catarina are piloting automated fogging systems with peracetic acid blends that operate at ambient temperatures without corroding aluminum equipment. The chemistry commands premium pricing but requires nozzle material upgrades and recalibrated dosing pumps.
- Phenolic Compounds:Captive bromine chemistry from Dead Sea and Arkansas brine operations anchors supply for veterinary-specific tar-acid derivatives.
- Chlorine Compounds:Sodium hypochlorite retains cost-sensitive penetration in Brazilian dairy regions despite corrosion limitations on metal equipment in high-humidity housing.
Today's leader: Quaternary Ammonium Compounds. Tomorrow's challenger: Hydrogen Peroxide.
Application:
Farm operations generate volume through recurring bulk consumption, while clinical and laboratory settings concentrate spending on validated, documented regimens.
- Farms:Commercial poultry and dairy operations in Brazil's Paraná and Minas Gerais states mandate documented disinfection regimens, expanding recurring chemical consumption through integrated hygiene service contracts. Large cooperatives in Wisconsin and California are unbundling equipment, audit, and chemical spend into single-source agreements with performance guarantees tied to export market access.
- Veterinary Clinics:Small-animal hospitals in France and Germany are consolidating purchases with suppliers holding pre-validated multi-active portfolios to navigate REACH-descending substance restrictions. Efficacy documentation requirements for EU veterinary practice accreditation elevate procurement sophistication.
- Animal Shelters:Controlled dilution economics and extended surface cling are gaining adoption where coverage precision matters and staff turnover complicates training.
- Laboratories:Research facilities require sporicidal validation and residue-free chemistries to protect cell culture integrity and comply with GLP documentation standards.
Farms dominate volume. Veterinary clinics concentrate margin through bundled compliance services.
Form:
Liquid formats leverage installed spray infrastructure, while alternative delivery modes capture premium through coverage precision and controlled dilution.
- Liquid:Dominates throughput due to compatibility with existing spray and fogging infrastructure across veterinary clinics and farm operations. Bulk tank systems and automated dosing equipment reduce labor costs in large-scale broiler houses.
- Powder:Controlled dilution economics and extended shelf stability are gaining adoption in animal shelter and laboratory settings where inventory management and coverage precision matter. Maharashtra and Gujarat dairy cooperatives in India are opening formal distribution channels for powder formats previously served by informal chemical suppliers.
- Foam:Extended surface cling improves contact time on vertical equipment surfaces in high-humidity poultry housing.
- Wipes:Pre-saturated formats reduce dilution error risk in veterinary clinics with high staff turnover and limited technical training.
Liquid holds installed base. Powder climbs fastest through emerging market formalization.
End User:
Procurement authority fragments between clinically trained veterinarians seeking efficacy validation and facility managers optimizing cost per square meter.
- Veterinarians:Small-practice owners in France and Germany prioritize surface compatibility and tissue safety documentation over unit cost, consolidating with suppliers offering multi-active portfolios and REACH compliance guarantees.
- Animal Care Facilities:Shelter operators in India and Brazil balance efficacy requirements against constrained operating budgets, creating demand for powder formats with controlled dilution economics.
- Research Institutes:GLP-compliant laboratories require validated sporicidal actives and residue-free decomposition pathways to protect experimental integrity.
- Distributors:Channel intermediaries in emerging markets are formalizing to serve FSSAI sanitation mandates for large-animal hospitals and dairy cooperatives in Maharashtra and Gujarat.
Veterinarians anchor premium positioning. Distributors reshape access in underpenetrated regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The veterinary disinfectants industry traces its modern commercial roots to post-war European chemical manufacturing, where German and Swiss firms first systematized phenolic formulations for livestock disease control. From these origins, production expertise diffused through multinational chemical conglomerates and specialized agricultural suppliers, establishing regional clusters tied to regulatory sophistication and livestock density.
United States
Large-scale dairy cooperatives in Wisconsin and California drive institutional procurement through integrated hygiene service contracts with performance guarantees. EPA registration timelines for new active ingredients extend multi-year approval cycles, freezing formulation innovation. The Corn Belt's concentrated animal feeding operations anchor volume consumption of legacy chlorine chemistries despite infrastructure corrosion concerns.
Germany
Small-animal veterinary clinics in Bavaria and North Rhine-Westphalia consolidate purchases with suppliers holding REACH-compliant multi-active portfolios. The EU Green Deal's Farm to Fork mandates accelerate biodegradable active requirements, redirecting procurement toward peracetic acid systems. Frankfurt's chemical formulation hub hosts captive production of veterinary-specific phenolic derivatives.
Brazil
Commercial poultry integrators in Paraná and Santa Catarina mandate documented disinfection regimens, expanding recurring chemical consumption through automated fogging systems. ANVISA veterinary product regulations formalize import substitution pressures. Minas Gerais dairy regions balance cost-sensitive sodium hypochlorite use against equipment replacement economics in high-humidity housing.
India
FSSAI sanitation mandates for large-animal hospitals and dairy cooperatives in Maharashtra and Gujarat open formal distribution channels previously served by informal chemical suppliers. Powder formats with controlled dilution economics gain adoption among budget-constrained shelter operators. Karnataka's veterinary pharmaceutical corridor attracts contract manufacturing investment from multinational suppliers.
France
Veterinary practice accreditation requirements in Île-de-France and Auvergne-Rhône-Alpes elevate procurement sophistication toward documented efficacy portfolios. REACH authorization sunset dates for quaternary ammonium precursors force substitution dossier submissions. Lyon's chemical engineering cluster specializes in accelerated hydrogen peroxide validation for residue-free decomposition pathways.
Veterinary Disinfectants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance depth and captive active ingredient access. The vendor base stratifies between European manufacturers with backward-integrated bromine or peroxygen chemistry and regional formulators dependent on merchant raw material supply. Three archetypes dominate: multinational chemical conglomerates with veterinary divisions, specialized agricultural hygiene suppliers, and animal health pharmaceutical companies with surface disinfection extensions. Consolidation pressure operates through M&A targeting REACH-compliant formulation portfolios and strategic partnerships bundling equipment with chemical supply.
Within the European manufacturing tier, Kersia Group and Lanxess AG exemplify archetypes built on captive chemistry and regulatory pre-validation. Kersia leverages its French production footprint to supply peracetic acid blends aligned with descending REACH substance restrictions. Lanxess anchors positioning through controlled bromine feedstock from Dead Sea and Arkansas brine operations. Among diversified hygiene service providers, Ecolab occupies a position integrating disinfectants with dosing equipment and audit infrastructure.
| Leading Market Players |
|---|
| Kersia Group |
| Lanxess AG |
| Ecolab |
| Evonik Industries AG |
| Zoetis Inc. |
| GEA Group |
| Neogen Corporation |
| Virbac SA |
| Ceva Santé Animale |
| Others |
Value Network & Pricing Analysis
EU Green Deal Farm to Fork mandates for biodegradable actives are forcing procurement officers toward peracetic acid and hydrogen peroxide systems, compelling suppliers to absorb reformulation costs and recalibrate pricing structures across livestock operations in Germany, France, and the Netherlands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant peracetic acid blends from legacy chlorine compounds and informal unregistered supplies. Price differentiation rests on ECHA registration status and bundled audit services rather than unit chemistry cost. Pricing pressure stems from Brazilian integrators consolidating volume through single-source hygiene contracts with performance guarantees. Dairy cooperatives in Minas Gerais exhibit highest price sensitivity; veterinary clinics in Bavaria and Île-de-France show lowest sensitivity due to accreditation documentation requirements.
Supply Chain Analysis
ANVISA import substitution pressures in Brazil and FSSAI formalization mandates in India are redirecting multinational sourcing toward domestic toll manufacturing partnerships. Captive bromine chemistry draws from Dead Sea and Arkansas brine operations, while peroxygen feedstock concentrates in German and Belgian chemical corridors. Single-source vulnerability sits with Dead Sea bromine access for phenolic disinfectant manufacturers. Distribution runs through veterinary pharmaceutical distributors in formalizing markets and direct service contracts in consolidated dairy regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary disinfectants market functions as a stable compounder anchored by recurring biosecurity protocol mandates across livestock operations, with regulatory compliance deepening customer switching costs and protecting incumbent revenue streams.
For Market Incumbents: Lock in captive active ingredient supply through backward integration into peroxygen chemistry or long-term bromine offtake agreements from Dead Sea operations. Secure REACH pre-validated multi-active portfolios to capture clinic consolidation in France and Germany as authorization sunset dates for quaternary ammonium precursors force substitution cycles. For New Entrants and Emerging Players: Veterinary pharmaceutical distributors in Maharashtra and Gujarat represent the most penetrable channel infrastructure for powder format entry under FSSAI sanitation mandates. Target budget-constrained animal shelters in Brazil and India with controlled dilution economics. Lead with equipment-chemical bundling to bypass entrenched liquid-format infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with European mid-cap formulators holding captive peracetic acid production and pre-submitted REACH substitution dossiers. Five-to-ten-year viability favors suppliers with backward-integrated active chemistry over merchant-dependent regional blenders. Monitor ECHA authorization sunset date announcements as inflection signals for portfolio acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peroxygen Chemistry | Captive hydrogen peroxide supply secures margin protection against merchant feedstock volatility. |
| REACH Pre-Validated Multi-Active Portfolio | ECHA-compliant formulation range captures clinic consolidation as substitution deadlines approach. |
| Integrated Hygiene Service Contract | Equipment-audit-chemical bundling locks in recurring revenue from Wisconsin and California dairy cooperatives. |
| Powder Format Manufacturing Scale-Up | Controlled dilution economics penetrate India's informal chemical supply channels under FSSAI mandates. |
| Electrolyzed Water Equipment Partnership | On-site generation technology absorbs Brazilian integrator capital investment seeking storage liability elimination. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary clinic procurement managers, livestock farm biosecurity officers, chemical distributor sales directors, and ECHA regulatory affairs specialists with secondary validation from customs trade data, SEC filings of listed chemical conglomerates, ANVISA veterinary product registrations, and FSSAI sanitation compliance records. Bottom-up volume builds across product type, application setting, and delivery format segments were cross-checked against top-down market envelope estimates.
Comparable-period anchoring linked historical consumption patterns across livestock density trends and regulatory implementation timelines to projection assumptions over the analysis window. Segmentation modeling captured formulation chemistry tier, farm versus clinical application, liquid versus powder versus foam delivery format, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend extrapolation adjusted for EU Green Deal mandate acceleration and Brazilian integrator contract consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization sunset date acceleration, Dead Sea bromine supply disruptions, and electrolyzed water technology substitution rates in Brazilian poultry operations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Lasers Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Animal Microchip Implant Market
Veterinary
Isoxazoline Market
Veterinary
Global Veterinary Drugs Market
Veterinary
CBD Pet Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
Veterinary Equipment and Supplies Market
Veterinary
Global Veterinary Care Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
OTC Cat Medicines Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Veterinary Healthcare Market
Veterinary
Japan Veterinary Healthcare Market
Veterinary
Animal Antibiotics Market