
 Pet Care Market | 2026-2036
Pet Care Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Care Market Analysis
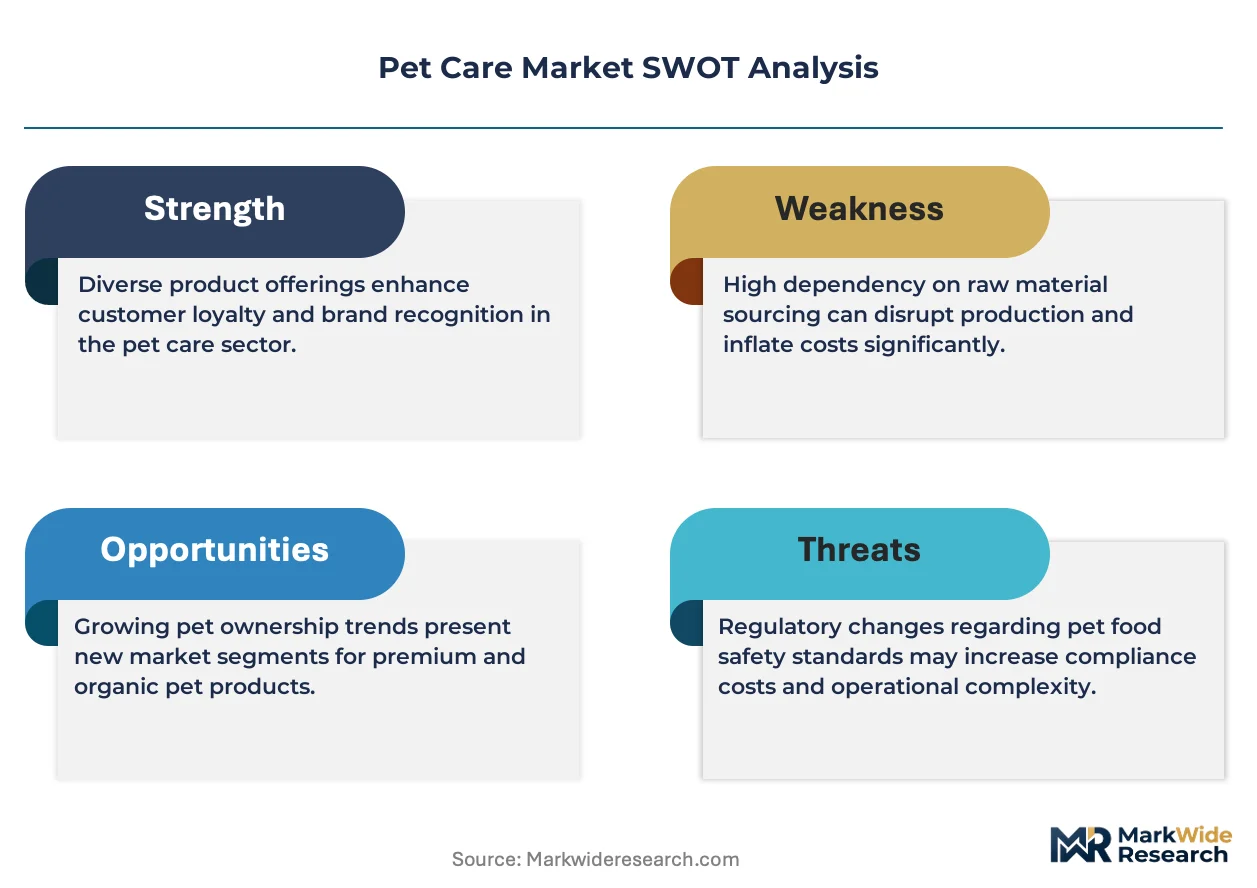
FDA enforcement of updated pet food safety standards is decoupling small private-label manufacturers from shelf space at major retailers. Mars Petcare leverages backward integration into veterinary nutrition science to sustain formulation leadership across prescription diets. Nestle Purina PetCare anchors North American volume through controlled distribution in veterinary clinics and specialty pet chains. Zoetis differentiates via its parallel animal health pharmaceutical portfolio, which creates cross-selling leverage into clinical nutrition channels.
Pet care encompasses the commercial ecosystem of nutrition, health maintenance, enrichment, and hygiene products manufactured for companion animals, with pet food formulations typically specifying guaranteed protein percentages, AAFCO nutrient profiles, and species-appropriate caloric density to ensure metabolic adequacy. The product type dimension shows food commanding the dominant margin pool due to repeat purchase frequency, while the animal type dimension reveals dogs generating the highest per-capita spending on premium formulations and preventive health services. Distribution channel structure tilts toward online platforms capturing subscription-driven replenishment, though veterinary clinics retain pricing power for therapeutic and prescription-tier nutrition.
USDA inspection protocols for meat-based pet food ingredients, FDA Center for Veterinary Medicine guidelines on additive safety, and state-level feed control official enforcement collectively elevate compliance costs for new entrants. The EU's REACH chemicals framework and FEDIAF nutritional guidelines impose parallel formulation constraints on European manufacturers seeking cross-border market access. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether centralized or region-specific product portfolios deliver superior returns.
Market Dynamics
Pet humanization is restructuring purchasing logic across the value chain, converting discretionary spending into non-discretionary household budget allocation and forcing manufacturers to reposition formulations as preventive health instruments rather than commodity feed.
Growth Catalysts
- Subscription replenishment models:Direct-to-consumer platforms lock in recurring revenue streams while capturing first-party data on consumption patterns and dietary transitions.
- FDA modernization of pet food safety standards:Enhanced traceability requirements accelerate consolidation toward manufacturers with integrated quality infrastructure.
- Veterinary nutrition science:Prescription-tier formulations command margin premiums through clinical validation and controlled distribution channels.
Market Restraints
- Protein input cost volatility:Meat and fish meal prices fluctuate with livestock commodity cycles, compressing gross margins for mid-tier producers without forward-contracting capabilities.
- Regulatory fragmentation:Divergent AAFCO, FEDIAF, and national feed control standards force portfolio duplication or exclusion from cross-border markets.
- Therapeutic diet substitution:Generic veterinary nutrition alternatives erode pricing power for originator formulations after patent exclusivity lapses.
Strategic Opportunities
- Senior pet nutrition formulations:Aging companion animal demographics create addressable white space for cognitive support and joint health functional ingredients.
- Cell-cultured protein integration:Novel meat alternatives bypass conventional agricultural supply constraints while appealing to sustainability-motivated owners.
- Veterinary clinic channel expansion:Therapeutic diet authorization through licensed practitioners insulates pricing from retail competitive pressure.
Industry Challenges
- Formulation scientist talent scarcity:Veterinary nutrition PhD recruitment lags behind pipeline expansion, delaying product development timelines.
- Legacy ERP integration complexity:Lot-level traceability mandates require expensive system overhauls for established manufacturers with siloed data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Care Market |
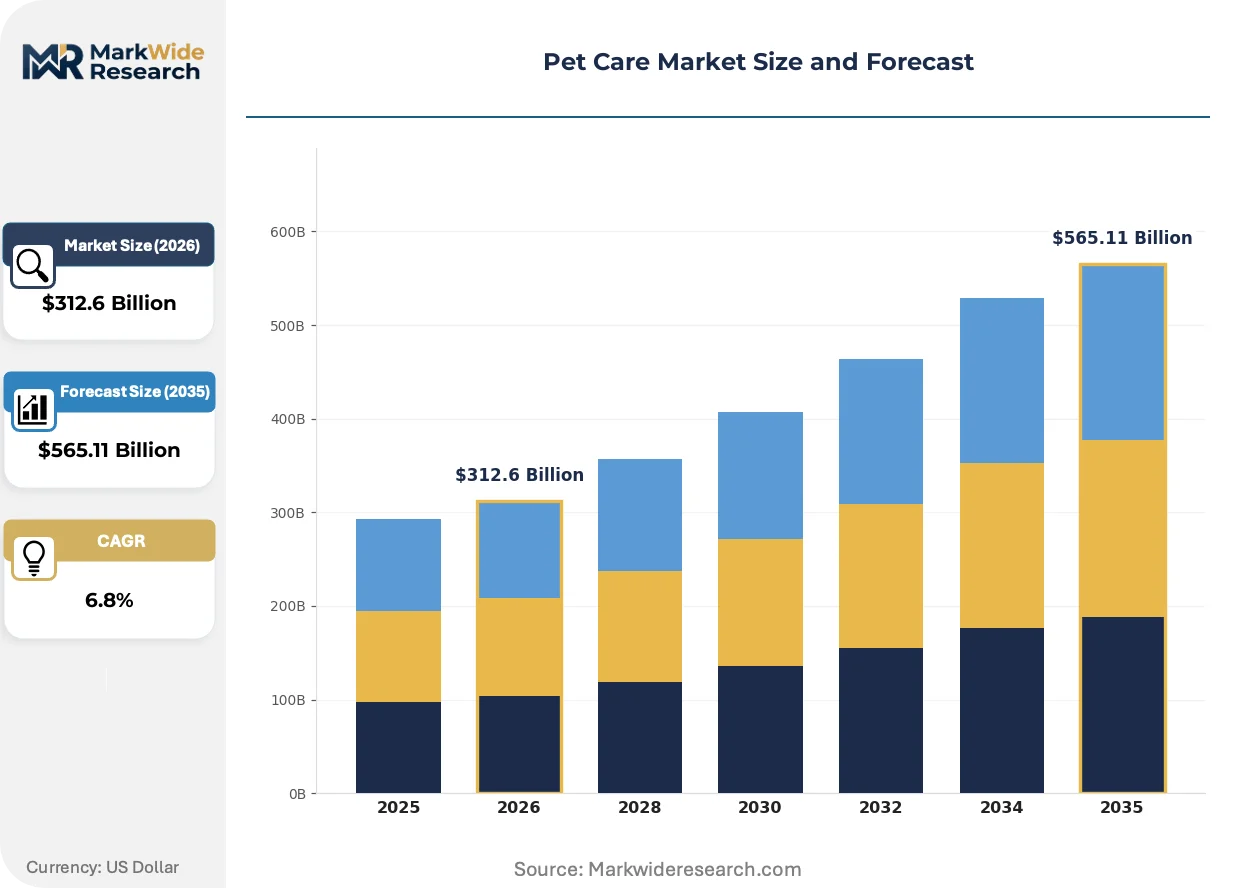
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Toys, Accessories, Grooming End User: Pet Owners, Veterinarians, Retailers, Shelters Distribution Channel: Online, Pet Shops, Supermarkets, Veterinary Clinics Animal Type: Dogs, Cats, Birds, Small Mammals |
| Companies Covered | Zoetis, General Mills, Mars Petcare, PawTree, LifeVantage, Nestle Purina PetCare, Chewy, Life Abundance, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Care Market Emerging Trajectories
Digital infrastructure and bioscience advances are converging to transform how nutrition is formulated, validated, and delivered to companion animals.
Precision microbiome testing is integrating into routine wellness protocols, enabling gut health diagnostics that match individual animals to customized probiotic and prebiotic supplementation protocols. Premium pet owners in urban United States markets are adopting these services at accelerating rates. The technology is integrating veterinary diagnostic laboratories with direct-to-consumer sample collection, collapsing the traditional clinic-mediated testing pathway.
REACH chemicals framework enforcement in Europe is restricting synthetic preservative options, forcing reformulation toward natural antioxidant alternatives. Manufacturers serving EU export markets must validate shelf-stability through accelerated aging studies using tocopherols and rosemary extract. Wet food and semi-moist categories face disproportionate technical burden given their higher water activity and spoilage risk profiles.
Subscription-based replenishment is compressing traditional retail purchase cycles, locking owners into automatic delivery schedules that reduce brand switching. Veterinary-exclusive and specialty e-commerce platforms capture this behavior shift most effectively. United States metropolitan markets exhibit the highest penetration of these models, with millennial and Generation Z households driving adoption velocity.
Pet Care Market Segmentation
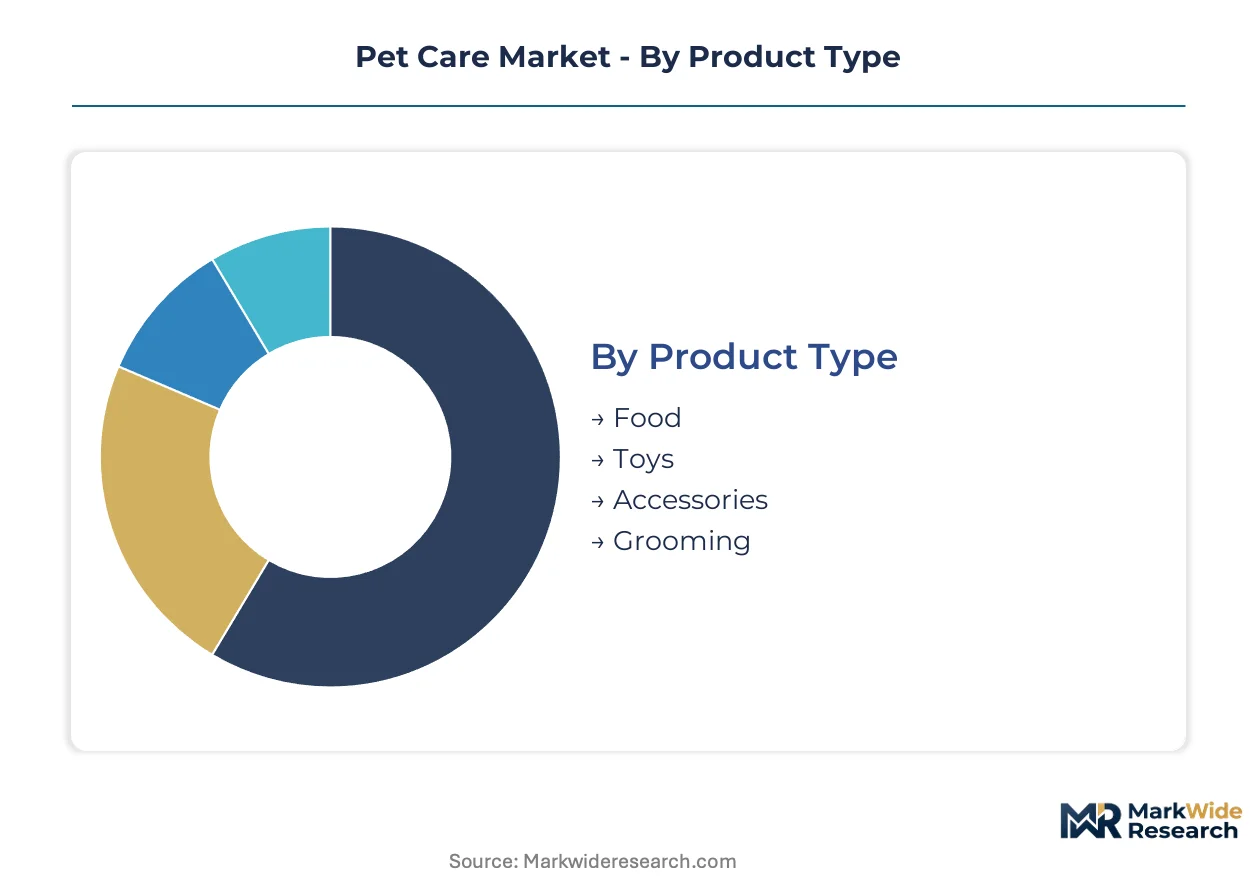
Pet care segmentation reveals how purchasing logic fragments across species-specific metabolic needs, professional versus consumer decision authority, and channel-controlled versus open-access distribution. Manufacturers must align formulation investment, margin architecture, and regulatory compliance to the distinct economics governing each segment intersection.
Product Type:
Margin capture differentiates fundamentally between consumable repeat purchases and durable discretionary spending.
- Food:Formulations specify guaranteed protein percentages, AAFCO nutrient profiles, and species-appropriate caloric density to ensure metabolic adequacy. United States millennial households concentrate demand for veterinary-grade nutrition with subscription replenishment locking in recurring revenue streams.
- Toys:Enrichment products span cognitive stimulation devices, chew-resistant materials, and interactive electronic systems. Urban pet owners in United States metropolitan markets drive premiumization as humanization converts discretionary toy spending into non-discretionary household budget allocation.
- Accessories:Collars, leashes, bedding, and travel carriers with functional specifications for safety certification and ergonomic design.
- Grooming:Shampoos, brushes, dental care, and coat maintenance tools requiring dermatological safety validation.
Volume sits with Food; growth tilts toward Toys.
End User:
Decision authority splits between emotional owner attachment and clinical professional judgment.
- Pet Owners:Emotional attachment drives premium formulation acceptance and preventive health expenditure conversion. FDA pet food safety standard enforcement elevates trust requirements for direct-to-consumer claims.
- Veterinarians:Prescription-tier nutrition authorization creates controlled distribution channels insulating pricing from retail competitive pressure. Clinical validation requirements concentrate purchasing power with manufacturers maintaining veterinary nutrition science capabilities.
- Retailers:Shelf space allocation favors suppliers with integrated quality infrastructure and lot-level traceability compliance.
- Shelters:Volume procurement prioritizes cost-efficient standard formulations meeting baseline nutritional adequacy.
Volume concentrates with Pet Owners; margin expansion tilts toward Veterinarians.
Distribution Channel:
Channel selection determines pricing power through access control and data capture depth.
- Online:Direct-to-consumer platforms capture subscription-driven replenishment with first-party consumption pattern data. United States metropolitan markets exhibit highest penetration as millennial and Generation Z households accelerate adoption velocity.
- Pet Shops:Specialty retail maintains curated assortment authority for premium and super-premium tier positioning.
- Supermarkets:Mass-market volume concentration demands packaging efficiency and trade promotion investment for shelf placement.
- Veterinary Clinics:Therapeutic diet authorization through licensed practitioners creates margin-protected segments with clinical validation requirements.
Volume flows through Online; value capture climbs fastest in Veterinary Clinics.
Animal Type:
Species-specific metabolic constraints dictate formulation complexity and per-capita spending ceilings.
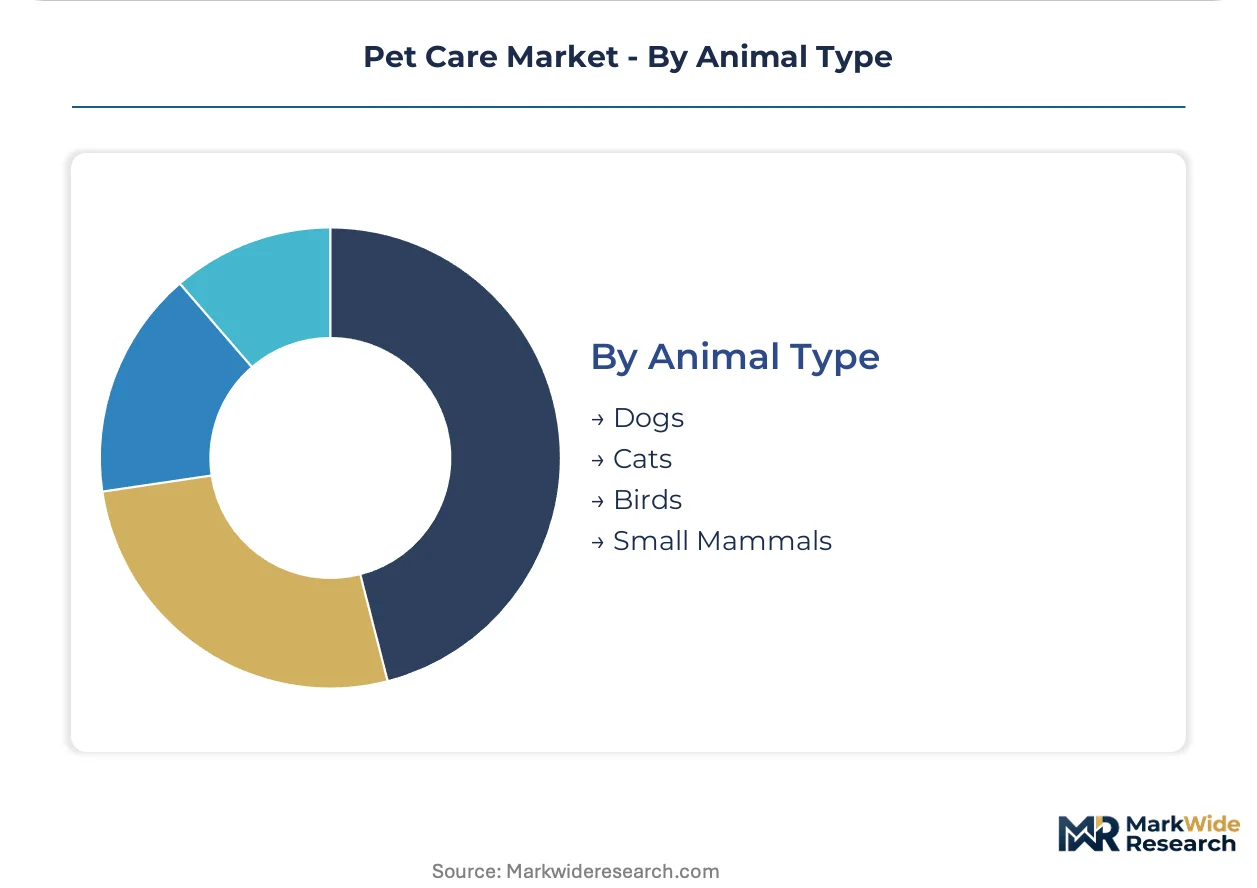
- Dogs:Largest body mass and longest lifespans generate highest per-capita spending on premium formulations and preventive health services. Aging companion animal demographics in United States markets create addressable white space for cognitive support and joint health functional ingredients.
- Cats:Obligate carnivore physiology demands precise amino acid profiling with taurine and arachidonic acid minimums. Urban household concentration drives wet food preference given higher water activity requirements.
- Birds:Species-specific seed, pellet, and nectar formulations with exacting vitamin A and calcium balance requirements.
- Small Mammals:Rabbits, guinea pigs, hamsters, and ferrets with fiber-centric digestive system adaptations demanding hay-based and extruded diet specialization.
Revenue concentrates with Dogs; formulation innovation accelerates fastest in Cats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and bonded logistics parks in the Netherlands concentrate pet food manufacturing and re-export activity. These zones attract multinational formulation facilities through customs duty exemptions and streamlined veterinary product registration pathways.
United States
Millennial household formation and pet humanization drive per-capita spending on subscription-based nutrition replenishment. FDA Center for Veterinary Medicine enforces updated pet food safety standards requiring lot-level traceability infrastructure. Kansas and Iowa host concentrated rendering and protein processing clusters supplying premium formulation facilities.
Germany
REACH chemicals framework enforcement restricts synthetic preservative options across wet food and semi-moist categories. EFSA nutritional guidelines and national feed control standards elevate compliance costs for cross-border market access. Bavaria anchors specialized veterinary nutrition research through integrated animal health science corridors.
China
Urban middle-class expansion and single-person household growth accelerate companion animal ownership rates. SAMR and NMPA coordinate on pet food ingredient safety registration and import inspection protocols. Yangtze River Delta manufacturing zones concentrate contract formulation capacity for export-oriented brands.
Brazil
Pet humanization trends convert discretionary spending into non-discretionary household budget allocation across São Paulo and Rio de Janeiro metro areas. ANVISA regulates veterinary product marketing authorization and therapeutic diet classification. Minas Gerais hosts integrated poultry and beef byproduct processing supplying regional formulation plants.
United Kingdom
Veterinary clinic channel expansion and prescription-tier nutrition authorization create margin-protected distribution segments. FEDIAF guidelines and post-BREXIT divergence from EU feed standards force portfolio duplication decisions. Greater London concentrates direct-to-consumer platform headquarters and specialty retail chain operations.
Pet Care Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven nutrition science capabilities clash with agile direct-to-consumer responsiveness. The vendor base stratifies into three archetypes: integrated consumer goods conglomerates with captive veterinary research infrastructure, subscription-native digital platforms with first-party data advantages, and pharmaceutical-animal health hybrids with cross-selling leverage into clinical channels. Consolidation pressure intensifies through FDA traceability mandates, while portfolio diversification into senior pet functional ingredients and cell-cultured protein alternatives accelerates competitive differentiation.
Within the integrated conglomerate tier, Mars Petcare and Nestle Purina PetCare exemplify backward integration into veterinary nutrition science and controlled distribution through veterinary clinics and specialty retail chains. Zoetis occupies a position bridging pharmaceutical development and clinical nutrition authorization. Chewy represents the digital-native archetype with subscription-driven replenishment infrastructure.
| Leading Market Players |
|---|
| Zoetis |
| General Mills |
| Mars Petcare |
| PawTree |
| LifeVantage |
| Nestle Purina PetCare |
| Chewy |
| Life Abundance |
| Hill's Pet Nutrition |
| Others |
Supply Flow & Price Mechanics
Chicago Mercantile Exchange live cattle futures volatility cascades through rendering and protein processing clusters in Kansas and Iowa, compressing gross margins for mid-tier pet food manufacturers lacking forward-contracting capabilities while amplifying pricing power for integrated conglomerates with captive supply chains.
Pricing Analysis
Short lead-time premiums for just-in-time veterinary clinic replenishment command margin advantages over spot inventory liquidation through mass retail channels. Three-tier pricing structure across prescription-tier, premium, and economy formulations separates clinical validation requirements from commodity feed positioning. Cost compression in mid-tier dry food is intensifying because generic veterinary nutrition alternatives erode originator pricing post-patent expiry. Shelter procurement represents highest price sensitivity; veterinary-exclusive therapeutic diets exhibit lowest.
Supply Chain Analysis
Regional distribution centers in the Netherlands and United Arab Emirates Free Trade Zones concentrate re-export activity through bonded logistics parks with streamlined veterinary product registration pathways. Protein input dependencies draw from Minas Gerais poultry processing, Yangtze River Delta contract manufacturing, and Iowa rendering clusters. Single-source vulnerability in AAFCO-compliant vitamin premix concentrates elevates disruption risk. Distribution runs through subscription-native direct-to-consumer platforms and veterinary clinic hub-and-spoke networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet care market consolidation accelerates as FDA lot-level traceability mandates force capital expenditure burdens that decouple small private-label manufacturers from major retailer shelf space.
For Market Incumbents: Anchor formulation leadership through backward integration into veterinary nutrition science research corridors in Bavaria and controlled distribution capture in veterinary clinics. Invest in captive quality infrastructure to meet evolving FDA Center for Veterinary Medicine safety standards. Cell-cultured protein R&D programs insulate against livestock commodity cycle volatility threatening mid-tier margin pools. For New Entrants and Emerging Players: Begin with senior pet cognitive support and joint health functional ingredients in United States metropolitan markets where aging companion animal demographics create addressable white space. Precision microbiome testing services offer lowest competitive density entry vector. Direct-to-consumer sample collection partnerships collapse traditional clinic-mediated pathways for millennial household acquisition. For Investors and Strategic Acquirers: Distressed-cycle entries favor subscription-native digital platforms with first-party data infrastructure in United States coastal metropolitan markets where millennial and Generation Z household penetration accelerates. Long-term viability hinges on recurring revenue lock-in rather than transactional retail volume. Monitor FDA enforcement intensity against small private-label manufacturers as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Nutrition Science Acquisition | Clinical validation capabilities unlock prescription-tier margin pools through controlled distribution channels. |
| Cell-Cultured Protein Integration | Novel meat alternatives bypass agricultural supply constraints while appealing to sustainability-motivated owners. |
| Subscription Platform Buildout | Automatic replenishment schedules reduce brand switching and capture consumption pattern data assets. |
| ERP Traceability Overhaul | Lot-level compliance infrastructure satisfies FDA modernization mandates and excludes undercapitalized competitors. |
| Senior Pet Formulation Pipeline | Cognitive support and joint health ingredients target aging companion animal demographics in United States markets. |
Methodological Framework
Independent corroboration across FDA Center for Veterinary Medicine enforcement records, AAFCO feed control official databases, and FEDIAF nutritional guideline submissions underwrites the qualitative findings. Primary interviews with veterinary nutrition PhDs, specialty retail category buyers, direct-to-consumer platform supply planners, and rendering facility procurement managers combined with secondary validation through customs trade data, SEC 10-K filings of diversified consumer goods conglomerates, and Nielsen retail audit information. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period historical reference anchored the projection horizon to observed subscription adoption velocity and regulatory enforcement phase-in patterns. Segmentation dimensions modeled include product type tier, animal species metabolic profile, decision authority split between owners and veterinarians, and channel control intensity. CAGRs derived from elasticity-adjusted consumption growth rates applied to protein input cost baselines and premiumization penetration curves.
Underlying measurement precision varies by segment; subscription-native direct-to-consumer data carries tighter precision than fragmented shelter procurement estimates. Forecasts reflect documented assumptions on FDA enforcement intensity, protein commodity cycle amplitude, and generational wealth transfer effects. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Pet Food Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Cannabidiol CBD Pet Market