
 US Camping and Caravanning Market | 2026-2036
US Camping and Caravanning Market Size, Share, and Industry Trends Forecast 2026-2036
US Camping and Caravanning Market Insights
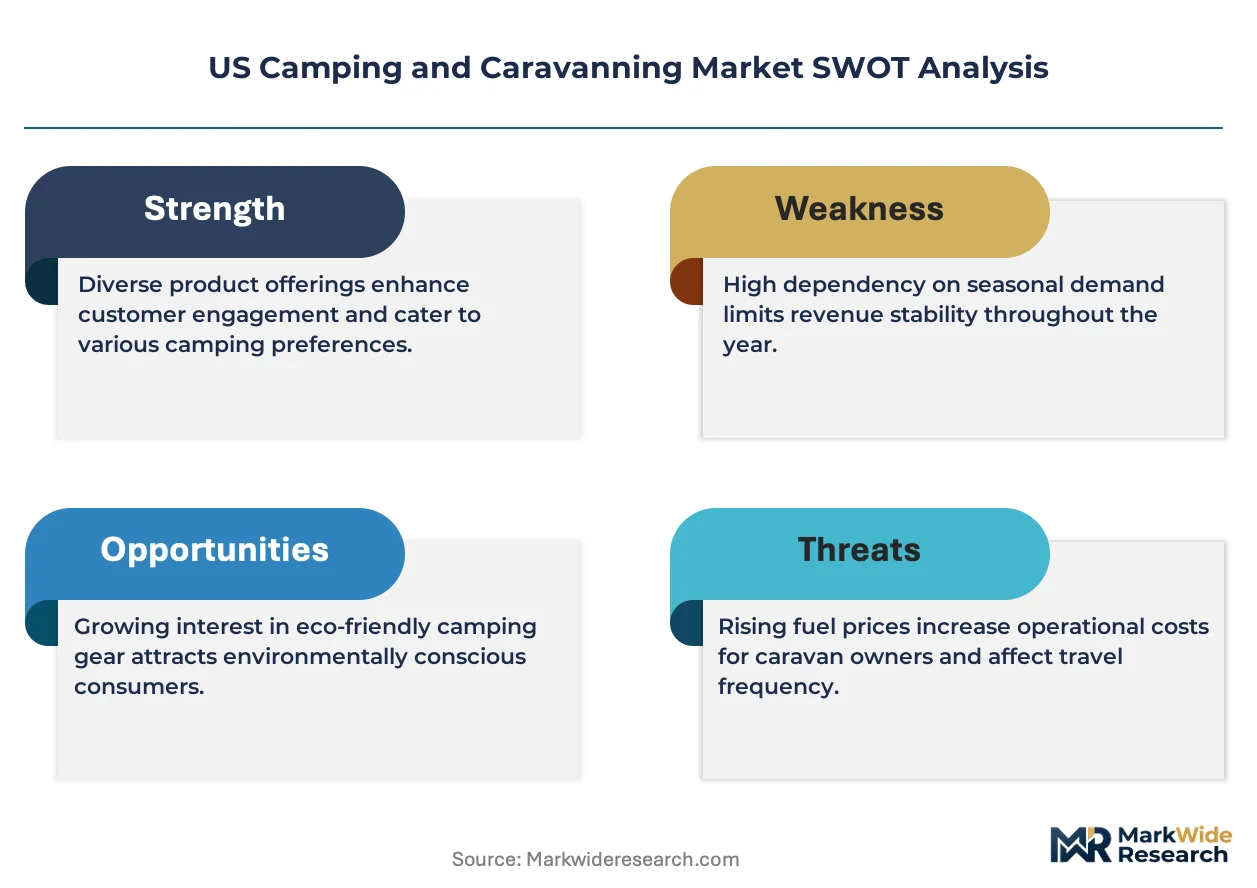
Subscription-based maintenance and roadside assistance is hardening into a core revenue layer for RV fleet operators and campground networks. Kampgrounds of America leverages its proprietary reservation platform to sustain recurring membership revenue across its franchise network. Thor Industries anchors its competitive position through manufacturing scale and vertical control over chassis supply. Hipcamp competes by extending private land access inventory beyond traditional public campground boundaries.
Camping and caravanning encompasses temporary outdoor accommodation through towable and motorized recreational vehicles, tent-based shelter systems, and associated equipment designed for mobility, weather resistance, and off-grid functionality, typically constructed with lightweight aluminum framing, composite sidewalls, and LP-gas or electrical power systems for habitation. The industry serves leisure travelers seeking flexible, self-contained lodging alternatives to hotels and vacation rentals. RVs command the dominant margin pool due to high unit values and financing attachment rates, while camping gear delivers volume velocity through online retail channels. Solo travelers represent the fastest-expanding customer type as remote work enables extended-duration trips outside traditional family vacation windows.
The National Highway Traffic Safety Administration governs RV safety standards and recall protocols, while the National Park Service manages access allocation through reservation systems and carrying-capacity limits that directly constrain peak-season inventory. State-level environmental compliance, particularly California Air Resources Board emissions rules for onboard generators, shapes product engineering requirements. Stakeholders must monitor evolving federal land-use policies and electrification infrastructure deployment timelines to align fleet composition and site development plans with emerging traveler expectations.
Market Dynamics
Peer-to-peer rental platforms and dispersed camping policy liberalization are fragmenting traditional campground gatekeeper roles, redistributing inventory control from established networks toward individual asset owners and federal land managers.
Growth Catalysts
- California Air Resources Board generator emissions standards:Tier 4 Final compliance mandates are accelerating propane-to-lithium powertrain conversions in Class B motorhomes, opening retrofit service revenue streams.
- Remote work normalization:Knowledge workers extending trips beyond traditional vacation windows are compressing shoulder-season occupancy gaps at Western Bureau of Land Management corridors.
- Millennial ownership preferences:Asset-light consumption patterns favor fractional RV access models over full acquisition, expanding addressable renter pools.
Market Restraints
- Chassis supply concentration:Ford E-Series and Mercedes-Benz Sprinter platforms dominate Class C and B van cutaway supply, creating single-source vulnerability for tier-two manufacturers.
- Lithium battery raw material volatility:Cobalt and nickel price swings compress margin predictability for off-grid power system integrators targeting boondocking segments.
- National Park Service reservation system capacity:Recreation.gov infrastructure constraints harden peak-season access scarcity, capping revenue velocity for destination-dependent operators.
Strategic Opportunities
- Inflation Reduction Act clean vehicle tax credits:Section 30D extension through 2032 subsidizes electric tow vehicle acquisition, reducing total cost of ownership for EV-compatible travel trailer buyers.
- Private land access expansion:Agricultural and timberland owners in Montana and Idaho are monetizing undeveloped acreage through platform-based booking, bypassing public campground infrastructure bottlenecks.
- Telematics-enabled predictive maintenance:IoT sensor integration with LP-gas and water systems allows fleet operators to unbundle roadside assistance into subscription tiers.
Industry Challenges
- RV technician certification gaps:National RV Training Academy throughput limits constrain service capacity expansion as unit volumes rise, extending repair backlogs.
- Multi-system integration complexity:Solar, lithium, and smart appliance convergence requires electrical engineering competencies legacy dealership networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Camping and Caravanning Market |
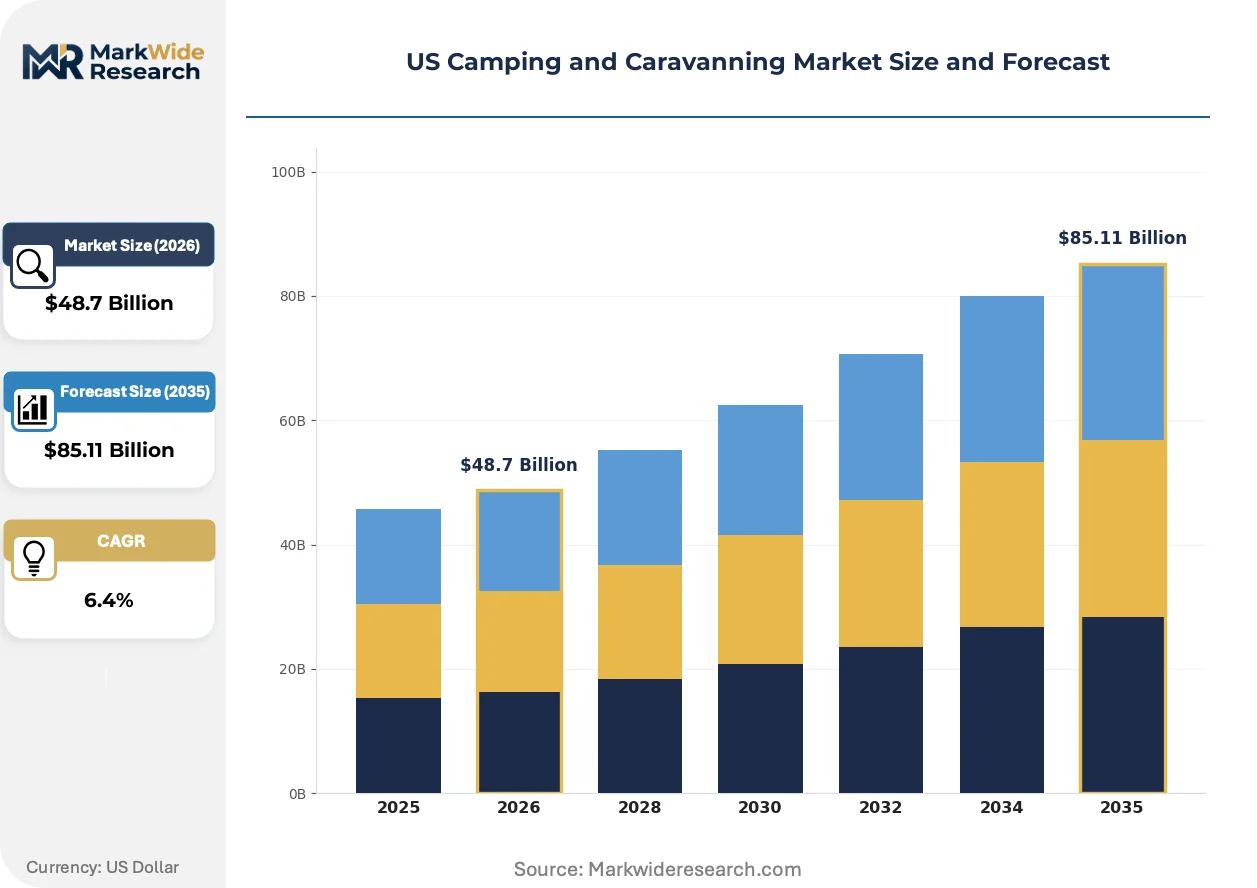
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, RVs, Camping Gear, Caravans Customer Type: Families, Solo Travelers, Outdoor Enthusiasts, Retirees Distribution Channel: Online Retail, Outdoor Stores, Specialty Shops, Direct Sales Seasonality: Summer, Spring, Fall, Holiday Season |
| Companies Covered | Kampgrounds of America (KOA), RVshare, Winnebago Industries, Thor Industries, Hipcamp, Cruise America, El Monte RV, Forest River, Camping World Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Camping and Caravanning Market Trends and Innovations
Electrification of powertrains and habitation systems is compressing the technical boundary between recreational vehicles and residential microgrids, while federal land access policy and remote work permanence reshape trip duration economics.
Lithium iron phosphate battery systems with integrated inverter-chargers are electrifying off-grid functionality for towable and motorized segments. Full-time remote workers and extended-stay travelers are adopting 400Ah+ configurations at accelerating rates. This technology is electrifying competitive differentiation, forcing traditional LP-gas appliance manufacturers toward hybrid-electric product lines or obsolescence.
The National Park Service's phased Recreation.gov modernization and dynamic pricing pilots are reallocating peak-season access toward revenue-maximizing algorithms. Carrying-capacity management now incorporates real-time congestion metrics rather than static lot counts. Western national park corridors and Appalachian gateway communities are responding with distributed camping alternatives on adjacent Bureau of Land Management and National Forest territories.
Solo travelers and remote-employed couples are compressing traditional family vacation booking windows into multi-week and month-long reservations. Kampgrounds of America and independent RV parks are displacing nightly-rate structures with weekly and monthly tiered pricing. This pattern concentrates most visibly in Arizona and Florida snowbird corridors, where seasonal occupancy now extends from four to eight months annually.
US Camping and Caravanning Market Segmentation
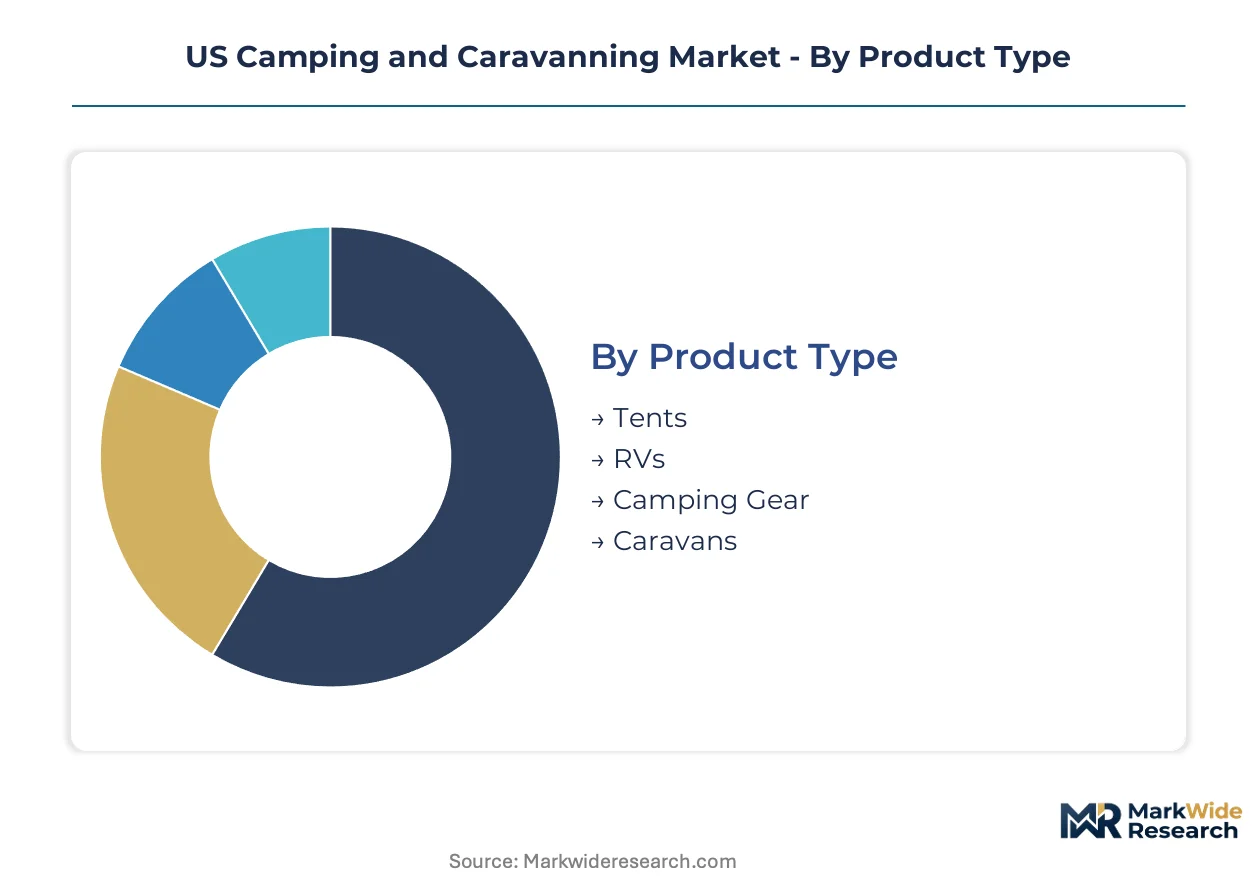
Segmentation in the US camping and caravanning market reveals divergent margin profiles and inventory velocity patterns across product categories and customer cohorts. RVs command financing attachment and service revenue streams, while gear and tent segments drive volume through digital channels. Understanding these structural differences enables operators to align capital deployment with expected return profiles.
Product Type:
Buyers select product categories based on trip duration intent, capital availability, and storage constraints rather than incremental feature comparisons.
- RVs:Motorized and towable recreational vehicles integrate LP-gas, electrical, and water systems for extended habitation. Demand concentrates in Western Bureau of Land Management corridors where dispersed camping policies accommodate self-contained units. Remote workers extending trips beyond traditional vacation windows compress shoulder-season occupancy gaps, sustaining annual utilization rates.
- Tents:Portable shelter systems constructed with lightweight aluminum framing and weather-resistant fabrics serve short-duration trips and entry-level outdoor participation. Demand clusters in Appalachian gateway communities and Pacific Northwest national forest territories where drive-up tent pads remain accessible. Solo travelers and weekend excursionists drive replacement cycles as waterproofing technologies advance.
- Camping Gear:Cooking systems, lighting, and portable power accessories deliver margin through online retail velocity. REI and direct-to-consumer brands capture recurring purchases from equipment upgraders.
- Caravans:European-style towable units with compact footprints suit retirees and seasonal migrants in Arizona and Florida snowbird corridors. Smaller dealer networks and import logistics constrain penetration versus domestic RV alternatives.
RVs lead on scale; camping gear leads on momentum.
Customer Type:
Demographic composition shifts as remote work permanence enables trip scheduling outside traditional family vacation windows.
- Families:Multi-generational units with school-calendar constraints concentrate demand in summer peak seasons. Kampgrounds of America and established national park corridors capture this cohort through reservation system access and amenity infrastructure.
- Solo Travelers:Individual participants represent the fastest-expanding customer type as distributed work arrangements permit extended-duration trips. Demand concentrates in Western dispersed camping territories and private land access platforms like Hipcamp that bypass Recreation.gov capacity constraints.
- Outdoor Enthusiasts:Activity-specialized campers pursuing climbing, fishing, or hunting access prioritize proximity to trailheads and water access over developed amenities. Bureau of Land Management territories in Montana and Idaho capture this segment through primitive road networks.
- Retirees:Seasonal migrants with flexible timing extend occupancy windows from four to eight months in Sun Belt corridors. Monthly rate structures displace nightly pricing at RV parks in Arizona and Florida.
Families anchor revenue concentration; solo travelers drive expansion velocity.
Distribution Channel:
Channel selection reflects purchase urgency, technical support requirements, and financing integration needs.
- Online Retail:Digital platforms capture camping gear and accessory volume through search-optimized discovery and subscription replenishment models. Amazon and REI.com dominate lightweight equipment transactions where physical inspection adds limited value.
- Outdoor Stores:REI, Bass Pro Shops, and regional chains serve as experiential showrooms where tactile evaluation drives tent and sleeping system purchases. Staff expertise and seasonal clinics sustain traffic against digital alternatives.
- Specialty Shops:Independent RV dealers and overland outfitters provide technical consultation, financing origination, and service bay access. These operators concentrate in Western states where unit density supports aftermarket revenue pools.
- Direct Sales:Manufacturer-owned showrooms and peer-to-peer rental platforms like Outdoorsy displace traditional dealer intermediaries. Thor Industries and smaller van conversion specialists deploy this channel to capture margin and customer relationship data.
Online retail leads on transaction velocity; specialty shops lead on unit margin capture.
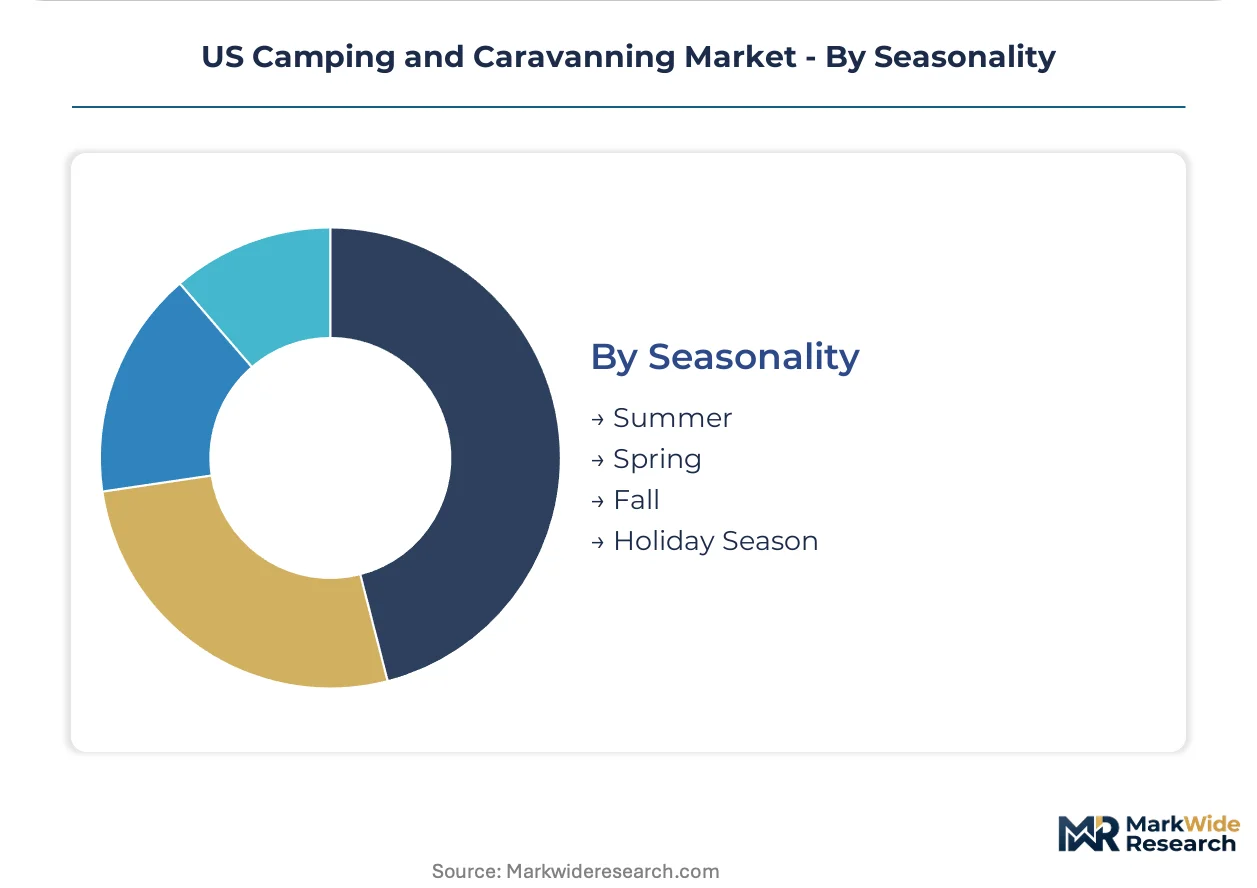
Seasonality:
Trip timing concentrates around school calendars, temperature patterns, and federal holiday scheduling.
- Summer:Peak demand months drive maximum occupancy and rate premiums at destination campgrounds. National Park Service carrying-capacity limits and Recreation.gov infrastructure constraints harden access scarcity.
- Spring:Shoulder-season recovery from winter closures concentrates in desert Southwest corridors and lower-elevation Appalachian access points. Wildflower and wildlife viewing windows drive regional demand spikes.
- Fall:Foliage tourism and hunting access sustain occupancy in New England and Rocky Mountain corridors. Temperature moderation extends camping windows before winter closures.
- Holiday Season:Compressed vacation windows around Thanksgiving, Christmas, and New Year concentrate in southern-tier states and developed campgrounds with winterized infrastructure. Florida and Texas destinations capture this residual demand.
Summer leads on absolute volume; spring leads on expansion trajectory as shoulder-season programming matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates camping and caravanning demand through dispersed public land access, while Canada relies on provincial park networks with tighter reservation constraints. Mexico's emerging RV corridor along Baja California attracts snowbird migration from colder climates. The analysis examines sub-regional concentration patterns across five American states and territories where inventory, policy, and traveler behavior intersect.
Western States
Bureau of Land Management territories in Utah, Nevada, and Arizona sustain dispersed camping demand through 14-day stay allowances on undeveloped acreage. California Air Resources Board generator emissions standards accelerate lithium powertrain adoption in Class B motorhomes traversing these corridors. Phoenix and Tucson RV parks compress shoulder-season gaps through monthly rate structures targeting remote workers.
Florida
Snowbird migration extends seasonal occupancy from four to eight months across the Gulf and Atlantic coasts, displacing nightly pricing with extended-stay tiers. The state's environmental regulators enforce coastal wetland setbacks that constrain new campground development in the Keys. Fort Myers and Sarasota anchor the highest density of age-restricted RV resorts serving retiree cohorts.
Texas
Hill Country and Gulf Coast corridors capture spring and fall demand windows between temperature extremes. State park reservation systems operated by Texas Parks and Wildlife Department limit peak-season access through lottery allocations. Austin and San Antonio metro areas concentrate peer-to-peer rental fleet bases serving festival and event tourism.
Pacific Northwest
National Forest campgrounds in Oregon and Washington face carrying-capacity constraints as remote workers extend stays beyond traditional vacation windows. The region's precipitation patterns compress the reliable camping season, intensifying demand concentration in July through September. Portland and Seattle serve as equipment retail hubs for tent and overland segments.
Appalachian Corridor
Gateway communities in Tennessee and North Carolina capture foliage and hiking-access demand through private campground networks adjacent to Great Smoky Mountains National Park. Recreation.gov infrastructure limitations at NPS facilities push overflow toward National Forest and commercial alternatives. Gatlinburg and Pigeon Forge anchor the highest concentration of amenity-heavy RV parks in the eastern United States.
US Camping and Caravanning Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated RV builders commanding financing attachment and service revenue pools while platform-based rental intermediaries capture recurring transaction fees. The market structures around three archetypes: manufacturing conglomerates with chassis supply control, franchise campground networks with proprietary reservation systems, and peer-to-peer rental platforms extending private land access. Consolidation pressure concentrates among tier-two manufacturers vulnerable to single-source chassis dependencies. Competitive moves center on fleet telematics integration and subscription-based maintenance unbundling.
Among manufacturing conglomerates, Thor Industries and Winnebago Industries occupy positions defined by scale and vertical control over supply chains. Kampgrounds of America anchors the franchise network tier through membership-based recurring revenue. Peer-to-peer platforms include RVshare and Hipcamp, which exemplify asset-light inventory models that bypass traditional campground infrastructure constraints. Cruise America and El Monte RV represent the rental fleet operator archetype with direct-to-consumer channel control. Forest River and Camping World Holdings sit within dealer and specialty retail channels where technical service integration determines customer retention.
| Leading Market Players |
|---|
| Kampgrounds of America (KOA) |
| RVshare |
| Winnebago Industries |
| Thor Industries |
| Hipcamp |
| Cruise America |
| El Monte RV |
| Forest River |
| Camping World Holdings |
| Others |
Pricing and Supply Chain Analysis
California Air Resources Board Tier 4 Final generator emissions standards gate qualified supply for lithium powertrain retrofits while anchoring premium-tier pricing for compliant Class B motorhomes. Manufacturers absorbing battery system integration costs pass selective premiums to remote-worker buyers seeking extended boondocking capability, compressing margin capture for non-compliant inventory.
Pricing Analysis
Capacity additions in Arizona and Florida RV park corridors are reshaping price floors for extended-stay tiers as monthly rate structures displace nightly pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates sites by shore power amperage and fiber internet access. Cost compression in entry-level tent-pad segments intensifies because platform-based private land access bypasses infrastructure overhead. Solo remote workers exhibit lowest price sensitivity; weekend family excursionists drive volume at rate-elastic price points.
Supply Chain Analysis
Domestic-content mandates for chassis assembly reshape sourcing patterns as Ford E-Series and Mercedes-Benz Sprinter platforms anchor Class B and C motorhome production. Manufacturing draws from Indiana assembly corridors, Mexican component feedstock, and Chinese lithium cell imports. Chassis supply concentration creates single-source vulnerability for tier-two builders lacking Ford fleet allocation priority. Distribution runs through independent dealer networks with service bay integration, though direct-to-consumer van conversion specialists capture margin and customer data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where dispersed camping access on Bureau of Land Management territories in Utah and Nevada offsets premium coastal campground rates, capturing remote-worker demand migration.
For Market Incumbents: Deploy telematics-enabled predictive maintenance subscriptions to unbundle roadside assistance into recurring revenue tiers. Kampgrounds of America should extend proprietary reservation platform licensing to independent parks, defending against Hipcamp's private land access fragmentation. Thor Industries must secure captive lithium battery supply agreements as cobalt and nickel volatility threatens margin predictability. For New Entrants and Emerging Players: Inflation Reduction Act Section 30D clean vehicle tax credits in the United States open a window for EV-compatible travel trailer specialists targeting California and Washington state buyers. White-space concentrates in overland van conversion for solo remote workers seeking dispersed camping capability. Agricultural land access partnerships in Montana and Idaho offer platform-based booking entry with minimal infrastructure capital. For Investors and Strategic Acquirers: Roll-up economics work for regional RV park networks because fragmented independent operators lack reservation system integration and telematics service capability. Target mid-scale portfolios in Arizona and Florida snowbird corridors with seasonal occupancy extension potential. Watch National Park Service Recreation.gov capacity expansion announcements as inflection indicators for destination-dependent operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium Powertrain Retrofit Service Launch | California Air Resources Board compliance mandates create captive upgrade demand from existing propane-fleet owners. |
| Private Land Access Platform Expansion | Agricultural and timberland partnerships in Montana bypass Recreation.gov infrastructure bottlenecks. |
| Telematics Subscription Tier Unbundling | IoT sensor integration with LP-gas systems enables predictive maintenance recurring revenue capture. |
| EV-Compatible Travel Trailer Development | Inflation Reduction Act subsidies reduce total cost of ownership for electric tow vehicle buyers. |
| Extended-Stay Rate Structure Implementation | Remote-worker demand compression in Arizona and Florida sustains eight-month seasonal occupancy. |
Research Methodology
Bottom-up remote-worker demand modeling reconciled against top-down RV production tracking forms the analytical core. Primary interviews with fleet operations directors, campground franchise development officers, lithium system integrators, and Bureau of Land Management permit administrators combined with secondary validation from NHTSA recall databases, Recreation.gov reservation statistics, SEC manufacturer filings, and EIA regional electricity demand profiles. Triangulation across these sources anchors volume estimates.
Input-output matrices segment the market by product type, customer cohort, distribution channel, and seasonality across the analysis window. CAGRs derive from installed base turnover rates, remote-worker population migration patterns, and electrification adoption curves. Forecast inputs incorporate National Park Service carrying-capacity policy trajectories and lithium battery cost decline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under federal land-use policy reversals or chassis supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aircraft Exterior Lighting Market
Others
Edible Insects for Animal Feed Market
Others
Global Duty-Free Retailing Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Coriolis Meters Market
Others
Prunes Market
Others
Education and Learning Analytics Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Inorganic Tin Chemicals Market
Others
Manometers Market
Others
Duty Free Retail Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
North America Astrology Market
Others
Rotary Dial Machine Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
South Korea Intellectual Property Market