
 Induced Pluripotent Stem Cells (Ipscs) Market | 2026-2036
Induced Pluripotent Stem Cells (Ipscs) Market Size, Share, and Industry Trends Forecast 2026-2036
Induced Pluripotent Stem Cells (Ipscs) Market Foresight
Project finance and milestone-based venture structures is fragmenting competitive access in the iPSC space, allowing specialized biotech firms to challenge incumbent platform providers without full capital commitment. Fate Therapeutics leverages its proprietary iPSC-derived cell therapy platform to anchor clinical-stage pipelines across oncology and immunology. Lonza dominates contract manufacturing and development services, extending its reach through dedicated cell-and-gene therapy production networks. Thermo Fisher Scientific controls upstream reagent and instrumentation supply, competing on integrated workflow solutions that reduce customer switching costs.
Induced pluripotent stem cells are somatic cells reprogrammed to a pluripotent state through defined transcription factor expression, typically achieved via Sendai virus, episomal plasmid, or mRNA-based delivery systems yielding cells capable of differentiating into any germ layer lineage. Their primary commercial purpose centers on producing patient-matched or allogeneic cell therapies, disease models for drug screening, and toxicology platforms that reduce animal dependency. Cell lines and reagents together capture the dominant share of product-type revenue, though culture systems command premium pricing where serum-free, chemically defined formulations reduce batch variability. Drug discovery applications lead current volume adoption, while regenerative medicine represents the fastest-growing segment as GMP-compatible iPSC banks enable scalable allogeneic therapies.
The FDA's regenerative medicine advanced therapy designation and evolving premarket guidance shape U.S. clinical trial economics and commercial timelines, while the EMA and national EU competent authorities enforce varying GMP standards for cell-based medicinal products that fragment market access requirements. Japan's PMDA operates under pioneering regenerative medicine legislation that compresses conditional approval pathways, creating regulatory arbitrage that attracts international trial sponsors. Stakeholders must monitor divergence between FDA, EMA, and PMDA post-market surveillance obligations, as differing long-term follow-up requirements will determine which geographies support profitable scalable manufacturing.
Market Dynamics
The transition from research-grade to GMP-compatible iPSC manufacturing is compressing vendor margins while elevating technical barriers, forcing contract manufacturers to absorb validation costs ahead of commercial therapy approvals.
Growth Catalysts
- Japan's regenerative medicine framework:The PMDA's conditional approval pathway accelerates clinical translation timelines, attracting international sponsors to establish manufacturing presence in Kobe and Osaka.
- Allogeneic cell therapy pipelines:Pharmaceutical developers are scaling GMP master cell bank creation to enable off-the-shelf immunotherapies, driving demand for qualified starting materials.
- Chemically defined culture media:Serum-free formulations reduce batch variability and simplify regulatory submissions, displacing fetal bovine serum-dependent workflows in toxicology screening.
Market Restraints
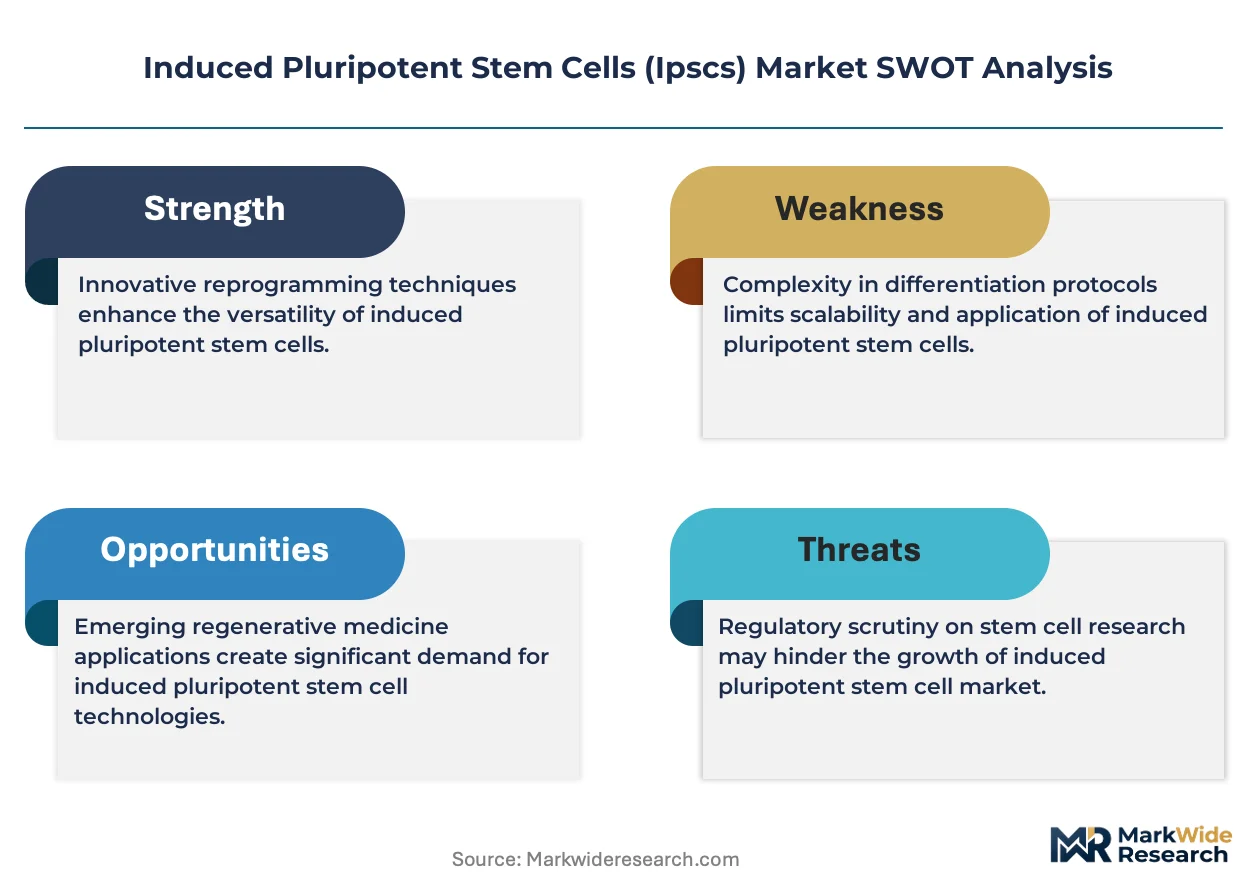
- Reagent supply concentration:Critical growth factors and cytokines source predominantly from a limited base of specialized suppliers, exposing developers to allocation risk during demand surges.
- GMP facility capex intensity:Cleanroom infrastructure and environmental monitoring systems require capital deployment that excludes mid-tier academic centers from commercial-scale production.
- Retroviral reprogramming legacy:Persistent concerns over genomic integration limit regulatory acceptance of certain iPSC lines, fragmenting bank qualification standards across jurisdictions.
Strategic Opportunities
- India's CDSCO pathway evolution:Draft cell therapy guidelines signal eventual alignment with ICH standards, positioning the country for contract research organization expansion.
- Organoid disease modeling:Patient-derived iPSC organoids enable mechanism-of-action studies that reduce animal use, opening toxicology service contracts with cosmetic and chemical sectors.
- Automated cell handling platforms:Closed-system bioreactors and machine vision-based quality assessment converge to reduce manual intervention error rates in high-volume manufacturing.
Industry Challenges
- Cell therapy manufacturing talent scarcity:GMP-grade iPSC expansion, differentiation, and cryopreservation require specialized skill sets that outpace current training program output.
- Post-approval pharmacovigilance burden:Long-term follow-up obligations for regenerative medicine products strain commercial infrastructure, particularly where conditional approvals mandate extended patient monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induced Pluripotent Stem Cells (Ipscs) Market |
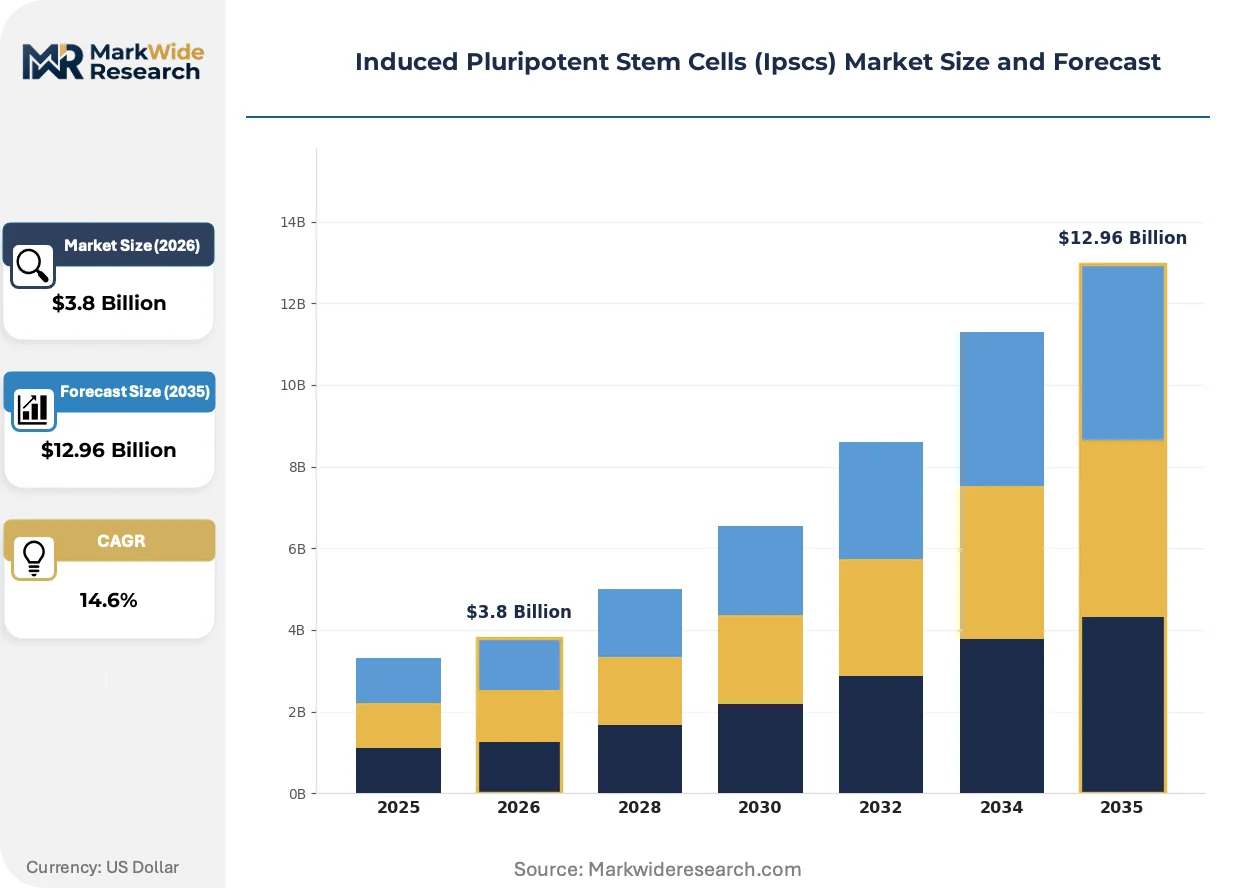
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Lines, Reagents, Culture Systems, Assay Kits Application: Regenerative Medicine, Drug Discovery, Disease Modeling, Toxicology Testing End User: Biotechnology Companies, Academic Institutions, Research Laboratories, Pharmaceutical Companies Technology: Gene Editing, Cell Reprogramming, Cloning, Cell Culture |
| Companies Covered | FUJIFILM Cellular Dynamics, Fate Therapeutics, Thermo Fisher Scientific, Lonza, REPROCELL, Ncardia, Axol Bioscience, Evotec, Cynata Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induced Pluripotent Stem Cells (Ipscs) Market Shifts & Advancements
Non-viral reprogramming modalities and closed-system manufacturing architectures are converging to reshape competitive requirements, elevating process robustness over research-grade flexibility as the decisive purchasing criterion.
mRNA-based reprogramming is rendering obsolete Sendai virus and episomal plasmid methods that dominate legacy iPSC generation. Large-molecule biopharma developers are adopting mRNA workflows for master cell bank creation to eliminate residual vector clearance validation. This shift is compressing the timeline from skin biopsy to qualified pluripotent line from months to weeks.
The FDA's regenerative medicine advanced therapy designation is compressing premarket review cycles for iPSC-derived products meeting serious unmet medical need criteria. Developers receiving this status gain rolling review and priority access to agency scientific advice, accelerating investment in U.S.-based manufacturing infrastructure. Oncology immunotherapy sponsors are disproportionately represented in current RMAT grants.
Academic medical centers are consolidating iPSC generation and characterization through centralized core facilities, displacing dispersed principal-investigator laboratory production. This concentration shifts procurement authority from individual researchers to institutional procurement offices with enterprise pricing leverage. The pattern is most visible in U.S. research-intensive universities where shared resource models achieve GMP-adjacent quality standards.
Induced Pluripotent Stem Cells (Ipscs) Market Segmentation
iPSC procurement patterns diverge sharply across user types, with pharmaceutical developers prioritizing GMP-compatible supply chains while academic buyers optimize for research-grade flexibility. Segment-specific technical requirements determine vendor selection criteria, contract terms, and pricing power distribution.
Product Type:
After-sales technical support intensity varies dramatically across product categories, with culture systems demanding sustained field service engagement while reagents operate on transactional replenishment models.
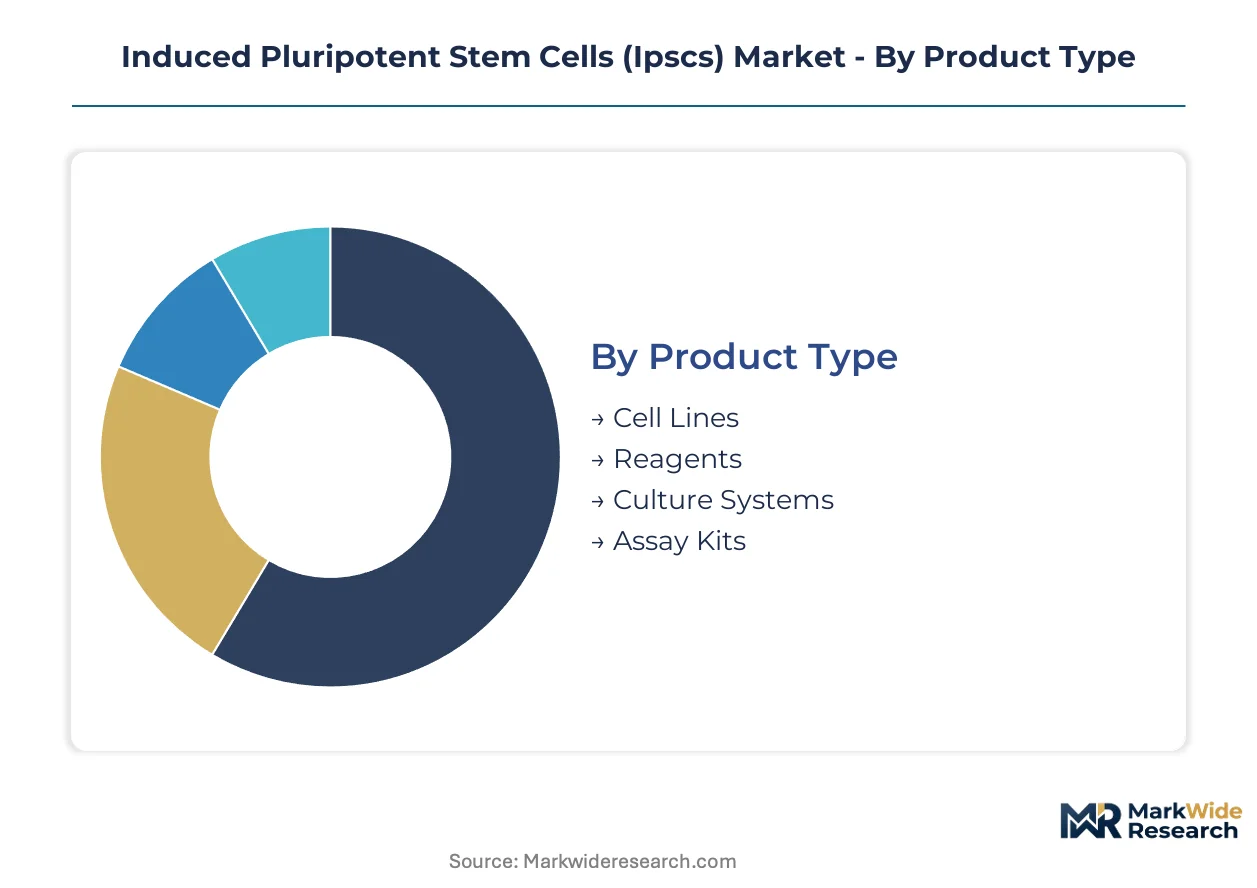
- Cell Lines:Qualified master cell banks and working cell banks serve as the biological starting material for all downstream therapeutic applications. Pharmaceutical companies in Japan and the United States are consolidating procurement through qualified GMP banks to streamline IND-enabling studies and reduce lot-to-lot variability.
- Reagents:Growth factors, cytokines, and reprogramming cocktails constitute the highest-volume consumable category with recurring purchase patterns. Academic core facilities in the United States and Germany are driving demand for chemically defined, serum-free formulations that simplify regulatory documentation.
- Culture Systems:Bioreactors, incubation platforms, and environmental control systems require capital deployment and integration support.
- Assay Kits:Pluripotency confirmation and differentiation monitoring tools enable quality control workflows.
Cell Lines and Reagents together hold the largest share; momentum sits with Culture Systems as GMP manufacturing scales.
Application:
Cost tier stratification separates high-investment therapeutic development from lower-commitment screening workflows, with regenerative medicine commanding premium pricing and extended contract durations.
- Regenerative Medicine:Allogeneic and autologous cell therapies derived from iPSC platforms address oncology, cardiovascular, and ophthalmic indications. The PMDA's conditional approval framework in Japan is accelerating clinical translation timelines for international sponsors establishing manufacturing presence in Kobe and Osaka.
- Drug Discovery:High-throughput screening platforms leverage iPSC-derived cardiomyocytes, hepatocytes, and neurons to predict compound efficacy and safety. Biotechnology companies in the United States are displacing animal models with patient-derived cell panels that capture genetic diversity.
- Disease Modeling:Patient-specific iPSC lines recapitulate pathological mechanisms for rare disease research.
- Toxicology Testing:Regulatory-compliant safety assessment platforms reduce pharmaceutical attrition rates.
Drug Discovery holds the largest share; Regenerative Medicine is climbing the fastest as GMP infrastructure matures.
End User:
Customer type determines procurement authority concentration, with pharmaceutical companies consolidating vendor relationships while academic institutions fragment purchasing across principal investigators.
- Biotechnology Companies:Venture-funded developers prioritize platform flexibility and rapid scale-up capabilities for IND-enabling studies. Cell therapy specialists in the United States are securing dedicated manufacturing slots with Lonza and other contract manufacturers to de-risk supply constraints.
- Pharmaceutical Companies:Large-molecule developers are building captive iPSC capabilities or exclusive partnerships for master cell bank creation. Internal GMP facilities at Merck KGaA, Roche, and Takeda are expanding in Germany, Switzerland, and Japan respectively.
- Academic Institutions:Shared resource core facilities are displacing dispersed laboratory production.
- Research Laboratories:Government and nonprofit research centers maintain diverse supplier relationships.
Pharmaceutical Companies hold the largest share; Biotechnology Companies are expanding most quickly as platform specialization deepens.
Technology:
Technology maturity curves separate established methods from emerging modalities, with cell reprogramming approaching commoditization while gene editing commands premium licensing structures.
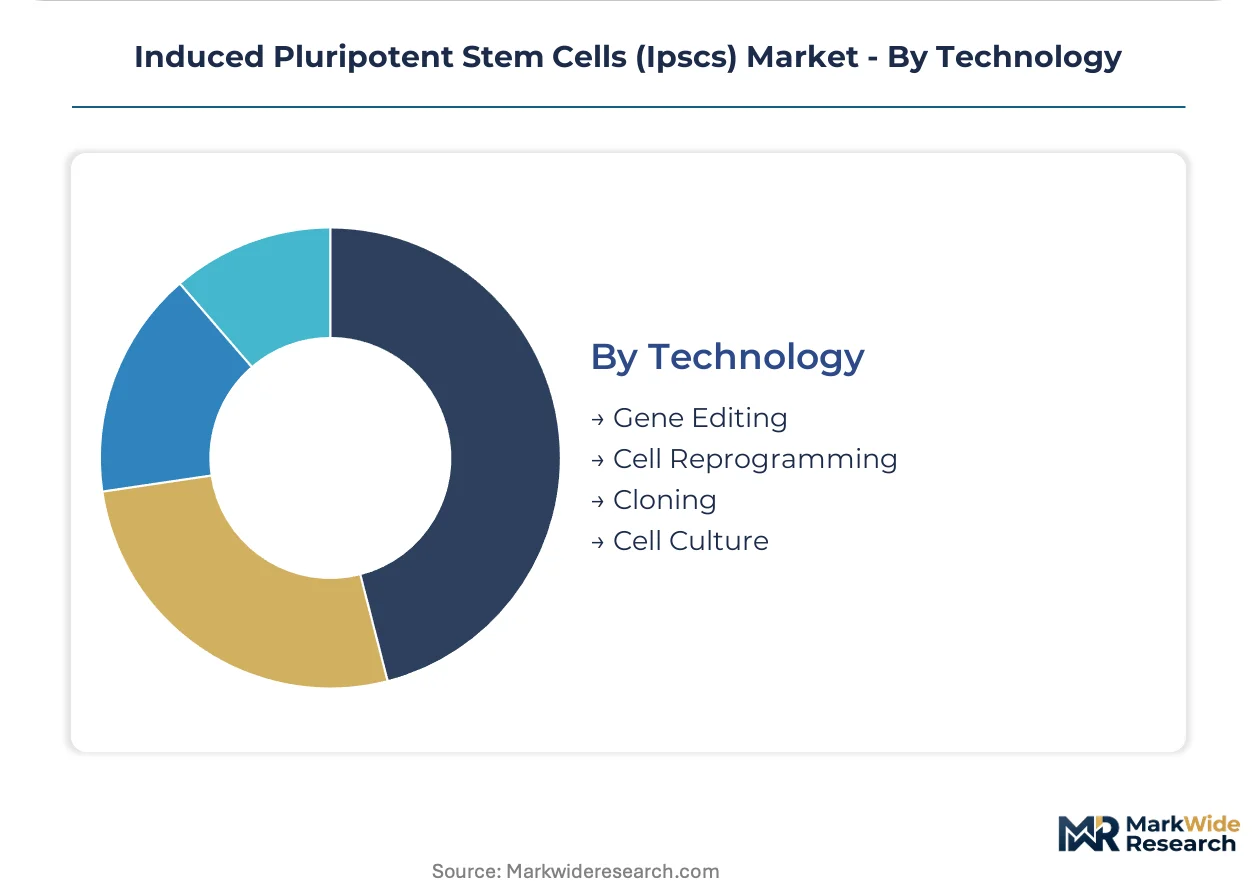
- Cell Reprogramming:mRNA-based delivery systems are displacing Sendai virus and episomal plasmid methods that dominated legacy workflows. Large-molecule developers are adopting non-viral approaches to eliminate residual vector clearance validation and compress timelines from biopsy to qualified line.
- Gene Editing:CRISPR-Cas9 and base editing platforms enable precise genetic corrections in patient-derived iPSC lines. Therapeutic developers targeting monogenic diseases are integrating editing and reprogramming into unified manufacturing processes.
- Cell Culture:Automated expansion and differentiation protocols reduce manual intervention error rates.
- Cloning:Single-cell isolation and expansion techniques support master cell bank derivation.
Cell Culture holds the largest share; Gene Editing is gaining share fastest as therapeutic applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in iPSC technologies favor net importers of GMP manufacturing infrastructure, with Japan and the United States running structural trade surpluses in qualified cell banks while European and Asian developers rely on cross-border sourcing for master cell line creation.
United States
Pharmaceutical developers concentrate clinical-stage iPSC pipelines in Massachusetts and California, driving demand for contract manufacturing slots. The FDA's regenerative medicine advanced therapy designation compresses premarket review timelines for qualifying candidates. Boston's biotech corridor hosts multiple GMP-adjacent academic core facilities that supply starting materials to venture-funded cell therapy specialists.
Japan
METI-backed national banking infrastructure positions the country as the dominant Pacific supplier of qualified iPSC lines for international therapeutic developers. The PMDA's conditional approval pathway accelerates commercial timelines, attracting foreign sponsors to establish manufacturing presence in Kobe and Osaka. Kobe's regenerative medicine cluster hosts dedicated GMP facilities serving both domestic and export markets.
Germany
Large-molecule developers in Baden-Württemberg and Bavaria are building captive iPSC capabilities for master cell bank creation. The EMA enforces GMP standards for cell-based medicinal products that exceed research-grade requirements. Heidelberg and Munich anchor competing academic-industrial consortia for non-viral reprogramming technology development.
Switzerland
Basel-based pharmaceutical conglomerates are consolidating iPSC procurement through exclusive partnerships with qualified suppliers. Swissmedic maintains alignment with EMA standards while offering streamlined national authorization pathways. The country's contract manufacturing sector specializes in high-value culture media formulations for export to EU and Asian markets.
South Korea
Seoul Capital Area biotech ventures are scaling GMP-compatible iPSC expansion for allogeneic immunotherapy applications. The MFDS has accelerated cell therapy approval timelines through conditional licensing frameworks. Songdo's free economic zone hosts dedicated regenerative medicine manufacturing parks targeting regional export demand.
Induced Pluripotent Stem Cells (Ipscs) Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated platform providers with captive manufacturing, specialized contract development organizations, and upstream reagent suppliers competing on workflow integration. Platform specialists anchor therapeutic pipelines through proprietary master cell bank creation. Contract manufacturers capture value from GMP facility scarcity. Reagent vendors defend position through chemically defined formulation portfolios that reduce customer switching costs. Dominant competitive moves include strategic partnerships for GMP slot allocation and technology licensing for non-viral reprogramming modalities.
Within the integrated platform tier, Fate Therapeutics exemplifies clinical-stage pipeline anchoring across oncology and immunology applications. Lonza occupies a dominant position in contract manufacturing and development services, extending reach through dedicated cell-and-gene therapy production networks. Thermo Fisher Scientific represents the upstream supply consolidation archetype, competing on integrated workflow solutions that reduce batch variability and simplify regulatory documentation for pharmaceutical developers.
| Leading Market Players |
|---|
| FUJIFILM Cellular Dynamics |
| Fate Therapeutics |
| Thermo Fisher Scientific |
| Lonza |
| REPROCELL |
| Ncardia |
| Axol Bioscience |
| Evotec |
| Cynata Therapeutics |
| Others |
Supply & Pricing Matrix
Japanese GMP master cell bank production concentrates upstream supply for qualified iPSC lines, anchoring margin capture downstream at contract manufacturing nodes in Kobe and Osaka where slot scarcity commands premium positioning.
Pricing Analysis
Pharmaceutical companies anchor pricing stratification across premium GMP-qualified, standard research-grade, and economy consumable tiers. Price differentiation rests on FDA/EMA/PMDA certification grade and serum-free formulation complexity. Cost compression in research-grade reagents intensifies as Chinese suppliers expand chemically defined media production. Academic core facilities exhibit highest price sensitivity; large-molecule developers with captive GMP infrastructure show lowest.
Supply Chain Analysis
Export-control regimes on CRISPR-Cas9 editing tools and mRNA reprogramming IP limit technology flows from United States and Germany to emerging manufacturing hubs. Critical growth factors and cytokines draw from Swiss and Japanese specialized suppliers, creating single-source vulnerability for qualified GMP inputs. Distribution runs through Lonza's cell-and-gene therapy networks and academic core facility consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
iPSC-derived allogeneic cell therapies sit in early-cycle expansion, with PMDA conditional approvals and RMAT designations compressing clinical translation timelines faster than prior regenerative medicine platforms.
For Market Incumbents: Harden GMP slot allocation through exclusive multi-year partnerships with emerging biotech developers, insulating against mRNA reprogramming commoditization. Lock in backward integration into chemically defined media production to defend margin position from Chinese supplier encroachment. Prioritize automated closed-system bioreactor deployment to reduce manual intervention error rates in high-volume manufacturing. For New Entrants and Emerging Players: Mid-tier CRO capacity in India and South Korea represents the most penetrable entry point as CDSCO and MFDS guidelines align with ICH standards. Organoid disease modeling contracts with cosmetic and chemical toxicology sectors offer near-term revenue without GMP infrastructure burden. Lead with machine vision-based quality assessment platforms to differentiate on process robustness. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing specialists holding GMP-adjacent academic core facility networks. Five-to-ten year viability hinges on allogeneic cell therapy commercialization scale rather than research-grade reagent volumes. Watch FDA regenerative medicine guidance evolution as the signal for manufacturing infrastructure investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Master Cell Bank Creation | Pharmaceutical developers consolidate procurement through qualified banks to streamline IND-enabling studies. |
| Non-Viral Reprogramming Licensing | mRNA-based delivery systems eliminate residual vector clearance validation and compress qualification timelines. |
| Automated Cell Handling Platforms | Closed-system bioreactors reduce manual intervention error rates in commercial-scale iPSC expansion. |
| Organoid Disease Modeling Services | Patient-derived iPSC organoids open toxicology contracts with cosmetic and chemical sectors. |
| Regulatory Approval Pathway Optimization | RMAT designation and PMDA conditional approvals accelerate premarket review for serious unmet medical need candidates. |
Research Methodology
Operator-level perspectives from cell therapy manufacturing heads, regulatory affairs leads at iPSC platform developers, GMP facility directors, and academic core facility managers anchored the qualitative base. Secondary validation drew from FDA RMAT designations, PMDA conditional approval filings, EMA cell-based medicinal product guidance, and ClinicalTrials.gov iPSC trial registries. Bottom-up segment sizing triangulated against top-down pharmaceutical pipeline value estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value outputs by product type, application, end user, and technology segmentation. CAGRs derived from GMP infrastructure deployment trajectories, regulatory approval velocity, and allogeneic cell therapy pipeline maturation. Forecast inputs incorporated METI-backed banking infrastructure expansion and mRNA reprogramming adoption curves.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding availability and cell therapy reimbursement policy would shift the trajectory. Material shifts in FDA regenerative medicine guidance or PMDA post-market surveillance requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wood Stoves Market
Others
Light Meter Market
Others
North America Astrology Market
Others
AI in Home Automation Market
Others
Automotive Smart Lighting Market
Others
Edge Computing in Healthcare Market
Others
Liposomes Market
Others
Asia-Pacific Adtech Market
Others
Global Compact Wheel Loaders Market
Others
China Automotive LED Lighting Market
Others
Storm Surge Barriers Market
Others
United States Bean Bags Market
Others
Global Hardware Acceleration Market
Others
Thiamethoxam Market
Others
Space Power Supply Market
Others
Global Drug Discovery Informatics Market