
 Personal Navigation Devices Market | 2026-2036
Personal Navigation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Navigation Devices Market Outlook
Aftermarket service revenue is rewriting margin capture across the personal navigation devices ecosystem. Garmin Ltd. dominates dedicated outdoor and automotive hardware with specialized handheld units built for geocaching and backcountry routing. TomTom International BV. leverages fleet management software subscriptions to sustain recurring revenue streams alongside its legacy navigation hardware. Apple Inc. competes through tight integration of GPS, GLONASS, and BeiDou positioning within its smartphone application layer, eroding standalone device relevance among casual travelers.
Personal navigation devices are portable or embedded electronic systems that compute real-time geographic position through multi-constellation satellite signal reception, typically integrating GPS, GLONASS, BeiDou, and Galileo receivers with digital map databases and route optimization algorithms for travel, fleet coordination, or outdoor wayfinding. The portable GPS category retains structural importance among hiking enthusiasts and commercial fleet operators requiring ruggedized hardware with extended battery life and offline map storage. Smartphone applications capture volume leadership through ubiquity, though wearable devices represent the fastest-growing segment as cyclists and fitness-oriented users demand wrist-mounted turn-by-turn guidance with heart rate and performance overlay integration.
The FCC governs radio frequency emissions and spectrum allocation for GNSS receivers sold in the United States, while the EU AI Act and CE marking requirements under the MDR framework shape product compliance for devices with biometric or voice-interaction features in Europe. China's SAMR enforces GB standards for electronic mapping accuracy and data security, constraining foreign map providers while accelerating domestic BeiDou-native hardware adoption. Stakeholders must monitor evolving multi-constellation mandates and cross-border data localization rules as regulators tie navigation accuracy claims to certified satellite coverage minimums.
Market Dynamics
Multi-constellation GNSS chipsets incorporating BeiDou and Galileo compatibility are compressing hardware margins while expanding positioning accuracy requirements across fleet management and outdoor recreation segments.
Growth Catalysts
- Fleet Management Digitization:Commercial vehicle operators in Germany are mandating dedicated portable units with offline map storage to reduce cellular dependency during cross-border logistics routing.
- REACH Compliance:European environmental regulations restricting hazardous substances in electronics are accelerating redesign cycles for ruggedized handheld devices with extended battery architectures.
- BeiDou Native Adoption:China's SAMR enforcement of GB standards for electronic mapping accuracy is driving domestic hardware substitution away from GPS-dependent legacy chipsets.
Market Restraints
- Semiconductor Supply Concentration:Advanced GNSS receiver fabrication depends on Taiwan-based foundry capacity, creating vulnerability to geopolitical disruption in multi-constellation chipset sourcing.
- Smartphone Substitution:Apple and Android integrated positioning layers are eroding casual traveler demand for standalone portable units through application-layer convenience.
- Lithium-Ion Cost Volatility:Extended battery life requirements for backcountry devices expose manufacturers to cathode material price swings in ruggedized product lines.
Strategic Opportunities
- Wearable Integration:Cyclists and fitness-oriented users in the United States are adopting wrist-mounted turn-by-turn guidance with heart rate overlay, creating white space for biometric-navigation convergence.
- EU AI Act Tailwind:Voice-interaction and biometric-enabled devices face compliance pathways through CE marking under MDR frameworks, favoring early-mover certification investments.
- Aftermarket Service Unbundling:Fleet operators are separating hardware procurement from software subscription renewals, enabling recurring revenue capture independent of device replacement cycles.
Industry Challenges
- Multi-Constellation Certification Complexity:FCC testing protocols for radio frequency emissions must now validate simultaneous GPS, GLONASS, BeiDou, and Galileo reception, extending product launch timelines.
- Legacy System Integration:Enterprise fleet management platforms require backward compatibility with decade-old telematics protocols, complicating firmware architecture for new hardware generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Navigation Devices Market |
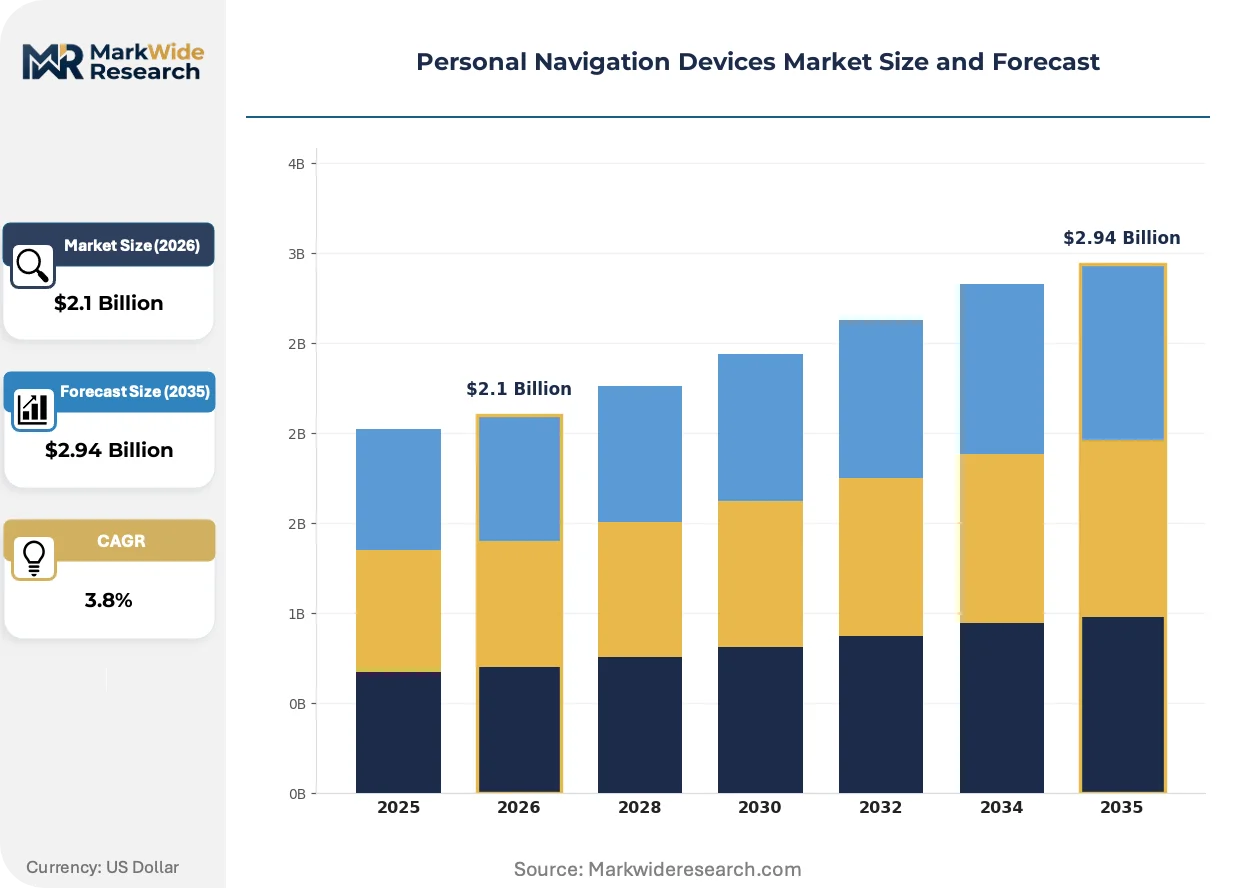
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable GPS, Built-in Navigation, Smartphone Applications, Wearable Devices Technology: GPS, GLONASS, BeiDou, Galileo End User: Automotive, Hiking Enthusiasts, Cyclists, Commercial Fleet Application: Travel, Geocaching, Fleet Management, Outdoor Activities |
| Companies Covered | Samsung Electronics Co. Ltd., Continental, Garmin Ltd., Shenzhen RoadRover Technology Co Ltd, Sony Corporation, Apple Inc., Huawei Technologies Co. Ltd., Magellan GPS, TomTom International BV., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Navigation Devices Market Strategic Shifts
Cloud-based map rendering and real-time traffic fusion are compressing the value of onboard storage while elevating connectivity requirements across portable and embedded navigation systems.
Software-defined GNSS receivers are virtualizing signal processing functions that previously required dedicated hardware accelerators. Fleet management operators are piloting these architectures to reduce unit costs in large-scale deployments. This virtualization is compressing the traditional hardware-software boundary and enabling over-the-air constellation support updates without physical redesign.
The EU AI Act and associated CE marking requirements under the MDR framework are mandating algorithmic transparency for devices with voice-interaction capabilities. Manufacturers must now document decision pathways for route recommendations involving biometric data. European outdoor recreation hardware faces the steepest compliance burden as hiking-oriented products integrate heart rate and stress indicators.
Aftermarket service unbundling is fragmenting traditional hardware-software bundling models. Fleet operators in Germany are separating device procurement from subscription renewals, forcing vendors to compete on recurring platform value rather than upfront unit economics. This behavioral shift is most visible in commercial logistics verticals where total cost of ownership calculations now dominate procurement evaluations.
Personal Navigation Devices Market Segmentation
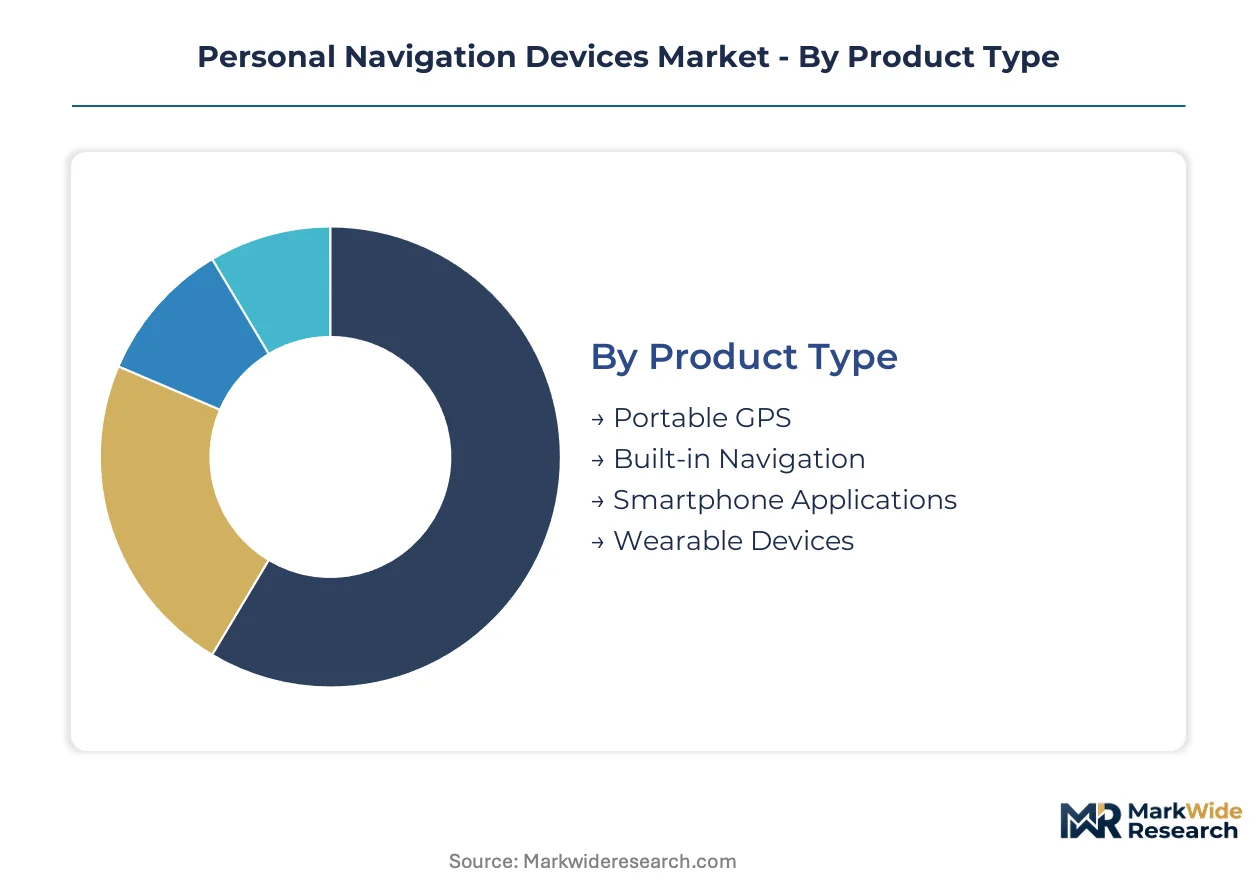
Hardware refresh cycles and software update frequencies diverge sharply across personal navigation devices. Segmentation reveals which categories generate recurring revenue versus one-time purchases.
Product Type:
Replacement timelines stretch from annual smartphone upgrades to decade-long embedded automotive installations, creating divergent revenue recognition patterns across hardware categories.
- Portable GPS:Ruggedized handheld units with offline map storage and extended battery architectures serve hiking enthusiasts and commercial fleet operators. Germany's cross-border logistics sector mandates these units to reduce cellular dependency during corridor routing.
- Smartphone Applications:GPS, GLONASS, and BeiDou positioning layers integrated within iOS and Android application stacks capture casual travelers through ubiquity. Apple and Google erode standalone device relevance by embedding turn-by-turn guidance at zero marginal hardware cost.
- Wearable Devices:Wrist-mounted units with heart rate overlay integration serve cyclists and fitness-oriented users in the United States. Biometric-navigation convergence drives steepest expansion trajectory in this category.
- Built-in Navigation:Embedded automotive systems with factory-installed receivers and proprietary map databases lock consumers into manufacturer update ecosystems. Long replacement cycles constrain aftermarket service penetration.
Smartphone applications dominate installed base. Wearable devices concentrate expansion momentum.
Technology:
Constellation compatibility requirements stratify by application criticality, with commercial fleet operators demanding multi-system redundancy that casual travelers forgo.
- GPS:Legacy L1/L5 signal reception remains baseline specification for consumer-grade hardware. United States regulatory frameworks through FCC emissions protocols anchor certification requirements for all downstream receivers.
- BeiDou:China's SAMR-enforced GB standards for electronic mapping accuracy accelerate domestic hardware substitution. Native chipset adoption displaces GPS-dependent legacy architectures in Chinese-manufactured devices.
- GLONASS:Russian constellation compatibility provides northern latitude coverage redundancy for outdoor recreation hardware. Cold-weather signal stability matters for backcountry routing above 60 degrees.
- Galileo:European GNSS infrastructure delivers high-accuracy service tier for commercial fleet management. CE marking requirements under EU regulatory frameworks validate receiver performance claims.
GPS retains installed base dominance. BeiDou captures fastest share gain in manufacturing origin.
End User:
Procurement authority separates consumer discretionary purchases from enterprise fleet mandates with binding technical specifications.
- Commercial Fleet:Enterprise operators in Germany separate hardware procurement from software subscription renewals, enabling recurring revenue capture independent of device replacement. Total cost of ownership calculations dominate procurement evaluations.
- Hiking Enthusiasts:Ruggedized handheld demand concentrates in United States and German markets where backcountry wayfinding requires offline map storage and extended battery life. REACH compliance accelerates redesign cycles for hazardous substance restrictions.
- Automotive:OEM-embedded systems lock consumers into proprietary update ecosystems with long replacement cycles constraining aftermarket penetration.
- Cyclists:Fitness-oriented users adopt wrist-mounted guidance with performance overlay integration, driving biometric-navigation hardware convergence.
Commercial fleet operators anchor enterprise revenue. Cyclists represent fastest-growing user acquisition pool.
Application:
Use case specificity determines hardware durability requirements and connectivity dependencies.
- Fleet Management:Real-time telematics integration with decade-old protocol backward compatibility complicates firmware architecture. Cloud-based map rendering elevates connectivity requirements while compressing onboard storage value.
- Outdoor Activities:Backcountry routing demands ruggedized hardware with extended battery architectures and offline map storage. EU AI Act compliance burdens hiking-oriented products integrating biometric indicators.
- Travel:Casual navigation relies on smartphone application ubiquity with minimal hardware differentiation.
- Geocaching:Specialized handheld units with sub-meter accuracy and community waypoint databases serve dedicated enthusiast communities.
Fleet management anchors enterprise software revenue. Outdoor activities drive ruggedized hardware margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in Germany accept premium pricing for certified multi-constellation hardware, while casual travelers in India gravitate toward zero-marginal-cost smartphone applications. This demand-elasticity contrast shapes divergent go-to-market strategies across geographies.
United States
Cyclists and fitness-oriented users drive wearable device adoption with wrist-mounted turn-by-turn guidance. The FCC governs radio frequency emissions for GNSS receivers through spectrum allocation protocols. Silicon Valley clusters host software-defined GNSS receiver development for fleet management virtualization.
Germany
Cross-border logistics operators mandate dedicated portable units with offline map storage to reduce cellular dependency. REACH compliance accelerates redesign cycles for hazardous substance restrictions in ruggedized handhelds. Bavaria hosts automotive OEM embedded navigation system engineering centers.
China
SAMR enforcement of GB standards for electronic mapping accuracy accelerates domestic BeiDou-native hardware substitution. MIIT coordinates multi-constellation chipset manufacturing standards. Shenzhen manufacturing clusters concentrate ruggedized portable GPS production for export markets.
Japan
METI promotes precision agriculture applications requiring sub-meter GNSS accuracy for automated machinery guidance. PMDA oversight extends to biometric-enabled wearable navigation devices with health monitoring integration. Nagoya automotive suppliers integrate multi-constellation receivers into factory-installed navigation platforms.
India
BIS certification requirements for electronic navigation devices create compliance barriers for imported hardware. TRAI spectrum policies shape GNSS receiver market access for foreign manufacturers. Bengaluru technology clusters develop low-cost smartphone navigation applications for mass-market penetration.
Personal Navigation Devices Market Competitive Environment
Capability concentration sits with specialized outdoor hardware fabricators; scale advantage sits with consumer electronics conglomerates with integrated positioning layers. The vendor base stratifies across three tiers: dedicated navigation specialists, diversified technology holding companies, and automotive Tier-1 suppliers. Dominant competitive moves include aftermarket service unbundling to capture recurring software revenue and multi-constellation certification investments to satisfy divergent regional mandates.
Within the dedicated navigation specialist tier, Garmin Ltd. and TomTom International BV. occupy positions defined by hardware-software integration depth. Among Asia-Pacific diversified technology conglomerates, Samsung Electronics Co. Ltd. and Huawei Technologies Co. Ltd. exemplify scale-driven positioning through smartphone ecosystem integration. Apple Inc. anchors the application-layer convergence archetype where zero-marginal hardware cost erodes standalone device relevance.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| Continental |
| Garmin Ltd. |
| Shenzhen RoadRover Technology Co Ltd |
| Sony Corporation |
| Apple Inc. |
| Huawei Technologies Co. Ltd. |
| Magellan GPS |
| TomTom International BV. |
| Others |
Value Chain & Pricing Dynamics
Taiwan-based foundry concentration for advanced GNSS receiver fabrication anchors margin distribution across the personal navigation devices ecosystem, with multi-constellation chipset sourcing vulnerability translating into pricing power asymmetries between hardware fabricators and downstream fleet management operators.
Pricing Analysis
Aftermarket service revenue tiers including software subscription renewals and extended warranty contracts now drive lifetime value capture across fleet management deployments. Three-tier pricing structure across premium certified multi-constellation units, standard GPS-native hardware, and economy smartphone-dependent applications stratifies the market. Cost compression in ruggedized handheld segments is intensifying because REACH compliance mandates accelerate redesign cycles for extended battery architectures. Commercial fleet operators demonstrate lowest price sensitivity due to total cost of ownership procurement frameworks, while casual travelers exhibit highest elasticity given zero-marginal-cost smartphone substitution.
Supply Chain Analysis
Supplier-financing facilities including extended payment terms from Taiwan-based semiconductor foundries have become critical liquidity mechanisms for hardware manufacturers managing lithium-ion cathode material price volatility. Geographic supply concentration centers on Taiwan for GNSS receiver fabrication, China for BeiDou-native chipset assembly, and South Korea for display panel integration. Raw material dependencies encompass lithium carbonate for battery architectures, rare earth elements for antenna substrates, and advanced ceramics for ruggedized housing components. Single-source vulnerability in Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through enterprise fleet procurement channels, outdoor recreation retail networks, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as fleet operators unbundle hardware procurement from software subscriptions, with interoperability between legacy telematics protocols and cloud-native navigation architectures determining competitive survival.
For Market Incumbents: Pre-empt smartphone ecosystem encroachment by deepening certification investments for FCC multi-constellation validation and EU AI Act compliance pathways. Fortify recurring revenue capture through aftermarket service unbundling that separates device replacement cycles from platform subscription renewals. Vertical integration into software-defined GNSS receiver development reduces unit cost exposure in large-scale fleet deployments. For New Entrants and Emerging Players: Mid-market wearable navigation devices for cyclists and fitness-oriented users in the United States represent the most penetrable entry point given biometric-navigation convergence tailwinds and lower incumbent saturation. Germany's cross-border logistics sector offers secondary white-space opportunity through REACH-compliant ruggedized hardware with offline map storage. Go-to-market execution should prioritize direct e-commerce channels bypassing traditional outdoor recreation retail markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet management software platforms possessing installed hardware bases but underoptimized subscription monetization. Long-term viability over the five-to-ten year window hinges on successful navigation-as-a-service transition away from transactional device economics. Monitor BeiDou-native hardware substitution rates in Chinese manufacturing clusters as the critical inflection signal for multi-constellation chipset demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification Investment | FCC validation protocols for simultaneous GPS, GLONASS, BeiDou, and Galileo reception extend product launch timelines but lock out uncertified competitors. |
| Software-Defined GNSS Receiver Development | Virtualization of signal processing functions enables over-the-air constellation updates without physical redesign for fleet operators. |
| EU AI Act Compliance Pathway | CE marking under MDR frameworks for voice-interaction devices mandates algorithmic transparency documentation for route recommendations. |
| Aftermarket Service Unbundling | Separating hardware procurement from subscription renewals captures recurring revenue independent of device replacement cycles. |
| Wearable Biometric Integration | Wrist-mounted turn-by-turn guidance with heart rate overlay serves cyclists and fitness-oriented users in the United States. |
Study Parameters
Initial hypotheses were tested against primary input from fleet management procurement directors, outdoor recreation retail buyers, GNSS chipset engineering leads, and automotive OEM platform engineers and refined through secondary validation against SEC filings, FCC equipment authorization databases, EU regulatory filings under MDR frameworks, and customs trade data for navigation hardware imports. Bottom-up unit shipment estimates across portable GPS, smartphone applications, wearable devices, and built-in navigation categories were triangulated against top-down market value reconstructions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions encompassing product type, constellation technology compatibility, end user procurement authority, and application use case specificity. CAGRs were derived from installed base evolution modeling incorporating replacement cycle divergence and technology substitution elasticities. Industry-specific forecast inputs included multi-constellation mandate adoption curves and fleet management digitization penetration rates.
Macroeconomic conditions sit as an overlay; deviation in lithium-ion battery material costs, semiconductor foundry utilization rates, or cross-border logistics freight indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and constellation infrastructure deployment schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Conveyor Monitoring Market
Sensors
Smart Mat Market
Sensors
Transport Monitoring System Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Underground Service Locator Market
Sensors
Telemetric Devices Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Vision Positioning System Market
Sensors
Residential Water Leak Detection System Market
Sensors
APAC Wireless Sensors Market
Sensors
Barcode Scanner Market
Sensors
Vibration Monitoring Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Weigh-In-Motion System Market