
 US Textile Market | 2026-2036
US Textile Market Size, Share, and Industry Trends Forecast 2026-2036
US Textile Market Insights
Defense contractors and technical apparel buyers is redrawing demand priorities across the US textile landscape. Milliken & Company leverages its vertically integrated manufacturing campus in South Carolina to dominate military-grade fabric contracts. Mohawk Industries anchors the residential flooring segment through extensive tufting operations across Georgia and Alabama. Parkdale Mills sustains its position as the nation's largest spinner of cotton and cotton-polyester yarns, supplying downstream weavers and knitters.
US textiles encompass fibers, yarns, fabrics, and finished goods engineered from natural and synthetic polymers, with technical specifications ranging from tenacity ratings of 7-15 grams per denier for industrial applications to flame-resistance standards of 12-second char lengths for protective wear. These materials serve commercial, industrial, and institutional end uses spanning apparel, interiors, transportation, and safety equipment. Cotton and polyester together command the product type landscape, with cotton benefiting from consumer preference for natural fibers while polyester gains ground in performance applications requiring moisture wicking and dimensional stability. The fabric type dimension shows knitted constructions outpacing woven alternatives in growth velocity, driven by athleisure and medical textile demand, while non-woven formats capture margin pools in filtration and hygiene disposables.
The Berry Amendment, administered by the Department of Defense, mandates domestic sourcing of textiles for military applications, creating a protected demand base for US-based spinners and weavers. OSHA workplace safety standards and FTC labeling requirements further constrain product specifications and market access for non-compliant imports. Stakeholders must monitor evolving Federal Trade Commission enforcement around recycled content claims and emerging state-level extended producer responsibility frameworks.
Market Dynamics
Defense procurement mandates and Berry Amendment compliance requirements are restructuring supplier qualification pathways across the US textile sector, compressing lead times for domestic mill certification while elevating technical performance thresholds for military-grade fabric contracts.
Growth Catalysts
- Berry Amendment Procurement Mandates:Department of Defense sourcing rules guarantee domestic mill participation in military textile contracts, insulating US spinners from import price competition.
- Technical Apparel Specifications:Flame-resistance standards for protective wear and tenacity ratings for industrial applications are pulling premium fiber development toward domestic R&D centers.
- Carolinas Manufacturing Corridor:Concentrated spinning, weaving, and finishing capacity across North and South Carolina reduces logistics costs for defense contractors qualifying suppliers.
Market Restraints
- Raw Cotton Price Volatility:Weather-driven supply fluctuations in Texas and Georgia growing regions compress spinning margins during drought cycles.
- Capital Equipment Concentration:High-speed air-jet looms and automated dyeing systems concentrate among a narrow supplier base, creating bottleneck risk for capacity expansion.
- Polyester Feedstock Dependency:PTA and MEG chemical inputs tie domestic synthetic fiber production to petroleum price cycles and Gulf Coast refinery output.
Strategic Opportunities
- Medical Textile Expansion:Antimicrobial fabric demand for surgical gowns and wound dressings opens white space beyond traditional apparel end-uses.
- IRA Clean Manufacturing Credits:Inflation Reduction Act incentives for energy-efficient textile production reward capital investment in heat-recovery dyeing systems.
- Recycled Polyester Integration:Post-consumer PET bottle feedstock convergence with fiber extrusion technology enables circular material claims for performance apparel brands.
Industry Challenges
- Skilled Loom Technician Shortage:Retirement waves among Jacquard and Dornier loom operators outpace vocational training program output in the Southeast.
- Berry Compliance Documentation Burden:Multi-tier supply chain tracing requirements for military contracts extend certification timelines for new mill entrants.
- Legacy Dyehouse System Integration:Waterless dyeing and digital printing technologies face friction against existing wastewater infrastructure and chemical handling permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Textile Market |
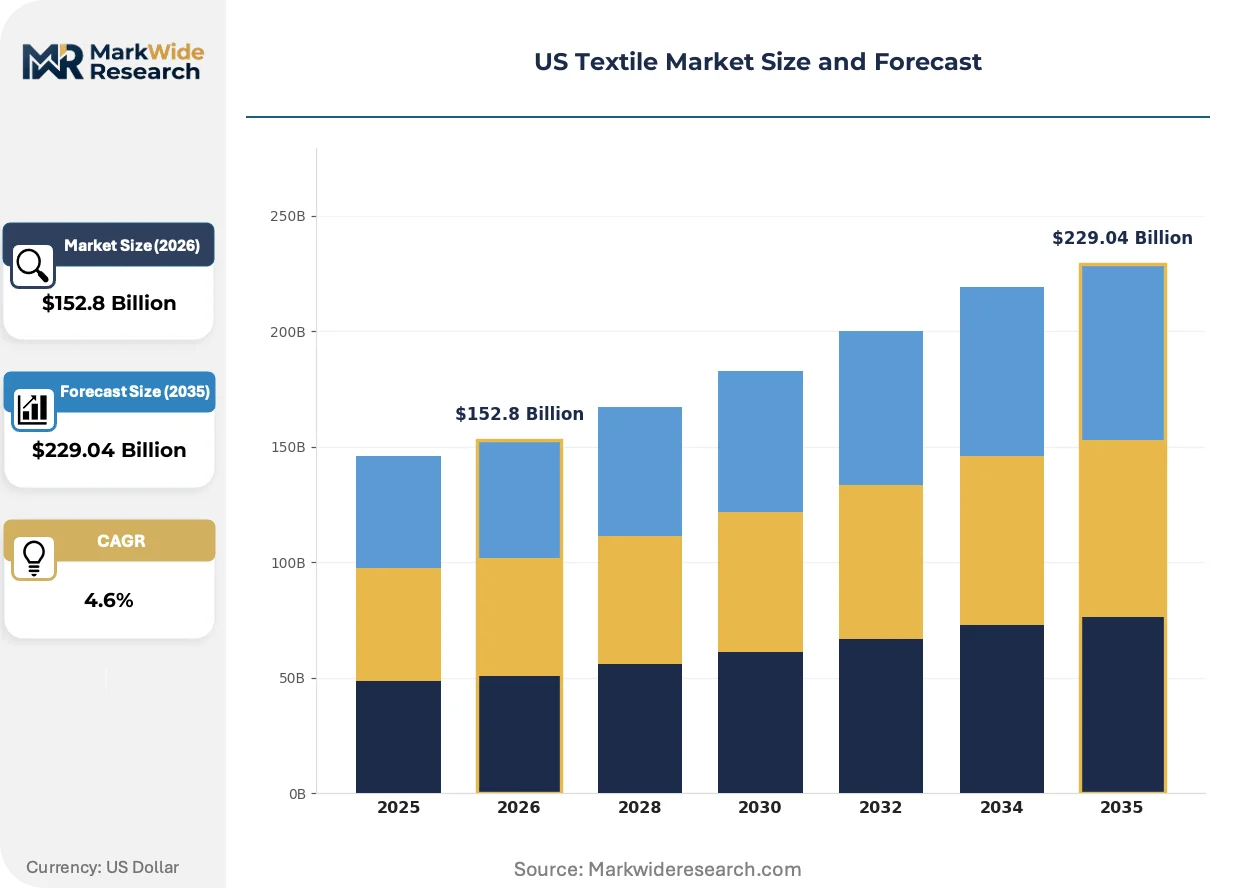
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $229.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Wool, Nylon End User: Fashion Apparel, Home Furnishings, Industrial Textile, Automotive Upholstery Fabric Type: Knitted, Woven, Non-Woven, Bonded Distribution Channel: E-Commerce, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Milliken & Company, Mohawk Industries, Shaw Industries Group, Parkdale Mills, Springs Global U.S. Inc., Hanesbrands, Inc., Maples Industries, Inc., Welspun Living, Standard Textile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Textile Market Trends and Innovations
Digital manufacturing and sustainability verification protocols are rewriting production workflows and buyer qualification standards across US textile operations. Technical performance demands from defense and medical end-uses are accelerating material science investment.
Digital textile printing is decomposing traditional rotary screen and flatbed methods by eliminating engraved cylinder lead times and enabling micro-batch color customization. Activewear brands and defense prototyping labs are adopting single-pass inkjet systems at accelerating pace. This technology is decomposing minimum order quantity constraints that historically protected large-volume commodity producers.
OSHA workplace safety standards and FTC Green Guides enforcement are tightening chemical disclosure and recycled content claim requirements for textile labeling. Manufacturers must now document flame-retardant additive compositions and substantiate environmental marketing claims with third-party certification. Technical apparel and home furnishings segments face the steepest compliance investment curves as enforcement actions escalate.
Defense contractors are consolidating supplier panels and extending qualification timelines to lock in Berry Amendment-compliant domestic sources. Long-term offtake agreements are displacing spot purchasing for military-grade nylon and aramid fabrics. This concentration is most visible in South Carolina, where Milliken and specialty weavers have secured multi-year Pentagon contracts through 2028.
US Textile Market Segmentation
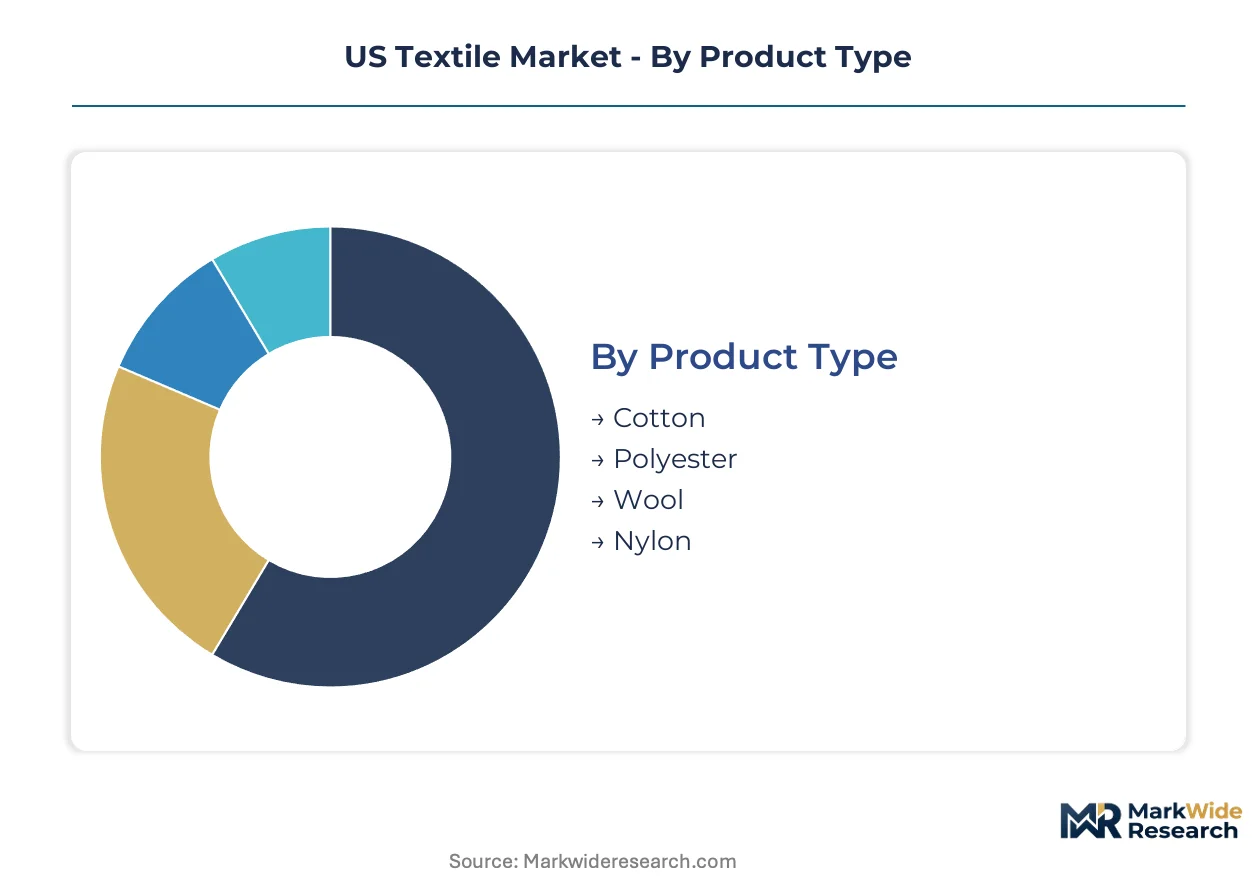
Segmentation in the US textile sector reveals how defense procurement mandates, regional manufacturing clusters, and channel economics partition commercial opportunity. Buyers across military, medical, and consumer verticals impose incompatible specification regimes that reward specialized production footprints.
Product Type:
Cotton and polyester dominate domestic mill output, while wool and nylon serve narrower export-defense niches with distinct certification requirements.
- Cotton:Natural cellulose fibers spun into yarns ranging from 20s to 80s count for apparel and home textile applications. Demand concentrates in Carolinas spinning corridors serving Berry Amendment-compliant military contracts and premium denim brands requiring traceable US-grown staple.
- Polyester:Thermoplastic polymer fibers extruded from PTA and MEG feedstocks, engineered for moisture-wicking athletic wear and industrial belting. The Southeast chemical belt around Charleston and Houston supplies domestic polymerization capacity, insulating spinners from Asian feedstock volatility.
- Wool:Protein fibers from domestic sheep operations in Texas and Montana, processed for cold-weather military layering and luxury suiting. Export demand from European tailoring houses sustains scouring capacity in New England.
- Nylon:Polyamide 6,6 fibers produced at Ascend Performance Materials' Alabama and Florida facilities, specified for parachute cord, ballistic fabrics, and automotive airbags. Pentagon offtake agreements lock in multi-year production schedules.
Cotton commands the established base. The steepest expansion runs through polyester.
End User:
Cost tiers separate commodity volume plays from specification-driven premium positions, with defense and medical buyers paying qualification premiums that apparel brands resist.
- Fashion Apparel:Garment manufacturing for mass-market and premium labels, sourced through domestic cut-and-sew contractors in Los Angeles and New York. Fast-fashion velocity demands compress lead times for knit jersey and woven shirting.
- Home Furnishings:Upholstery, drapery, and carpet yarns tufted across Georgia and Alabama. Mohawk Industries and Shaw Industries anchor residential flooring demand with specification-grade stain resistance and wear ratings.
- Industrial Textile:Conveyor belting, filtration media, and geotextiles requiring tenacity ratings above 10 grams per denier. Technical specifications from OSHA and EPA drive flame-retardant and chemical-resistance testing protocols.
- Automotive Upholstery:Seating fabrics and interior trim for Detroit Three and transplant assembly plants. Just-in-sequence delivery requirements from Tennessee and Kentucky auto corridors favor nearby weaving operations.
Home furnishings absorb the highest fiber tonnage. Industrial textiles claim the fastest margin expansion.
Fabric Type:
Application requirements dictate construction choice, with medical and defense buyers driving technology migration across format boundaries.
- Knitted:Interlooped yarn constructions produced on circular and flatbed machines, dominating athleisure and compression medical garments. North Carolina's technical knitting cluster supplies antimicrobial and graduated-compression specifications for surgical recovery wear.
- Woven:Interlaced warp and weft constructions on air-jet and rapier looms, specified for military uniforms and ballistic panels. South Carolina's Milliken campus maintains Berry Amendment certification for Pentagon combat fabric contracts.
- Non-Woven:Fiber webs bonded mechanically, thermally, or chemically for filtration, hygiene, and medical disposables. Spunbond and meltblown capacity expanded during pandemic demand surges for N95 media.
- Bonded:Laminated multi-layer fabrics combining wovens, knits, and membranes for protective outerwear and surgical barriers. Cleanroom manufacturing in Massachusetts and Minnesota serves FDA-regulated medical device integration.
Woven fabrics anchor defense procurement volumes. Knitted constructions expand most quickly through medical and athletic channels.
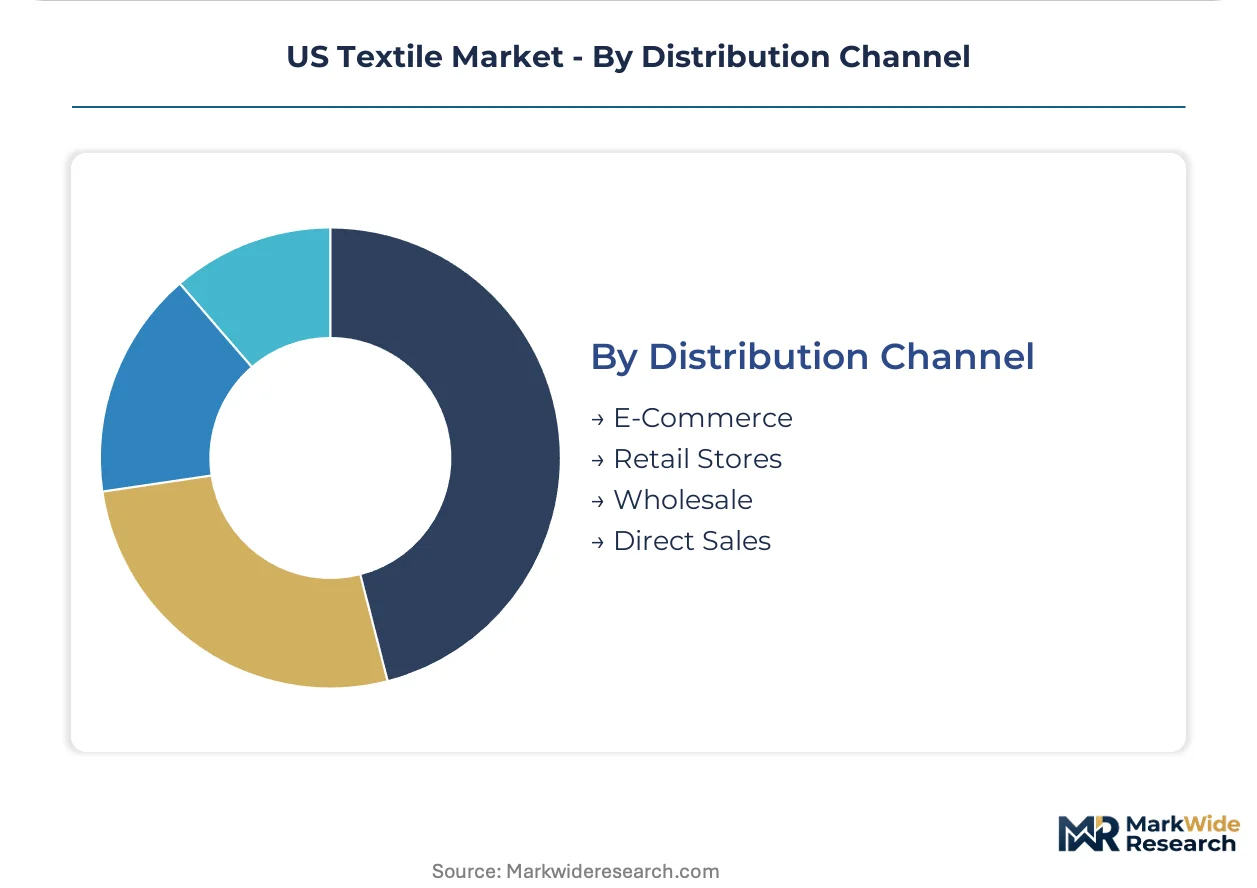
Distribution Channel:
Customer type and order scale determine channel economics, with defense contractors bypassing intermediaries while fashion brands fragment across multiple touchpoints.
- E-Commerce:Direct-to-consumer fabric sales and finished goods platforms, enabling micro-batch customization for independent designers. Digital printing integration allows single-yard orders with sub-week fulfillment from Southeast fulfillment centers.
- Retail Stores:Big-box home improvement and specialty fabric chains carrying commodity upholstery and quilting cottons. Jo-Ann Stores and Hobby Lobby drive seasonal demand spikes for DIY craft segments.
- Wholesale:Converter houses aggregating mill production for apparel manufacturers and contract furniture suppliers. New York's Garment District and Los Angeles Fashion District maintain residual jobber networks for remnant and closeout volumes.
- Direct Sales:Mill-direct relationships with defense contractors, automotive Tier 1s, and medical device manufacturers. Long-term offtake agreements with the Department of Defense lock in multi-year nylon and aramid commitments.
Wholesale channels move the highest fabric volumes. Direct sales capture the steepest value-per-pound premiums through military qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US textile capacity clusters in the Carolinas corridor, where spinning, weaving, and finishing operations concentrate within a 200-mile radius. This geographic density reduces logistics costs for defense contractors qualifying Berry Amendment-compliant suppliers. State-level economic development incentives and existing wastewater infrastructure reinforce the region's manufacturing dominance.
Southeast (Carolinas and Georgia)
Defense procurement and technical apparel manufacturing drive fiber demand across North and South Carolina. Berry Amendment mandates from the Department of Defense require domestic sourcing for military uniforms and ballistic fabrics. Milliken's vertically integrated campus in Spartanburg, South Carolina anchors Pentagon combat fabric contracts through 2028.
Texas and Southwest
Raw cotton production and synthetic fiber feedstock operations define the regional textile economy. Weather-driven supply fluctuations in Texas growing regions compress spinning margins during drought cycles. Gulf Coast petrochemical corridors around Houston supply PTA and MEG inputs for domestic polyester extrusion.
Georgia and Alabama
Residential flooring and carpet manufacturing absorb substantial fiber tonnage across the region. Mohawk Industries maintains extensive tufting operations serving stain-resistance and wear-rating specifications. State workforce development programs target loom technician training to offset retirement waves among experienced operators.
New England
Specialty wool scouring and medical textile cleanroom manufacturing persist in Massachusetts and Connecticut. Export demand from European tailoring houses sustains limited protein fiber processing capacity. FDA-regulated surgical barrier production in Boston suburbs serves medical device integration requirements.
California and Pacific Coast
Garment manufacturing for premium denim and athleisure brands concentrates in Los Angeles cut-and-sew corridors. Fast-fashion velocity demands compress lead times for knit jersey production. State-level extended producer responsibility frameworks are emerging for textile waste management compliance.
US Textile Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized military contractors. The sector exhibits tiered structure: vertically integrated majors controlling defense contracts, mid-scale converters serving automotive and medical channels, and regional jobbers handling commodity remnants. Two strategic archetypes dominate: Berry Amendment-certified defense suppliers and performance fiber specialists. Competitive moves center on multi-year Pentagon offtake agreements and heat-recovery dyeing system investments qualifying for IRA clean manufacturing credits.
Among the vertically integrated majors, Milliken & Company and Mohawk Industries occupy positions at opposite ends of the specification spectrum. Milliken exemplifies the defense-certified archetype through its South Carolina manufacturing campus. Mohawk Industries anchors the residential flooring segment with scale-driven tufting operations across Georgia and Alabama. Parkdale Mills represents the upstream spinner archetype as the nation's largest cotton and cotton-polyester yarn producer.
| Leading Market Players |
|---|
| Milliken & Company |
| Mohawk Industries |
| Shaw Industries Group |
| Parkdale Mills |
| Springs Global U.S. Inc. |
| Hanesbrands, Inc. |
| Maples Industries, Inc. |
| Welspun Living |
| Standard Textile |
| Others |
Pricing and Supply Chain Analysis
Recycled polyester feedstock substitution for virgin PTA-based polymer is redrawing supply geography toward post-consumer PET collection networks while compressing premium pricing power for conventional synthetic spinners. This material transition simultaneously elevates logistics costs for coastal extrusion plants and fragments historical feedstock concentration around Gulf Coast refineries.
Pricing Analysis
The Berry Amendment dictates the pricing tier structure across US textile procurement, separating Pentagon-compliant domestic mills from import-excluded commodity suppliers. Three-tier pricing structure across defense-certified, commercial-specification, and unbranded commodity levels reflects certification investment and traceability documentation burdens. Cost compression in standard-grade apparel fabrics is intensifying because Bangladesh and Vietnam spinning capacity captures downstream garment assembly. Fashion apparel brands exhibit the highest price sensitivity, while defense contractors accept qualification premiums for Berry-compliant domestic sourcing.
Supply Chain Analysis
Container availability fluctuations across the Shanghai-Charleston trade lane are elevating inbound chemical feedstock costs for Southeast polymerization plants. Geographic supply concentration centers on the Carolinas corridor, Texas cotton-growing regions, and Gulf Coast petrochemical complexes near Houston. Raw material dependencies rest on Texas upland cotton, PTA and MEG chemical inputs, and post-consumer PET flake collections. Single-source vulnerability concentrates in high-speed air-jet loom manufacturing, where European and Japanese equipment suppliers dominate. Distribution runs through mill-direct relationships with defense contractors, converter houses for apparel brands, and big-box retail chains for home furnishing commodities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical textile service layers—comprising Berry Amendment compliance consulting, dyehouse wastewater management, and loom maintenance contracts—are expanding faster than base fiber production as defense contractors outsource certification documentation and environmental permitting.
For Market Incumbents: Compound defensive positioning through captive recycling infrastructure for post-consumer PET feedstock and exclusive multi-year Pentagon offtake agreements. Emerging specialized weavers with rapid prototyping capabilities threaten contract renewal timelines for legacy mills. Certification investment in FDA-compliant cleanroom manufacturing for medical textiles represents the critical lever for margin expansion beyond commodity defense fabrics. For New Entrants and Emerging Players: Digital printing service gaps—where incumbents under-serve micro-batch customization for independent designers—offer the most penetrable white space. Target e-commerce direct-to-consumer channels with sub-week fulfillment capabilities enabled by Southeast fulfillment center partnerships. White space concentrates in antimicrobial medical textile development for surgical gown specifications not yet locked into long-term supply agreements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical fiber producers seeking exit liquidity after consolidation plays. Long-term viability over the coming decade hinges on IRA clean manufacturing credit capture and circular material certification capabilities. Acquisition target archetypes include regional dyehouses with wastewater infrastructure permits and technical knitting operations serving medical compression garment specifications. Watch Pentagon procurement budget allocation shifts between combat fabric and next-generation ballistic protection programs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Berry Amendment Certification Investment | Unlocks Pentagon combat fabric contracts through domestic sourcing compliance. |
| Post-Consumer PET Recycling Integration | Enables circular material claims for performance apparel brand partnerships. |
| Heat-Recovery Dyeing System Deployment | Captures IRA clean manufacturing credits for energy-efficient textile production. |
| Medical Textile Cleanroom Manufacturing | Qualifies FDA-regulated surgical barrier production for device integration. |
| Digital Printing Service Expansion | Eliminates minimum order constraints for micro-batch independent designer demand. |
Research Methodology
Operator-level perspectives from spinning plant managers, defense procurement officers at Tier 1 contractors, dyehouse operations directors, and medical device textile engineers anchored the qualitative base. Primary interview insights combined with secondary validation from Berry Amendment compliance filings, EPA wastewater discharge records, SEC 10-K disclosures from listed textile conglomerates, and Department of Defense contract award databases. Bottom-up fiber consumption modeling and top-down end-use demand estimation provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against raw cotton price volatility, PTA feedstock cost fluctuations, and Pentagon procurement budget scenarios. Segmentation dimensions modeled include product type, end-user vertical, fabric construction format, and distribution channel economics. CAGRs derived from historical shipment data and projected capacity expansion schedules across the Carolinas manufacturing corridor. Industry-specific inputs incorporated loom retirement rates and vocational training program output from Southeast technical colleges.
Forecasts assume regulatory continuity in Berry Amendment domestic sourcing requirements and OSHA workplace safety standards; material policy shifts would require re-modeling. Unmodeled risks include extended drought cycles in Texas cotton regions, Gulf Coast petrochemical disruption, and accelerated state-level extended producer responsibility mandates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Microfiber Leather Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Nylon Fibers Market
Synthetic Fibers
Bio-Based Elastic Core-Spun Yarn for Denim Stretch Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Anti-Static Fibers Market
Synthetic Fibers
Designer Fiber Market