
 North America Oil and Gas Line Pipe Market | 2026-2036
North America Oil and Gas Line Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil and Gas Line Pipe Market Analytics
API 5L X70 and X80 grade specifications is unwinding legacy inventory across North American transmission networks. Tenaris SA leverages its seamless pipe capacity to serve Gulf Coast LNG export terminal projects. U.S. Steel Tubular Products Inc. anchors domestic welded pipe supply for Appalachian shale gathering systems. EVRAZ plc competes through its Canadian and U.S. mill network for heavy-wall large-diameter orders.
Oil and gas line pipe denotes steel tubular products engineered to transport hydrocarbons under pressure, typically manufactured through seamless extrusion or electric resistance welding with specified yield strengths from API 5L Grade B through X80. Welded pipe dominates volume in onshore transportation applications where cost efficiency outweighs the burst-resistance premium of seamless alternatives. Coated pipe captures expanding share in offshore and corrosive-soil environments where fusion-bonded epoxy and three-layer polyethylene barriers extend asset life. Casing pipe maintains stable demand tied to drilling activity cycles rather than pipeline construction intensity.
PHMSA enforces integrity management standards under 49 CFR Part 195, while the EPA regulates emissions from compressor stations and associated infrastructure, collectively elevating material certification and welding documentation burdens. The Canadian Energy Regulator imposes comparable pressure-testing and leak-detection protocols on cross-border pipelines. Stakeholders must weigh domestic mill capacity constraints against import lead times when scheduling multi-year infrastructure commitments.
Market Dynamics
PHMSA's Mega Rule enforcement is compressing material certification timelines while Permian Basin shale operators accelerate gathering network replacement cycles, creating simultaneous demand pull and compliance friction across North American supply chains.
Growth Catalysts
- PHMSA Mega Rule integrity mandates:Mandatory traceability documentation for replacement-grade pipe is forcing system-wide inventory turnover across Texas and Louisiana transmission corridors.
- LNG export terminal construction:Gulf Coast liquefaction facilities require specialized heavy-wall large-diameter pipe for cryogenic service, drawing mill capacity from standard transmission grades.
- Appalachian shale gathering expansion:Marcellus and Utica producers are extending lateral networks into previously unserviced acreage, sustaining welded pipe demand despite commodity price volatility.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when shredded scrap spikes, constraining welded pipe pricing flexibility against seamless alternatives.
- Canadian mill concentration:Heavy-wall large-diameter capacity clusters in Western Canada, exposing buyers to cross-border tariff exposure and currency fluctuation risk.
- API 5L X80 weldability constraints:High-strength grade adoption stalls in sour service environments where hydrogen-induced cracking resistance remains unproven at scale.
Strategic Opportunities
- Carbon capture transport infrastructure:CO2 pipeline specifications favor corrosion-resistant coated pipe, opening premium product categories beyond hydrocarbon service.
- Mexico energy reform implementation:CFE and Pemex downstream modernization creates import demand for API-certified product where domestic seamless capacity is absent.
- Digital twin integration:Sensor-embedded smart pipe converges with predictive maintenance platforms, enabling lifecycle service contracts alongside commodity sales.
Industry Challenges
- Welding inspector certification backlog:PHMSA-qualified radiographic interpreters face 18-month training pipelines, delaying field joint qualification for integrity management programs.
- Fusion-bonded epoxy applicator capacity:Coating facility throughput constraints create 12-week lead time extensions for offshore and corrosive-soil specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil and Gas Line Pipe Market |
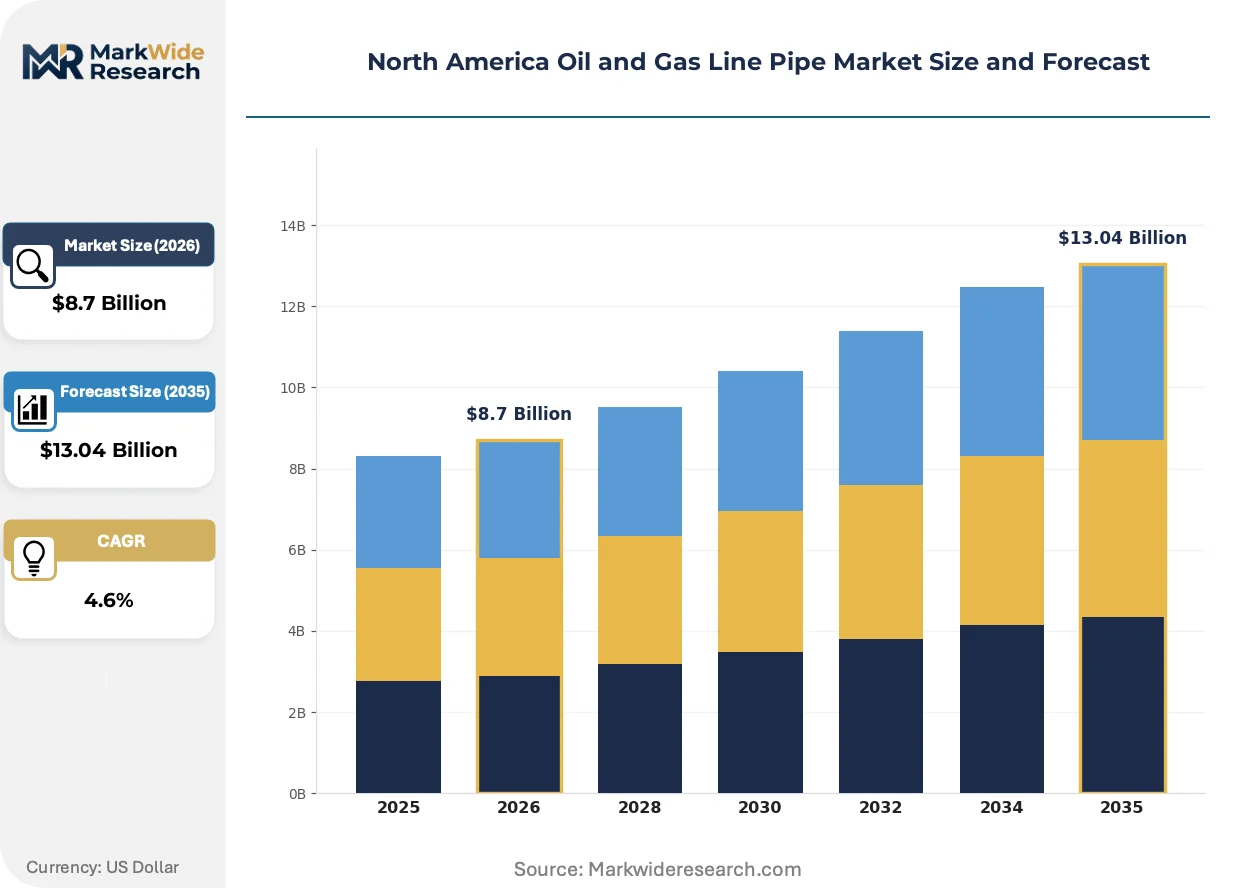
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Pipe, Welded Pipe, Coated Pipe, Casing Pipe Application: Transportation, Storage, Offshore, Onshore End User: Energy Companies, Industrial Manufacturers, Construction Firms, Environmental Agencies Size: Small Diameter, Medium Diameter, Large Diameter, Customized Size |
| Companies Covered | Tenaris SA, JFE Steel Corporation, Vallourec S.A., Welspun Group, Jindal SAW Ltd., Nippon Steel & Sumitomo Metal Corporation, ArcelorMittal S.A., U.S. Steel Tubular Products Inc., EVRAZ plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil and Gas Line Pipe Market Evolving Landscape
Digital inspection technologies and advanced metallurgy are compressing traditional quality assurance timelines while regulatory pressure elevates documentation burdens, forcing parallel investment in automation and compliance infrastructure.
Automated ultrasonic testing (AUT) systems are replacing manual radiographic inspection for girth weld qualification. Pipeline contractors in the Permian Basin deploy phased-array equipment to accelerate tie-in schedules. This technology is miniaturizing field inspection footprints, enabling single-operator deployment in remote gathering locations previously requiring multi-person crews.
PHMSA's material traceability requirements under 49 CFR Part 195 now mandate heat-level documentation from melt to final installation. Mill operators have retrofitted ERP systems to capture chemical composition data at each transformation stage. Canadian cross-border projects face equivalent Canadian Energy Regulator documentation standards, harmonizing North American compliance architectures.
Integrated service contracts now bundle pipe supply with coating, logistics, and field technical support. Midstream operators in the Appalachian Basin prefer single-source accountability over fragmented procurement of commodity pipe and third-party coating. This consolidation concentrates vendor relationships around full-service domestic mills with captive coating capacity.
North America Oil and Gas Line Pipe Market Segmentation
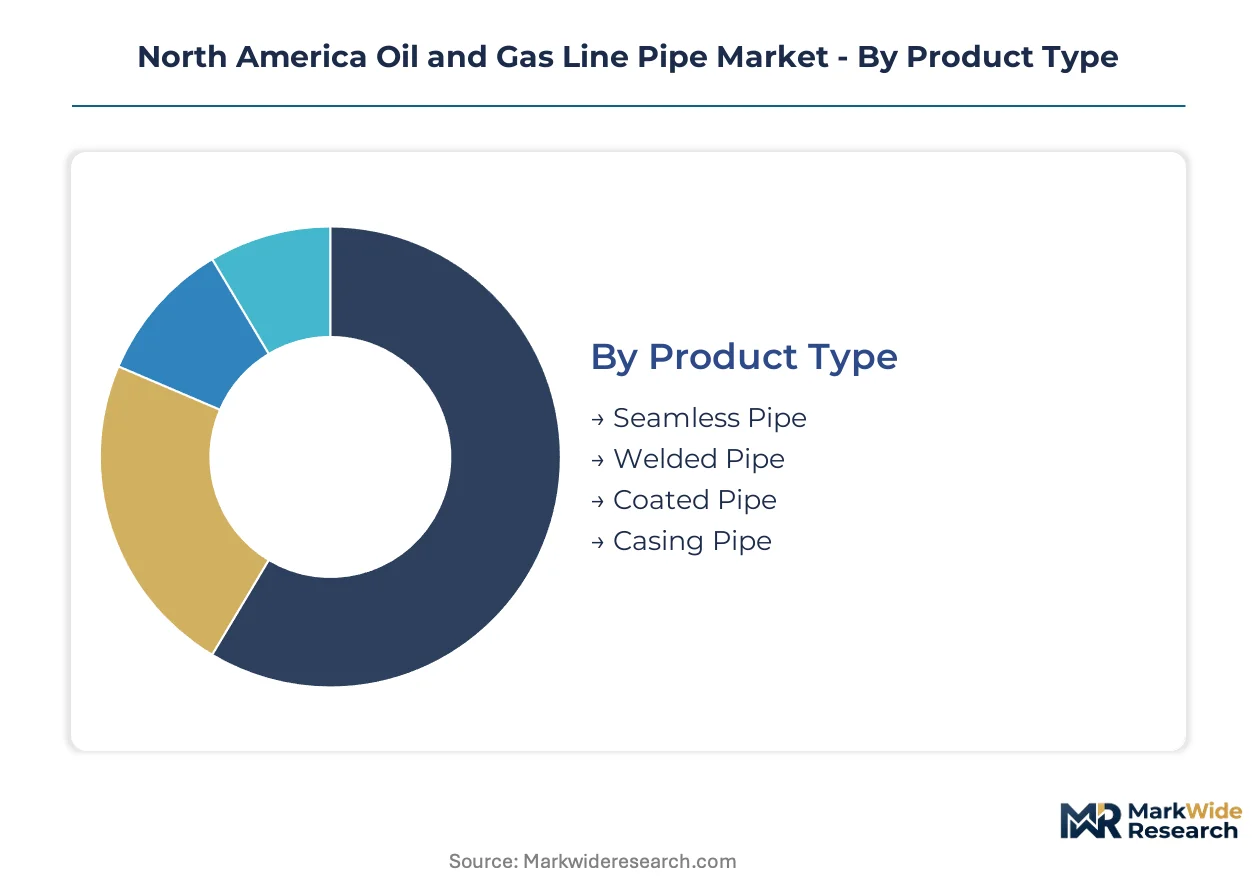
Segmentation in the North American oil and gas line pipe market reflects divergent technical requirements across pressure ratings, corrosion environments, and regulatory jurisdictions. Understanding these splits enables procurement teams to align material specifications with PHMSA integrity mandates and project-specific duty cycles.
Product Type:
Seamless pipe faces intensifying substitution pressure from advanced high-frequency welded alternatives in onshore transmission service, though sour gas applications preserve its technical premium.
- Seamless Pipe:Manufactured through rotary piercing and extrusion of solid billets to eliminate longitudinal weld seams. API 5L X80 grades serve Permian Basin high-pressure gathering systems where burst resistance outweighs cost premiums.
- Welded Pipe:Formed from hot-rolled coil via electric resistance welding or submerged arc welding processes. Texas and Louisiana replacement cycles favor welded product for standard-pressure transmission corridors under PHMSA Mega Rule timelines.
- Coated Pipe:Fusion-bonded epoxy and three-layer polyethylene barriers extend service life in corrosive soils and offshore environments.
- Casing Pipe:Structural tubulars for wellbore integrity, demand-tied to drilling activity rather than pipeline construction intensity.
Welded pipe retains volume leadership; coated pipe holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity onshore transport from engineered offshore specifications requiring enhanced fatigue resistance and cathodic protection integration.
- Transportation:Long-haul transmission pipelines moving crude oil, natural gas, and refined products between production basins and processing facilities. The Appalachian-to-Gulf Coast corridor sustains welded pipe demand for NGL takeaway capacity.
- Offshore:Subsea flowlines and riser systems demanding sour service-resistant metallurgy and heavy-wall construction. Gulf of Mexico developments specify seamless or longitudinally welded pipe with enhanced collapse resistance for deepwater pressure regimes.
- Storage:Injection and withdrawal lines for underground gas storage caverns.
- Onshore:Gathering systems, distribution networks, and terminal interconnects.
Transportation commands the largest installed base; offshore applications are climbing the fastest.
End User:
Customer type fragmentation concentrates procurement authority among integrated energy majors while industrial manufacturers fragment specifications across lower-volume specialty orders.
- Energy Companies:Integrated majors and independent producers specifying API-certified product for operated pipeline systems. Permian Basin shale operators consolidate purchasing through master service agreements with domestic mills.
- Construction Firms:Engineering-procurement-construction contractors executing turnkey pipeline projects. Appalachian Basin EPCs favor single-source pipe and coating bundles to compress project schedules.
- Industrial Manufacturers:Petrochemical facilities and refineries requiring process piping and utility lines.
- Environmental Agencies:Remediation contractors replacing legacy infrastructure under consent decrees.
Energy companies dominate procurement volume; construction firms are gaining share fastest.
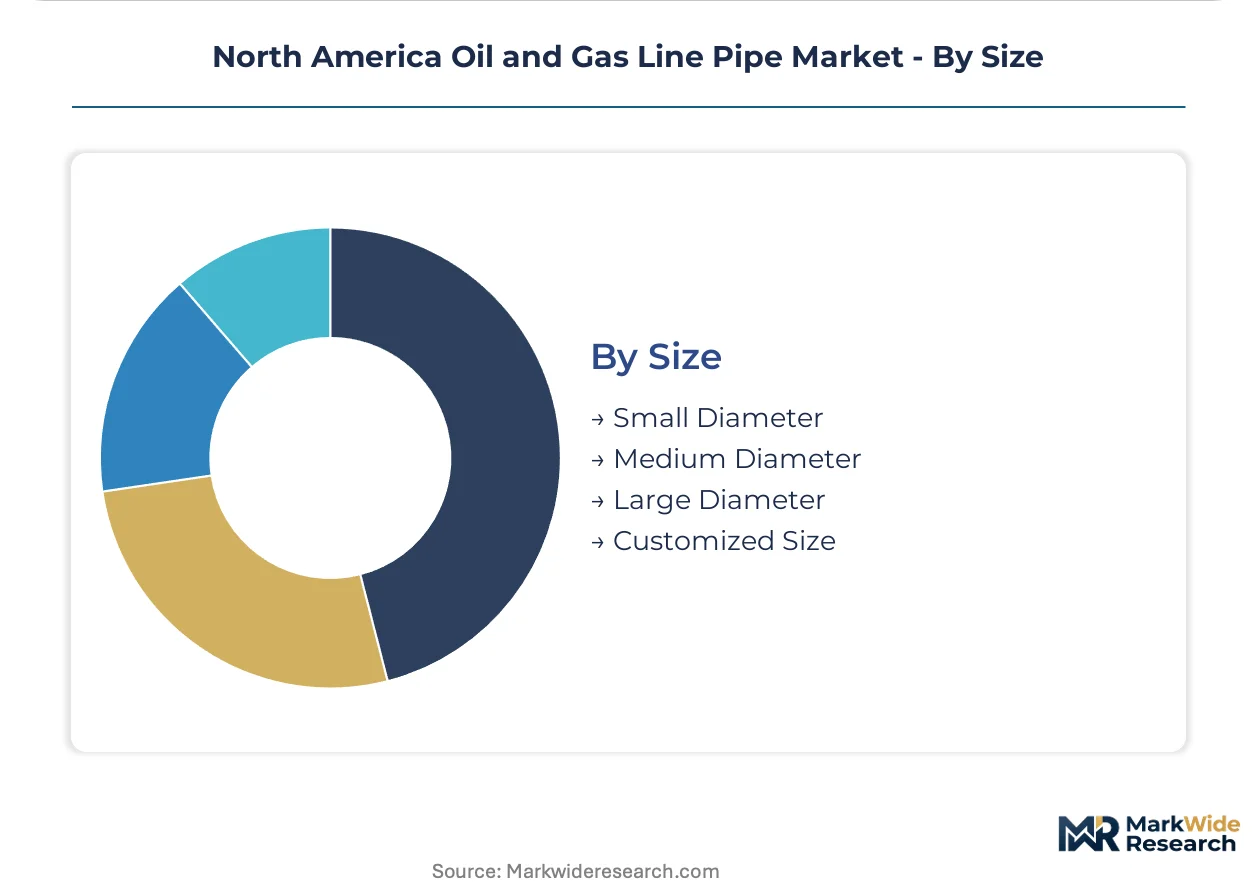
Size:
Supply concentration in heavy-wall large-diameter capacity creates procurement bottlenecks distinct from the commoditized small-diameter segment served by multiple regional mills.
- Large Diameter:Nominal pipe sizes exceeding 24 inches for mainline transmission and LNG terminal feedstock lines. Western Canadian mill capacity anchors North American supply for 36-inch and 42-inch specifications.
- Medium Diameter:8-inch to 24-inch range serving gathering system headers and lateral pipelines. Texas and Louisiana shale plays drive replacement demand in 12-inch and 16-inch grades.
- Small Diameter:Less than 8 inches for wellsite gathering and distribution laterals.
- Customized Size:Non-standard wall thicknesses and diameters for specialized process applications.
Medium diameter retains volume leadership; large diameter holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American line pipe trade flows reflect divergent domestic capacity positions across the three member economies. The United States maintains a structural import requirement for heavy-wall large-diameter specifications, while Canada exports surplus seamless and welded tonnage southward. Mexico remains a net importer of API-certified product for energy infrastructure modernization.
United States
Permian Basin shale operators in West Texas and southeastern New Mexico are accelerating gathering network replacement cycles under PHMSA Mega Rule timelines. The Pipeline and Hazardous Materials Safety Administration enforces 49 CFR Part 195 integrity standards that mandate heat-level traceability from melt to installation. Gulf Coast LNG export terminals in Texas and Louisiana draw specialized heavy-wall capacity from domestic and Canadian mills for cryogenic service lines.
Canada
Western Canadian mill capacity in Alberta and British Columbia anchors North American supply for 36-inch and 42-inch transmission specifications. The Canadian Energy Regulator imposes pressure-testing and leak-detection protocols on cross-border pipelines that harmonize with PHMSA documentation standards. EVRAZ plc operates integrated steelmaking and pipe finishing facilities in Regina and Camrose, serving heavy-wall orders for oil sands and shale plays.
Mexico
CFE and Pemex downstream modernization programs create import demand for API 5L-certified seamless and welded pipe where domestic capacity is absent. The Comisión Reguladora de Energía oversees natural gas transportation infrastructure standards that reference API specifications. Northeastern industrial corridors around Monterrey and Tampico concentrate pipeline construction activity for gas distribution network expansion.
North America Oil and Gas Line Pipe Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base organizes around three strategic archetypes: integrated steelmakers with captive pipe mills, standalone tubular specialists, and regional fabricators serving niche specifications. Scale-driven consolidation targets coating and logistics capabilities, while technology licensing agreements proliferate for automated weld inspection systems.
Among the integrated steelmaker archetype, ArcelorMittal S.A. and U.S. Steel Tubular Products Inc. occupy positions defined by backward control over raw material supply. EVRAZ plc exemplifies the transnational mill network model with facilities spanning multiple regulatory jurisdictions. Tenaris SA represents the seamless pipe specialist tier with manufacturing presence referenced in the company name. These three anchors illustrate how competitive positioning stratifies across vertical integration depth and product technology focus.
| Leading Market Players |
|---|
| Tenaris SA |
| JFE Steel Corporation |
| Vallourec S.A. |
| Welspun Group |
| Jindal SAW Ltd. |
| Nippon Steel & Sumitomo Metal Corporation |
| ArcelorMittal S.A. |
| U.S. Steel Tubular Products Inc. |
| EVRAZ plc |
| Others |
Value Network & Pricing Analysis
API 5L certification tiers gate both mill qualification and price stratification across North American line pipe procurement, compressing uncertified suppliers into commodity margins while premium-grade producers capture integrity-management premiums tied to PHMSA traceability mandates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in this market, with pricing stratifying across API 5L X70, X80, and legacy grade tiers based on certification completeness and heat-level documentation depth. Cost compression in standard welded pipe intensifies as electric arc furnace operators face shredded scrap volatility, while seamless alternatives maintain pricing power in sour service specifications. Midstream operators show lowest price sensitivity for coated pipe with captive logistics bundling, whereas independent shale producers drive hardest bargain on gathering-grade welded tonnage.
Supply Chain Analysis
Strategic stockpile preferences dominate heavy-wall large-diameter procurement as buyers buffer against Western Canadian mill concentration and cross-border tariff exposure, while just-in-time inventory governs commoditized small-diameter gathering pipe. Raw material flows draw from U.S. shredded scrap, Canadian DRI pellets, and Mexican semi-finished billet imports. Single-source vulnerability clusters in Alberta and British Columbia for 36-inch and 42-inch specifications. Distribution runs through mill-direct contracts with integrated coating and field technical support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent line pipe manufacturers face substitution pressure from composite and thermoplastic alternatives in gathering applications, requiring defensive repositioning around integrity-certification depth and full-service bundling to preserve contract renewal rates.
For Market Incumbents: Consolidate coating capacity integration and captive logistics networks to defend against fragmented regional fabricators undercutting on unbundled pipe quotes. Prioritize API 5L X80 weldability R&D investment to extend high-strength grade adoption into sour service environments where hydrogen-induced cracking resistance currently stalls market penetration. Lock in multi-year master service agreements with Permian Basin shale operators before PHMSA Mega Rule compliance costs fully transmit to procurement decisions.
For New Entrants and Emerging Players: PHMSA-qualified radiographic interpreter certification fast-tracks entry into integrity management service bundles where incumbent mills lack field joint qualification bandwidth. Target Appalachian Basin EPC contractors with single-source pipe-coating-logistics packages to exploit procurement consolidation preferences. Lead with automated ultrasonic testing equipment deployment as differentiated field technical support rather than commodity pipe margin competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heavy-wall large-diameter capacity expansions as cryogenic service specifications for Gulf Coast LNG terminals demand specialized metallurgy investments. Favor acquisition targets with captive seamless pipe capacity and Western Canadian mill network presence serving cross-border transmission corridors. Watch welding inspector certification backlog duration as inflection signal for field service margin expansion opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Capacity Integration | Captive fusion-bonded epoxy throughput compresses lead times for corrosive-soil specifications under PHMSA timelines. |
| Automated Ultrasonic Testing Deployment | Phased-array equipment accelerates girth weld qualification for Permian Basin tie-in schedules. |
| API 5L X80 Weldability R&D | Hydrogen-induced cracking resistance breakthrough unlocks sour service adoption in high-strength grades. |
| Master Service Agreement Consolidation | Multi-year commitments with shale operators lock in volume before Mega Rule compliance costs transmit. |
| Western Canadian Mill Network Expansion | Alberta and British Columbia capacity anchors North American supply for 36-inch and 42-inch transmission specifications. |
Research Methodology
Operator-level perspectives from midstream procurement directors, PHMSA compliance officers, EPC project managers, and mill sales executives anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against PHMSA enforcement records, Canadian Energy Regulator filings, FERC certificate applications, and customs trade data for steel tubular imports. Bottom-up shipment tallies by product grade and diameter triangulated against top-down infrastructure investment tracking across Texas, Louisiana, and Appalachian Basin corridors.
Sensitivity analysis framed volume and value projections across the analysis window, modeling segmentation dimensions including product type, pressure rating tier, coating specification, and end-user procurement authority. CAGRs derived from installed base replacement cycles, LNG terminal construction pipelines, and shale gathering network expansion trajectories. Forecast inputs incorporated scrap steel price volatility bands, welding inspector certification throughput constraints, and cross-border tariff exposure scenarios.
Decision-makers should treat outputs as directional under base assumptions of sustained Permian Basin production growth and PHMSA Mega Rule enforcement continuity; material deviation would warrant model refresh. Specific risk factors include composite pipe substitution acceleration in gathering applications, electric arc furnace margin collapse from shredded scrap spikes, and regulatory delays in Mexico energy reform implementation. Revision becomes warranted when welding inspector certification backlog duration crosses 24-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Natural Gas Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Upstream Services Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Global Seismic Survey Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market