
 Lithium Marine Battery Market | 2026-2036
Lithium Marine Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Marine Battery Market Insights
Marine electrochemical engineering talent scarcity is redrawing competitive boundaries in battery pack integration. Corvus Energy leverages its Norwegian project heritage to dominate offshore supply vessel electrification. Siemens Energy anchors European ferry retrofit programs through integrated drivetrain-battery packages. CATL extends its automotive cell cost structure into commercial marine volumes, competing on manufacturing scale against specialized incumbents.
A lithium marine battery is a rechargeable energy storage system employing lithium-ion electrochemistry, typically housed in IP67-rated enclosures with active thermal management, designed to deliver sustained deep-cycle discharge in saltwater environments. Its primary purpose is to replace or supplement diesel propulsion and auxiliary power generation aboard watercraft, eliminating onboard emissions and reducing acoustic signatures. LFP chemistry leads commercial vessel adoption due to thermal stability and cycle life economics, while NMC variants occupy premium yacht installations where energy density drives hull space optimization. Battery Management Systems technology represents the fastest-growing margin pool as insurers and classification societies mandate predictive fault detection and state-of-health verification before port entry clearance.
DNV classification rules, the EU Green Deal's Fit for 55 maritime package, and the International Maritime Organization's revised carbon intensity indicators are tightening propulsion system compliance thresholds across European and Asian registry fleets. These frameworks shape demand by disqualifying conventional diesel-electric retrofits from green financing facilities and zero-emission port access incentives. Stakeholders must monitor whether emerging solid-state electrolyte formulations can satisfy safety-case requirements before next-generation vessel design cycles lock in cell architecture commitments.
Market Dynamics
The EU Green Deal's Fit for 55 maritime package is compressing vessel retrofit timelines, forcing ferry operators and offshore supply fleets to commit to lithium-ion propulsion architectures before next-generation solid-state alternatives reach commercial maturity.
Growth Catalysts
- EU Green Deal maritime decarbonization mandates:Norway's fjord tourism operators face binding zero-emission requirements in heritage-protected waterways, accelerating full-electric ferry procurement.
- LFP chemistry thermal stability advantages:Commercial vessel operators prioritize cycle life economics over energy density, favoring iron phosphate cells for deep-cycle auxiliary power and propulsion systems.
- Urban ferry network electrification:Copenhagen, Amsterdam, and Stockholm harbor authorities now condition port access fees on battery-electric propulsion certification.
Market Restraints
- Cell supply concentration in East Asian manufacturing:European pack integrators remain dependent on imported cylindrical and prismatic cells, exposing project margins to shipping cost volatility and currency fluctuation.
- DNV classification compliance costs:Predictive fault detection and state-of-health verification requirements for Battery Management Systems add certification overhead that disqualifies smaller vessel operators from retrofit financing.
- Diesel-electric hybrid persistence:Long-haul cargo operators continue specifying dual-fuel architectures for transoceanic routes where charging infrastructure gaps persist.
Strategic Opportunities
- Swedish archipelago short-sea shipping:Island-hopping cargo routes under 50 nautical miles remain underpenetrated by full-electric solutions due to fragmented ownership structures and municipal procurement silos.
- IMO carbon intensity indicator tightening:The revised CII framework creates regulatory tailwinds for battery-hybrid retrofits that improve vessel efficiency ratings ahead of 2025 enforcement thresholds.
- Digital twin integration with predictive maintenance:Convergence of vessel operational data platforms and cell degradation modeling enables insurers to price risk differentially for monitored versus unmonitored battery systems.
Industry Challenges
- Marine electrochemical engineering talent scarcity:Pack integration specialists capable of saltwater corrosion mitigation and active thermal management design command premium compensation that compresses integrator margins.
- Legacy vessel hull space constraints:Retrofit projects face structural modification costs when original diesel tank volumes cannot accommodate equivalent energy capacity in lithium-ion form factors.
- Multi-stakeholder certification coordination:Classification society approval, flag state verification, and port authority clearance timelines often misalign, delaying revenue service dates for completed installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Marine Battery Market |
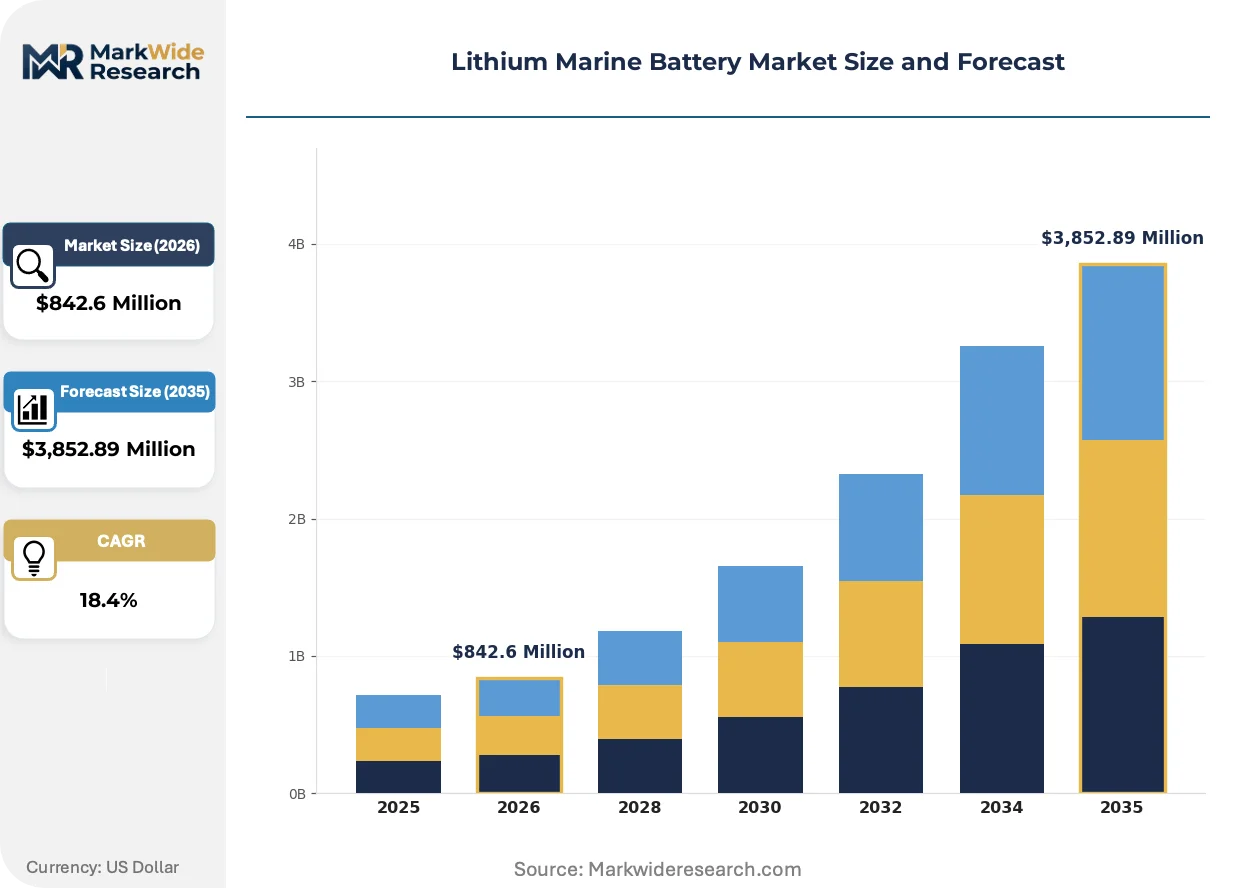
| Market Size in 2026 | $842.6 Million |
| Market Size in 2035 | $3,852.89 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Leisure Boats, Commercial Vessels, Military Crafts, Yachts Battery Type: LFP, NMC, NCA, LTO End User: Fleet Operators, Shipbuilders, Marine Enthusiasts, Government Agencies Technology: Energy Storage Systems, Battery Management Systems, Hybrid Systems, Charging Solutions |
| Companies Covered | Corvus Energy, Siemens Energy, Leclanché SA, CATL, Victron Energy, ABB, Wärtsilä, Kongsberg Gruppen, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Marine Battery Market Trends and Innovations
Electrification architecture decisions are locking in before solid-state electrolyte commercialization, creating a window where incumbent lithium-ion formats must defend their installed base through service lifecycle contracts rather than cell performance advantages.
Solid-state battery development is fragmenting the R&D commitment strategies of major maritime battery integrators. Corvus Energy and Siemens Energy have diverged on whether to pursue sulfide-based or oxide-based electrolyte pathways for next-generation vessel programs. Norwegian offshore supply vessel operators are piloting hybrid solid-state demonstrators while deferring fleet-wide commitments until thermal runaway test protocols mature. This technology uncertainty is fragmenting capital allocation between near-term LFP volume expansion and longer-dated solid-state production tooling.
The EU Green Deal's Fit for 55 maritime package is tightening propulsion system compliance thresholds across European registry fleets. Green financing facilities now exclude conventional diesel-electric retrofits from eligibility, redirecting capital toward full-electric or hydrogen-hybrid architectures. German and Dutch ferry operators are responding by consolidating procurement into multi-vessel framework agreements that lock in battery supply before 2027 certification deadlines.
Charter contracts are increasingly specifying zero-emission operational capability as a threshold qualification rather than a price premium factor. Offshore wind service vessel operators in the North Sea now face charterer mandates for battery-electric or hydrogen fuel cell propulsion that displace traditional diesel-mechanical specifications. This buyer concentration is most visible in Denmark's Esbjerg port cluster, where wind farm developers coordinate vessel pooling agreements that standardize electrification requirements across competing service providers.
Lithium Marine Battery Market Segmentation
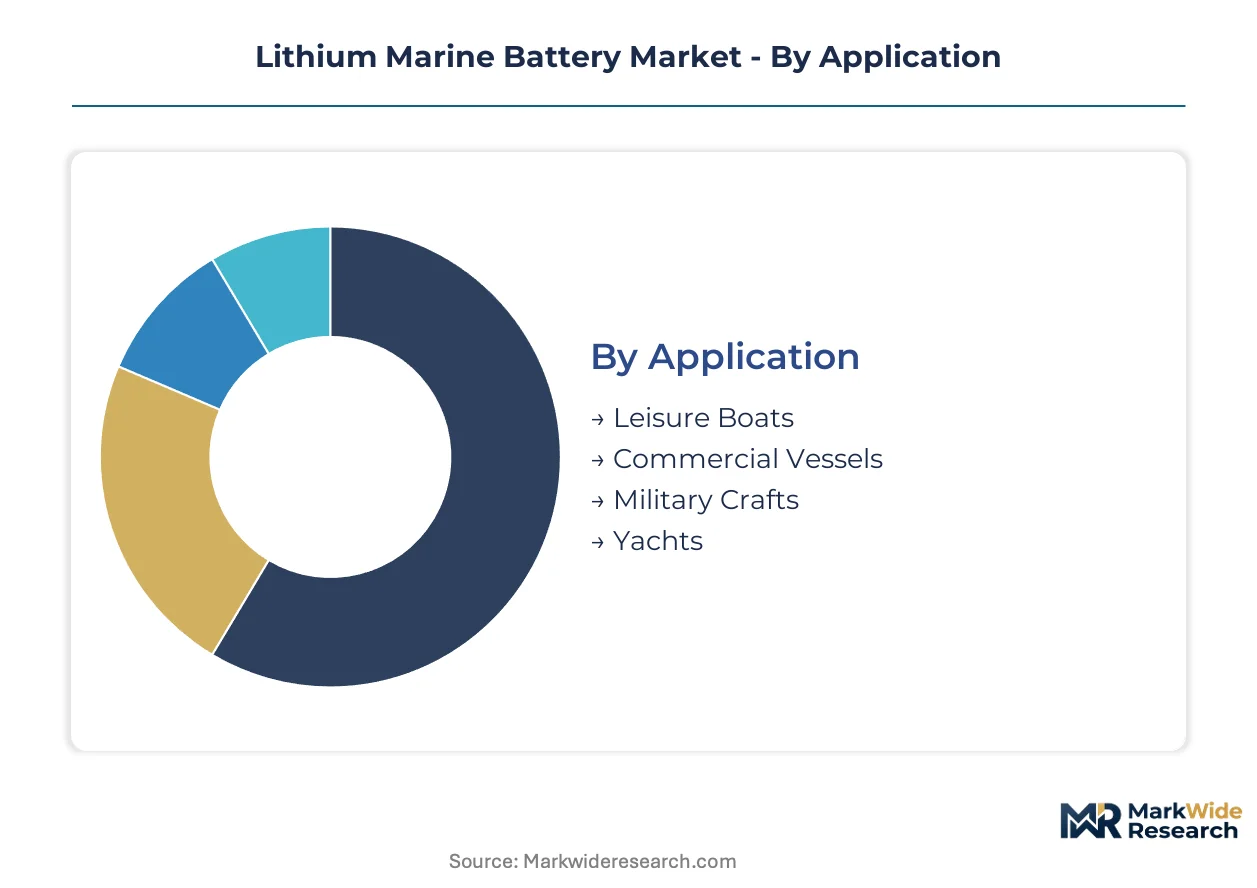
Segmentation in the lithium marine battery market reveals divergent procurement patterns across vessel types and operator profiles. Battery chemistry selection, system architecture, and end-user sophistication create distinct margin pools that reward specialized integration capabilities over commodity cell supply.
Application:
Commercial demand concentrates in Northern European ferry networks, while leisure applications show broader geographic dispersion across Mediterranean and Southeast Asian marinas.
- Commercial Vessels:These systems employ LFP chemistry in IP67-rated enclosures with active liquid cooling, designed for 6,000+ cycle lifespans. Norwegian fjord ferry operators and Danish offshore wind service fleets drive procurement volumes as EU Green Deal mandates compress retrofit timelines.
- Leisure Boats:Day-cruisers and weekend vessels under 12 meters dominate this segment, typically specifying NMC pouch cells for weight-sensitive hull designs. Demand clusters in Italian, Croatian, and Turkish coastal marinas where diesel outboard bans are proliferating.
- Yachts:Superyacht installations prioritize energy density for auxiliary hotel loads and silent anchoring operations.
- Military Crafts:Special operations vessels require low-acoustic-signature propulsion with electromagnetic interference shielding.
Commercial Vessels holds the largest share; momentum sits with Leisure Boats.
Battery Type:
Cost tiers separate thermal-stable iron phosphate from energy-dense nickel chemistries, with cycle life economics driving commercial adoption decisions.
- LFP:Lithium iron phosphate cells dominate ferry and workboat specifications due to thermal runaway resistance and flat discharge curves. Norwegian integrators specify these for heritage waterway operations where safety-case documentation faces heightened regulatory scrutiny.
- NMC:Nickel manganese cobalt variants command premium positioning in yacht and high-performance craft where volumetric energy density determines hull space allocation.
- NCA:Nickel cobalt aluminum formulations occupy niche military and racing applications.
- LTO:Lithium titanate batteries serve harbor tug and short-cycle ferry routes requiring 15-minute fast charging capability.
LFP captures the dominant installed base; NMC is expanding most quickly in premium installations.
End User:
Procurement sophistication varies sharply between institutional fleet operators and individual marine enthusiasts, creating divergent sales channel requirements.
- Fleet Operators:Urban ferry authorities in Copenhagen, Amsterdam, and Stockholm coordinate multi-vessel framework agreements with integrated drivetrain-battery packages. These buyers mandate predictive maintenance interfaces and classification society pre-certification.
- Shipbuilders:New-construction yards in Germany and the Netherlands specify battery systems during hull design phase, enabling optimized weight distribution and thermal management integration.
- Marine Enthusiasts:Individual boat owners purchase through distributor networks with installation support.
- Government Agencies:Coast guard and naval procurement programs emphasize electromagnetic compatibility and shock resistance.
Fleet Operators command the largest contract values; Shipbuilders show the steepest expansion trajectory as new-build electrification accelerates.
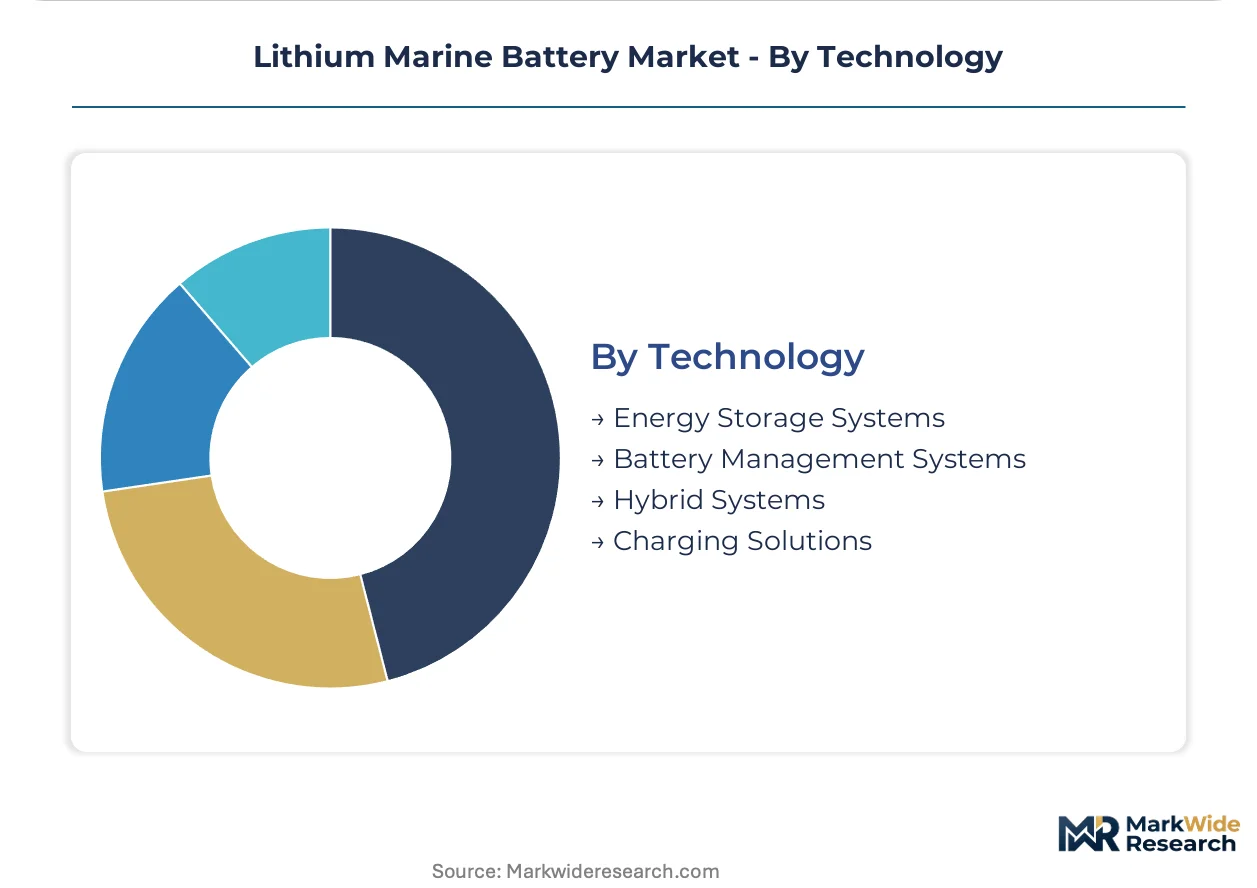
Technology:
Margin pools are concentrating in software-defined systems that enable insurer-mandated state-of-health verification and predictive fault detection.
- Battery Management Systems:These platforms integrate cell balancing, thermal regulation, and predictive analytics to satisfy DNV classification requirements for port entry clearance. Norwegian and German insurers now price coverage differentially based on monitored versus unmonitored installations.
- Energy Storage Systems:Pack-level integration of cells, thermal management, and safety enclosures constitutes the core hardware value.
- Hybrid Systems:Diesel-electric architectures persist in long-haul cargo applications where charging infrastructure gaps remain.
- Charging Solutions:Shore power interfaces and vessel-to-grid capabilities enable overnight depot charging for ferry fleets.
Energy Storage Systems represents the revenue base; Battery Management Systems is gaining share fastest as regulatory compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian pack integrators command 15-20% price premiums over East Asian cell suppliers, while German ferry operators absorb certification overhead that compresses margins for smaller Mediterranean yards. This pricing-power asymmetry shapes procurement patterns across coastal Europe and East Asian manufacturing hubs.
Norway
Fjord tourism operators and offshore supply vessel fleets drive concentrated demand for LFP-based propulsion systems. The EU Green Deal's Fit for 55 maritime package mandates zero-emission operations in heritage-protected waterways by 2026. Bergen and Stavanger harbor clusters anchor battery pack integration facilities serving North Sea electrification programs.
Germany
Urban ferry authorities in Hamburg and Kiel coordinate multi-vessel framework agreements for integrated drivetrain-battery packages. The country's national maritime regulator enforces DNV-aligned classification rules for predictive fault detection systems. Bremerhaven and Rostock shipyards specialize in new-construction electrification with optimized thermal management integration.
Netherlands
Amsterdam harbor authority conditions port access fees on battery-electric propulsion certification, accelerating retrofit commitments. REACH regulations govern cell import compliance and recycling obligations for pack integrators. Rotterdam's offshore wind service vessel cluster standardizes electrification requirements through developer-coordinated pooling agreements.
China
CATL extends automotive cell cost structures into commercial marine volumes, competing on manufacturing scale against specialized European incumbents. The country's Ministry of Industry and Information Technology oversees dual carbon goals affecting export-oriented battery production. Ningbo and Shenzhen manufacturing hubs supply cylindrical and prismatic cells to European pack integrators.
Sweden
Island-hopping cargo routes under 50 nautical miles remain underpenetrated by full-electric solutions due to fragmented ownership structures. The Swedish Transport Agency coordinates zero-emission pilot programs for archipelago short-sea shipping. Gothenburg's ferry network and Stockholm's urban waterway operators consolidate procurement through municipal framework agreements.
Lithium Marine Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where specialized integrators defend premium positioning against scale-driven cell suppliers. The vendor base separates into three strategic archetypes: Norwegian heritage integrators with project execution capabilities, German-Swiss industrial conglomerates offering integrated drivetrain packages, and Chinese cell manufacturers extending automotive cost structures. Dominant competitive moves include multi-vessel framework agreements that lock in supply before certification deadlines, and service lifecycle contracts that defend installed bases against next-generation solid-state alternatives.
Among Norwegian heritage integrators, Corvus Energy occupies a position exemplifying offshore supply vessel electrification expertise, while Kongsberg Gruppen represents the industrial systems integration archetype. German-Swiss industrial conglomerates include Siemens Energy, which anchors European ferry retrofit programs, and ABB, sitting within the power electronics and marine automation tier. These named companies serve as anchors for understanding how geographic project heritage and integrated system capabilities shape competitive positioning without specifying individual strategic actions or financial performance.
| Leading Market Players |
|---|
| Corvus Energy |
| Siemens Energy |
| Leclanché SA |
| CATL |
| Victron Energy |
| ABB |
| Wärtsilä |
| Kongsberg Gruppen |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cell inventory cycles at European pack integrators signal how supply-chain distance from East Asian manufacturing nodes translates directly into pricing power erosion for regional assemblers facing volatile freight rates and currency exposure.
Pricing Analysis
Configured-to-order pricing for heritage waterway ferry retrofits commands spreads of 35-50% above standard catalog systems for harbor workboats, with DNV certification grade and active thermal management complexity as the primary differentiation drivers. Cost compression in standard LFP pack tiers is intensifying because CATL's automotive cell cost structures are extending into commercial marine volumes. Fleet operators in Copenhagen and Amsterdam show lowest price sensitivity due to EU Green Deal compliance deadlines, while individual leisure boat owners in Mediterranean marinas exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
China and South Korea anchor cylindrical and prismatic cell fabrication for marine battery systems, with Japan contributing specialized electrolyte formulations and separator membranes. European pack integrators draw from imported NMC and LFP cells, graphite anode materials, and copper current collectors. Single-source vulnerability concentrates in cathode active material supply from integrated Chinese mining-refining complexes. Distribution runs through Bremerhaven and Rotterdam port clusters for just-in-time delivery to Norwegian and German integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium marine battery market sits in early-cycle expansion as EU Green Deal mandates force vessel retrofit commitments before solid-state alternatives mature, creating a window where incumbent lithium-ion formats must defend through service lifecycle contracts.
For Market Incumbents: Compound project execution capabilities in Norwegian fjord heritage waterways to lock in multi-vessel framework agreements before certification deadlines. Deepen backward integration into Battery Management Systems software to capture insurer-mandated predictive analytics margins that emerging Chinese cell suppliers cannot replicate. Solid-state electrolyte uncertainty threatens near-term LFP volume commitments.
For New Entrants and Emerging Players: Anchor in Swedish archipelago short-sea shipping routes under 50 nautical miles, where fragmented municipal ownership structures have delayed full-electric adoption despite technical feasibility. Target island-hopping cargo operators with modular LFP pack architectures that minimize hull modification costs. Pursue vessel-pooling agreement participation through Esbjerg port cluster coordination.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with stranded marine battery divisions lacking integrated drivetrain capabilities. Five-to-ten year viability hinges on classification society pre-certification relationships and service lifecycle contract backlogs. Monitor solid-state thermal runaway test protocol maturation as inflection signal for next-generation capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vessel Framework Agreements | Locks battery supply before EU Green Deal certification deadlines for German ferry operators. |
| Battery Management Systems Certification | Satisfies DNV predictive fault detection requirements for port entry clearance in Norwegian waters. |
| Backward Integration into Cell Assembly | Reduces exposure to East Asian shipping cost volatility for European pack integrators. |
| Digital Twin Platform Development | Enables insurer risk differentiation for monitored versus unmonitored battery installations. |
| Solid-State Electrolyte R&D Partnership | Positions for next-generation vessel design cycles before architecture lock-in occurs. |
Research Methodology
A spread of perspectives from ferry fleet procurement directors, marine classification surveyors, battery pack integration engineers, and port authority electrification officers converged on the working assumptions that shaped this analysis. Primary fieldwork combined structured interviews with secondary validation through DNV classification rule filings, EU Green Deal maritime package documentation, and customs trade data for lithium-ion cell imports. Bottom-up vessel retrofit project pipelines and top-down regulatory mandate timelines were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled include vessel type, battery chemistry, end-user procurement sophistication, and technology integration level across the analysis window. CAGRs were derived from regression analysis against regulatory enforcement schedules and fleet replacement cycles. Forecast inputs incorporated charging infrastructure deployment timelines and insurer coverage pricing differentials for monitored battery systems.
Underlying assumptions cover solid-state electrolyte commercialization delays and EU Green Deal enforcement continuity, with deviation risk concentrated in East Asian export restriction policies and charter contract zero-emission clause standardization. Recalibration cycles align with material shifts in IMO carbon intensity indicator enforcement thresholds and breakthrough announcements in thermal runaway mitigation protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
East Africa Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Portable Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
Inverter Battery Market
Batteries
Southeast Asia Battery Market
Batteries
India Rechargeable Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Europe Rechargeable Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Micro Mobility Battery PACK Market
Batteries
North America NMC Battery Pack Market
Batteries
PVT Battery Panel Market
Batteries
Molten Salt Battery Market
Batteries
India Battery Market