
 Printed Batteries Market | 2026-2036
Printed Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Batteries Market Intelligence
High-energy-density printed cell specifications are reorganizing competitive tiers as manufacturers race to replace conventional coin cells in space-constrained electronics. Samsung SDI leverages its display-panel heritage to dominate roll-to-roll electrode fabrication. Enfucell anchors Nordic medical patch deployments with zinc-manganese formulations optimized for skin-contact wearables. Blue Spark Technologies differentiates through proprietary silver-oxide chemistries that sustain stable voltage across extreme temperature swings.
Printed batteries are electrochemical energy devices fabricated through additive manufacturing techniques such as screen-printing or inkjet deposition of active materials onto flexible polymer substrates, typically achieving thicknesses below one millimeter to serve applications where mechanical compliance matters more than absolute capacity. Flexible batteries occupy the largest addressable position because they bridge wearable electronics and smart packaging with minimal retooling of existing production lines. Rechargeable configurations represent the fastest-expanding margin pool as IoT sensor networks demand cycle durability beyond the disposable alternative.
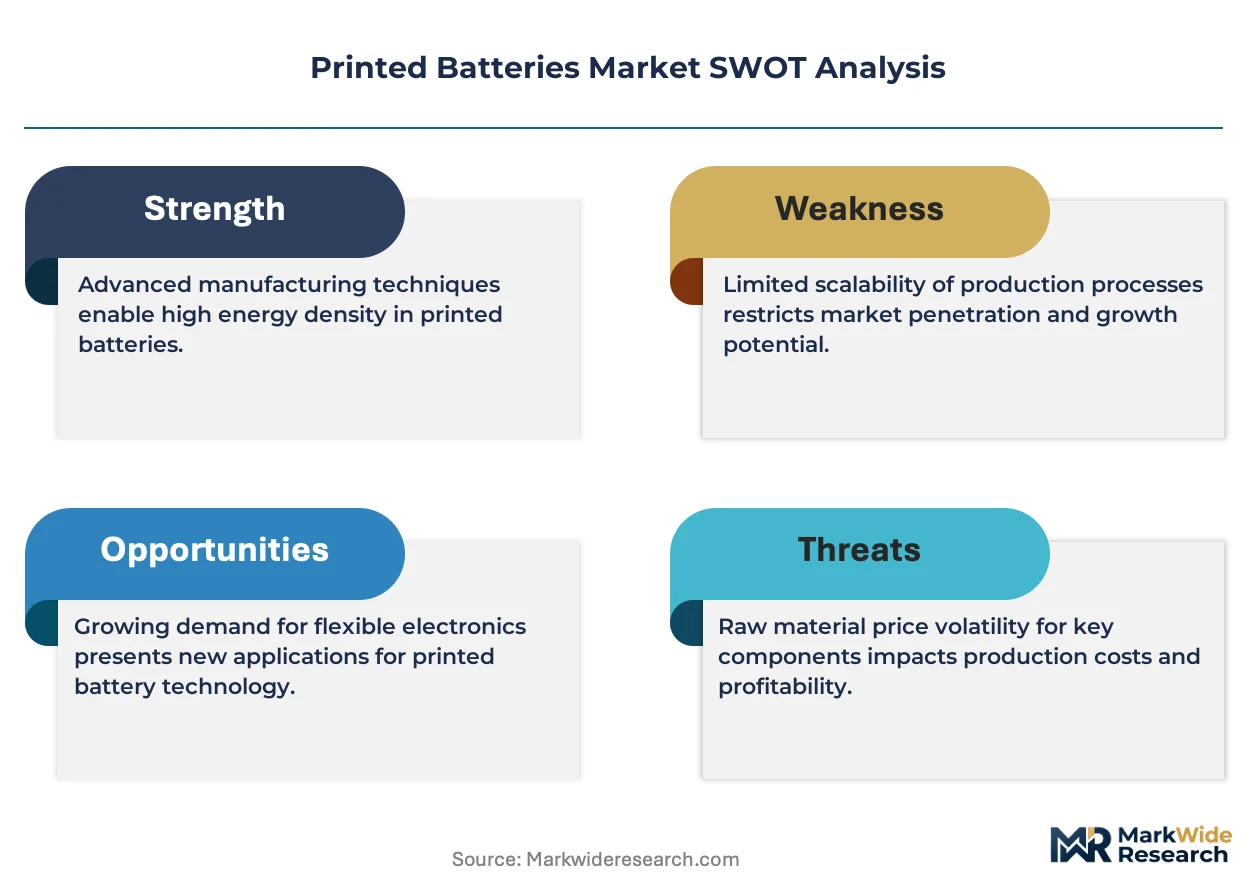
FDA biocompatibility standards govern medical device integrations in the United States, while REACH chemical restrictions in Europe constrain heavy-metal content in conductive inks sold across member states. The EU Battery Directive's forthcoming due-disclosure rules are forcing non-European suppliers to requalify material sourcing or forfeit access to healthcare procurement channels. Stakeholders must monitor how solid-state electrolyte patents and regional recycling mandates converge to reshape which chemistries achieve commercial scale.
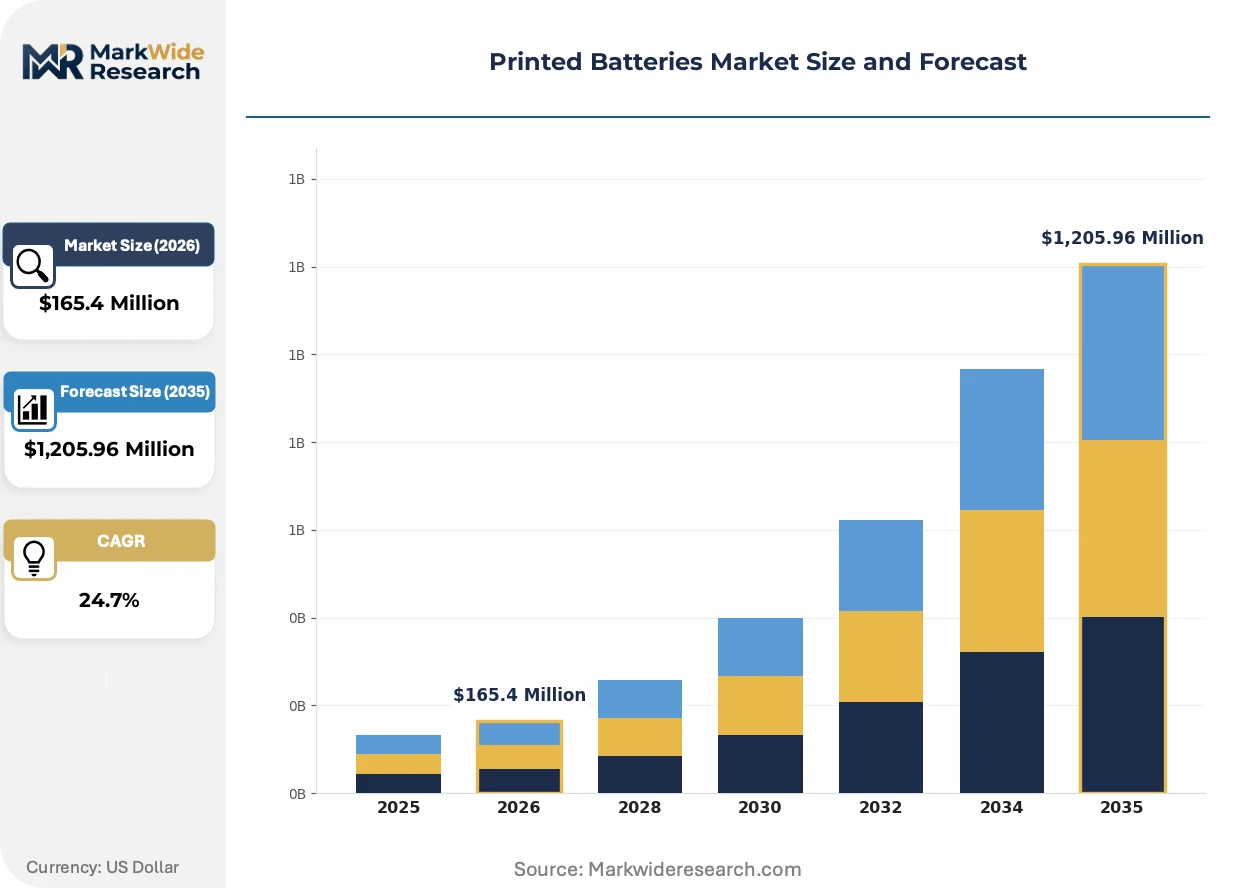
Market Dynamics
The EU Battery Directive's heavy-metal elimination mandates are forcing printed battery suppliers to requalify entire material streams, compressing formulation cycles and redrawing competitive tiers around REACH-compliant chemistries.
Growth Catalysts
- Wearable device procurement:Samsung SDI and domestic Korean materials suppliers anchor a vertically integrated cluster that accelerates roll-to-roll electrode fabrication for skin-contact electronics.
- REACH chemical restrictions:European conductive ink suppliers are eliminating cadmium and lead from formulations, opening procurement channels to healthcare device integrators previously blocked by biocompatibility barriers.
- Rechargeable configuration demand:IoT sensor networks require cycle durability beyond disposable alternatives, pulling capital toward solid-state electrolyte development.
Market Restraints
- Silver oxide cost volatility:Precious metal price swings compress margins for stable-voltage chemistry specialists serving temperature-sensitive applications.
- South Korean supply concentration:Display-panel heritage capabilities cluster around Seoul-Incheon corridor, creating single-point vulnerability for electrode substrate sourcing.
- Energy density ceiling:Zinc-manganese formulations hit theoretical limits below lithium-ion equivalents, constraining medical patch runtime specifications.
Strategic Opportunities
- Nordic medical patch expansion:Finland and Sweden present underpenetrated demand for disposable zinc-manganese cells in continuous glucose monitoring applications.
- EU due-disclosure rules:The Battery Directive's forthcoming supply chain transparency mandates create first-mover advantage for suppliers with pre-qualified conflict-mineral-free material streams.
- Solid-state electrolyte convergence:Polymer-ceramic composite deposition techniques promise to bridge the gap between printed manufacturing scalability and lithium-metal energy density.
Industry Challenges
- Roll-to-roll technician scarcity:Screen-printing precision at sub-millimeter thickness requires specialized workforce training programs that Korean technical institutes have not yet scaled.
- FDA 510(k) timeline compression:Biocompatibility documentation for skin-contact wearables extends certification cycles, delaying revenue recognition for new formulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Batteries Market |
| Market Size in 2026 | $165.4 Million |
| Market Size in 2035 | $1,205.96 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Batteries, Thin-film Batteries, Rechargeable Batteries, Disposable Batteries Application: Wearable Devices, Smart Packaging, Medical Devices, Internet of Things Technology: Electrochemical, Conductive Ink, Organic Substrates, Nanotechnology End User: Consumer Electronics, Healthcare Providers, Automotive, Industrial Equipment |
| Companies Covered | Enfucell, Samsung SDI, Molex, Blue Spark Technologies, BrightVolt, Cymbet Corporation, Ultralife Corporation, STMicroelectronics, Imprint Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Batteries Market Strategic Shifts & Innovations
Printed battery manufacturing is pivoting from batch screen-printing toward continuous roll-to-roll deposition, compressing unit economics and enabling substrate formats previously incompatible with conventional cell assembly.
Silver-zinc rechargeable chemistries are displacing primary silver-oxide configurations in temperature-extreme logistics sensors. Cold-chain monitoring device manufacturers in Germany and the Netherlands are adopting these formulations for warehouse-to-last-mile tracking. The chemistry shift is displacing established Japanese coin-cell suppliers from European pharmaceutical distribution contracts.
REACH Annex XVII restrictions on nickel compounds are forcing reformulation of conductive pastes used in medical-grade flexible batteries. The European Chemicals Agency's 2023 update expanded substance restrictions to cover cobalt and nickel in skin-contact applications. Nordic patch manufacturers are accelerating qualification of carbon-based conductive alternatives to maintain CE marking eligibility.
Direct procurement from materials suppliers is fragmenting traditional distributor channels for printed battery substrates. Large wearable OEMs in South Korea are establishing captive ink formulation partnerships, bypassing regional component distributors. This channel compression is most visible in Seoul's Pangyo tech cluster, where Samsung SDI maintains direct technical collaboration with domestic polymer substrate specialists.
Printed Batteries Market Segmentation
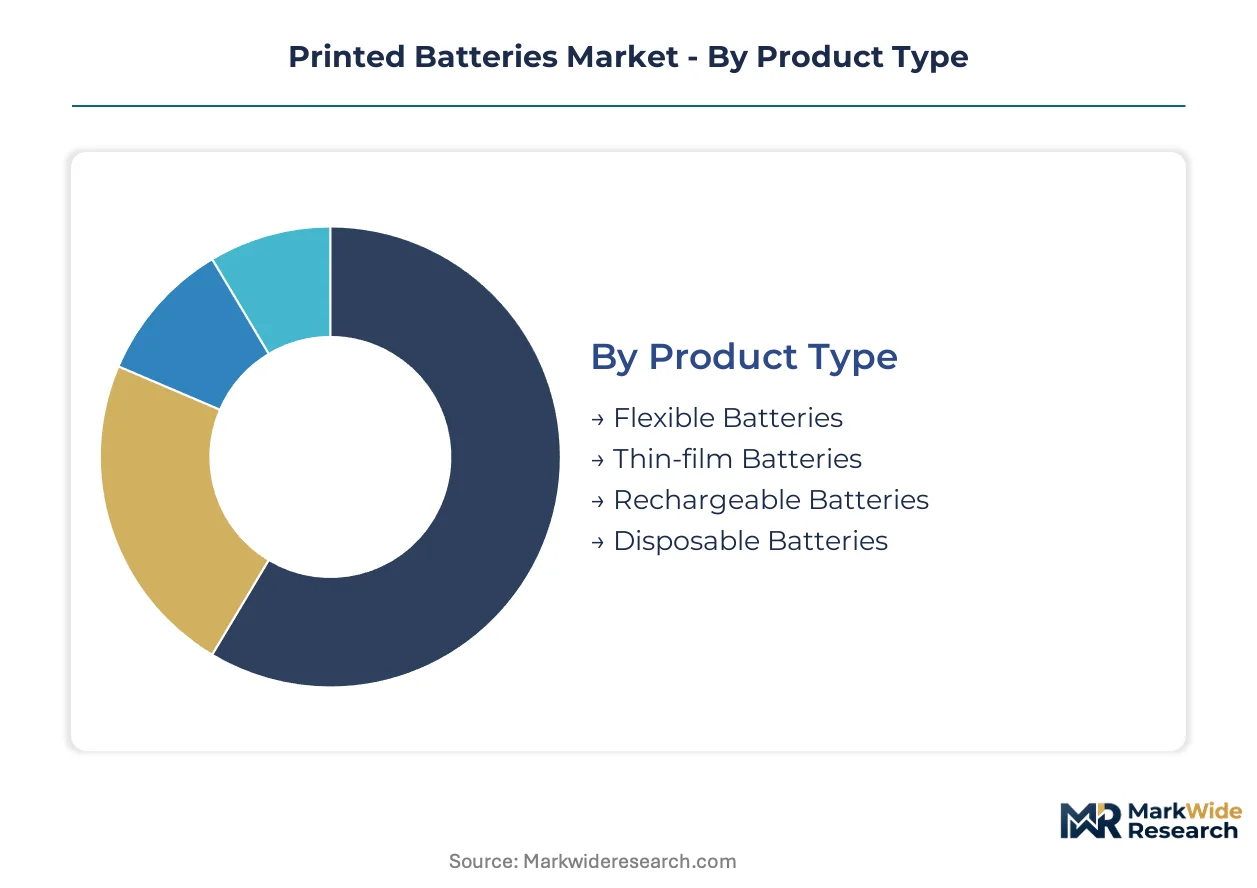
Printed battery manufacturers configure production lines around substrate flexibility, rechargeability, and application-specific power profiles. Segment boundaries blur as electrochemical innovations migrate across product categories and end-use specifications.
Product Type:
Flexible batteries face the most acute substitution pressure from conventional lithium-polymer cells in consumer electronics, while thin-film architectures carve defensible niches in space-constrained medical applications.
- Flexible Batteries:Polymer substrate architectures achieve sub-millimeter thickness through roll-to-roll electrode deposition. Demand concentrates in South Korean wearable OEM supply chains, where Samsung SDI leverages display-panel heritage to compress fabrication costs for skin-contact electronics.
- Thin-film Batteries:Vacuum-deposited solid-state layers eliminate liquid electrolyte packaging overhead. Medical patch manufacturers in Finland and Sweden specify these for continuous glucose monitoring where mechanical compliance outweighs absolute capacity.
- Rechargeable Batteries:Silver-zinc and emerging solid-state chemistries target IoT sensor networks requiring cycle durability.
- Disposable Batteries:Zinc-manganese formulations dominate single-use medical diagnostics and smart packaging.
Flexible batteries retain volume leadership; rechargeable configurations hold the steepest expansion curve.
Application:
Cost tier stratification separates premium medical device integrations from commodity smart packaging volumes.
- Wearable Devices:FDA biocompatibility documentation and REACH skin-contact restrictions govern material selection. Korean manufacturers accelerate procurement of ultra-thin power cells for fitness bands and hearables.
- Smart Packaging:Unit economics demand the lowest cost-per-cell in the addressable market. Cold-chain pharmaceutical logistics in Germany and the Netherlands drive silver-zinc adoption for temperature-extreme tracking.
- Medical Devices:Nordic patch deployments favor zinc-manganese for disposable diagnostics.
- Internet of Things:Distributed sensor networks pull capital toward solid-state electrolyte development for cycle durability.
Wearable devices retain volume leadership; IoT applications hold the steepest expansion curve.
Technology:
Supply concentration in conductive ink formulation creates margin pressure for electrochemical specialists without captive materials partnerships.
- Electrochemical:Established redox chemistries including zinc-manganese and silver-oxide dominate commercial production. Seoul-Incheon corridor suppliers anchor vertically integrated electrode fabrication.
- Conductive Ink:Carbon-based alternatives displace nickel and cobalt formulations under REACH Annex XVII restrictions. European suppliers reformulate pastes to maintain CE marking eligibility.
- Organic Substrates:Biodegradable polymer research targets EU Battery Directive sustainability mandates.
- Nanotechnology:Polymer-ceramic composite electrolytes promise lithium-metal energy density with printed manufacturing scalability.
Electrochemical retains volume leadership; nanotechnology holds the steepest expansion curve.
End User:
Customer type determines certification burden and pricing power, with healthcare procurement imposing the strictest qualification timelines.
- Consumer Electronics:Large OEMs establish direct ink formulation partnerships, bypassing regional distributors. Pangyo tech cluster activity demonstrates channel compression in Korean supply chains.
- Healthcare Providers:FDA 510(k) timelines and EMA medical device regulations extend certification cycles. Biocompatibility documentation delays revenue recognition for new formulation launches.
- Automotive:Temperature-extreme specifications favor stable-voltage silver-oxide chemistries.
- Industrial Equipment:Logistics sensor networks demand cycle durability beyond disposable alternatives.
Consumer electronics retains volume leadership; healthcare providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in printed batteries tilt heavily toward export surplus in East Asian manufacturing hubs, while European and North American markets absorb volumes through healthcare and IoT procurement channels. Import dependency for conductive inks and specialized polymer substrates concentrates in Germany and the United States, where domestic electrode fabrication remains limited.
South Korea
Seoul-Incheon corridor manufacturers command roll-to-roll electrode fabrication for wearable OEM supply chains. MFDS biocompatibility guidelines shape skin-contact material selection for medical patch exports. Pangyo tech cluster hosts direct partnerships between display-panel heritage fabricators and domestic polymer substrate specialists, compressing distributor channels.
United States
FDA 510(k) certification timelines govern medical device integration demand from Boston and Minneapolis healthcare technology clusters. EPA chemical reporting requirements for imported conductive inks add qualification overhead to European and Asian material sourcing. Silicon Valley IoT sensor developers pull silver-zinc rechargeable volumes for logistics network deployments.
Germany
Cold-chain pharmaceutical logistics operators in Munich and Hamburg drive silver-zinc adoption for warehouse-to-last-mile temperature tracking. REACH Annex XVII restrictions on nickel and cobalt compounds force reformulation of medical-grade conductive pastes. Dresden and Stuttgart industrial sensor manufacturers anchor solid-state electrolyte qualification programs.
Finland
Nordic continuous glucose monitoring patch developers specify zinc-manganese disposable cells for skin-contact applications. ECHA compliance documentation requirements filter non-European suppliers from healthcare procurement channels. Espoo and Tampere medical technology clusters concentrate Enfucell-anchored supply relationships for single-use diagnostics.
Japan
Tokyo and Osaka wearable electronics OEMs accelerate procurement of ultra-thin power cells for hearables and fitness bands. METI technology roadmaps prioritize solid-state electrolyte development for cycle durability specifications. Kyoto materials research institutes collaborate with domestic ink formulators on carbon-based conductive alternatives to heavy-metal pastes.
Printed Batteries Market Key Industry Players
Listed leaders compete with private specialists across electrode fabrication scale and formulation chemistry depth. The vendor base separates into three tiers: display-panel heritage conglomerates with captive roll-to-roll capacity, Nordic medical patch specialists with zinc-manganese skin-contact expertise, and venture-backed solid-state electrolyte developers. Strategic moves concentrate on backward integration into conductive ink formulation and direct OEM partnerships that bypass regional distribution channels.
Within the display-panel heritage tier, Samsung SDI exemplifies scale-driven electrode fabrication anchored in Seoul manufacturing corridors. Among Nordic medical patch specialists, Enfucell occupies a position exemplifying zinc-manganese formulation optimization for disposable diagnostics. Blue Spark Technologies represents the stable-voltage chemistry archetype serving temperature-extreme applications through proprietary material approaches.
| Leading Market Players |
|---|
| Enfucell |
| Samsung SDI |
| Molex |
| Blue Spark Technologies |
| BrightVolt |
| Cymbet Corporation |
| Ultralife Corporation |
| STMicroelectronics |
| Imprint Energy |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for conductive inks tether pricing power to Seoul-Incheon corridor electrode fabrication capacity. Korean display-panel heritage manufacturers compress unit economics through captive polymer substrate partnerships, while European buyers absorb REACH compliance premiums for heavy-metal-free formulations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA biocompatibility certification grade and volume scale commitments. Cost compression in standard-tier zinc-manganese cells is intensifying because silver oxide price volatility squeezes margin pools for temperature-stable chemistry specialists. Healthcare device integrators exhibit least price sensitivity due to extended 510(k) certification timelines, while smart packaging volume buyers drive hardest bargain negotiation.
Supply Chain Analysis
Strategic stockpile preferences dominate conductive ink procurement as buyers buffer against precious metal price swings. Manufacturing concentrates in South Korea, Japan, and Germany. Raw material flows draw from silver oxide refiners, zinc-manganese precursor suppliers, and polymer substrate specialists. Single-source vulnerability clusters around Seoul-Incheon electrode fabrication corridors. Distribution runs through direct OEM partnerships that bypass regional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printed batteries sit in early-cycle expansion as wearable OEM procurement accelerates ultra-thin power cell adoption beyond medical patch origins.
For Market Incumbents: Shield formulation expertise against solid-state electrolyte disruption by deepening backward integration into conductive ink production. Samsung SDI-style captive polymer substrate partnerships in Seoul's Pangyo cluster demonstrate defensible channel control. Prioritize REACH Annex XVII pre-qualification to maintain European healthcare procurement access. For New Entrants and Emerging Players: Lead with Nordic continuous glucose monitoring patch deployments where Enfucell-anchored relationships have not saturated demand. Finland and Sweden present underpenetrated white space for disposable zinc-manganese qualification. Pursue direct technical collaboration with domestic materials suppliers rather than distributor channel entry. For Investors and Strategic Acquirers: Carve-out targets emerge from display-panel conglomerates with dormant roll-to-roll electrode fabrication assets. Five-to-ten year viability hinges on solid-state electrolyte patent conversion rates. Watch polymer-ceramic composite deposition breakthroughs as inflection signal for lithium-metal energy density scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Ink | Captive silver-oxide formulation hedges against precious metal price volatility for temperature-stable chemistries. |
| Direct OEM Partnership Formation | Samsung SDI's Pangyo cluster model compresses distributor margins and locks substrate supply contracts. |
| REACH Annex XVII Pre-Qualification | Carbon-based conductive paste certification opens European healthcare procurement channels blocked to nickel formulations. |
| Solid-State Electrolyte R&D Scale-Up | Polymer-ceramic composite deposition bridges printed manufacturing scalability with lithium-metal energy density targets. |
| Nordic Medical Patch Market Entry | Finland and Sweden continuous glucose monitoring deployments favor disposable zinc-manganese skin-contact configurations. |
Research Approach
The analysis maps flexible substrate architectures, thin-film solid-state layers, rechargeable silver-zinc configurations, and disposable zinc-manganese cells, each validated through electrode fabrication engineers, conductive ink formulators, wearable OEM procurement leads, and medical device regulatory affairs specialists. Primary fieldwork combined with secondary validation from SEC filings, Korean MFDS biocompatibility registrations, ECHA REACH Annex XVII updates, and customs trade data. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor capital expenditure disclosures and display-panel equipment shipment data. The analytical framework modeled product type, application, technology, and end-user dimensions across the projection horizon. CAGRs derived from segment-level adoption curves weighted by regulatory approval timelines and OEM procurement cycle phases. Forecast inputs incorporated roll-to-roll fabrication capacity expansion announcements and solid-state electrolyte patent filing velocity.
The analysis sits within stated boundaries; outcomes outside sustained wearable electronics procurement growth or REACH regulatory stability would require recalibration. Forecasts reflect assumptions about silver oxide price band persistence and Korean electrode fabrication capacity utilization. Revision becomes warranted when solid-state electrolyte deposition yield rates cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Portable Battery Powered Products Market
Batteries
Battery Maintainer Market
Batteries
Europe Battery Cell Market
Batteries
North Europe Battery Market
Batteries
Rechargeable Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Nimh Battery Market
Batteries
Lithium Marine Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Sodium-Air Battery Market
Batteries
Hybrid Flow Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Nanicl Battery Market
Batteries
Smart Diagnostic Battery Charger Market