
 Cephalosporin Market | 2026-2036
Cephalosporin Market Size, Share, and Industry Trends Forecast 2026-2036
Cephalosporin Market Intelligence
CEP certification for active pharmaceutical ingredient manufacturing is collapsing the supplier base as smaller producers fail quality audits. Pfizer Inc. leverages vertical integration across fermentation and finished-dose production to sustain supply security. Lupin Limited anchors its position through specialized cephalosporin API capacity in Indian manufacturing zones. Sandoz Group AG competes on volume scale in European hospital procurement channels.
Cephalosporins constitute a class of beta-lactam antibiotics derived from Acremonium fungi, characterized by a dihydrothiazine ring fused to a beta-lactam nucleus that confers bactericidal activity against gram-positive and gram-negative pathogens through cell-wall synthesis inhibition. Industrial production relies on semi-synthetic routes beginning with 7-aminocephalosporanic acid (7-ACA) or 7-aminodesacetoxycephalosporanic acid (7-ADCA) intermediates, followed by acylation with side-chain precursors to yield specific generation compounds. Injectable formulations dominate hospital revenue pools due to critical-care administration requirements and higher unit economics, while oral tablet demand clusters in outpatient antibiotic therapy for community-acquired infections. Ceftriaxone and ceftazidime segments lead in surgical prophylaxis applications where broad-spectrum coverage and established efficacy protocols drive formulary placement.
FDA current Good Manufacturing Practice enforcement and EMA's Falsified Medicines Directive shape batch-release documentation and track-and-trace obligations for cross-border cephalosporin shipments. India's CDSCO and China's NMPA impose parallel bioequivalence and stability-testing standards that gate market access for generic entrants. WHO prequalification requirements for procurement into developing-country health systems add a third compliance layer for volume manufacturers. Stakeholders must monitor evolving carbapenem-resistance patterns and corresponding stewardship restrictions that could redirect hospital formulary budgets toward alternative beta-lactam classes.
Market Dynamics
Antimicrobial stewardship programs in tertiary hospitals are compressing cephalosporin prescribing volumes while simultaneously elevating demand for high-grade injectable formulations that meet stringent bioequivalence thresholds. This tension between volume restriction and quality escalation defines current market mechanics.
Growth Catalysts
- CDSCO bioequivalence mandates:India's tightened API certification standards are consolidating production toward large-scale fermentation facilities capable of 7-ACA intermediate output.
- Surgical prophylaxis protocols:Ceftriaxone and ceftazidime retain formulary dominance in orthopedic and abdominal procedures requiring gram-negative coverage.
- China's NMPA generic consistency evaluations:Domestic manufacturers are retrofitting sterile injectable lines to capture hospital procurement contracts previously held by imported brands.
Market Restraints
- Fermentation feedstock volatility:Corn steep liquor and soybean meal price swings directly compress 7-ACA production margins.
- Zhejiang and Shandong supply concentration:Over half of global cephalosporin API fermentation capacity sits within 200 kilometers of Hangzhou Bay, creating single-point-of-failure exposure.
- Carbapenem cross-resistance patterns:Extended-spectrum beta-lactamase prevalence in Klebsiella pneumoniae strains is triggering stewardship committees to restrict third-generation cephalosporin empiric use.
Strategic Opportunities
- Sub-Saharan Africa WHO prequalification pathway:Volume manufacturers can access pooled procurement through Global Fund and UNICEF tenders by meeting stability-testing benchmarks.
- Combination therapy formulations:Ceftazidime-avibactam and ceftolozane-tazobactam beta-lactamase inhibitor pairings address resistant Pseudomonas aeruginosa in cystic fibrosis and ICU settings.
- Continuous manufacturing adoption:FDA's emerging guidance on real-time release testing enables API-to-finished-dose integration that reduces batch cycle times.
Industry Challenges
- CEP certification timeline compression:European Directorate for the Quality of Medicines audit backlogs extend API supplier qualification to 18-24 months, freezing capacity expansion plans.
- Sterile fill-finish automation integration:Isolator technology and restricted access barrier systems require capital outlays that mid-tier generic houses cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cephalosporin Market |
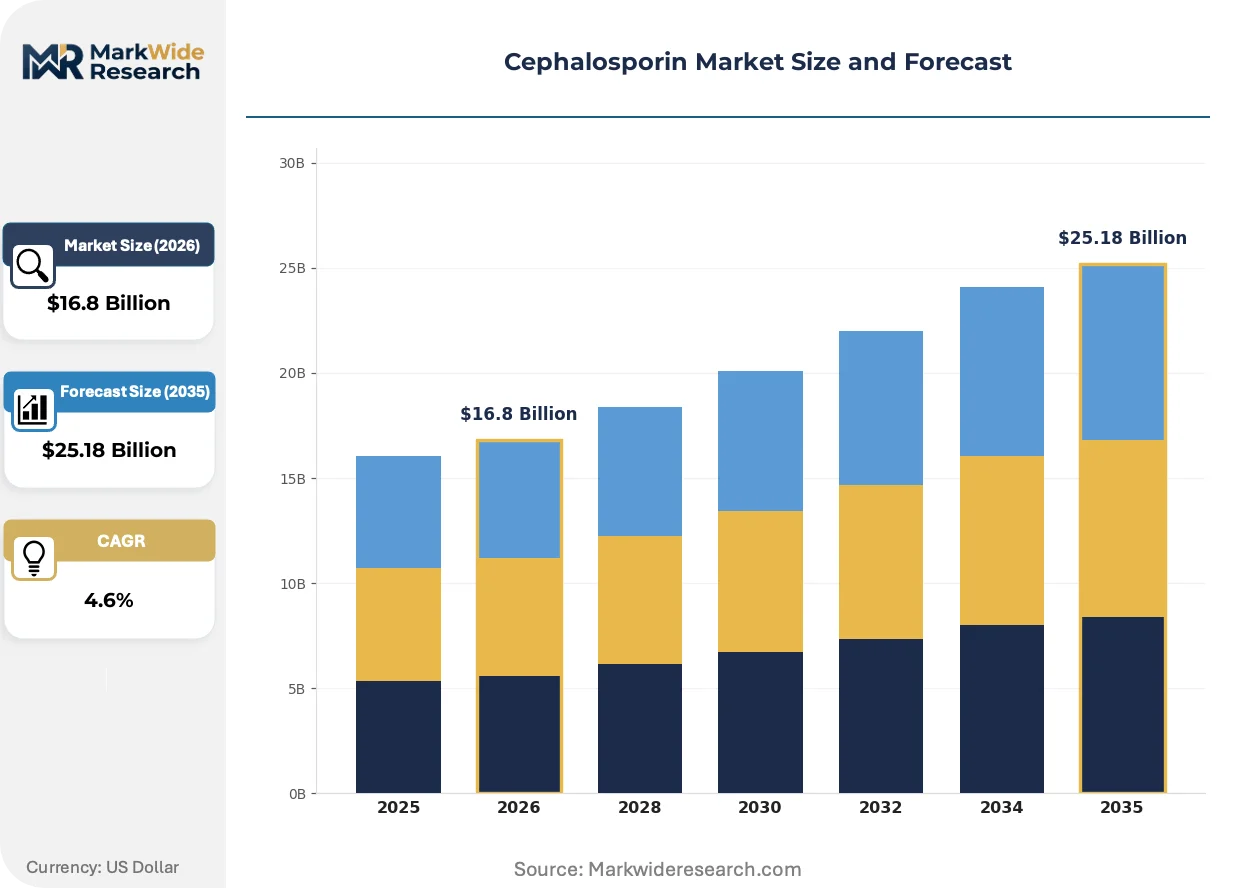
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceftriaxone, Cefotaxime, Ceftazidime, Cefepime End User: Hospitals, Clinics, Pharmacies, Research Laboratories Form: Injectable, Oral Tablet, Powder, Suspension Application: Infections, Surgical Prophylaxis, Antibiotic Therapy, Lyme Disease |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck & Co. Inc., Lupin Limited, Sandoz Group AG, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cephalosporin Market Strategic Shifts & Innovations
Enzymatic synthesis routes are displacing chemical acylation in 7-ACA and 7-ADCA production, cutting solvent waste and enabling side-chain flexibility that chemical methods cannot match. This biotechnology inflection is redrawing competitive boundaries between fermentation specialists and finished-dose formulators.
Biocatalysis is fragmenting traditional cephalosporin manufacturing economics. Penicillin G acylase and expandase enzyme platforms now enable direct ring expansion from penicillin substrates, bypassing multiple isolation steps. Sandoz and Lupin have licensed this technology for Indian and European facilities, compressing capital intensity for new entrants while eroding the cost advantage of legacy chemical routes. The technology is fragmenting supplier tiers by separating enzyme-capable producers from chemical-dependent competitors.
EMA's Falsified Medicines Directive serialization requirements are mandating end-to-end track-and-trace infrastructure for all cephalosporin shipments entering European Economic Area markets. Manufacturers must integrate 2D data matrix coding and tamper-evident features at both API and finished-dose levels. Injectable antibiotic packs bear the highest compliance burden due to cold-chain integrity documentation, pushing smaller Indian exporters toward contract manufacturing arrangements with EU-based packagers.
Hospital formulary committees are consolidating antibiotic purchasing through centralized procurement platforms that bundle cephalosporins with carbapenems and anti-MRSA agents. This category management approach displaces traditional sales representative access in favor of pharmacoeconomic dossiers and real-world evidence submissions. The shift is most visible in Germany's hospital sector purchasing organizations and France's regional health agency tenders, where annual contract values now hinge on resistance surveillance data and stewardship program participation rather than unit price alone.
Cephalosporin Market Segmentation
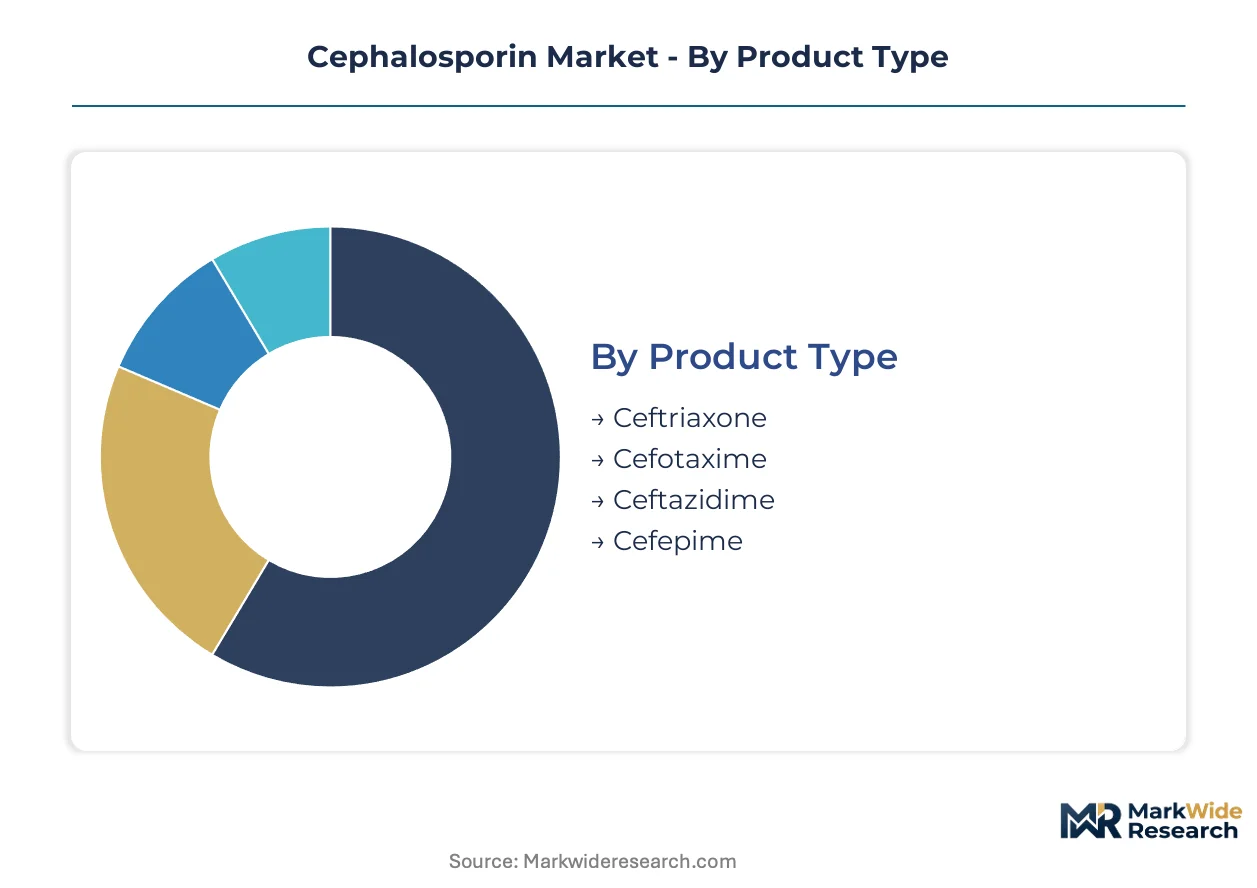
Cephalosporin procurement patterns diverge sharply across product generations and administration routes. Hospital formulary committees segment demand by resistance profile and surgical protocol requirements, while outpatient channels prioritize oral bioavailability and dosing convenience.
Product Type:
Export-led demand concentrates in third-generation injectables for hospital critical care, whereas domestic markets absorb broader-spectrum fourth-generation compounds for resistant infections.
- Ceftriaxone:Third-generation cephalosporin with extended half-life enabling once-daily dosing in severe gram-negative infections. Demand clusters in Indian and Chinese hospital procurement for surgical prophylaxis and community-acquired pneumonia protocols, constrained by CDSCO and NMPA batch-release documentation requirements.
- Ceftazidime:Antipseudomonal third-generation agent with enhanced beta-lactamase stability. European hospital purchasing organizations drive volume through centralized tenders bundling ceftazidime-avibactam combinations for ICU-resistant Pseudomonas coverage.
- Cefotaxime:Broad-spectrum third-generation cephalosporin with CNS penetration for meningitis indications.
- Cefepime:Fourth-generation zwitterionic structure conferring enhanced gram-positive activity alongside gram-negative coverage.
Ceftriaxone commands the established base. The steepest expansion runs through ceftazidime-avibactam combination formulations.
End User:
Cost tier separation distinguishes capital-intensive hospital procurement from price-sensitive retail pharmacy channels.
- Hospitals:Tertiary care institutions administer injectable cephalosporins through antimicrobial stewardship programs with restricted empiric prescribing. EMA Falsified Medicines Directive serialization and cold-chain integrity documentation elevate compliance costs for suppliers.
- Clinics:Outpatient infusion centers and ambulatory surgery facilities drive demand for pre-mixed parenteral formulations with reduced preparation time.
- Pharmacies:Community retail channels distribute oral tablet generics for uncomplicated urinary tract and respiratory infections.
- Research Laboratories:Academic and contract research organizations procure reference standards and analytical-grade APIs for bioequivalence studies and resistance surveillance.
Hospitals absorb the premium-grade volume. Pharmacies represent the most price-compressed channel with thinning margins.
Form:
Supply concentration favors sterile injectable manufacturing given capital barriers to entry.
- Injectable:Vial and pre-filled syringe presentations dominate hospital revenue pools with higher unit economics. Fill-finish automation and isolator technology requirements consolidate production toward FDA-registered facilities with real-time release testing capability.
- Oral Tablet:Immediate-release and extended-release solid dosages serve outpatient antibiotic therapy with lower bioequivalence thresholds than parenteral equivalents.
- Powder:Lyophilized and crystalline API forms supply compounding pharmacies and veterinary applications.
- Suspension:Pediatric liquid formulations address swallowing difficulties with flavored excipient systems.
Injectable forms capture the value concentration. Oral tablet production is gaining share fastest in emerging market retail expansion.
Application:
Maturity differentiation separates established infection treatment from emerging combination therapy indications.
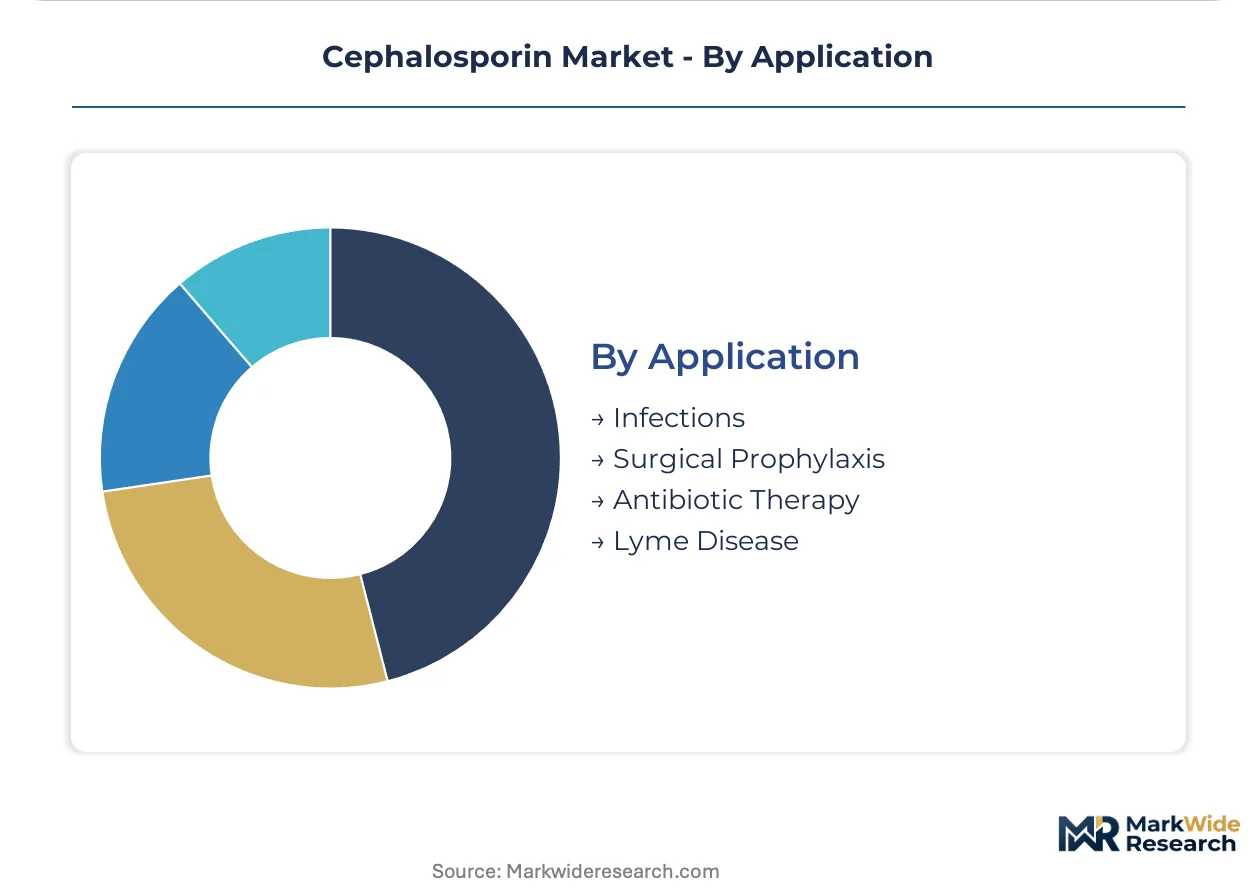
- Infections:Community-acquired pneumonia, complicated intra-abdominal infections, and pyelonephritis represent core indications with standardized dosing protocols.
- Surgical Prophylaxis:Preoperative ceftriaxone and cefotaxime administration in orthopedic and abdominal procedures requires gram-negative coverage with established efficacy data.
- Antibiotic Therapy:Empiric and targeted treatment regimens for sepsis and bacteremia in immunocompromised patients.
- Lyme Disease:Ceftriaxone IV therapy for disseminated and neurological manifestations when oral doxycycline contraindicated.
Infection treatment anchors the volume base. Surgical prophylaxis protocols are expanding most quickly through bundled procurement contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, India, China, and Japan concentrate the bulk of cephalosporin purchasing power. These buyers operate under divergent regulatory frameworks that reshape supplier qualification requirements and manufacturing compliance investments.
United States
Tertiary hospital systems drive demand for sterile injectable formulations through centralized purchasing organizations. FDA current Good Manufacturing Practice enforcement mandates batch-release documentation and real-time release testing capabilities for API suppliers. New Jersey and North Carolina host the densest clusters of finished-dose manufacturing facilities serving domestic hospital networks.
Germany
Hospital sector purchasing organizations bundle cephalosporins with carbapenems in annual tender contracts exceeding regional health agency thresholds. EMA's Falsified Medicines Directive imposes 2D data matrix serialization and tamper-evident packaging requirements on all shipments entering the European Economic Area. Bavaria and North Rhine-Westphalia concentrate sterile fill-finish capacity for Central European distribution.
India
Domestic hospital procurement and export-oriented API production create dual demand streams for fermentation-derived intermediates. CDSCO bioequivalence mandates and tightened CEP certification standards consolidate production toward large-scale 7-ACA facilities in Gujarat and Maharashtra. Hyderabad and Mumbai anchor the supplier base for sterile injectable exports to regulated markets.
China
NMPA generic consistency evaluations drive retrofitting of sterile injectable lines to capture hospital contracts previously held by imported brands. Zhejiang and Shandong provinces host over half of global cephalosporin API fermentation capacity within 200 kilometers of Hangzhou Bay. Domestic manufacturers face pressure to meet dual carbon goals while scaling output for Belt and Road health system procurement.
Japan
PMDA maintains stringent stability-testing and bioequivalence standards that limit generic entrant numbers in hospital formulary channels. METI industrial policy supports domestic fermentation capacity for strategic pharmaceutical security. Osaka and Tokyo metropolitan areas concentrate finished-dose formulation for aging-population infection treatment protocols.
Cephalosporin Market Key Industry Players
Player mix skews toward vertically integrated pharmaceutical conglomerates with captive fermentation capacity and specialized Indian API manufacturers serving export markets. The structure divides between premium-tier innovators with patented combination therapies and volume-scale generic houses competing on cost and regulatory certification speed. Two strategic archetypes dominate: fermentation specialists controlling 7-ACA intermediate supply and finished-dose formulators with FDA-registered sterile fill-finish lines. Competitive moves center on enzymatic synthesis technology licensing and backward integration into fermentation feedstock security.
Among North American-based conglomerates, Pfizer Inc. exemplifies the integrated archetype spanning fermentation through hospital channel distribution. Lupin Limited and Sun Pharmaceutical Industries Ltd. anchor the Indian specialist tier with concentrated API capacity in domestic manufacturing zones. Sandoz Group AG occupies a position bridging European hospital procurement scale with technology licensing flexibility.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck & Co. Inc. |
| Lupin Limited |
| Sandoz Group AG |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Indian API manufacturers and European hospital purchasing organizations lock in multi-year supply access while embedding corn steep liquor and soybean meal indexation clauses that preserve margin visibility against fermentation feedstock volatility. These arrangements concentrate pricing power among vertically integrated producers with captive 7-ACA intermediate capacity, while mid-tier generic houses face spot market exposure on both input costs and finished-dose procurement.
Pricing Analysis
Cost-plus contracts with corn steep liquor indexation dominate API procurement between Indian fermentation specialists and European hospital purchasing organizations. Three-tier pricing structure across CEP-certified premium, CDSCO-registered standard, and non-certified economy grades separates Pfizer and Sandoz from domestic Chinese suppliers. Pricing pressure stems from NMPA generic consistency evaluations compressing margins on sterile injectable lines. Retail pharmacy channels exhibit the highest price sensitivity, while tertiary hospital systems prioritize bioequivalence certification over unit cost.
Supply Chain Analysis
China and India anchor global cephalosporin API production, with Zhejiang and Shandong provinces hosting over half of worldwide fermentation capacity and Gujarat and Maharashtra concentrating 7-ACA intermediate output. Manufacturing draws from corn steep liquor, soybean meal, and penicillin G acylase enzyme feedstocks. Single-source vulnerability concentrates in the 200-kilometer radius around Hangzhou Bay, where environmental compliance shutdowns ripple through global supply. Distribution runs through FDA-registered sterile fill-finish facilities in New Jersey, Bavaria, and Hyderabad before reaching hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital purchasing organization consolidation across Germany and France has shifted bargaining power toward centralized formulary committees, fragmenting supplier access and elevating pharmacoeconomic dossier requirements over traditional sales relationships.
For Market Incumbents: Compound fermentation capacity advantages by securing CEP certification for expanded 7-ACA intermediate output in Indian manufacturing zones, while investing in enzymatic synthesis technology licensing to displace chemical-dependent competitors threatened by European Directorate for the Quality of Medicines audit backlogs. Lock in long-term offtake arrangements with hospital purchasing organizations before NMPA generic consistency evaluations fully mature.
For New Entrants and Emerging Players: Contract manufacturing service gaps in sterile fill-finish automation for mid-tier Indian exporters present white-space entry points, particularly for EU-based packagers capable of EMA Falsified Medicines Directive serialization compliance. Target WHO prequalification pathways for Sub-Saharan Africa pooled procurement through Global Fund tenders, leveraging stability-testing benchmarks as a differentiated go-to-market angle against established volume manufacturers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors enzyme-capable fermentation specialists with CEP certification momentum over chemical-dependent API producers. Long-term viability hinges on backward integration into fermentation feedstock security and real-time release testing capability. Watch carbapenem cross-resistance surveillance data as the inflection signal for stewardship-driven formulary budget redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Technology Licensing | Penicillin G acylase platforms cut solvent waste and enable side-chain flexibility that chemical routes cannot match. |
| CEP Certification Acceleration | European Directorate for the Quality of Medicines audit qualification separates API suppliers from frozen expansion plans. |
| WHO Prequalification Pathway | Stability-testing benchmarks unlock Global Fund and UNICEF tenders for Sub-Saharan Africa volume access. |
| Sterile Fill-Finish Automation Integration | Isolator technology and restricted access barrier systems consolidate production toward FDA-registered facilities. |
| Combination Therapy Formulation Development | Ceftazidime-avibactam pairings address resistant Pseudomonas aeruginosa in cystic fibrosis and ICU settings. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up fermentation capacity modeling and top-down hospital spending pattern analysis were triangulated to cross-check volume and value estimates.
Segmentation dimensions modeled include product generation, administration route, end-user channel, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating antimicrobial stewardship program penetration rates and surgical prophylaxis protocol adoption. Industry-specific forecast inputs encompassed CDSCO bioequivalence mandate implementation timelines and NMPA generic consistency evaluation completion rates.
Underlying assumptions cover carbapenem-resistance surveillance stability and fermentation feedstock price regime continuity, with deviation risk concentrated in Zhejiang environmental compliance actions and European hospital purchasing organization tender bundling shifts. Recalibration cycles align with material shifts in stewardship program restrictiveness and CEP certification audit backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market