
 Global Insulin Glargine Market | 2026-2036
Global Insulin Glargine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulin Glargine Market Foresight
Chinese API producers is repositioning global supply chains for recombinant insulin analogs, shifting cost structures for finished formulation manufacturers worldwide. Sanofi leverages vertical integration from active pharmaceutical ingredient synthesis to pre-filled pen delivery systems, sustaining margin capture across the value chain. Novo Nordisk anchors its position through proprietary yeast expression platforms that differentiate manufacturing efficiency. Eli Lilly and Company competes via concentrated insulin formulations that extend dosing intervals for high-need patient segments.
Insulin glargine is a recombinant human insulin analog engineered with two arginine additions at the B-chain C-terminus and glycine substitution at A21, creating a hexameric formulation with delayed subcutaneous absorption and peakless 24-hour basal glucose coverage. The molecule's pH-dependent solubility profile enables once-daily administration for glycemic control in insulin-dependent diabetes patients. Biosimilar insulin glargine occupies the fastest-expanding product category as regulatory interchangeability designations unlock automatic pharmacy substitution in major markets. Type 2 diabetes applications dominate volume consumption due to progressive beta-cell failure requiring basal insulin escalation, while Type 1 diabetes segments retain premium pricing for originator brands. Home healthcare providers represent a structurally growing end-user channel as pen-based delivery systems reduce clinical dependency.
The FDA's interchangeable biosimilar standards and EMA's biosimilar comparability guidelines create divergent market access timelines across jurisdictions, directly shaping competitive entry sequencing. China's NMPA accelerated biosimilar approval pathways compress development timelines for domestic manufacturers including Gan & Lee and Tonghua Dongbao. WHO prequalification standards for insulin products influence procurement eligibility across low- and middle-income country tenders. Stakeholders must monitor regulatory divergence between interchangeability standards and real-world substitution policies as these determine biosimilar penetration velocity and originator defense strategies.

Market Dynamics
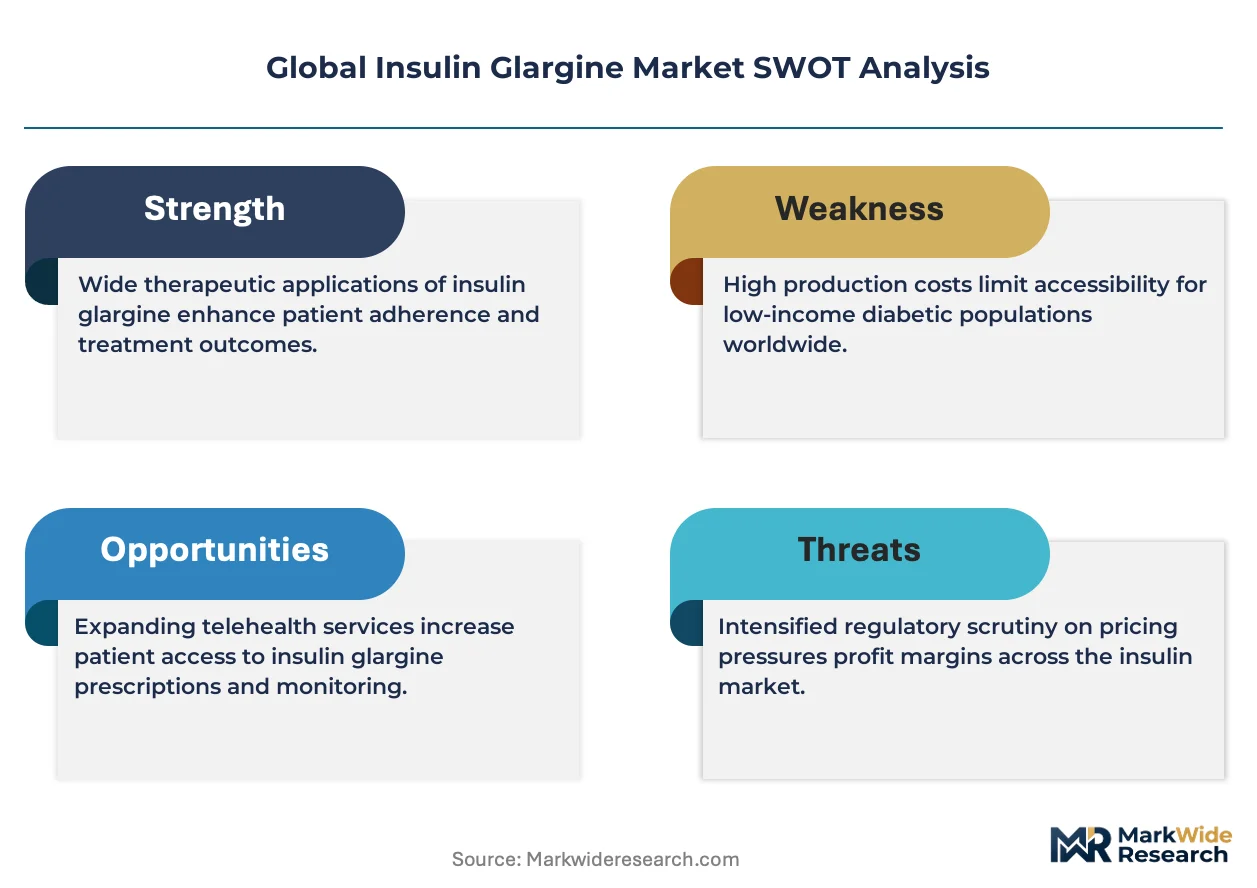
Biosimilar interchangeability designations are compressing originator pricing power while redirecting pharmacy substitution patterns across hospital and retail channels. This regulatory mechanism is restructuring competitive economics for long-acting insulin analogs.
Growth Catalysts
- FDA Interchangeability Pathway:Automatic substitution authority at the pharmacy level eliminates prescriber friction and accelerates biosimilar volume capture in US retail settings.
- Type 2 Diabetes Progression:Beta-cell failure patterns in aging populations escalate basal insulin requirements, expanding the addressable patient pool for glargine formulations.
- Home Healthcare Expansion:Pen-based delivery systems reduce clinical dependency and enable self-administration, shifting site-of-care economics toward outpatient channels.
Market Restraints
- Recombinant Insulin API Concentration:Chinese active pharmaceutical ingredient producers control critical fermentation capacity, creating supply vulnerability for finished formulation manufacturers.
- Cold Chain Infrastructure Gaps:Temperature-controlled distribution requirements limit market penetration in low- and middle-income countries lacking reliable logistics networks.
- Immunogenicity Surveillance Burden:Post-market immunogenicity monitoring requirements impose sustained regulatory compliance costs on biosimilar entrants.
Strategic Opportunities
- India's Biosimilar Acceleration:CDSCO streamlined approval pathways and domestic manufacturing incentives create entry vectors for cost-optimized glargine production.
- Concentrated Insulin Formulations:U300 and higher-strength analogs address high-need patient segments with reduced injection volumes and extended dosing intervals.
- WHO Prequalification:Procurement eligibility for low- and middle-income country tenders opens institutional volume channels outside branded markets.
Industry Challenges
- Analytical Biosimilarity Demonstration:Extensive physicochemical and functional characterization requirements compress development timelines and inflate CMC expenditure.
- Yeast Expression Platform Expertise Scarcity:Proprietary fermentation and purification capabilities concentrate among established manufacturers, constraining new entrant process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulin Glargine Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basal Insulin, Biosimilar Insulin Glargine, Concentrated Insulin, Pre-mixed Formulation Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Latent Autoimmune Diabetes in Adults End User: Hospitals, Clinics, Diabetes Care Centers, Home Healthcare Providers Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Drug Wholesalers |
| Companies Covered | Sanofi, Novo Nordisk, Eli Lilly and Company, Biocon Biologics, Wockhardt, Julphar, Gan & Lee, Tonghua Dongbao, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulin Glargine Market Shifts & Advancements
Connected delivery devices and real-time glucose monitoring integration are redefining patient adherence measurement and dosing optimization. These digital interfaces are shifting competitive differentiation toward data-enabled care ecosystems.
Smart pen technologies with dose-capture and Bluetooth transmission capabilities are converging with continuous glucose monitoring platforms to enable closed-loop decision support. Home healthcare providers and diabetes management platforms are piloting these integrated systems in Germany and the United States. This convergence is compressing the feedback loop between glucose measurement and insulin dosing, potentially displacing traditional pen-and-logbook adherence models.
EMA's refined biosimilar comparability guidelines are tightening immunogenicity assessment standards and extending clinical trial requirements for insulin analogs. The industrial consequence is elevated development costs and elongated approval timelines for European market entry. Biosimilar manufacturers are responding with parallel US-EU filing strategies that prioritize FDA interchangeability designation before EMA scientific advice completion.
Hospital procurement consortia are consolidating purchasing authority and unbundling device components from drug pricing negotiations. Group purchasing organizations in the United States are extracting separate rebates for pen needles and delivery systems, compressing bundled margin structures. This disintermediation is most visible in integrated delivery networks where pharmacy benefit managers now control formulary placement independent of device preferences.
Global Insulin Glargine Market Segmentation
Insulin glargine market segmentation reveals distinct technology-specification, patient-population, and channel-access boundaries that determine pricing power and competitive entry vectors. Each dimension carries regulatory, reimbursement, and supply chain implications that shape manufacturer strategy.
Product Type:
Molecular engineering and manufacturing complexity differentiate product tiers across the glargine landscape.
- Biosimilar Insulin Glargine:Recombinant analogs demonstrating physicochemical and functional equivalence to originator reference products through extensive analytical characterization. FDA interchangeability designations in the United States and EMA biosimilar approvals in Germany are accelerating automatic pharmacy substitution and compressing originator pricing power.
- Basal Insulin:Standard U100 glargine formulations providing 24-hour peakless glucose coverage through delayed subcutaneous absorption from hexameric precipitation. Type 2 diabetes progression patterns in aging populations are escalating volume requirements for once-daily basal regimens.
- Concentrated Insulin:U300 and higher-strength formulations reducing injection volumes for insulin-resistant patients requiring elevated daily doses. High-need patient segments with severe insulin resistance are driving adoption in specialized diabetes centers.
- Pre-mixed Formulation:Fixed-ratio combinations of rapid-acting and long-acting insulin analogs in single-dose presentations. Simplified regimens for patients with limited self-management capacity are sustaining demand in emerging markets with constrained specialist access.
Mature deployment sits with Basal Insulin. Newer deployment is concentrated in Biosimilar Insulin Glargine.
Application:
Disease etiology and progression dynamics segment addressable populations by insulin dependence severity and treatment escalation patterns.
- Type 2 Diabetes:Progressive beta-cell failure in aging populations creates escalating basal insulin requirements as oral agent efficacy declines. Hospital formulary committees in the United States are prioritizing biosimilar glargine for this volume-dominant segment.
- Type 1 Diabetes:Absolute insulin deficiency requiring comprehensive basal-bolus regimens with stringent glycemic targets. Pediatric and young adult populations in Germany retain premium pricing tolerance for originator brands with established immunogenicity profiles.
- Gestational Diabetes:Pregnancy-specific insulin requirements prioritizing maternal-fetal safety and rapid dose titration capability. Maternal health protocols in hospital settings are specifying glargine for overnight glucose control when dietary management fails.
- Latent Autoimmune Diabetes in Adults:Slow-onset autoimmune beta-cell destruction often misdiagnosed as Type 2 diabetes. Specialist endocrinology practices in China are expanding diagnostic recognition and insulin initiation for this previously under-treated population.
Type 2 Diabetes captures the highest absolute volumes. Type 1 Diabetes commands the strongest pricing premiums.
End User:
Site-of-care economics and clinical oversight intensity determine device requirements and reimbursement pathways.
- Home Healthcare Providers:Outpatient diabetes management platforms and visiting nurse services enabling pen-based self-administration with remote monitoring support. United States integrated delivery networks are expanding home-based initiation programs to reduce hospital readmission penalties.
- Hospitals:Inpatient glycemic management protocols and perioperative insulin regimens requiring standardized formulary compliance. Group purchasing organization consolidation in the United States is extracting separate device rebates and compressing bundled margins.
- Clinics:Primary care and endocrinology practices managing stable outpatients with periodic dose adjustments. China's tiered hospital system is shifting routine diabetes follow-up to municipal clinics under national essential medicines programs.
- Diabetes Care Centers:Specialized facilities with continuous glucose monitoring integration and closed-loop system capabilities. Germany's disease management program structure is concentrating complex cases in certified centers with outcome-based reimbursement.
Hospital procurement concentrates volume purchasing power. Home Healthcare Providers are expanding most quickly as pen technologies reduce clinical dependency.
Distribution Channel:
Channel structure determines substitution authority, cold chain requirements, and patient access economics.
- Retail Pharmacies:Community-based dispensing with automatic substitution authority for interchangeable biosimilars under FDA and state pharmacy regulations. United States retail chains are deploying pharmacist-led diabetes management services to capture adherence-linked reimbursement.
- Hospital Pharmacies:Captive dispensing integrated with electronic health records and inpatient glycemic protocols. Formulary placement decisions by pharmacy and therapeutics committees in Germany are prioritizing total cost of ownership over acquisition price.
- Online Pharmacies:Direct-to-patient delivery platforms with temperature-controlled logistics for maintenance prescriptions. China's e-commerce penetration in chronic disease medications is accelerating under internet healthcare reimbursement pilots.
- Drug Wholesalers:Temperature-controlled distribution infrastructure connecting manufacturers to institutional and retail endpoints. Three-tier distributor consolidation in the United States is compressing margins and demanding data-sharing agreements for inventory optimization.
Drug Wholesalers anchor supply chain infrastructure. Online Pharmacies are gaining share fastest where cold chain logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant insulin API fermentation capacity concentrates in Chinese industrial clusters around Beijing and Tianjin, anchoring upstream supply for finished formulation manufacturers worldwide. This geographic concentration shapes competitive dynamics across major consumption markets.
United States
Hospital formulary committees and pharmacy benefit managers drive biosimilar substitution through FDA interchangeability designations, compressing originator pricing power. The IRA's Medicare drug price negotiation provisions reshape reimbursement economics for long-acting insulin analogs. Indianapolis anchors domestic manufacturing concentration for concentrated insulin formulations serving high-need patient segments.
Germany
Disease management programs concentrate complex diabetes cases in certified centers with outcome-based reimbursement structures. EMA biosimilar comparability guidelines tighten immunogenicity assessment standards, extending development timelines for European market entry. The Rhine-Ruhr and Bavarian pharmaceutical clusters host formulation and packaging operations for regional distribution.
China
NMPA accelerated approval pathways compress development timelines for domestic biosimilar manufacturers targeting volume-dominant Type 2 diabetes segments. National essential medicines programs shift routine diabetes follow-up to municipal clinics under tiered hospital system reforms. Beijing-Tianjin-Hebei corridor fermentation facilities supply recombinant insulin API to domestic and export markets.
India
CDSCO streamlined biosimilar approval pathways and domestic manufacturing incentives create entry vectors for cost-optimized glargine production targeting institutional tenders. WHO prequalification standards influence procurement eligibility for low- and middle-income country supply. Mumbai-Pune and Hyderabad pharmaceutical clusters concentrate formulation and analytical capabilities for export-oriented production.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates biosimilar entry pathways for insulin analogs in Latin America's largest diabetes market. Public health system procurement through unified purchasing platforms concentrates volume negotiations for basal insulin regimens. São Paulo state pharmaceutical manufacturing infrastructure supports regional packaging and distribution operations.
Global Insulin Glargine Market Competitive Landscape
Global majors compete with regional champions across regulatory approval pathways and manufacturing scale dimensions. The vendor base stratifies between vertically integrated originators controlling expression platform technology, biosimilar specialists leveraging cost-optimized fermentation, and emerging market manufacturers capturing institutional tender volumes. Three archetypes dominate: proprietary technology holders, regulatory fast-followers, and cost-driven volume suppliers. Capacity expansion in Chinese API fermentation and strategic partnerships for distribution access constitute the dominant competitive moves.
Among proprietary technology holders, Sanofi and Novo Nordisk anchor positions through captive expression platforms and integrated delivery system portfolios. Eli Lilly and Company occupies a position among concentrated formulation specialists addressing insulin-resistant patient segments with extended dosing interval products. Gan & Lee and Tonghua Dongbao exemplify the regulatory fast-follower archetype, leveraging NMPA accelerated pathways to compress development timelines and capture domestic Chinese volume before export expansion.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Eli Lilly and Company |
| Biocon Biologics |
| Wockhardt |
| Julphar |
| Gan & Lee |
| Tonghua Dongbao |
| Boehringer Ingelheim |
| Others |
Supply & Pricing Matrix
Originator manufacturers with captive fermentation capacity anchor pricing discipline through backward integration into recombinant insulin API production, insulating margin structures from Chinese supplier volatility while biosimilar entrants absorb upstream cost pass-through. This ownership pattern concentrates pricing power among vertically integrated incumbents and compresses margin capture for formulation-only competitors dependent on external API sourcing.
Pricing Analysis
Warranty and service bundling separates originator brands offering immunogenicity surveillance and patient support programs from unbundled biosimilar pricing that strips out adherence services. Three-tier pricing structure across premium originator, standard biosimilar, and economy institutional-tender levels stratifies the market by certification grade and volume scale. Pricing pressure stems from FDA interchangeability designations enabling automatic pharmacy substitution without prescriber consultation. Hospital procurement committees exhibit highest price sensitivity through consolidated purchasing authority, while pediatric Type 1 diabetes segments retain lowest sensitivity due to immunogenicity risk aversion.
Supply Chain Analysis
Reverse logistics for temperature excursions and expired product returns flows through specialized cold-chain carriers with validated thermal packaging recovery protocols. Recombinant insulin API production concentrates in China, South Korea, and Denmark, drawing from microbial fermentation and yeast expression platforms. Critical inputs include recombinant DNA plasmids, fermentation media components, and pharmaceutical-grade resins for chromatographic purification. Single-source vulnerability concentrates in Chinese API fermentation capacity controlling global supply. Distribution runs through three-tier drug wholesaler networks with temperature-controlled warehousing connecting manufacturers to retail and institutional endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin glargine sector is consolidating around vertical-integration races where control over yeast expression platforms and pre-filled pen manufacturing determines competitive survival. Players are pursuing captive API fermentation capacity as the decisive upstream lever to secure margin capture and supply certainty.
For Market Incumbents: Deploy formulary lock-in agreements with integrated delivery networks to defend against interchangeable biosimilar substitution at the pharmacy level. Deepen backward integration into recombinant insulin API fermentation through capacity expansion in the Beijing-Tianjin corridor or strategic offtake arrangements with Chinese producers. Strengthen immunogenicity surveillance databases as a defensive moat against biosimilar safety equivalence claims. For New Entrants and Emerging Players: Launch via WHO prequalification pathways targeting institutional tenders in low- and middle-income countries where originator brands hold limited presence. Concentrate initial penetration on India's CDSCO-accelerated approval environment for cost-optimized production serving domestic and export markets. Pursue concentrated insulin U300 formulations as a differentiated entry vector for insulin-resistant patient segments underserved by standard U100 offerings. For Investors and Strategic Acquirers: Distressed-cycle entries favor biosimilar specialists with NMPA approvals and dormant export capacity in China's pharmaceutical clusters. Long-term viability hinges on regulatory fast-follower positioning rather than originator R&D intensity. Monitor FDA interchangeability designation velocity and Medicare price negotiation implementation as inflection indicators for biosimilar penetration trajectories versus originator defense durability.| Strategic Initiative | Industry Significance |
|---|---|
| Yeast Expression Platform Acquisition | Captive fermentation technology anchors manufacturing cost advantage against biosimilar competition. |
| FDA Interchangeability Designation Pursuit | Automatic substitution authority unlocks pharmacy-level volume capture without prescriber friction. |
| Cold Chain Infrastructure Partnership | Temperature-controlled logistics partnerships reduce distribution vulnerability in emerging markets. |
| Concentrated Insulin Formulation Development | U300 and higher-strength products address insulin-resistant segments with reduced injection burden. |
| WHO Prequalification Submission | Procurement eligibility opens institutional volume channels across low- and middle-income tenders. |
Research Methodology
FDA filings, EMA scientific advice documents, and ClinicalTrials.gov records formed the secondary backbone for regulatory pathway and trial design validation. Primary interviews with regulatory affairs leads at biosimilar developers, formulary directors at integrated delivery networks, hospital procurement managers at group purchasing organizations, and payer access specialists at pharmacy benefit managers combined with secondary validation to triangulate market sizing. Bottom-up patient volume modeling and top-down manufacturer revenue reconciliation anchored value estimates across the analysis window.
Historical trendline analysis of insulin analog adoption patterns, biosimilar penetration trajectories in comparable biologic categories, and pricing erosion curves informed projection frameworks. Segmentation modeling spanned product type, application by diabetes etiology, end-user site-of-care economics, and regional regulatory cluster. CAGRs derived from weighted average of epidemiological demand drivers, substitution elasticity parameters, and reimbursement policy evolution across the projection horizon. Forecast inputs included beta-cell failure progression rates and cold chain infrastructure development indices.
Regulatory approval delays, immunogenicity surveillance findings, and API supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding interchangeability designation timelines and Medicare negotiation implementation scope. Practitioners should monitor FDA biosimilar approval cadence and Chinese fermentation capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Vaccine Production Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Immunocytokines Market