
 Rapid Acting Insulin Market | 2026-2036
Rapid Acting Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Acting Insulin Market Intelligence
Biocon Limited is broadening manufacturing capacity for recombinant insulin analogs at its Bengaluru facilities to serve regulated and emerging markets. Novo Nordisk A/S anchors European supply through its Kalundborg production complex, the world's largest insulin manufacturing site. Eli Lilly and Company leverages vertical integration from active pharmaceutical ingredient synthesis to finished-dose packaging, sustaining cost advantages in lispro production. Sanofi S.A. competes through differentiated delivery device ecosystems paired with glulisine formulations.
Rapid acting insulin comprises genetically engineered analogs of human insulin with modified amino acid sequences that accelerate subcutaneous absorption, typically reaching peak plasma concentration within 30 to 90 minutes to mimic physiological prandial insulin response. These analogs are produced through recombinant DNA technology in microbial or mammalian cell cultures, then purified and formulated for injection to manage postprandial glucose excursions in diabetes patients. Insulin Lispro and Insulin Aspart dominate current prescription volumes, reflecting established clinical familiarity and broad payer coverage, while Fiasp represents the fastest-growing product type due to its accelerated onset profile. Pump Delivery systems command premium positioning among technology-integrated patient segments, though Injection Pens retain the largest volume share across hospital and homecare settings.
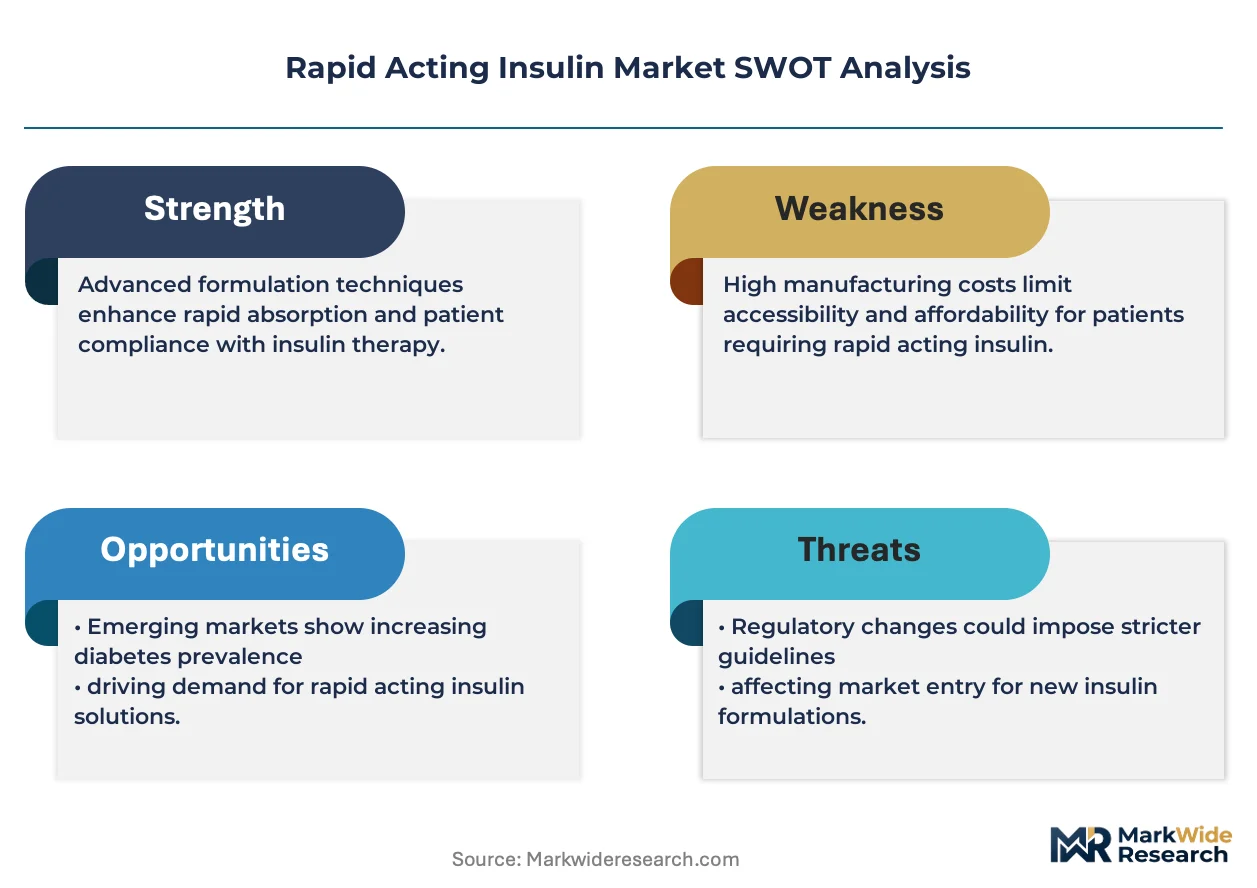
FDA biosimilar interchangeability standards and EMA biosimilar guidelines jointly shape product development investments and market access timelines for new entrants. The WHO prequalification program and national pricing authorities in Germany, France, and Japan exert downward pressure on reference product premiums while expanding access pathways. Stakeholders must monitor evolving interchangeability designation decisions and real-world evidence requirements that will determine competitive substitution dynamics and portfolio prioritization strategies.
Market Dynamics
FDA's biosimilar interchangeability pathway is compressing reference product exclusivity periods while pump-integrated delivery systems are absorbing premium patient segments faster than standard injection formats.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage for continuous glucose monitor-insulin pump integration is accelerating technology adoption among Type 1 diabetes patients in the United States.
- Surgical Glycemic Protocols:Hospital perioperative insulin standardization is driving institutional procurement volumes for rapid-acting analogs in ICU and operating theater settings.
- Accelerated Onset Formulations:Faster-absorption insulin analogs are displacing first-generation prandial products in intensive insulin regimens where postprandial glucose control is prioritized.
Market Restraints
- API Supply Concentration:Recombinant insulin active pharmaceutical ingredient production clusters in Denmark and the United States, creating geographic supply vulnerability for non-integrated manufacturers.
- Cold Chain Complexity:Temperature-controlled distribution requirements from manufacturing through patient administration impose logistics costs that erode margin in price-sensitive markets.
- Biosimilar Substitution Barriers:State-level pharmacy substitution laws and prescriber notification requirements create friction against automatic interchangeability despite FDA designation.
Strategic Opportunities
- Connected Delivery Ecosystems:Bluetooth-enabled smart pens paired with dose-logging applications are opening adherence-monitoring revenue streams beyond drug formulation alone.
- Hospital Contracting Consolidation:Group purchasing organization centralization of insulin procurement is creating volume aggregation points for manufacturers with integrated device-drug offerings.
- Pre-Filled Syringe Automation:Ready-to-administer formats are reducing nursing labor in surgical settings and capturing formulary preference in integrated delivery networks.
Industry Challenges
- Biosimilar Manufacturing Scale-Up:Cell culture yield optimization and biosimilar immunogenicity testing require specialized bioprocessing expertise that constrains new entrant capacity expansion timelines.
- Interchangeability Evidence Generation:FDA switching studies demand substantial patient exposure data that extends development timelines and inflates pre-market investment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Acting Insulin Market |
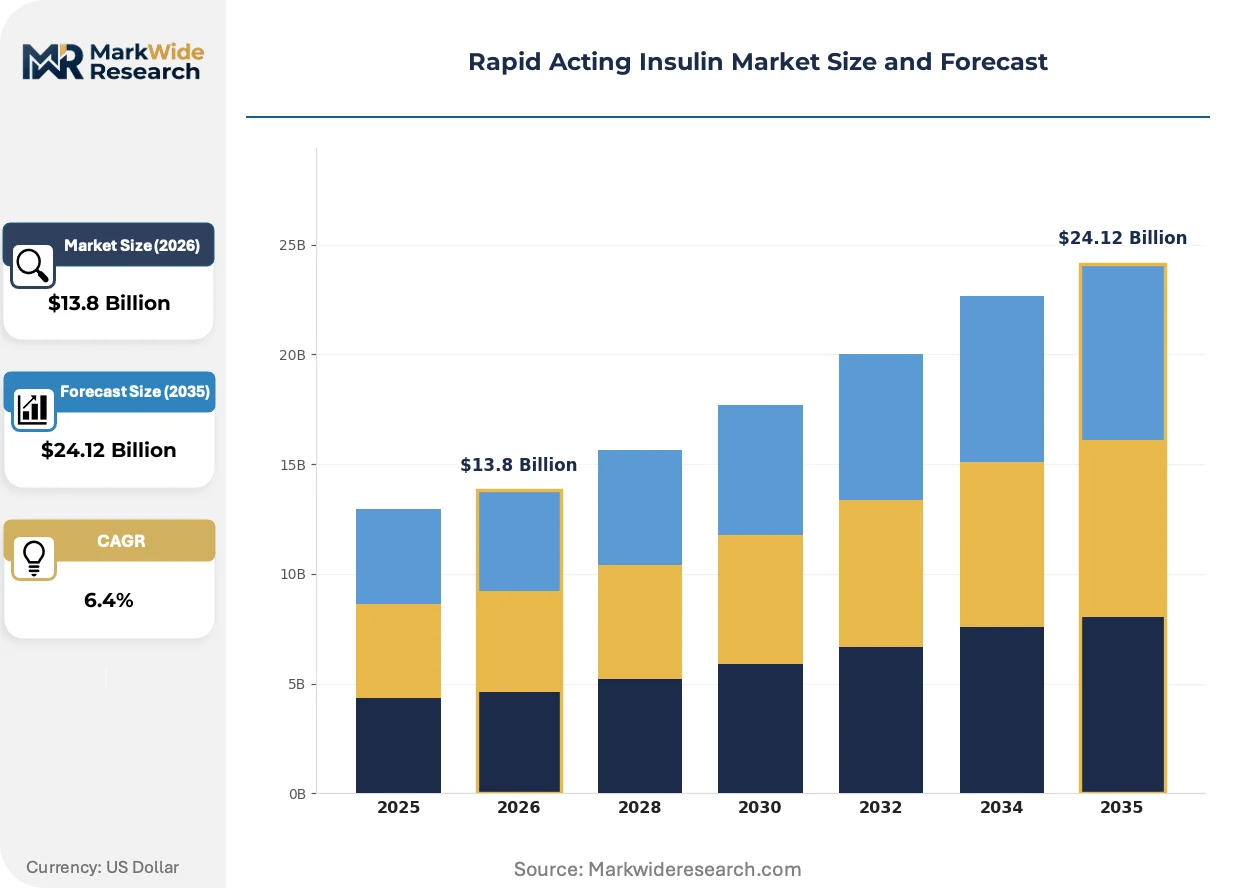
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Aspart, Insulin Lispro, Insulin Glulisine, Fiasp Delivery Mode: Injection Pens, Vials, Pump Delivery, Prefilled Syringes End User: Hospitals, Homecare, Diabetes Clinics, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Eli Lilly and Company, Novo Nordisk A/S, Sanofi S.A., Biocon Limited, MannKind Corporation, Adocia, Gan & Lee Pharmaceuticals Co. Ltd., Wockhardt Ltd., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Acting Insulin Market Strategic Shifts & Innovations
Delivery technology convergence with digital health platforms is redefining competitive differentiation beyond molecular formulation, while regulatory pathways for biosimilar substitution are rewriting commercial access dynamics.
Ultra-rapid insulin formulations with modified excipient compositions are absorbing the intensive insulin therapy segment previously served by standard rapid-acting analogs. Endocrinology practices managing Type 1 diabetes with automated insulin delivery systems are adopting these faster-onset products at accelerating rates. This absorption is compressing the effective market window for first-generation prandial insulins and forcing portfolio rationalization among established manufacturers.
EMA's refined biosimilar insulin guidelines and FDA's interchangeability designation framework are jointly reshaping market entry economics for follow-on biologics. The industrial consequence is heightened investment in real-world evidence generation and pharmacovigilance infrastructure to support automatic substitution at pharmacy level. Products seeking interchangeability status face the most pronounced compliance burden, particularly in the United States where state substitution laws create patchwork access conditions.
Hospital procurement consolidation through group purchasing organizations is concentrating insulin purchasing authority among fewer decision-makers with standardized glycemic control protocols. Traditional distributor relationships are giving way to direct manufacturer-contracting with integrated delivery networks seeking bundled device-drug pricing. This concentration is most visible in the United States, where Medicare reimbursement pressure and value-based care mandates are accelerating formulary restriction and therapeutic interchange programs.
Rapid Acting Insulin Market Segmentation
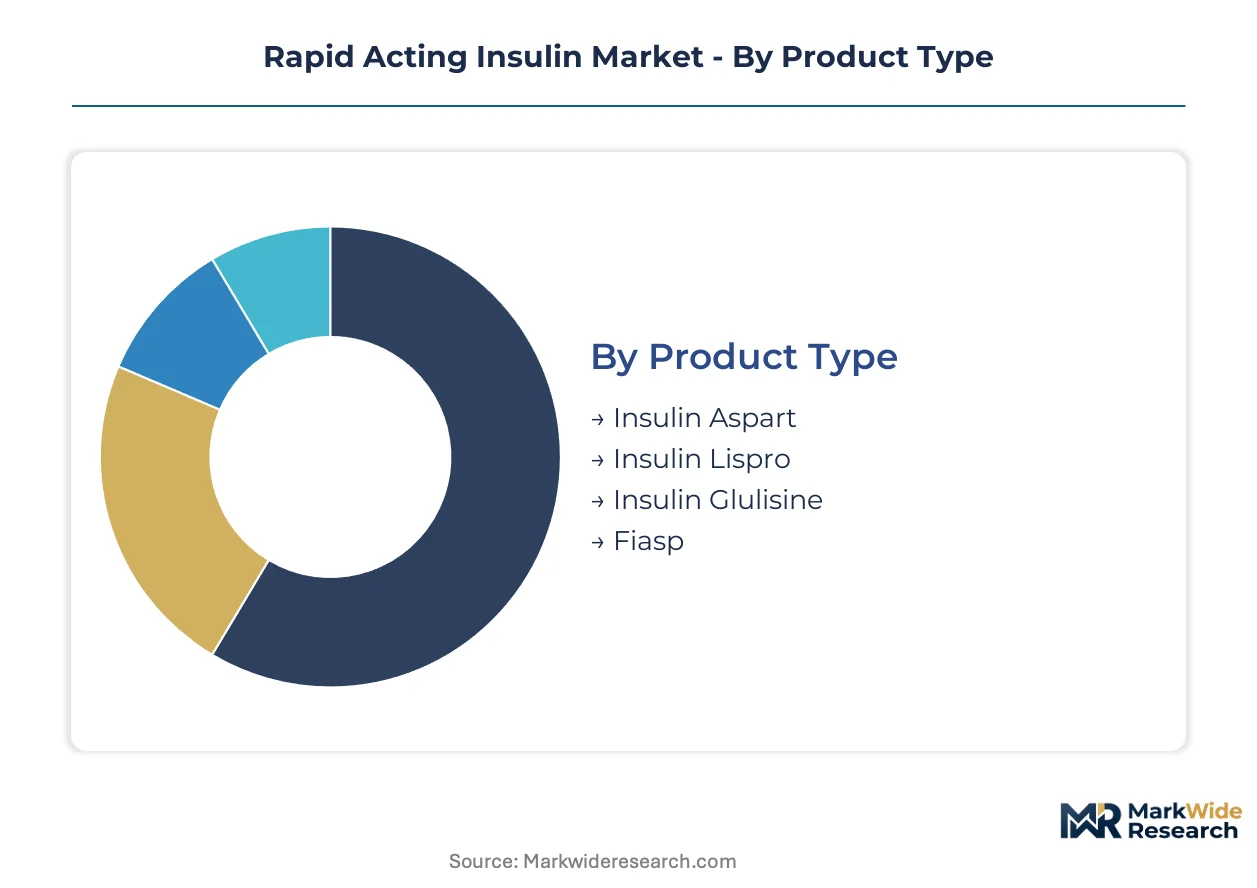
Rapid acting insulin segmentation reveals distinct upgrade cycles across molecular formulations and delivery technologies. Replacement dynamics differ materially between hospital procurement systems and individual patient prescriptions.
Product Type:
Reformulation cycles accelerate as ultra-rapid analogs displace first-generation prandial products in intensive insulin regimens.
- Insulin Aspart:Recombinant analog produced in Saccharomyces cerevisiae with amino acid substitution at position B28. Demand concentrates in United States hospital systems where Novo Nordisk's NovoLog maintains broad formulary access through integrated delivery network contracts.
- Insulin Lispro:Engineered through reversal of B28 proline and B29 lysine residues to reduce hexameric aggregation. Eli Lilly's Humalog dominates Medicare Part D volume through established prior authorization pathways and endocrinology practice familiarity.
- Insulin Glulisine:Modified B3 asparagine and B29 lysine substitutions yield faster dissociation kinetics. Sanofi's Apidra captures niche positioning in pump-compatible formulations.
- Fiasp:Aspart analog with niacinamide excipient accelerating initial absorption. Fastest uptake among automated insulin delivery users seeking tighter postprandial control.
Volume placements concentrate in Insulin Lispro; the faster expansion belongs to Fiasp.
Delivery Mode:
Cost tier stratification separates premium connected devices from commodity injection formats.
- Injection Pens:Disposable and reusable pen systems dominate homecare dispensing through pharmacy benefit manager formularies. United States retail channels favor pen formats for Medicare reimbursement simplicity.
- Vials:Traditional multi-dose glass containers retain hospital preference for ICU insulin infusions and surgical glycemic protocols where dosing flexibility outweighs convenience.
- Pump Delivery:Continuous subcutaneous insulin infusion systems command premium pricing through integrated CGM-pump ecosystems. Tandem Diabetes Care and Medtronic pump hardware drives analog-specific cartridge demand.
- Prefilled Syringes:Ready-to-administer formats reduce nursing labor in perioperative settings. Group purchasing organization contracts favor these for standardized glycemic control bundles.
Standard injection formats generate highest shipment volumes; connected pump systems claim steepest expansion trajectory.
End User:
Customer type determines procurement channel and pricing negotiation leverage.
- Hospitals:Institutional procurement through group purchasing organizations aggregates demand across integrated delivery networks. Surgical glycemic protocol standardization drives rapid-acting analog volume.
- Homecare:Individual patient prescriptions flow through retail pharmacy and mail-order channels. Medicare Part D and commercial insurance formularies shape brand access.
- Diabetes Clinics:Specialized endocrinology practices influence pump-initiation decisions and intensive insulin regimen selection. Sample programs and device training support analog preference.
- Pharmacies:Community and specialty pharmacies manage biosimilar substitution under state-level interchangeability laws. Pharmacist notification requirements create friction against automatic switching.
Homecare channels move the largest prescription volumes; hospital procurement is expanding most quickly through perioperative protocol adoption.
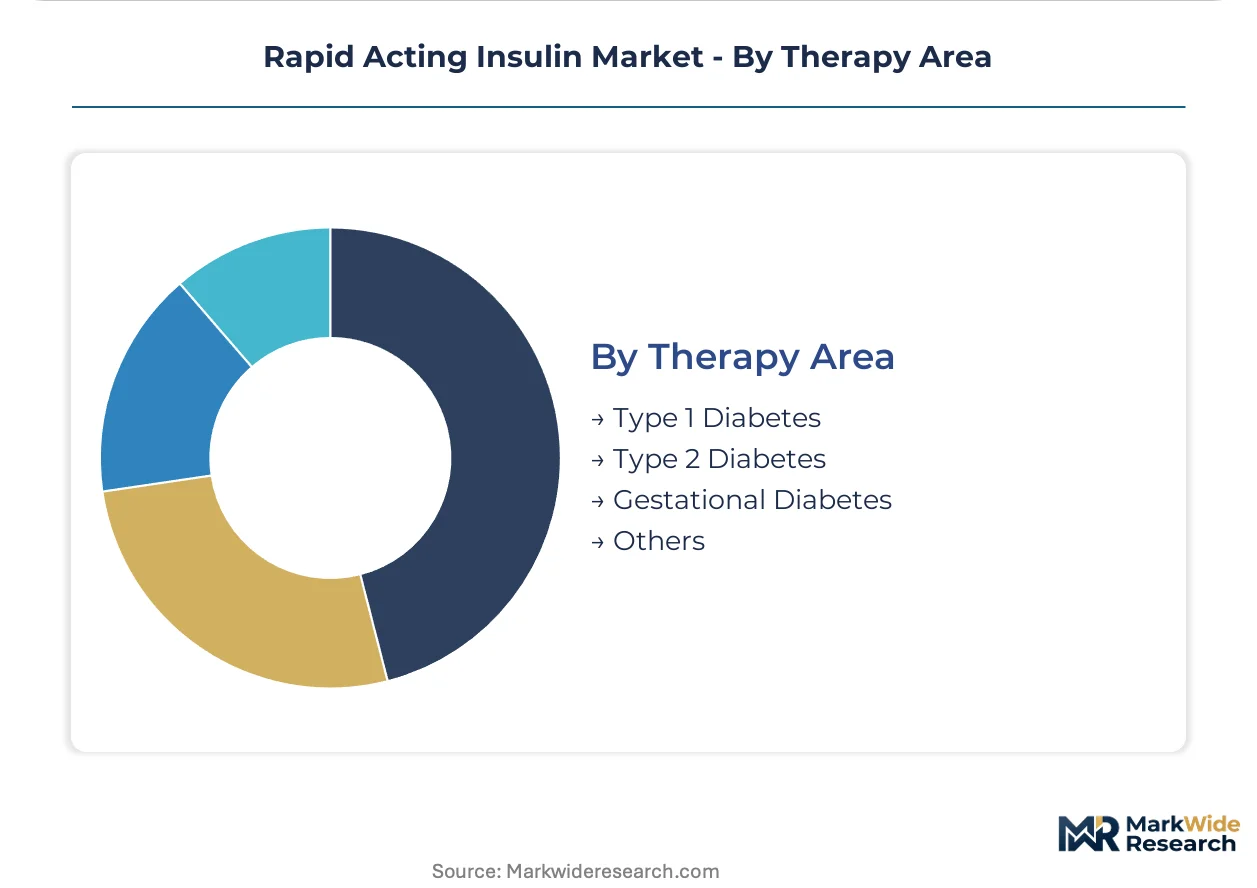
Therapy Area:
Disease severity and treatment intensity segment analog demand by physiological requirement.
- Type 1 Diabetes:Absolute insulin deficiency mandates prandial analog coverage for all carbohydrate intake. Pump and multiple daily injection regimens drive highest per-patient analog consumption.
- Type 2 Diabetes:Progressive beta-cell failure creates escalating prandial insulin need. Basal-bolus intensification protocols expand rapid-acting analog use beyond basal insulin alone.
- Gestational Diabetes:Pregnancy-specific glycemic targets favor rapid-acting analogs for precise mealtime control. Maternal-fetal medicine specialists prioritize lispro and aspart for established safety profiles.
- Others:Steroid-induced hyperglycemia and cystic fibrosis-related diabetes represent niche indications with institutional prescribing patterns.
Type 2 Diabetes accounts for broadest patient population; Type 1 Diabetes shows fastest per-capita analog intensity growth through technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant insulin active pharmaceutical ingredient production clusters in Denmark and the United States, creating geographic supply vulnerability for non-integrated manufacturers dependent on imported biological starting materials.
United States
Medicare Part D volume and continuous glucose monitor-insulin pump integration drive prescription concentration. FDA's biosimilar interchangeability pathway compresses reference product exclusivity periods while state-level pharmacy substitution laws create patchwork access conditions. Indianapolis anchors Eli Lilly's vertical integration from active pharmaceutical ingredient synthesis to finished-dose packaging.
Germany
National pricing authorities exert downward pressure on reference product premiums while expanding access pathways through statutory health insurance. EMA biosimilar guidelines shape product development investments and market access timelines for new entrants. The Rhine-Main region hosts major distribution hubs serving European hospital procurement consolidation through group purchasing organizations.
Denmark
Kalundborg's production complex represents the world's largest insulin manufacturing site, anchoring European supply for recombinant analogs. Danish regulatory alignment with EMA standards facilitates streamlined cross-border distribution. Copenhagen-based Novo Nordisk A/S dominates regional export volumes through integrated device-drug ecosystems.
India
Domestic diabetes prevalence and government-led access programs expand volume for recombinant insulin analogs in tier-2 and tier-3 cities. CDSCO regulatory pathways for biosimilars attract multinational manufacturing investments. Bengaluru facilities are broadening capacity to serve regulated and emerging markets with cost-optimized production.
China
Local insulin analog production scales through NMPA-approved manufacturing investments targeting substitution of imported reference products. National volume-based procurement compresses pricing premiums while expanding patient access. Yangtze River Delta clusters concentrate fill-finish operations for both domestic consumption and export markets.
Rapid Acting Insulin Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and regulatory sophistication, producing a tiered structure where integrated device-drug portfolios command premium positioning. The vendor base separates into three archetypes: vertically integrated innovators with captive API production, biosimilar specialists pursuing interchangeability designation, and regional formulators serving price-sensitive markets. Dominant competitive moves include capacity expansion in low-cost manufacturing jurisdictions and strategic partnerships for connected delivery ecosystem integration.
Among integrated innovators, Eli Lilly and Company, Novo Nordisk A/S, and Sanofi S.A. exemplify the archetype of manufacturers controlling active pharmaceutical ingredient synthesis through finished-dose packaging. These entities occupy positions defined by decades of regulatory dossier accumulation and established formulary access. Biocon Limited represents the biosimilar specialist tier, pursuing regulated market entry through manufacturing scale expansion and immunogenicity testing infrastructure. Regional formulators such as Gan & Lee Pharmaceuticals Co. Ltd. and Wockhardt Ltd. anchor cost-competitive positioning in emerging markets with localized production and distribution networks.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novo Nordisk A/S |
| Sanofi S.A. |
| Biocon Limited |
| MannKind Corporation |
| Adocia |
| Gan & Lee Pharmaceuticals Co. Ltd. |
| Wockhardt Ltd. |
| Merck & Co. Inc. |
| Others |
Cost & Logistics Intelligence
Device-drug bundling separates premium pump-integrated analogs from commodity vial formats, with that divergence producing divergent margin structures and supply chain configurations. Pump ecosystems command bundled pricing with captive cartridge supply chains, while standard injection formats compete on API cost efficiency and cold-chain logistics scale.
Pricing Analysis
Service-bundling intensity distinguishes connected delivery ecosystems from unbundled commodity formats. Three-tier pricing structure across premium, standard, and economy levels reflects device connectivity, formulation generation, and regional regulatory tier. Cost compression in biosimilar vials is intensifying because of Medicare reimbursement pressure and group purchasing organization aggregation. Hospital procurement managers show highest price sensitivity; automated insulin delivery users demonstrate lowest sensitivity due to therapy outcome prioritization.
Supply Chain Analysis
Dual-sourcing requirements for recombinant insulin API mandate multi-supplier qualification among non-integrated manufacturers seeking supply security. Production gravity centers on Denmark, the United States, and India, with fill-finish operations distributed across European and Asian markets. Manufacturing draws from microbial cell culture substrates, purification resins, and specialized cold-chain packaging. Single-source vulnerability concentrates in Kalundborg-derived API for European supply. Distribution runs through temperature-controlled logistics networks with validated storage at wholesaler and pharmacy levels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over recombinant API production and device ecosystem capture determines sustainable margin position.
For Market Incumbents: Lock in formulary access through integrated device-drug contracting with group purchasing organizations and hospital systems. Deepen backward integration into recombinant cell culture capacity to offset biosimilar API supply vulnerability. Prioritize real-world evidence generation for FDA interchangeability defense against automatic substitution threats. For New Entrants and Emerging Players: Rural and underserved diabetes clinics in tier-2 and tier-3 Indian cities represent the most penetrable buyer archetype for cost-optimized biosimilar analogs. Prefilled syringe formats for surgical glycemic protocols offer white-space entry with reduced device development burden. Pursue CDSCO regulatory alignment as a pathway to WHO prequalification and emerging market expansion. For Investors and Strategic Acquirers: Re-rating potential sits with biosimilar specialists possessing EMA-compliant manufacturing and immunogenicity testing infrastructure given FDA interchangeability designation catalysts. Five-to-ten-year viability hinges on substitution law harmonization and real-world evidence accumulation. Monitor state-level pharmacy substitution legislation as the critical inflection signal for automatic interchangeability penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Biocon Limited's Bengaluru expansion targets regulated market entry with cost-optimized recombinant analog output. |
| Regulatory Approval Pathway | FDA interchangeability designation accelerates pharmacy-level substitution and compresses reference product exclusivity windows. |
| Product Launch | Fiasp's niacinamide formulation captures automated insulin delivery users seeking accelerated postprandial glucose control. |
| Strategic Partnership | Tandem Diabetes Care pump hardware integration creates analog-specific cartridge demand with premium pricing capture. |
| Reimbursement Strategy | CMS coverage for CGM-pump integration drives Medicare Part D volume concentration among technology-adopting patients. |
Research Approach
Independent corroboration across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists underwrites the qualitative findings. Primary interviews with formulary directors and GPO contracts managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Rate-of-change decomposition across molecular formulation generation, delivery technology tier, end-user channel, and regional regulatory cluster structured the analytical framework. CAGRs were derived from segment-level growth trajectory analysis over the projection horizon. Forecast inputs incorporated biosimilar interchangeability designation timelines, pump adoption curves, and hospital glycemic protocol standardization rates.
Revisions become necessary when FDA interchangeability decisions, state substitution law harmonization, or API supply disruptions materialize. Deviation in biosimilar immunogenicity profiles or cold-chain logistics costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Diabetes Drugs Market