
 Sol-Gel Processing Market | 2026-2036
Sol-Gel Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Sol-Gel Processing Market Analytics
Modular coating kits that separate primer, barrier, and topcoat layers are repositioning procurement patterns across industrial buyers. SCHOTT AG leverages its vertically integrated fused silica operations to dominate optical coating substrates for semiconductor lithography. Evonik Industries AG anchors its position through high-purity metal alkoxide precursors that sustain consistent batch-to-batch reactivity. PPG Industries competes by extending its automotive refinish distribution network into thin-film sol-gel protective solutions.
Sol-gel processing synthesizes inorganic networks through hydrolysis and condensation of metal alkoxides in liquid solution, typically forming oxide films with thicknesses ranging from nanometers to micrometers at temperatures below conventional ceramic sintering thresholds. The technique produces uniform coatings, porous membranes, and ceramic fibers for applications requiring precise control over surface chemistry and microstructure. Coatings command the largest value share among product types due to recurring demand from corrosion protection and optical interference layers in electronics. The aerospace application segment generates premium pricing from FAA-certified thermal barrier systems on turbine blades, while semiconductor end users drive volume through wafer-level dielectric deposition processes. Nanotechnology-enabled formulations represent the fastest-expanding technology category as feature sizes shrink below 100 nanometers in advanced packaging.
EPA regulations on volatile organic compound emissions restrict solvent-based formulations in US manufacturing facilities, while REACH registration requirements in Europe mandate full chemical safety dossiers for precursor substances imported above one-ton thresholds. FDA oversight of implantable biomaterials shapes healthcare applications through biocompatibility testing protocols for sol-gel-derived bioactive glass. ISO 10993 standards further define cytotoxicity benchmarks that determine market access for medical device coatings. Stakeholders must monitor evolving dual-use export controls on precursor chemicals and decide whether to qualify alternative alkoxide sources before supply chain disruptions materialize.
Market Dynamics
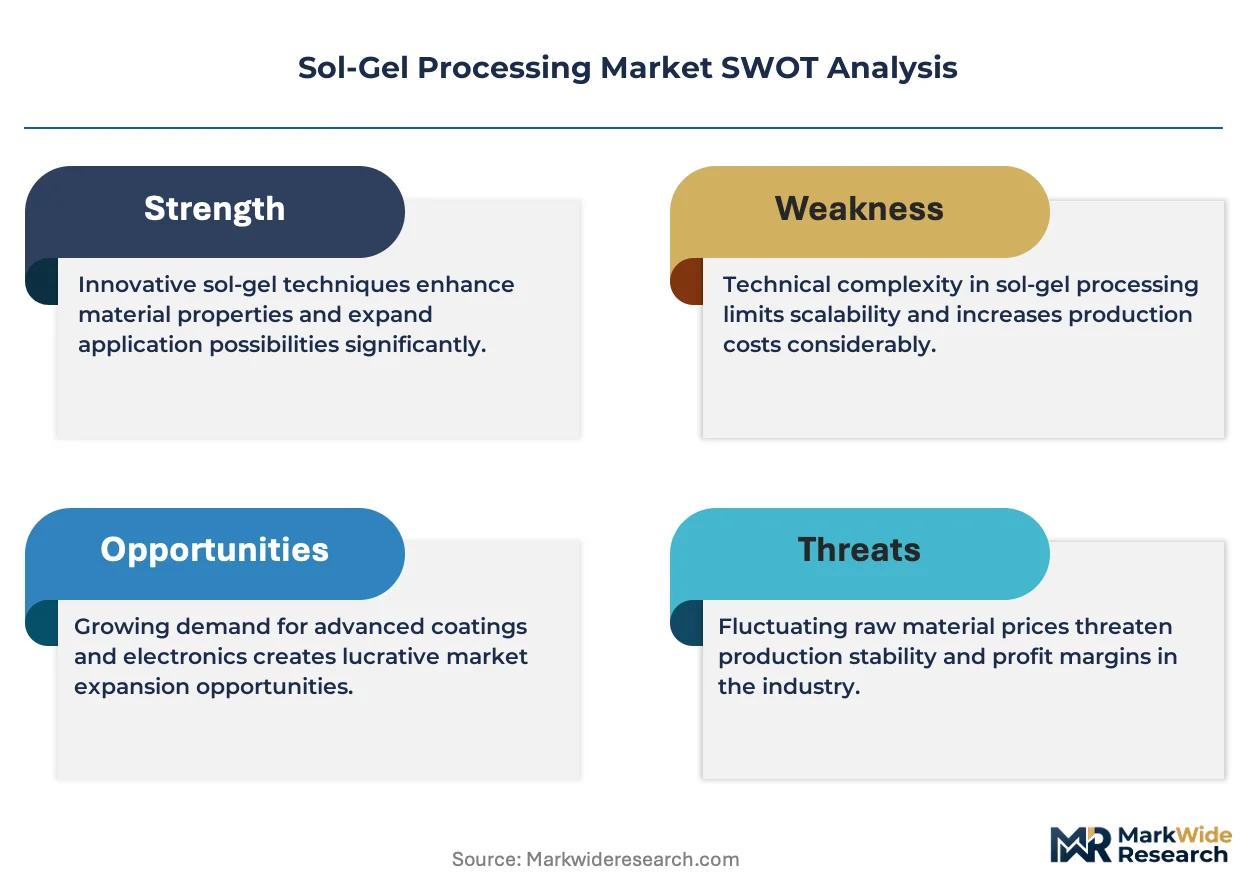
Water-based sol-gel formulations are displacing solvent-based systems as REACH compliance deadlines and EPA VOC emission ceilings harden procurement specifications across industrial coating buyers.
Growth Catalysts
- Thermal barrier coatings:Aerospace turbine blade manufacturers specify sol-gel ceramic matrices for FAA-certified high-temperature protection, creating recurring demand from engine OEMs.
- REACH registration thresholds:ECHA mandates for precursor substances above one-ton import volumes accelerate formulator migration toward compliant alkoxide supply chains.
- Wafer-level dielectric deposition:Semiconductor fabs integrate sol-gel spin-coating into advanced packaging nodes below 100 nanometers, driving volume procurement of high-purity formulations.
Market Restraints
- Metal alkoxide cost volatility:Tetraethyl orthosilicate and titanium alkoxide prices fluctuate with petrochemical feedstock indices, compressing formulation margins.
- German precursor concentration:High-purity metal alkoxide supply clusters disproportionately in Bavaria and Baden-Württemberg, exposing buyers to single-region disruption risk.
- Hydrolysis rate control:Batch-to-batch reactivity variance in atmospheric moisture conditions limits reproducibility for sub-micron film specifications.
Strategic Opportunities
- India precision ceramics:Bengaluru and Hyderabad semiconductor packaging clusters lack qualified domestic sol-gel coating suppliers, creating first-mover entry potential.
- EU Green Deal procurement mandates:Public infrastructure projects in Germany and France now specify low-carbon coating processes, advantaging water-based sol-gel bidders.
- Biomaterial convergence:Sol-gel bioactive glass synthesis combines with 3D-printed scaffold architectures for orthopedic implant applications.
Industry Challenges
- ISO 10993 cytotoxicity testing timelines:Medical device coatings require 12-18 month biocompatibility validation cycles that delay product launch windows.
- Legacy solvent-based line retrofit costs:Automotive refinish shops face capital outlays for ventilation and curing system modifications to handle aqueous sol-gel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sol-Gel Processing Market |
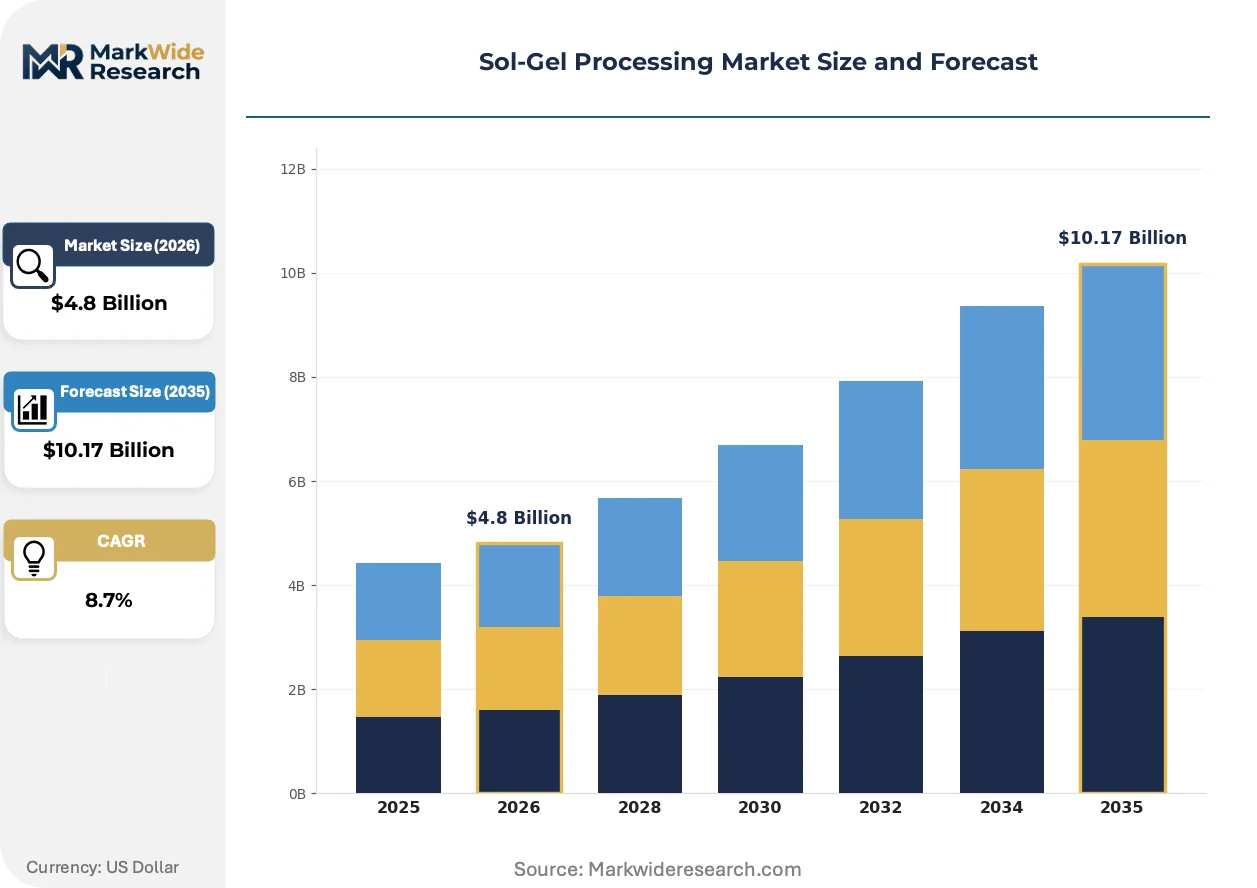
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Powders, Gels, Fibers Application: Aerospace, Electronics, Energy, Healthcare End User: Automotive, Construction, Consumer Goods, Semiconductor Technology: Nanotechnology, Photovoltaics, Ceramics, Biomaterials |
| Companies Covered | SCHOTT AG, PPG Industries, Evonik Industries AG, Merck KGaA, Akzo Nobel, Cabot Corporation, BASF SE, Heraeus Holding GmbH, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sol-Gel Processing Market Evolving Landscape
Process intensification through continuous-flow synthesis and precursor recycling loops is compressing production economics while nanostructured architectures unlock functional performance thresholds previously unattainable with conventional ceramic processing.
Hybrid organic-inorganic sol-gel formulations incorporating functionalized silanes and transition metal oxides is rewriting corrosion protection specifications for offshore wind turbine components. Coatings suppliers to North Sea installations now specify 25-year service life guarantees that only nanostructured barrier architectures can satisfy. The shift is compressing qualification timelines for conventional epoxy-polyurethane systems while expanding sol-gel coating procurement volumes.
EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) for surface coating operations now mandate 95% capture efficiency for solvent-based processes. Metal finishing facilities in Michigan and Ohio are retrofitting lines with aqueous sol-gel primer systems to avoid capital-intensive thermal oxidizer installations. The regulatory pressure is accelerating formulator R&D spending on ambient-cure water-based chemistries.
Modular coating kit architectures separate primer, barrier, and topcoat functions into discrete application stages that industrial buyers can source independently. Automotive OEMs in Germany now specify layer-specific performance warranties rather than bundled system guarantees, enabling tier-2 suppliers to displace integrated coating vendors. The unbundling is visible most acutely in Stuttgart and Munich precision engineering clusters where procurement teams optimize total applied cost through mix-and-match formulations.
Sol-Gel Processing Market Segmentation
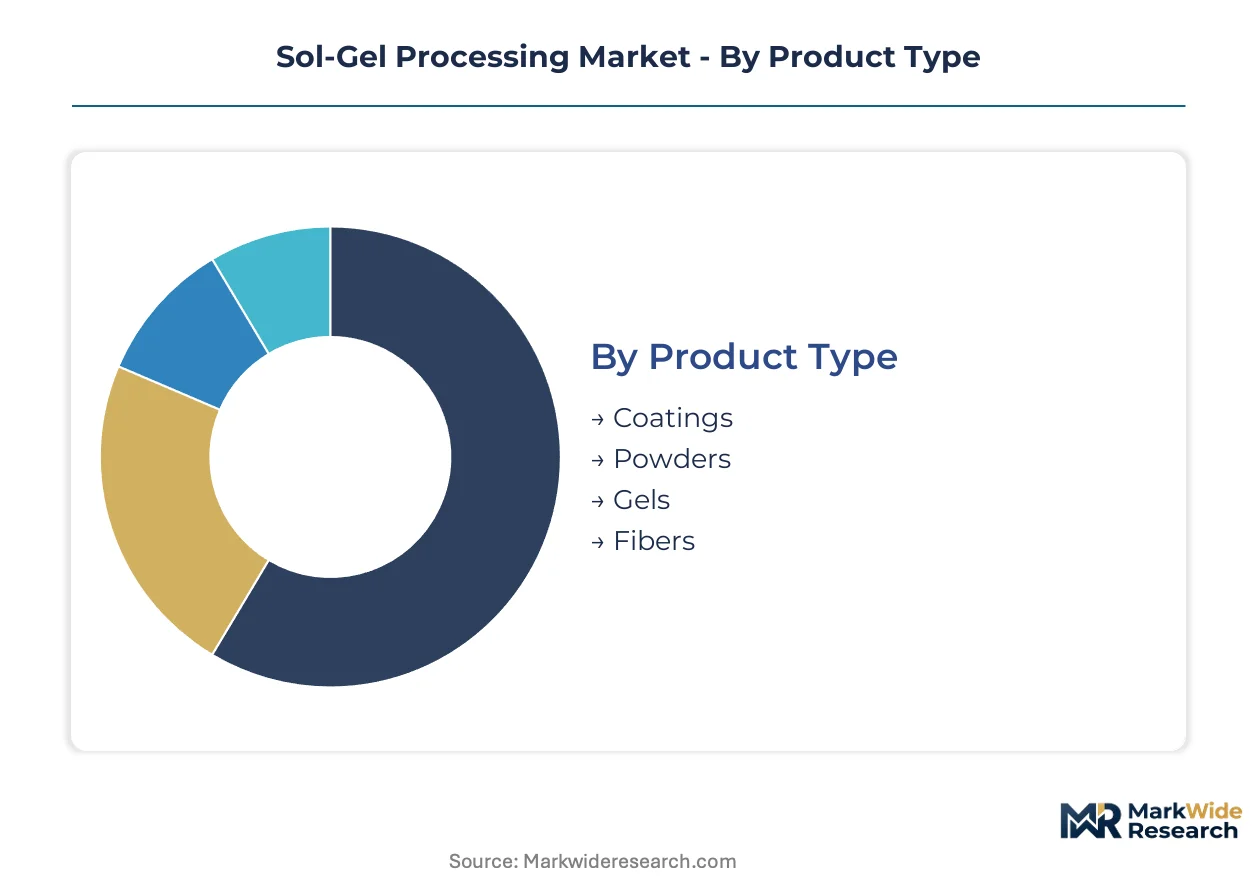
Sol-gel processing spans diverse certification regimes across product types and end uses. Aerospace coatings demand FAA airworthiness approvals, while healthcare applications navigate FDA and ISO 10993 biocompatibility protocols. Semiconductor fabs impose purity specifications that filter supplier pools.
Product Type:
FAA certification burdens concentrate on thermal barrier coatings for turbine blades, while semiconductor dielectrics face fab-specific qualification timelines. Powder and fiber segments encounter lighter regulatory overhead but tighter customer specifications.
- Coatings:Nanometer-to-micrometer oxide films formed through hydrolysis-condensation at sub-sintering temperatures. Demand concentrates in Stuttgart and Munich automotive clusters where corrosion protection specifications unbundle into layer-specific warranties. REACH registration thresholds for precursor substances above one ton compress formulation margins.
- Powders:Spherical ceramic particles synthesized through controlled nucleation in sol-gel matrices. Aerospace OEMs in Toulouse and Hamburg specify powder feedstock for thermal spray overlay coatings. Tetraethyl orthosilicate price volatility transmits directly to powder production economics.
- Gels:Three-dimensional inorganic networks retaining liquid phase for membrane and sensor substrates.
- Fibers:Continuous ceramic filaments drawn from viscous sol precursors for refractory insulation.
Leading the category by volume: Coatings. Growing fastest: Powders.
Application:
Margin structures diverge sharply across application verticals. Aerospace commands premium pricing for FAA-certified systems, while electronics drives volume through wafer-level deposition scale.
- Aerospace:FAA-certified thermal barrier systems on turbine blades generate recurring procurement from engine OEMs. Bavarian coating facilities supply Rolls-Royce and MTU Aero Engines with sol-gel ceramic matrices qualified for 1,200°C service environments.
- Electronics:Wafer-level dielectric deposition in advanced packaging nodes below 100 nanometers. Hyderabad and Bengaluru semiconductor clusters import high-purity formulations from German precursor suppliers.
- Energy:Offshore wind turbine corrosion protection with 25-year service guarantees.
- Healthcare:Biocompatible coatings for implantable devices facing 12-18 month ISO 10993 validation cycles.
Aerospace captures the highest unit margins. Electronics posts the steepest volume expansion trajectory.
End User:
Customer procurement sophistication varies by sector maturity. Automotive buyers leverage unbundled layer specifications, while semiconductor fabs enforce captive supplier qualification.
- Automotive:German OEMs in Stuttgart specify modular coating kits separating primer, barrier, and topcoat functions. Tier-2 suppliers displace integrated vendors through mix-and-match formulation sourcing.
- Semiconductor:Fab-level dielectric deposition demands batch-to-batch reactivity consistency below 0.5% variance. High-purity metal alkoxide supply clusters in Baden-Württemberg expose buyers to single-region disruption risk.
- Construction:EU Green Deal procurement mandates in France and Germany specify low-carbon coating processes.
- Consumer Goods:Optical coatings for electronics displays with interference layer specifications.
Automotive leads procurement volume. Semiconductor commands the most stringent qualification protocols.
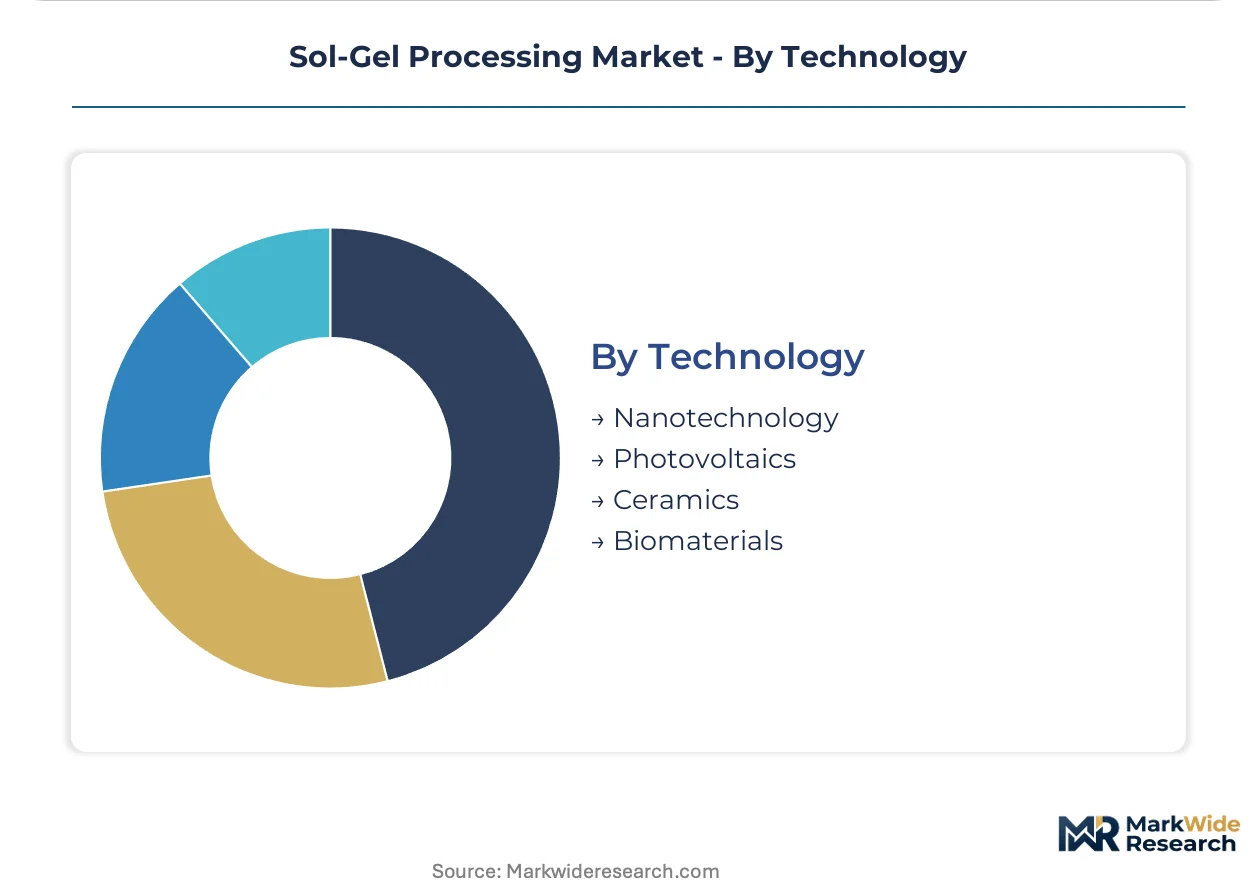
Technology:
Technology selection determines addressable market breadth. Nanotechnology-enabled formulations unlock sub-100 nanometer feature sizes, while biomaterials convergence creates orthopedic implant opportunities.
- Nanotechnology:Sub-100 nanometer architectures for advanced packaging and optical interference layers. Feature size shrinkage below 50 nanometers is climbing the fastest among technology categories.
- Biomaterials:Bioactive glass synthesis combined with 3D-printed scaffold architectures for orthopedic implants. FDA oversight shapes market access through biocompatibility testing protocols.
- Photovoltaics:Anti-reflective coatings and dopant diffusion sources for silicon cell manufacturing.
- Ceramics:Structural oxide and non-oxide components for high-temperature applications.
Nanotechnology dominates revenue concentration. Biomaterials is gaining share fastest through medical device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precursor suppliers dominate high-purity metal alkoxide production, while semiconductor packaging demand concentrates in South and East Asia. Aerospace coating procurement flows through Toulouse, Hamburg, and Bavarian industrial corridors.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate 95% capture efficiency for solvent-based coating operations. Metal finishing facilities in Michigan and Ohio retrofit lines with aqueous sol-gel primer systems to avoid thermal oxidizer capital outlays. Automotive refinish networks in Detroit extend procurement into thin-film protective solutions.
Germany
EU Green Deal procurement mandates specify low-carbon coating processes for public infrastructure projects. REACH registration thresholds above one ton compress formulation margins for imported alkoxides. Stuttgart and Munich precision engineering clusters unbundle coating specifications into layer-specific warranties.
China
Semiconductor fabs in the Yangtze River Delta integrate sol-gel spin-coating into advanced packaging nodes. MIIT standards on volatile organic compound emissions harden procurement specifications for industrial coating buyers. Shanghai and Suzhou lithography equipment clusters drive substrate demand.
India
Bengaluru and Hyderabad semiconductor packaging clusters lack qualified domestic sol-gel coating suppliers. Central Electricity Authority efficiency mandates accelerate solar cell anti-reflective coating procurement. Domestic precision ceramics capacity remains underdeveloped relative to import dependency.
France
EU Green Deal procurement mandates advantage water-based sol-gel bidders for public infrastructure coatings. ANSM oversight shapes healthcare application access through biocompatibility testing protocols. Toulouse aerospace engineering corridors source thermal barrier systems for turbine blade manufacturers.
Sol-Gel Processing Market Competitive Landscape
The competitive structure tilts toward vertically integrated chemical conglomerates with captive precursor supply. Tiered specialization separates high-purity alkoxide suppliers from application-specific coating formulators. Three archetypes dominate: diversified materials conglomerates with fused silica operations, specialty chemical houses with metal alkoxide expertise, and automotive refinish distributors extending into thin-film solutions. Consolidation pressure concentrates among coating formulators seeking backward integration into precursor supply.
Within the diversified materials tier, SCHOTT AG anchors optical coating substrate supply through in-house fused silica production. Evonik Industries AG exemplifies the specialty chemical archetype with high-purity metal alkoxide precursor operations. PPG Industries occupies a position bridging automotive refinish distribution into sol-gel protective solutions. These three entities represent distinct competitive vectors: captive raw material control, batch-to-batch reactivity consistency, and end-user channel access.
| Leading Market Players |
|---|
| SCHOTT AG |
| PPG Industries |
| Evonik Industries AG |
| Merck KGaA |
| Akzo Nobel |
| Cabot Corporation |
| BASF SE |
| Heraeus Holding GmbH |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Performance-grade divergence between FAA-certified thermal barrier systems and commodity corrosion coatings manifests in both pricing power and supply chain configuration. Premium aerospace formulations command sustained margin premiums through captive precursor supply in Bavaria, while standard industrial coatings face cost compression from volatile tetraethyl orthosilicate feedstock indices.
Pricing Analysis
Cost-down pressure on semiconductor-grade formulations accelerates because high-purity metal alkoxide supply clusters disproportionately in Baden-Württemberg. Three-tier pricing structure across aerospace-certified, fab-qualified, and industrial-standard levels tracks certification burden and batch-to-batch reactivity consistency. Price differentiation hinges on ECHA REACH registration status and ISO 10993 biocompatibility validation. Automotive refinish buyers exhibit highest price sensitivity, while semiconductor fabs prioritize reactivity consistency over unit cost.
Supply Chain Analysis
High-purity metal alkoxide supply rests on German specialty chemical producers, with secondary sourcing from Japanese and South Korean precursor houses. Tetraethyl orthosilicate, titanium alkoxides, and functionalized silanes constitute critical input dependencies. Single-region concentration in Bavaria and Baden-Württemberg exposes buyers to disruption risk from regional logistics constraints. Distribution runs through direct mill-to-fab contracts for semiconductor applications and automotive refinish distribution networks for industrial coatings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity precursor capacity constraints in Germany prop pricing premiums across qualified supply chains, creating durable margin pools for incumbent players with captive alkoxide production.
For Market Incumbents: Anchor market position through backward integration into metal alkoxide precursor supply and expansion of aqueous formulation capacity ahead of EPA NESHAP enforcement deadlines. Defend against emerging Indian precision ceramics entrants by accelerating fab qualification timelines in Hyderabad and Bengaluru clusters. Prioritize ECHA REACH dossier completion for import volumes above one-ton thresholds to maintain European market access. For New Entrants and Emerging Players: Domestic coating suppliers in India represent an underserved buyer archetype with concentrated semiconductor packaging demand and limited qualified local alternatives. Establish technical partnerships with Bengaluru lithography equipment clusters to bypass German supplier lock-in. Pursue EU Green Deal procurement mandates in French and German public infrastructure as a beachhead for water-based sol-gel credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical houses with metal alkoxide expertise and established fab qualification relationships. Five-to-ten year viability favors vertically integrated players with captive fused silica or precursor operations over pure-play coating formulators. Monitor ECHA registration compliance rates as an inflection indicator for supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive metal alkoxide production insulates margins from petrochemical feedstock volatility. |
| Aqueous Formulation Capacity Expansion | EPA NESHAP compliance positions suppliers for Michigan and Ohio metal finishing retrofits. |
| Fab Qualification in South Asia | Hyderabad and Bengaluru semiconductor clusters lack qualified domestic coating alternatives. |
| EU Green Deal Certification | Low-carbon process validation unlocks German and French public infrastructure procurement. |
| ISO 10993 Biocompatibility Investment | FDA-aligned testing protocols enable orthopedic implant coating market entry. |
Research Methodology
SEC 10-K filings, ECHA registration databases, and customs trade records formed the secondary backbone, supplemented by primary interviews with semiconductor fab procurement managers, aerospace coating technical directors, automotive refinish distribution heads, and specialty chemical R&D leads. Bottom-up volume estimates from application-specific consumption rates triangulated against top-down market sizing from precursor production capacity disclosures.
Historical trendline analysis of metal alkoxide pricing and coating formulation volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, application vertical, end-user industry, technology category, and regional production hub dimensions. CAGRs derived from regression-adjusted growth rates applied to qualified capacity expansion announcements and regulatory compliance timelines.
Revisions become necessary when REACH registration deadlines accelerate, EPA enforcement intensifies, or semiconductor node transitions alter dielectric deposition specifications. Forecasts reflect assumptions about precursor supply stability and fab qualification cycle durations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market