
 Bio-Wax Market | 2026-2036
Bio-Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Wax Market Analysis
Project finance tied to circular-economy feedstock certification is reconfiguring entry barriers for mid-scale bio-wax producers. Croda International leverages backward integration into vegetable oil refining to sustain margin control across European supply chains. Clariant anchors its position through R&D intensity in polymer-modified natural waxes. Koster Keunen competes via geographic dominance in North American beeswax distribution networks.
Bio-wax comprises renewable lipid-based materials—primarily esters, fatty acids, and long-chain hydrocarbons derived from botanical, animal, or synthesized biological feedstocks—that deliver controlled melting points between 45°C and 95°C for surface coating, barrier, and rheology-modification functions. The cosmetics application segment leads value generation due to premium formulation requirements for emulsion stability and skin-feel performance, while soy wax within the product type dimension exhibits the fastest volume trajectory as candle manufacturers switch from paraffin. Food industry applications remain structurally mature with lower margin pools concentrated in confectionery glazing and produce coating.
REACH in Europe, EPA bio-preferred standards in the United States, and BIS certification requirements in India each tighten compositional disclosure rules and restrict petrochemical-derived alternatives in consumer-facing products. These frameworks collectively shift procurement criteria toward verified feedstock traceability and carbon-intensity documentation. Stakeholders must monitor evolving biodegradability test protocols to anticipate which product grades will retain commercial access across major economies.
Market Dynamics
REACH compliance in Europe is compressing petrochemical wax availability while soy and beeswax suppliers scramble to certify traceability documentation for cosmetic and candle manufacturers.
Growth Catalysts
- REACH Phase-In Restrictions:ECHA's tightening substance authorization requirements block paraffin alternatives in personal care formulations across France, Germany, and Italy.
- Candle Industry Feedstock Switch:Soy wax processors capture volume from paraffin-dependent manufacturers seeking EPA bio-preferred certification for retail shelf placement.
- India BIS Labelling Mandate:The Bureau of Indian Standards now requires origin disclosure on packaged consumer goods, accelerating domestic procurement of certified botanical waxes.
Market Restraints
- Beeswax Supply Concentration:North American apiary networks face colony collapse pressure, concentrating raw material access among a handful of regional distributors.
- Vegetable Oil Price Volatility:Soy and palm oil feedstock costs swing with agricultural commodity futures, squeezing margin predictability for mid-scale refiners.
- Technical Performance Gaps:Plant-derived waxes exhibit inferior oxidative stability versus synthetic esters in high-temperature industrial coating applications.
Strategic Opportunities
- Brazilian Amazon Sourcing:Untapped carnauba palm processing capacity in Ceará and Piauí offers low-carbon-intensity feedstock for European cosmetic brands.
- Pharmaceutical-Grade Certification:USP and EP monograph compliance for excipient waxes opens formulation access to oral solid dosage and topical delivery systems.
- Digital Traceability Platforms:Blockchain-enabled supply chain verification satisfies EUDR deforestation-free requirements for palm and soy derivatives entering EU ports.
Industry Challenges
- Analytical Chemist Shortage:Specialized lipid characterization expertise for carbon-14 testing and contaminant screening remains scarce across contract laboratories.
- Multi-Standard Certification Overlap:Simultaneous compliance with REACH, EPA bio-preferred, and BIS frameworks extends product launch timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Wax Market |
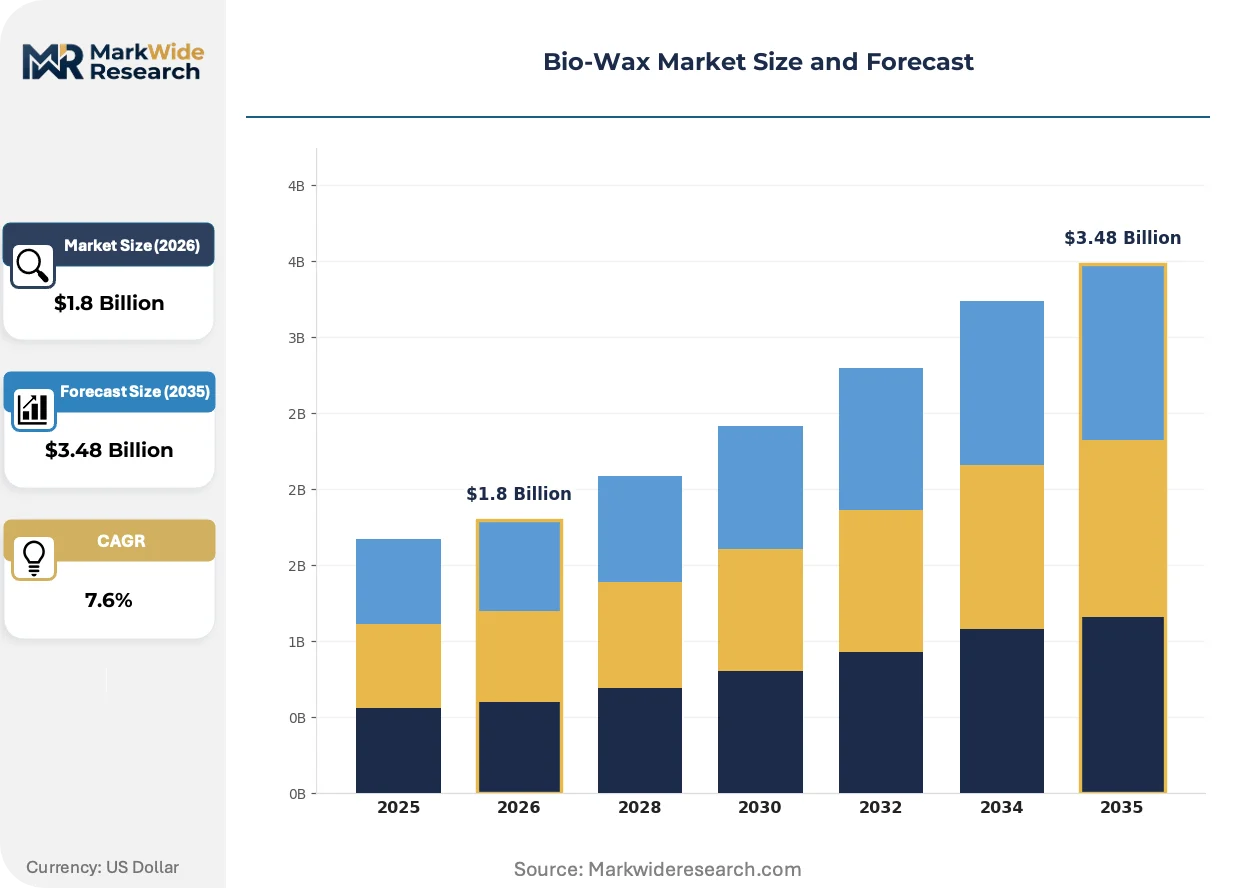
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Wax, Synthetic Wax, Beeswax, Soy Wax Application: Cosmetics, Food Industry, Pharmaceuticals, Craft Supplies Form: Granules, Block, Liquid, Pellets End User: Manufacturers, Retailers, Craftsmen, Chemists |
| Companies Covered | Clariant, Croda International, Ashland, Koster Keunen, Strahl & Pitsch, Evonik, Sonneborn, The Lubrizol Corporation, EcoSynthetix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Wax Market Emerging Trajectories
Formulation science is converging with supply chain verification technology to redefine what constitutes a premium-grade bio-wax across cosmetic, food, and industrial end-uses.
Polymer-modified natural wax technology is hybridizing conventional petroleum-derived rheology modifiers with plant-based esters to achieve tunable melting profiles. Cosmetic compounders in Germany and France adopt these hybrids at pilot scale for lipstick and foundation matrices. The structural consequence is compression of the performance gap between synthetic and bio-based alternatives in color cosmetic applications.
EU Deforestation Regulation enforcement timelines are accelerating due diligence requirements for soy, palm, and carnauba supply chains entering European ports. Importers must now geolocate production plots and document chain-of-custody back to farm gate. Smallholder-dependent wax categories face the steepest compliance burden, favoring vertically integrated plantation operators with captive traceability systems.
Long-term offtake contracting is displacing spot market purchasing among major candle and personal care manufacturers. Buyers in the United States and Germany now negotiate eighteen to thirty-six month supply agreements with fixed volume floors and price collars indexed to agricultural commodity futures. This shift concentrates procurement leverage among refiners with certified inventory buffers, squeezing speculative traders out of upstream sourcing channels.
Bio-Wax Market Segmentation
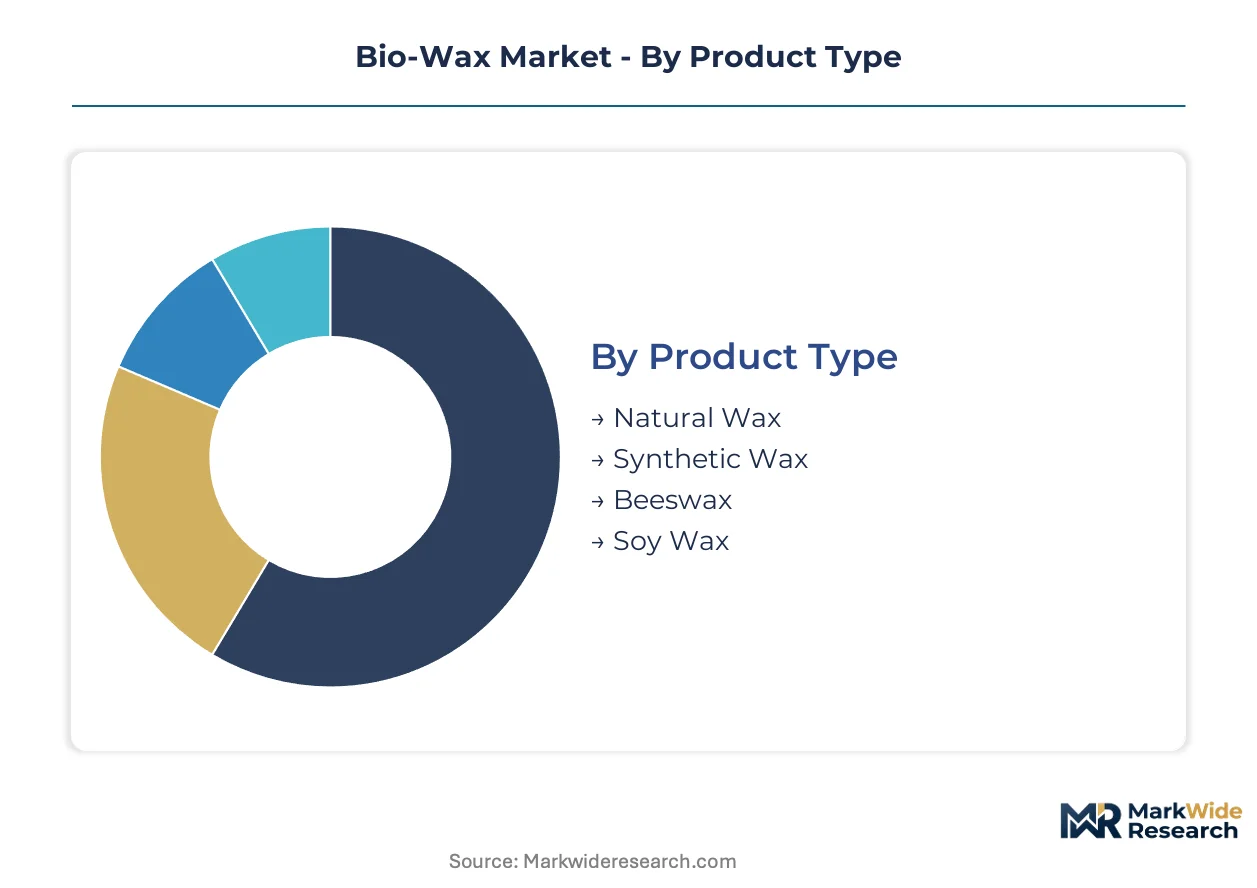
Segmentation in bio-wax markets reveals how procurement criteria diverge across regulatory environments and performance specifications. Understanding these fault lines enables suppliers to align certification investments with buyer willingness to pay for traceability and compositional purity.
Product Type:
Cost tier differentiation separates commodity feedstocks from certified specialty grades, with pricing power concentrating in segments offering verified carbon intensity documentation.
- Soy Wax:Hydrogenated soybean oil refined to controlled iodine values and melting points between 52°C and 57°C. Candle manufacturers in the United States and Germany are locking in eighteen-month offtake agreements to secure EPA bio-preferred certification for retail shelf placement.
- Beeswax:Secreted by Apis mellifera with characteristic ester composition yielding 62°C to 64°C melting profiles and natural emulsification properties. North American apiary networks face colony collapse pressure, concentrating raw material access among regional distributors serving premium cosmetic formulators.
- Natural Wax:Carnauba and candelilla botanical extracts with high carnaubic acid content for hardness and gloss.
- Synthetic Wax:Fischer-Tropsch or gas-to-liquid processes producing tailored chain-length distributions for industrial coating applications.
Soy wax holds installed capacity. Beeswax is rotating up the share rankings.
Application:
Margin pools vary dramatically by end-use, with pharmaceutical and cosmetic segments commanding price premiums tied to monograph compliance while food applications remain structurally mature.
- Cosmetics:Lipstick, foundation, and skincare formulations demanding emulsion stability, skin-feel performance, and REACH-compliant compositional disclosure. German and French manufacturers are expanding procurement of plant-derived waxes as ECHA authorization requirements tighten for paraffin alternatives.
- Pharmaceuticals:Excipient functions in oral solid dosage and topical delivery systems requiring USP and EP monograph compliance for controlled release and binding properties.
- Food Industry:Confectionery glazing and produce coating applications with lower margin concentration and established supply relationships.
- Craft Supplies:Hobbyist candle making and artisanal product segments with fragmented demand and price-sensitive purchasing.
Cosmetics commands pricing power. Pharmaceuticals is climbing the fastest.
Form:
Processing infrastructure and logistics economics favor specific physical configurations depending on melt-handling capabilities at customer facilities.
- Pellets:Uniform dimensions enabling automated feeding systems and precise dosing in high-volume candle manufacturing.
- Granules:Intermediate particle size for flexible melting kinetics in batch cosmetic compounding operations.
- Block:Traditional bulk format for artisanal craftsmen and small-scale processors with manual handling.
- Liquid:Pre-melted delivery for continuous industrial coating lines eliminating on-site thermal processing.
Pellets dominate volume throughput. Liquid is gaining share fastest.
End User:
Customer type determines contract structure, with manufacturers negotiating long-term offtake agreements while retailers and craftsmen operate on spot purchasing.
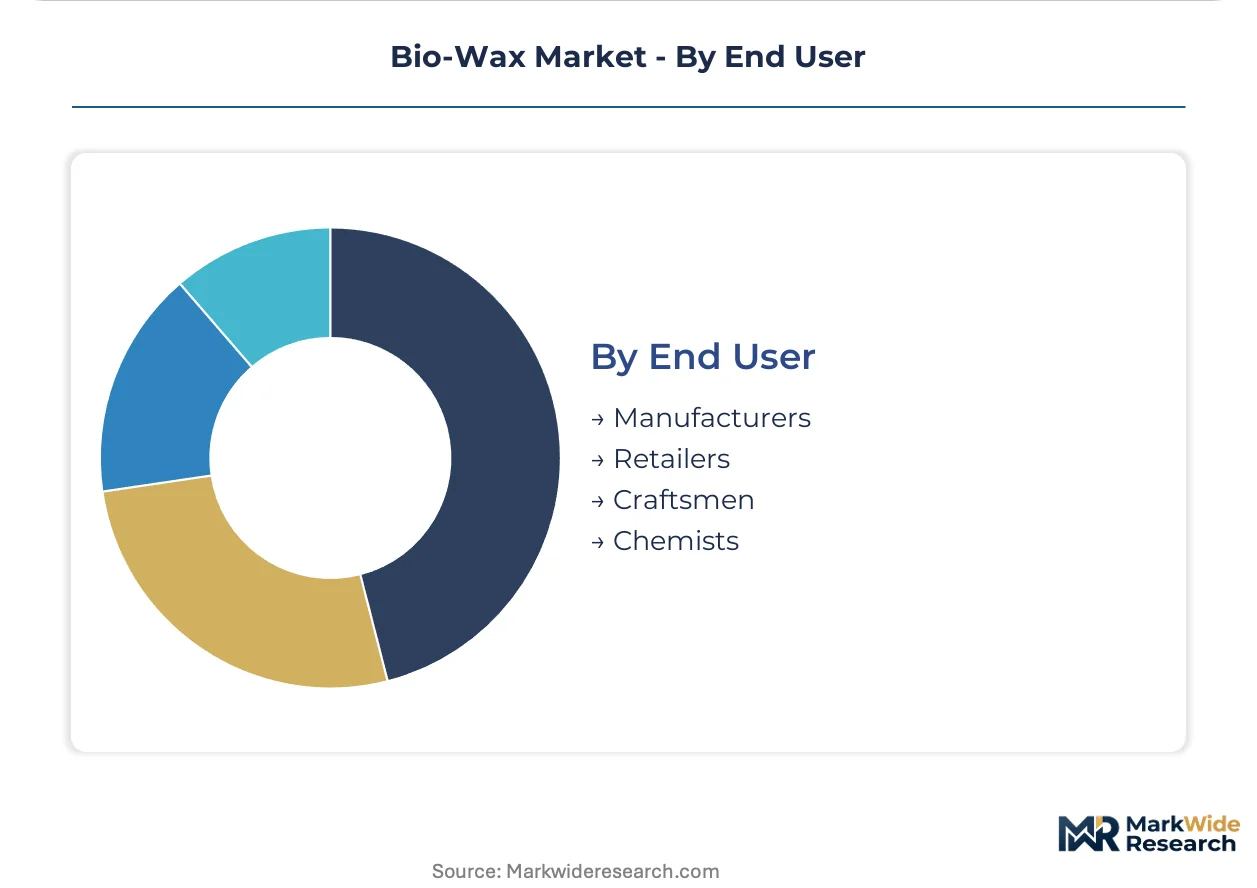
- Manufacturers:Candle, cosmetic, and pharmaceutical producers with certified inventory buffers and fixed-volume procurement agreements indexed to agricultural commodity futures.
- Retailers:Private label and branded goods distributors requiring documented feedstock traceability for consumer-facing sustainability claims.
- Craftsmen:Artisanal producers with fragmented demand and limited scale for certification investment.
- Chemists:Formulation laboratories and R&D facilities sourcing small quantities for product development and stability testing.
Manufacturers anchor procurement volume. Retailers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Phase-In Restrictions and EPA bio-preferred certification requirements are redirecting procurement flows toward verified feedstock traceability across major consuming economies. The analysis spans five countries where regulatory enforcement and manufacturing concentration intersect.
Germany
Cosmetic compounders in Hamburg and Frankfurt are locking in eighteen-month supply agreements for plant-derived waxes as ECHA authorization requirements tighten. The country's national chemical regulator enforces substance disclosure thresholds that block paraffin alternatives in personal care formulations. North Rhine-Westphalia hosts refining clusters where backward integration into vegetable oil processing secures margin control.
United States
Candle manufacturers in the Midwest and Southeast are switching feedstocks to capture EPA bio-preferred certification for retail shelf placement. The Environmental Protection Agency administers procurement preference standards that disadvantage petrochemical-derived competitors. Chicago-area processors negotiate long-term offtake contracts with fixed volume floors indexed to agricultural commodity futures.
France
Lipstick and foundation formulators in Paris and Lyon are expanding procurement of botanical waxes to satisfy REACH compositional disclosure rules. ECHA substance authorization requirements compress availability of synthetic alternatives in color cosmetic applications. The Île-de-France region concentrates R&D-intensive compounders piloting polymer-modified natural wax hybrids.
India
Domestic wax processors in Maharashtra and Gujarat are scaling certified botanical production as BIS labelling mandates accelerate origin disclosure requirements. The Bureau of Indian Standards now requires traceability documentation on packaged consumer goods entering retail channels. Mumbai-based refiners invest in carbon-intensity documentation systems to serve export markets.
Brazil
Carnauba palm processors in Ceará and Piauí are attracting European cosmetic brand procurement due to low-carbon-intensity feedstock credentials. The country's national agricultural export regulator enforces deforestation-free documentation for botanical derivatives entering EU ports. Northeastern processing clusters leverage captive plantation traceability to satisfy EUDR due diligence timelines.
Bio-Wax Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: multinational chemical conglomerates with captive R&D infrastructure, mid-scale specialists with backward integration into feedstock refining, and regional distributors with concentrated access to apiary or plantation networks. Competitive positioning depends on certification breadth, traceability system maturity, and long-term contracting capacity. The dominant competitive moves are strategic partnerships with agricultural cooperatives for feedstock security and portfolio diversification into pharmaceutical-grade monograph compliance.
Within the multinational tier, Clariant and Croda International exemplify archetypes built on R&D intensity and backward integration respectively. Koster Keunen occupies a position among North American distributors with concentrated apiary network access. These three anchors illustrate how geographic feedstock dominance, vertical control over refining stages, and certification breadth differentiate competitive outcomes in procurement negotiations with cosmetic and pharmaceutical manufacturers.
| Leading Market Players |
|---|
| Clariant |
| Croda International |
| Ashland |
| Koster Keunen |
| Strahl & Pitsch |
| Evonik |
| Sonneborn |
| The Lubrizol Corporation |
| EcoSynthetix |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European vegetable oil refining is forcing buyers into longer contracting cycles and compressing spot market liquidity. This utilization squeeze simultaneously elevates supplier pricing power and accelerates backward integration investments among mid-scale compounders seeking feedstock security.
Pricing Analysis
Certification level (REACH-compliant versus standard technical grade) creates the primary spread between commodity and specialty bio-wax tiers. Contract-based long-term offtake agreements with fixed volume floors now dominate procurement between German cosmetic manufacturers and vegetable oil refiners. Price differentiation intensifies around carbon-intensity documentation and EUDR geolocation verification, with uncertified soy wax facing cost compression from traceable Brazilian carnauba alternatives. Candle manufacturers exhibit highest price sensitivity due to thin retail margins, while pharmaceutical formulators accept premium tiers for USP and EP monograph compliance.
Supply Chain Analysis
Extended payment terms from European cosmetic brands are squeezing working capital across mid-scale Brazilian carnauba processors. Geographic supply concentration centers on Brazil for carnauba palm, the United States for soy wax refining, and Germany for hydrogenated vegetable oil processing. Raw material dependencies rest on soybean futures, palm kernel derivatives, and apiary-derived beeswax subject to colony collapse volatility. Single-source vulnerability runs through North American beeswax distribution networks where regional distributors control fragmented apiary access. Distribution runs through vertically integrated refiners with certified inventory buffers rather than speculative traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Petroleum-derived synthetic waxes retain cost advantages in high-temperature industrial coatings, threatening to recapture share if plant-derived alternatives fail to close oxidative stability gaps. Incumbents must navigate this substitution threat while defending premium positioning in cosmetic and pharmaceutical segments.
For Market Incumbents: Pre-empt synthetic wax recapture by accelerating polymer-modified natural wax R&D to close performance gaps in industrial coating applications. Secure Brazilian carnauba sourcing through equity stakes in Ceará processing cooperatives before EUDR enforcement tightens. Certification investment in pharmaceutical-grade monograph compliance anchors pricing power against commodity tier erosion. For New Entrants and Emerging Players: Pursue pharmaceutical excipient white space where USP and EP compliance barriers filter out commodity refiners. Target Indian domestic market expansion under BIS labelling mandates accelerating origin disclosure requirements. Go-to-market leverage rests on blockchain-enabled traceability platforms satisfying EUDR deforestation-free documentation for European cosmetic brand procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Brazilian plantation-to-port infrastructure as EUDR geolocation requirements mandate captive traceability systems. Long-term viability favors vertically integrated specialists with certified feedstock control rather than trading-dependent distributors. Acquisition target archetype: mid-scale European refiners with backward integration into vegetable oil processing and REACH-compliant product portfolios. Signal to watch: divergence between spot and contract pricing for certified versus uncertified soy wax grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Refining | Croda International's vegetable oil processing control secures margin stability across REACH-pressured European supply chains. |
| Pharmaceutical-Grade Certification Investment | USP and EP monograph compliance opens formulation access to oral solid dosage manufacturers with stringent excipient standards. |
| Blockchain Traceability Platform Deployment | Digital supply chain verification satisfies EUDR deforestation-free requirements for carnauba and soy derivatives entering EU ports. |
| Long-term Offtake Contracting | Eighteen to thirty-six month supply agreements with fixed volume floors displace spot purchasing among major candle manufacturers. |
| Brazilian Sourcing Expansion | Ceará and Piauí carnauba processing capacity offers low-carbon-intensity feedstock credentials for European cosmetic brand procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, candle manufacturing procurement leads, vegetable oil refinery technical directors, pharmaceutical excipient buyers, and Brazilian carnauba cooperative managers. Secondary validation drew from ECHA substance authorization databases, EPA bio-preferred procurement standards, BIS labelling mandate circulars, customs trade flows for hydrogenated vegetable oils, and SEC filings from disclosed market participants. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Calibration against historical price spreads between certified and uncertified grades anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application margin pool, physical form configuration, and end-user contract structure. CAGRs were derived from trend extrapolation of regulatory enforcement timelines and feedstock switching rates. Forecast inputs incorporated vegetable oil futures volatility patterns and EUDR implementation phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity futures, euro-dollar exchange rates, or trans-Atlantic shipping costs would shift the trajectory. Forecasts reflect documented assumptions regarding REACH authorization timelines and EPA procurement preference enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market