
 Plasticizer Alcohols Market | 2026-2036
Plasticizer Alcohols Market Size, Share, and Industry Trends Forecast 2026-2036
Plasticizer Alcohols Market Analytics
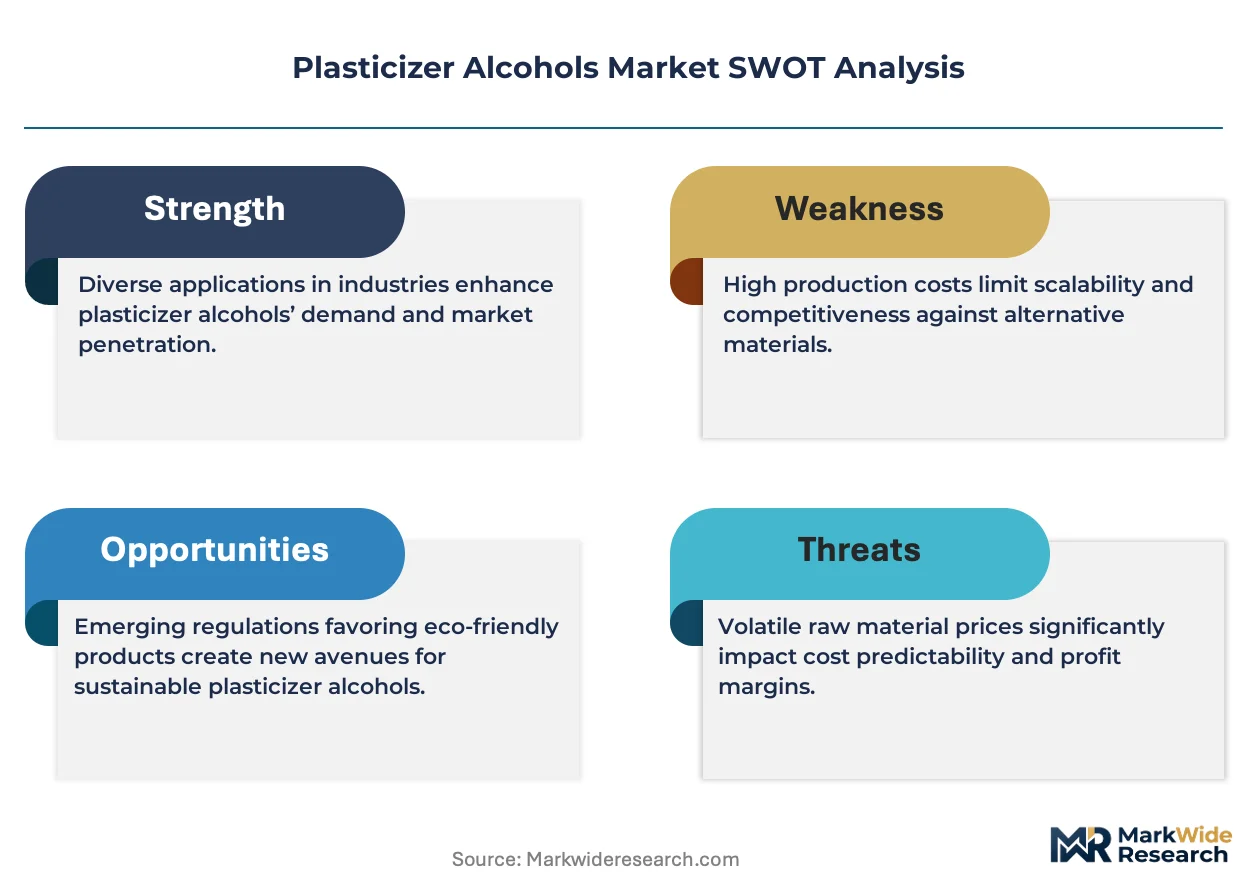
High-purity specification grades for medical and food-contact applications is collapsing the legacy commodity tier as buyers prioritize compliance over cost. BASF SE leverages its integrated C4 value chain to control feedstock quality from butadiene extraction through oxo-alcohol output. Eastman Chemical Company differentiates through specialized non-phthalate plasticizer alcohols that serve regulated end uses in healthcare and children's products. Sasol Limited anchors African supply with Fischer-Tropsch-derived alcohol streams that compete on carbon chain specificity.
Plasticizer alcohols are C4-C13 branched or linear aliphatic alcohols produced via oxo synthesis or hydroformylation, typically exhibiting boiling points between 183°C and 255°C and purity thresholds above 99.5% for premium grades. These alcohols esterify with phthalic anhydride or adipic acid to form plasticizers that impart flexibility, durability, and processability to polyvinyl chloride and other polymers. Glycerol Monostearate and Sorbitol segments within the product type dimension are gaining structural share as bio-derived alternatives attract formulation investment from compounders seeking renewable content. The construction end use industry retains the dominant margin pool due to scale, though automotive applications are shifting fastest toward low-VOC and migration-resistant grades driven by interior air quality standards.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements through ECHA are restricting legacy phthalate plasticizers and redirecting demand toward approved alcohol precursors. FDA food-contact notifications and EU Regulation 10/2011 on plastic materials further constrain which plasticizer alcohols may enter packaging and medical device supply chains. BIS certification in India and China's GB standards through SAMR add compliance layers for market access across major manufacturing geographies. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that limits geographic flexibility.
Market Dynamics
Phthalate-free formulation mandates across multiple jurisdictions are compressing legacy alcohol demand while redirecting capital toward bio-based and non-phthalate precursor synthesis. This regulatory compression is restructuring supplier portfolios and end-use qualification requirements faster than capacity can reconfigure.
Growth Catalysts
- REACH Annex XIV Authorizations:European restrictions on DEHP and BBP are accelerating compounder migration toward adipate and trimellitate ester precursors. Medical device manufacturers now specify high-purity C8-C10 alcohol grades for tubing and bag applications.
- China Infrastructure Pipeline:SAMR-approved GB standards for flexible PVC in water and drainage systems sustain large-volume 2-ethylhexanol consumption. Provincial infrastructure bonds in Sichuan and Guangdong are funding residential and commercial construction through 2030.
- Bio-based Feedstock Integration:Oleochemical routes from palm and rapeseed oils are achieving cost parity with petrochemical oxo-alcohols in select European formulations. Compounders seeking renewable content certificates are qualifying glycerol-derived monostearate alternatives.
Market Restraints
- Propylene-Butadiene Feedstock Volatility:C4 olefin supply fluctuations from steam cracker operating rate adjustments directly impact oxo-alcohol production economics. Asian naphtha price spreads compress margin predictability for integrated producers.
- Geographic Supply Concentration:Fischer-Tropsch-derived C12-C13 alcohol output remains concentrated in South African and Middle Eastern gas-to-liquids facilities. Logistics bottlenecks through the Cape of Good Hope route create delivery uncertainty for European buyers.
- Technical Purity Limitations:Bio-based alcohol streams struggle to meet sub-500ppm total carbonyl specifications required for automotive interior air quality certifications. Purification capex for renewable grades exceeds petrochemical equivalent by 40-60%.
Strategic Opportunities
- India PLI Scheme Alignment:Domestic PVC compounding capacity expansion under the Production Linked Incentive scheme is creating captive demand for plasticizer alcohol imports. BIS certification timelines for phthalate-free grades present first-mover positioning for qualified suppliers.
- Automotive Low-VOC Specifications:SAE J3077 and OEM-specific interior air quality standards are mandating migration-resistant plasticizer systems. C9-C11 linear alcohol precursors for trimellitate esters are penetrating premium vehicle segments.
- Digital Formulation Platforms:AI-driven plasticizer blend optimization is reducing qualification cycle times from 18 months to 6 months for new alcohol grades. Cloud-based regulatory compliance tracking is enabling real-time formulation adjustments across multi-jurisdictional product lines.
Industry Challenges
- Cross-Contamination Control:Multi-product alcohol plants face batch segregation requirements that reduce effective capacity utilization. FDA food-contact notification holders must maintain dedicated storage for pharma-grade versus industrial-grade streams.
- Legacy Ester Requalification:Compounders holding decades-old phthalate formulations face customer-mandated reformulation deadlines that outstrip technical service bandwidth. Simultaneous multi-certification pursuit for REACH, FDA, and GB standards strains regulatory affairs departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasticizer Alcohols Market |
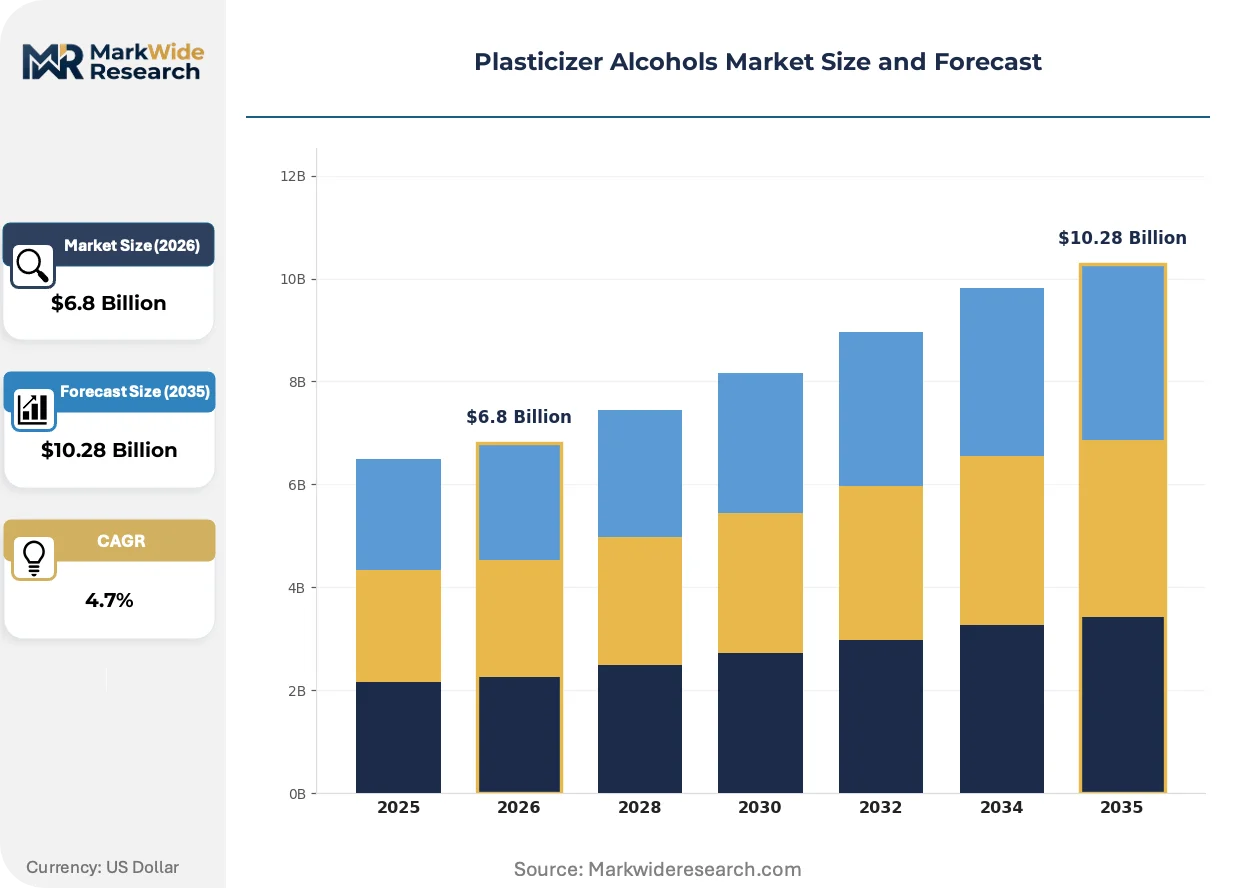
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerol Monostearate, Sorbitol, Ethylene Glycol, Triethylene Glycol End Use Industry: Construction, Automotive, Food & Beverage, Healthcare Formulation Type: Water-Soluble, Oil-Soluble, Solid, Liquid Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, ExxonMobil Chemical Company, Eastman Chemical Company, Dow Inc., Evonik Industries AG, Sasol Limited, Arkema S.A., LG Chem, Oxea GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasticizer Alcohols Market Evolving Landscape
Formulation science is converging with digital compliance tools to compress product development cycles while expanding the addressable application set for non-phthalate plasticizer systems. Three intersecting developments are reshaping competitive positioning in precursor alcohol supply.
Enzymatic esterification processes using immobilized lipase biocatalysts are fragmenting traditional acid-catalyzed production economics. Specialty compounders serving cosmetics and food-contact niches are adopting these routes for C8-C10 adipate esters. The technology is fragmenting volume concentration among large-scale petrochemical producers by enabling smaller-batch, higher-margin production at distributed sites.
EPA risk evaluations under the Toxic Substances Control Act Section 6 are systematically restricting legacy phthalate manufacturing and import. Industrial processors in the United States are accelerating DINP and DIDP phaseouts ahead of formal rulemaking timelines. Wire and cable jacketing applications are most affected, with compounders stockpiling approved non-phthalate alcohol precursors through 2025-2026.
Certification-driven procurement is compressing supplier qualification cycles from multi-year engagements to 90-day competitive tenders. Automotive OEMs and medical device contract manufacturers are unbundling formulation development from volume supply agreements. This pattern is most visible in Germany and the United States, where sustainability scorecards now weight renewable content above unit cost in supplier selection algorithms.
Plasticizer Alcohols Market Segmentation
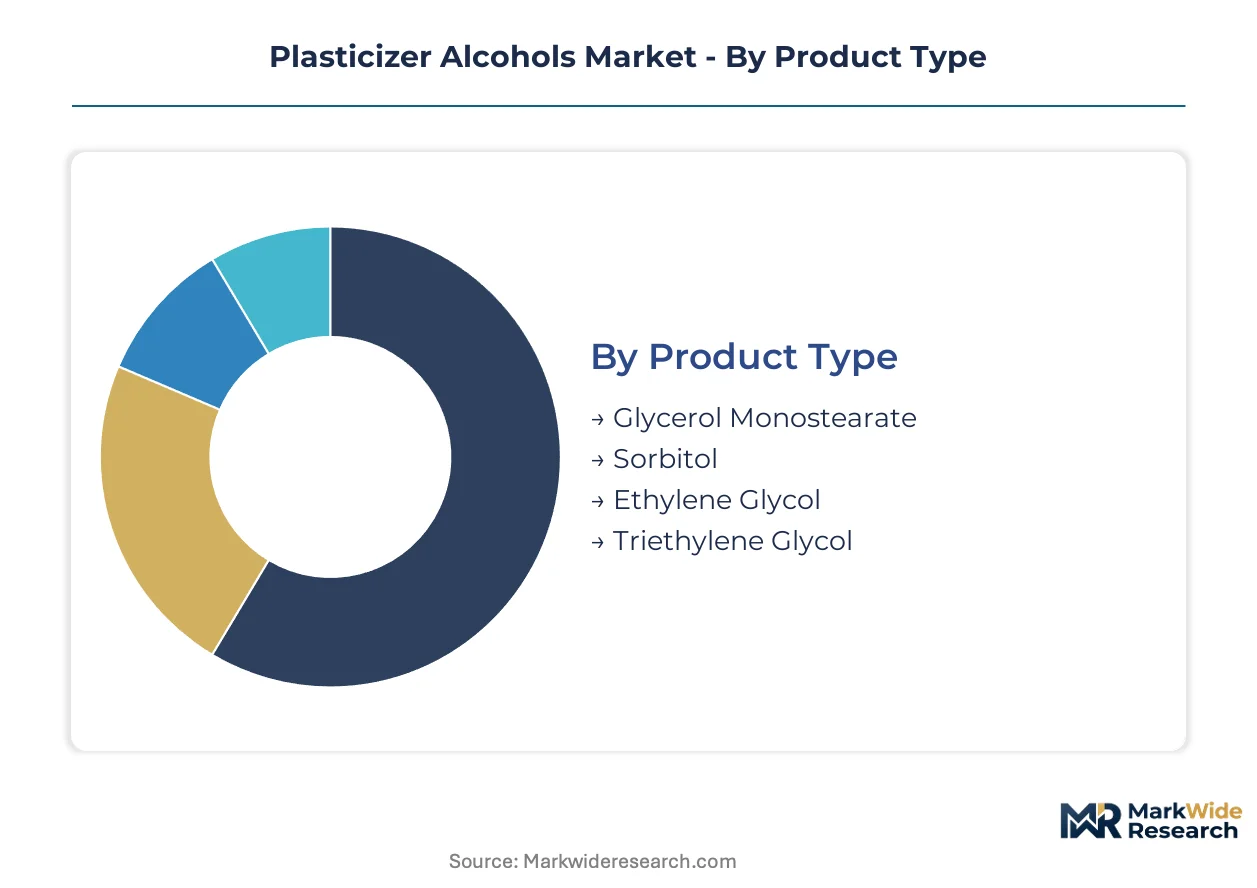
Segmentation in plasticizer alcohols reveals how substitution pressures and regulatory compliance reshape procurement priorities across distinct chemical families and end-use specifications. Buyers now segment suppliers by purity grade and certification status rather than carbon chain length alone.
Product Type:
Substitution pressure from bio-based feedstocks hits synthetic polyols hardest while glycerol-derived platforms gain formulation share in regulated applications.
- Glycerol Monostearate:Derived from vegetable oil transesterification, this bio-based alcohol meets FDA food-contact notifications and EU Regulation 10/2011 for packaging films. European compounders seeking renewable content certificates are qualifying glycerol monostearate for flexible PVC in medical tubing where DEHP replacement is mandated.
- Sorbitol:Hydrogenated glucose syrup yields this polyol plasticizer alcohol with hygroscopic properties suited to moisture-sensitive polymer systems. Sorbitol-derived esters penetrate personal care and pharmaceutical packaging segments in Germany and France where biogenic content thresholds apply.
- Ethylene Glycol:Petrochemical diol produced via ethylene oxide hydration serves industrial-grade plasticizer precursors for wire insulation and flooring.
- Triethylene Glycol:Higher molecular weight glycol derivative offers reduced volatility profiles for high-temperature PVC processing applications.
Glycerol monostearate anchors the volume base among bio-derived alternatives while sorbitol gains share at the steepest rate in premium cosmetic and medical formulations.
End Use Industry:
Margin compression varies sharply by end-use, with construction tolerating commodity grades and automotive demanding sub-500ppm carbonyl specifications.
- Construction:Flexible PVC for water pipes, drainage systems, and flooring membranes consumes 2-ethylhexanol and C9-C11 linear alcohols at scale. China's provincial infrastructure bonds in Sichuan and Guangdong sustain large-volume consumption through SAMR-approved GB standards for building materials.
- Automotive:Interior air quality certifications under SAE J3077 mandate migration-resistant trimellitate esters derived from C9-C11 linear alcohol precursors. German OEMs now specify renewable content minimums in supplier scorecards, redirecting procurement toward certified bio-based alcohol streams.
- Food & Beverage:FDA food-contact notifications and EU 10/2011 compliance constrain which alcohol precursors may enter food packaging supply chains.
- Healthcare:REACH Annex XIV authorizations restrict DEHP and BBP in medical devices, accelerating adipate and trimellitate ester adoption for tubing and blood bags.
Construction anchors the volume base through infrastructure deployment while automotive climbs the fastest toward low-VOC specification premiums.
Formulation Type:
Physical state determines logistics economics and blending flexibility, with liquid formats dominating continuous compounding operations.
- Water-Soluble:Polyol-based systems enable aqueous dispersion in coating and adhesive applications where solvent recovery is uneconomical.
- Oil-Soluble:Traditional phthalate and adipate ester precursors integrate with hydrocarbon-based compounding oils for flexible PVC calendering.
- Solid:Flaked or pelletized glycerol monostearate reduces shipping costs for distant bio-refinery supply and enables dust-free handling in food-contact facilities.
- Liquid:Pumpable C4-C13 oxo-alcohols feed continuous esterification reactors at integrated petrochemical sites.
Liquid formats retain the dominant volume position while solid glycerol monostearate expands most quickly in distributed bio-refinery supply models.
Distribution Channel:
Channel selection reflects order size, technical service requirements, and the geographic spread of compounder facilities.
- Direct Sales:Integrated producers BASF and Eastman supply automotive and medical device manufacturers under long-term qualification agreements with dedicated technical service support.
- Distributors:Regional chemical distributors hold inventory positions for mid-tier compounders requiring mixed-product shipments and just-in-time delivery.
- Online Retail:E-procurement platforms serve small-batch specialty compounders in cosmetics and artisan polymer processing with rapid qualification documentation.
- Wholesalers:Volume aggregators supply industrial flooring and wire jacketing compounders in China and India where price sensitivity dominates procurement.
Direct sales anchor the premium grade volume base while online retail gains share fastest among small-batch specialty formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major plasticizer alcohol markets, with integrated producers in Germany and the United States maintaining feedstock self-sufficiency while Asian compounders rely on seaborne C4-C13 alcohol shipments. Trade flows concentrate through Rotterdam and Singapore hubs, where storage terminals buffer against propylene-butadiene volatility.
China
Provincial infrastructure bonds in Sichuan and Guangdong sustain large-volume 2-ethylhexanol consumption for water pipe and drainage applications. SAMR-administered GB standards for flexible PVC building materials redirect procurement toward phthalate-free alcohol precursors. Yangtze River Delta petrochemical clusters near Shanghai and Ningbo operate the world's largest oxo-alcohol production trains, supplying domestic compounders and Southeast Asian export markets.
Germany
Automotive OEMs in Stuttgart and Munich mandate renewable content minimums in supplier scorecards, accelerating bio-based alcohol qualification. ECHA REACH Annex XIV authorizations restrict DEHP and BBP in medical tubing, redirecting demand toward adipate ester precursors. BASF's Ludwigshafen complex anchors European supply through integrated C4 value chain control from butadiene extraction to finished oxo-alcohol output.
United States
EPA Toxic Substances Control Act Section 6 risk evaluations systematically constrain legacy phthalate manufacturing, with wire and cable compounders stockpiling approved non-phthalate precursors. Houston Ship Channel petrochemical corridors maintain flexible PVC compounding capacity serving Gulf Coast construction markets. FDA food-contact notification holders face batch segregation requirements that reduce effective multi-product alcohol plant utilization rates.
India
Production Linked Incentive scheme expansion for domestic PVC compounding creates captive demand for plasticizer alcohol imports, particularly phthalate-free grades requiring BIS certification. Maharashtra and Gujarat industrial corridors concentrate flexible PVC processing for packaging and construction applications. Mumbai and Ahmedabad distribution hubs mediate between international suppliers and mid-tier compounders seeking just-in-time delivery.
South Africa
Sasol's Secunda gas-to-liquids facility anchors Fischer-Tropsch-derived C12-C13 alcohol output competing on carbon chain specificity for premium trimellitate ester applications. Durban port logistics constrain European delivery schedules through Cape of Good Hope routing uncertainty. Johannesburg chemical distributors hold inventory positions serving sub-Saharan African flooring and wire jacketing compounders.
Plasticizer Alcohols Market Competitive Landscape
Listed leaders compete with private specialists across feedstock integration depth, with publicly traded petrochemical majors commanding capital markets access for capacity expansion while family-owned oxo-alcohol producers retain flexibility in specialty grade allocation. Market structure tiers into three archetypes: integrated C4 value chain operators, Fischer-Tropsch-derived alcohol specialists, and bio-based platform developers. Dominant competitive moves include backward integration into propylene-butadiene supply and strategic partnerships with compounders seeking multi-jurisdictional regulatory qualification.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify divergent strategic positioning—BASF through Ludwigshafen-based value chain control, Eastman through specialized non-phthalate grade development. Sasol Limited occupies a distinctive position as the anchor Fischer-Tropsch producer, with Secunda-derived streams supplying European automotive and medical device specifications. These three entities collectively represent the competitive archetypes reshaping procurement relationships as certification requirements compress supplier qualification cycles.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Chemical Company |
| Eastman Chemical Company |
| Dow Inc. |
| Evonik Industries AG |
| Sasol Limited |
| Arkema S.A. |
| LG Chem |
| Oxea GmbH |
| Others |
Value Network & Pricing Analysis
Bio-based glycerol monostearate substitution for petrochemical 2-ethylhexanol is simultaneously redrawing supply geography toward Southeast Asian oleochemical hubs and compressing pricing premiums for legacy oxo-alcohol grades as compounders rebalance feedstock portfolios.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with FDA food-contact notification holders commanding substantial premiums over industrial-grade streams. Cost compression in standard-tier C4-C13 oxo-alcohols is intensifying because propylene-butadiene feedstock volatility erodes margin predictability. Construction compounders in China exhibit the highest price sensitivity, while automotive OEMs in Germany prioritize specification compliance over unit cost.
Supply Chain Analysis
Cape of Good Hope transit uncertainty constrains Fischer-Tropsch-derived C12-C13 alcohol delivery schedules to European buyers. Supply concentrates in China, Germany, and South Africa, with production drawing from naphtha crackers, coal-to-liquids facilities, and gas-to-liquids complexes respectively. Feedstock dependencies rest on propylene, butadiene, and natural gas feedstocks. Single-source vulnerability from Sasol's Secunda facility creates concentration risk for premium trimellitate precursors. Distribution runs through Rotterdam and Singapore storage terminals serving regional compounding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital formulation platforms are transforming this market into a data-network economy where AI-driven blend optimization and cloud-based regulatory compliance tracking create interoperability advantages that compound with scale.
For Market Incumbents: Secure backward integration into C4 olefin supply to insulate margin structures from naphtha price spread volatility. BASF's Ludwigshafen model demonstrates how feedstock quality control from butadiene extraction through finished oxo-alcohol output defends against bio-based substitution threats. Prioritize certification investment for REACH Annex XIV-compliant grades to maintain automotive and medical device qualification status. For New Entrants and Emerging Players: BIS certification fast-track for phthalate-free grades in India offers the most penetrable entry point under the Production Linked Incentive scheme. Maharashtra and Gujarat industrial corridors present white-space demand from domestic PVC compounding capacity expansion. Pursue distributor partnerships in Mumbai and Ahmedabad to bypass direct qualification barriers with established compounders. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors Fischer-Tropsch specialists with carbon chain specificity advantages. Long-term viability hinges on feedstock flexibility across petrochemical, coal, and bio-based routes. Acquisition targets should demonstrate multi-jurisdictional regulatory qualification bandwidth. Watch EPA Section 6 risk evaluation timelines as the signal for phthalate phaseout velocity and non-phthalate precursor demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Olefins | BASF's Ludwigshafen complex demonstrates how feedstock control insulates margin from naphtha volatility. |
| Multi-Jurisdictional Certification Investment | REACH, FDA, and GB standard alignment unlocks automotive OEM and medical device supply chains. |
| Bio-Based Feedstock Qualification | Glycerol monostearate certification under EU Regulation 10/2011 captures renewable content procurement mandates. |
| Digital Formulation Platform Deployment | AI-driven blend optimization compresses qualification cycles from 18 months to 6 months for new alcohol grades. |
| Regional Distribution Hub Establishment | Rotterdam and Singapore terminal positions buffer compounders against Cape of Good Hope logistics uncertainty. |
Research Methodology
A standing panel of oxo-alcohol plant managers, PVC compounder procurement leads, automotive OEM material engineers, and chemical distribution channel partners provided ongoing calibration across the study period. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical majors, and SAMR GB standard documentation. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity announcements and end-use consumption surveys.
Consistency checks validated outputs against external benchmarks including ECHA REACH registration volumes, FDA food-contact notification databases, and provincial infrastructure bond disbursement records from Sichuan and Guangdong. The analytical framework segmented across grade tier, end-use industry, formulation type, and regional production hub throughout the forecast period. CAGRs were derived from regression analysis of historical consumption patterns against projected construction spending, automotive production schedules, and regulatory phaseout timelines. Industry-specific inputs included steam cracker operating rate assumptions and bio-based feedstock cost parity trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure investment in China, gradual REACH Annex XIV enforcement escalation, and stable Fischer-Tropsch output from Secunda; material deviation in any would warrant model refresh. Practitioners should keep alternative scenarios live as EPA Section 6 rulemaking timelines and oleochemical route scale-up economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Citrate Anhydrous Market
Additives
South America Sodium Reduction Agents Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Foundry Additives Market
Additives
Pectin Market
Additives
Anti-Block Additives Market
Additives
Metal Deactivators Market
Additives
Shortstop Inhibitor Market
Additives
Alginic Acid Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Drilling Fluid Additives Market
Additives
Sorbitan Oleate Market
Additives
Propyl Gallate Market
Additives
Global Isononanoic Acid Market
Additives
Global Glass Additives Market