
 Liquid Thickeners Market | 2026-2036
Liquid Thickeners Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Thickeners Market Foresight
Pre-portioned single-serve thickener packets is broadening choice for institutional buyers managing dysphagia patients. Cargill leverages its agricultural supply chain to secure cost-advantaged raw material positions in natural thickeners. Tate & Lyle PLC sustains formulation partnerships with European beverage manufacturers seeking clean-label credentials. Ingredion Incorporated anchors its competitive stance through R&D intensity in modified starch functionality.
Liquid thickeners comprise hydrocolloid and polysaccharide additives that increase viscosity in aqueous systems, typically functioning at concentrations between 0.5% and 5% by weight to achieve target texture grades for safe swallowing. Their primary commercial purpose spans food texture modification, pharmaceutical suspension stability, and personal care rheology control. Natural thickeners occupy the largest volume share as food manufacturers reformulate away from synthetic additives under consumer pressure. Cellulose derivatives represent the fastest-expanding category, driven by pharmaceutical applications requiring precise viscosity control in oral dosage forms. Gum-based thickeners command premium positioning in nutritional applications where cold-water solubility and clarity specifications justify higher formulation costs.
FDA oversight of medical foods and the EU's Food Information to Consumers Regulation shape thickener labeling, purity standards, and health claim substantiation across both jurisdictions. The EPA and ECHA govern manufacturing discharge limits for starch and cellulose processing facilities, influencing plant location and capital intensity decisions. ISO viscosity measurement protocols provide the technical baseline for cross-border product specification and quality arbitration. Stakeholders must monitor evolving dysphagia diet frameworks from the International Dysphagia Diet Standardisation Initiative, as adoption of global texture descriptors will reshape procurement specifications and reformulation requirements across healthcare and foodservice channels.
Market Dynamics
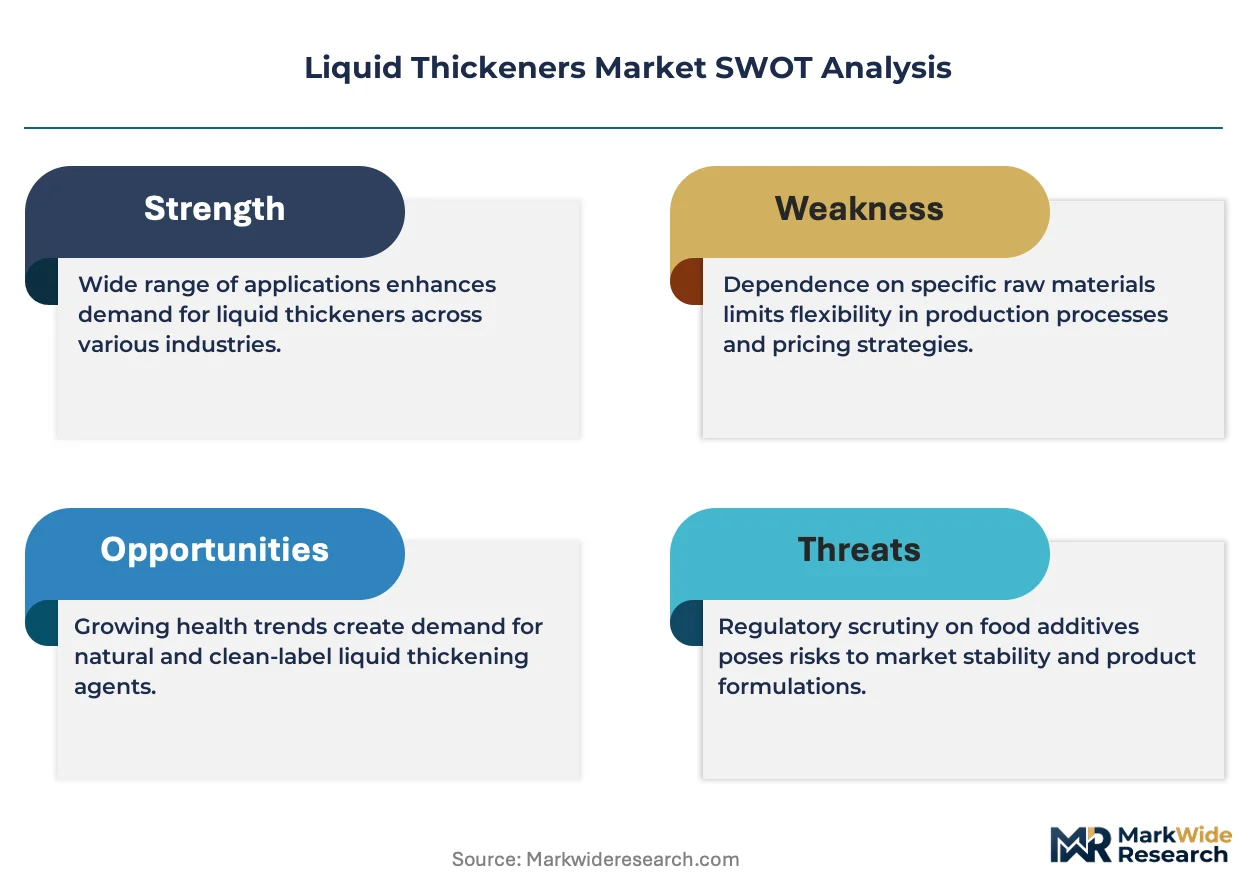
Clean-label mandates from the FDA and EFSA are systematically displacing synthetic hydrocolloids with plant-derived alternatives, forcing reformulation investments across food and pharmaceutical manufacturing networks.
Growth Catalysts
- Aging Demographics:Dysphagia prevalence in institutional care settings is accelerating standardized thickener procurement across post-acute hospital networks.
- EU Food Information to Consumers Regulation:Mandatory disclosure of additive origins is compelling manufacturers to source certified natural thickeners with full supply chain traceability.
- Cellulose Derivative Functionality:Precise viscosity control in oral pharmaceutical suspensions is expanding adoption of modified cellulose beyond traditional food applications.
Market Restraints
- Raw Material Concentration:Guar gum supply depends on monsoon-dependent harvests in Rajasthan, India, creating price volatility that destabilizes formulation budgeting.
- Clean-Label Cost Premium:Plant-derived hydrocolloids command 40-60% higher input costs versus synthetic alternatives, compressing margins for mid-tier food manufacturers.
- REACH Compliance Burden:ECHA registration requirements for novel biopolymer thickeners extend commercialization timelines by 18-24 months versus conventional additives.
Strategic Opportunities
- Pediatric Dysphagia Protocols:Underpenetrated neonatal and pediatric nutrition segments in Germany and France present white-space expansion for texture-modified beverage systems.
- ISO Texture Standardization:Adoption of International Dysphagia Diet Standardisation Initiative frameworks is creating first-mover advantage for suppliers with pre-validated product portfolios.
- Direct-to-Institution Platforms:E-procurement portals bypassing traditional distributor markups are capturing share in US nursing home and assisted-living purchasing.
Industry Challenges
- Formulation Scientist Scarcity:Specialized expertise in hydrocolloid hydration kinetics and shear-thinning behavior remains concentrated among senior chemists approaching retirement.
- Cross-Border Certification Complexity:Divergent FDA medical food designations versus EFSA food additive classifications force dual-track regulatory submissions for identical products.
- Cold-Chain Integration:Pre-hydrated liquid thickeners require refrigerated distribution infrastructure that conflicts with existing ambient-temperature foodservice supply networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Thickeners Market |
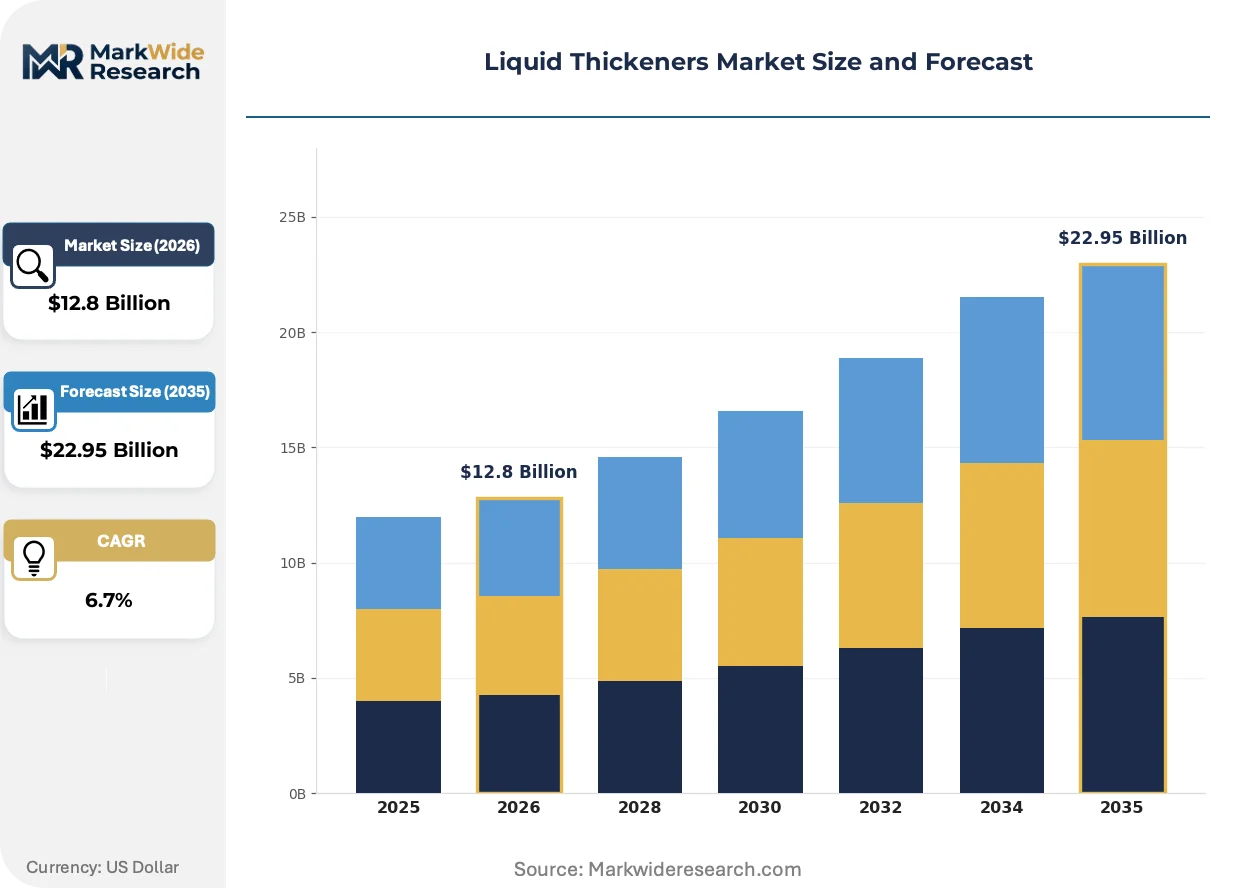
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Modified Starch, Cellulose Derivatives, Gum Application: Food & Beverage, Pharmaceuticals, Personal Care, Nutritional Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Healthcare Providers, Consumers, Restaurants |
| Companies Covered | Cargill, Inc., DuPont de Nemours, Inc., Tate & Lyle PLC, Ingredion Incorporated, CP Kelco, Kerry Group, Ashland Global Holdings Inc., BASF SE, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Thickeners Market Shifts & Advancements
Functional ingredient platforms are converging with digital specification tools to compress product development cycles and enable mass customization of viscosity profiles.
Cold-water soluble gum systems are modularizing formulation workflows for ready-to-drink manufacturers. Beverage processors in the United States are adopting these pre-hydrated concentrates to eliminate heating steps and reduce energy inputs. This technology is modularizing production line configurations, allowing single facilities to switch between texture grades without equipment changeovers.
REACH authorization requirements for synthetic polymer thickeners are tightening purity thresholds and traceability documentation. European compounders must now submit full toxicological dossiers for hydrocolloid derivatives previously grandfathered under earlier substance listings. Pharmaceutical excipient suppliers serving EMA-regulated markets are accelerating migration to bio-based alternatives to preempt authorization denial risks.
Consolidated purchasing by US hospital networks is compressing supplier margins while demanding just-in-time inventory guarantees. Group purchasing organizations now specify ISO-compliant viscosity certification as a mandatory bid qualification, displacing legacy brand-loyalty procurement patterns. This concentration is most visible in the southeastern United States, where regional health systems have centralized thickener procurement across 200+ affiliated facilities.
Liquid Thickeners Market Segmentation
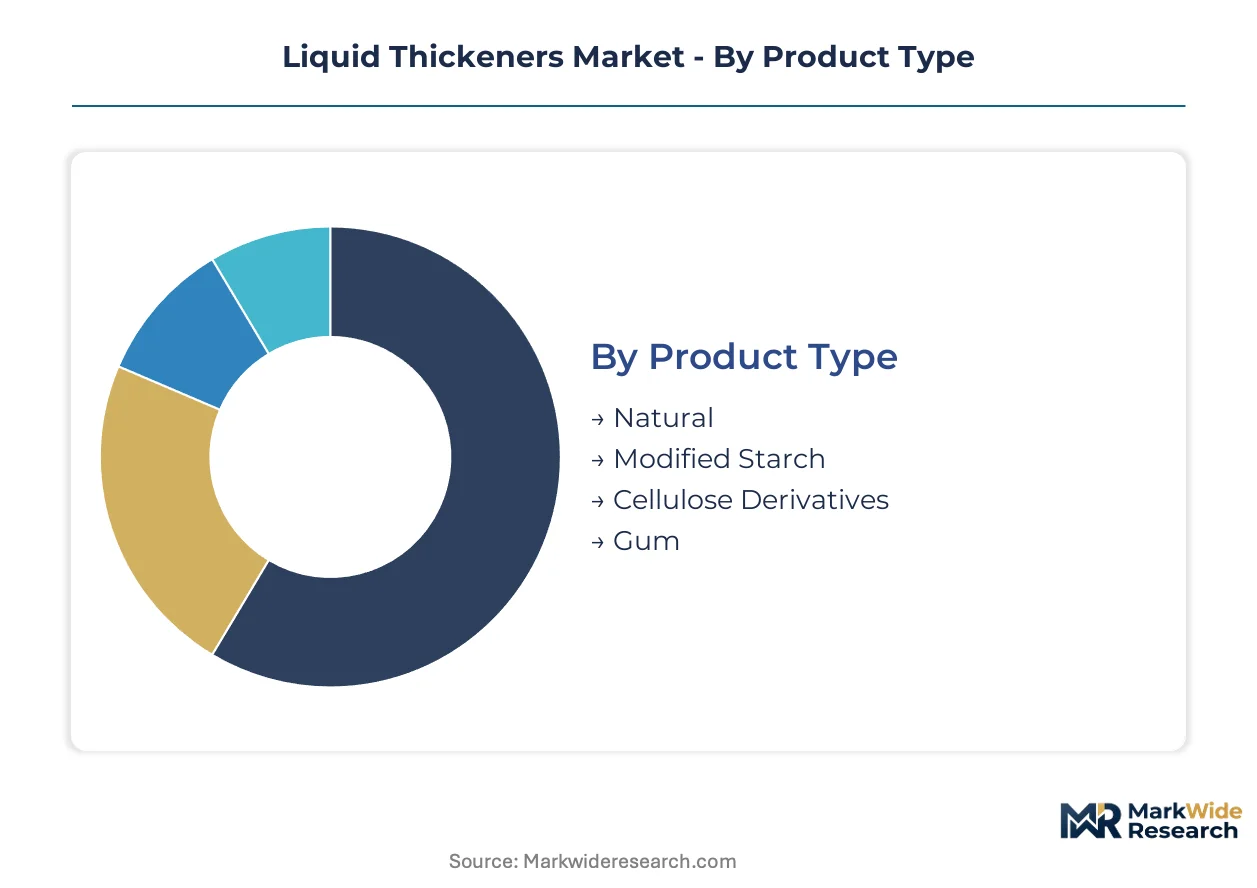
Liquid thickener procurement patterns diverge sharply across product chemistry and end-use specifications. Healthcare reimbursement protocols favor standardized viscosity grades, while food manufacturers prioritize cold-solubility and clean-label positioning.
Product Type:
Capital intensity peaks in cellulose derivative production, where etherification reactors and solvent recovery systems demand eight-figure facility investments.
- Natural:Plant-derived hydrocolloids extracted from guar, locust bean, and tara gum dominate volume consumption. Food manufacturers in Germany and France are reformulating under EFSA clean-label mandates, rejecting synthetic alternatives despite 40-60% cost premiums.
- Modified Starch:Cross-linked and pre-gelatinized starches offer cost-efficient viscosity building for institutional foodservice. US hospital networks specify these thickeners for dysphagia management protocols, with group purchasing organizations mandating ISO-compliant viscosity certification as bid qualification.
- Cellulose Derivatives:Methylcellulose and hydroxypropyl methylcellulose require specialized chemical processing infrastructure.
- Gum:Xanthan and gellan gum systems command premium positioning in beverage clarity applications.
Most installed capacity flows through Natural thickeners. Expansion is steepest in Cellulose Derivatives.
Application:
Margin structures vary threefold across applications, with pharmaceutical excipients capturing value premiums over commodity food additives.
- Food & Beverage:Texture-modified products for dysphagia patients represent the largest addressable volume. Post-acute care facilities in the United States drive standardized procurement, with texture grades aligned to International Dysphagia Diet Standardisation Initiative frameworks.
- Pharmaceuticals:Oral suspension stability and controlled-release tablet matrices demand precise viscosity control. EMA-regulated markets require full toxicological dossiers for hydrocolloid excipients, accelerating migration to bio-based alternatives.
- Personal Care:Rheology modifiers for lotions and creams favor cold-process compatible grades.
- Nutritional:Pediatric and geriatric nutrition formats require hypoallergenic, transparent solutions.
Food & Beverage absorbs the majority of production volume. Pharmaceuticals is climbing the fastest as regulatory barriers steepen.
Form:
Distribution economics favor dry formats, though pre-hydrated systems are capturing share in ready-to-drink manufacturing.
- Powder:Dominant format for institutional procurement, offering extended shelf stability and freight efficiency. US nursing homes and assisted-living facilities specify powder thickeners for inventory simplicity and dosing flexibility.
- Liquid:Pre-hydrated concentrates eliminate hydration time for beverage processors. Cold-water soluble gum systems allow single facilities to switch between texture grades without equipment changeovers, though refrigerated distribution conflicts with ambient-temperature foodservice networks.
- Granular:Intermediate flow properties for automated dispensing systems.
- Paste:Concentrated formats for industrial-scale batching operations.
Powder formats command the bulk of installed capacity. Liquid formats are gaining share fastest in ready-to-drink manufacturing.
End User:
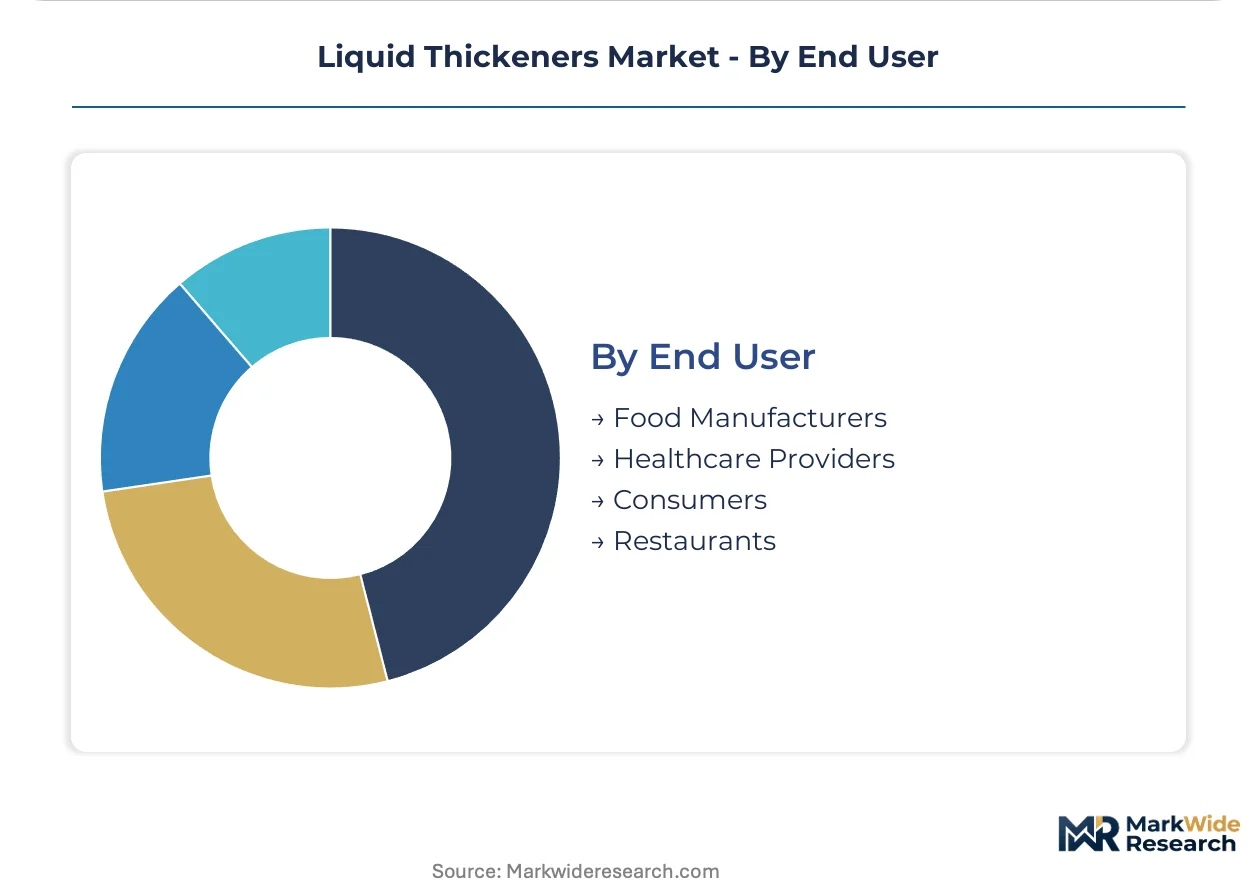
Procurement sophistication separates institutional buyers from consumer-direct channels, with healthcare providers demanding batch-level traceability.
- Food Manufacturers:Clean-label reformulation pressures under FDA and EU frameworks drive substitution of synthetic hydrocolloids. Beverage processors seek modular viscosity platforms enabling rapid texture grade switches.
- Healthcare Providers:Hospital networks and long-term care facilities specify standardized thickeners for dysphagia protocols. Southeastern US health systems have centralized procurement across 200+ affiliated facilities, compressing supplier margins while demanding just-in-time inventory guarantees.
- Consumers:Direct-purchase retail formats for home dysphagia management.
- Restaurants:Limited adoption due to per-portion cost constraints and staff training requirements.
Healthcare Providers channel the most installed capacity. Food Manufacturers are expanding fastest as clean-label mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hydrocolloid processing originated in European textile and paper chemistry laboratories during the early twentieth century, with commercial-scale starch modification later scaling across the American Midwest. These historical footprints continue to shape regional specialization in thickener manufacturing and end-use application development.
United States
Post-acute care reimbursement policies drive standardized thickener procurement across hospital networks, with group purchasing organizations mandating ISO-compliant viscosity certification. FDA oversight of medical foods shapes labeling requirements and purity standards for dysphagia management products. Southeastern health systems have centralized procurement across two hundred-plus affiliated facilities, compressing supplier margins while demanding just-in-time inventory guarantees.
Germany
Food manufacturers reformulate under EFSA clean-label mandates, rejecting synthetic hydrocolloids despite substantial cost premiums. REACH authorization requirements for synthetic polymer thickeners tighten purity thresholds and traceability documentation. The Rhine-Ruhr industrial corridor hosts specialized chemical processing infrastructure for cellulose derivative production, with etherification reactors demanding eight-figure facility investments.
France
Pediatric and neonatal nutrition segments present underpenetrated white-space expansion for texture-modified beverage systems. ANSM pharmaceutical regulations govern excipient standards for oral suspension stability applications. The Lyon-Grenoble chemical cluster anchors European pharmaceutical excipient manufacturing, with EMA-regulated markets requiring full toxicological dossiers for hydrocolloid derivatives.
India
Monsoon-dependent guar gum harvests in Rajasthan create price volatility that destabilizes formulation budgeting for global manufacturers. FSSAI food safety standards and BIS certification requirements shape import and domestic manufacturing protocols. The Gujarat chemical belt concentrates starch and gum processing capacity, serving both domestic food manufacturers and export markets.
China
Modified starch production scales to serve cost-efficient viscosity building for institutional foodservice across Asia-Pacific markets. SAMR food additive regulations and GB standards govern purity specifications and labeling requirements. The Yangtze River Delta hosts integrated hydrocolloid manufacturing complexes, with dual carbon goals driving energy efficiency investments in processing facilities.
Liquid Thickeners Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clean-label certification and pharmaceutical-grade purity tiers. The vendor base stratifies into three concentration levels: agricultural conglomerates with captive raw material supply, specialized chemical processors with etherification expertise, and regional compounders serving institutional foodservice. Three strategic archetypes dominate: supply-chain-integrated agricultural processors, R&D-intensive functional ingredient specialists, and regulatory-compliance-focused pharmaceutical excipient suppliers. M&A activity concentrates on securing guar gum and locust bean supply origins, while capacity expansion targets cold-water soluble gum systems for ready-to-drink manufacturing.
Within the agricultural-integrated tier, Cargill leverages its supply chain position while Tate & Lyle PLC and Ingredion Incorporated exemplify formulation partnership approaches with beverage manufacturers. These three entities represent distinct competitive positioning vectors: Cargill anchors cost-advantaged natural thickener sourcing, Tate & Lyle occupies European clean-label credential partnerships, and Ingredion concentrates modified starch functionality development. Each sits within a different margin tier and geographic emphasis, collectively spanning the pricing spectrum from commodity foodservice grades to premium pharmaceutical excipients.
| Leading Market Players |
|---|
| Cargill, Inc. |
| DuPont de Nemours, Inc. |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| CP Kelco |
| Kerry Group |
| Ashland Global Holdings Inc. |
| BASF SE |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Guar gum harvest volatility in Rajasthan feeds directly into formulation budgeting instability for mid-tier food manufacturers, compressing margins as plant-derived hydrocolloids command substantial premiums over synthetic alternatives across institutional procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade cellulose derivatives from foodservice modified starches and commodity natural gums. Certification under ISO viscosity protocols and FDA medical food designations drives substantial price differentiation, with clean-label credentials capturing further premiums. Pricing pressure stems from consolidated purchasing by US hospital networks demanding just-in-time guarantees. Mid-tier food manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize purity over cost.
Supply Chain Analysis
Direct-to-institution platforms bypassing traditional distributor markups are capturing share in US nursing home and assisted-living purchasing. Raw material supply draws from guar gum cultivation in India, locust bean processing in the Mediterranean, and cellulose etherification in Germany and the United States. Supply chain risk centers on monsoon-dependent agricultural yields creating input price volatility. Distribution runs through agricultural conglomerates with captive sourcing, specialized chemical processors, and regional compounders serving institutional foodservice.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cold-water soluble gum systems and pharmaceutical-grade cellulose derivatives, where clean-label premiums and regulatory compliance requirements sustain pricing power above commodity tiers.
For Market Incumbents: Anticipate REACH authorization tightening for synthetic hydrocolloids by accelerating bio-based alternative portfolios. Deepen backward integration into guar gum and locust bean supply origins to preempt raw material volatility. Secure ISO-compliant viscosity certification as mandatory bid qualification for US group purchasing organizations.
For New Entrants and Emerging Players: Enter via underpenetrated pediatric and neonatal nutrition segments in Germany and France, where texture-modified beverage protocols remain nascent. Target direct-to-institution e-procurement channels in southeastern US health systems. Position around cold-water soluble pre-hydrated concentrates for ready-to-drink manufacturers seeking equipment flexibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation scientist scarcity intersects with retiring senior chemist expertise in hydrocolloid hydration kinetics. Long-term viability favors R&D-intensive functional ingredient specialists with validated pharmaceutical excipient dossiers. Watch adoption velocity of International Dysphagia Diet Standardisation Initiative frameworks as inflection signal for procurement specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Supply | Captive sourcing from Rajasthan agricultural networks reduces monsoon-driven price volatility exposure. |
| Pharmaceutical Excipient Certification | EMA toxicological dossiers unlock premium positioning in oral suspension stability applications. |
| Cold-Water Soluble Gum Development | Pre-hydrated concentrates eliminate heating steps for US beverage processors seeking line flexibility. |
| Direct-to-Institution Platform Launch | E-procurement portals bypass distributor markups in nursing home and assisted-living channels. |
| ISO Viscosity Pre-Validation | Pre-certified portfolios capture first-mover advantage as IDDSI frameworks standardize procurement. |
Research Methodology
Coverage spans the United States, Germany, France, India, and China, with primary inputs from each market combining interviews with formulation scientists at hydrocolloid processors, procurement managers at hospital group purchasing organizations, regulatory affairs leads at pharmaceutical excipient suppliers, and technical directors at beverage manufacturers. Secondary validation drew from FDA medical food filings, EMA excipient submissions, FSSAI food safety standards, customs trade data on guar gum imports, and SEC disclosures from agricultural conglomerates. Bottom-up volume modeling and top-down value triangulation anchored projections.
Granularity-level modeling dissected the analysis window by product chemistry tier, application end-use, physical form factor, and buyer channel sophistication. CAGRs were derived from segment-level growth trajectories weighted by installed capacity shares. Forecast inputs incorporated dysphagia prevalence demographics, clean-label mandate enforcement timelines, and REACH authorization progression for synthetic hydrocolloids.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time guar gum harvest yield data introduce uncertainty bands around natural thickener pricing assumptions. Forecasts reflect documented base-case assumptions regarding IDDSI framework adoption rates and pharmaceutical excipient migration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Plastic Antioxidants Market
Additives
Adjustive Agents Market
Additives
Crosslinking Agents Market
Additives
Global Rheology Modifiers Market
Additives
Global Propyl Acetate Market
Additives
China Sodium Reduction Ingredient Market
Additives
Anti-Creasing Agent Market
Additives
Additives for Metalworking Fluids Market
Additives
South America Sodium Reduction Agents Market
Additives
Ascorbyl Stearate Market
Additives
Water-Borne Coating Additives Market
Additives
Ruminant Feed Additive Market
Additives
Global UV Absorbers Market
Additives
United States Citric Acid Market
Additives
Dispersing Agents Market
Additives
Rosin Ester Market