
 Combustion Clean-Up Additives for High-Mileage Fleets Market | 2026-2036
Combustion Clean-Up Additives for High-Mileage Fleets Market Size, Share, and Industry Trends Forecast 2026-2036
Combustion Clean-Up Additives for High-Mileage Fleets Market Insights
Logistics providers operating long-haul heavy-duty truck fleets is hardening as the dominant demand source for combustion clean-up additives. BASF leverages its global manufacturing scale to supply fuel additives and engine oil additives across European and North American freight corridors. The Lubrizol Corporation sustains technology leadership in ashless dispersant chemistry for high-mileage diesel engines. Afton Chemical competes through specialized distribution partnerships with fleet maintenance networks in North America.
Combustion clean-up additives for high-mileage fleets comprise chemical formulations including detergents, dispersants, friction modifiers, and combustion catalysts blended at treat rates between 50 and 5,000 parts per million to restore engine efficiency, reduce deposit formation, and lower particulate emissions in vehicles exceeding 150,000 operational miles. Fuel additives dominate current volume consumption among product types due to frequent dosing cycles and immediate drivability benefits, while emission reducers represent the fastest-expanding category as regulatory enforcement tightens. Heavy-duty trucks anchor application-level demand through intensive utilization patterns, though public transport vehicles generate premium margin pools due to municipal procurement standards requiring certified additive performance.
The EPA enforces Tier 3 emission standards and renewable fuel mandates that shape additive formulation requirements for US fleet operators, while the EU Green Deal and F-Gas Regulation in Europe drive parallel demand for low-carbon combustion improvement technologies. Fleet operators must monitor evolving regulatory thresholds in both jurisdictions to align additive procurement with compliance timelines and avoid operational restrictions in designated low-emission zones.
Market Dynamics
EPA Tier 3 emission standards and Euro VI mandates are compressing formulation development cycles while logistics operators demand additive packages that extend engine rebuild intervals beyond 500,000 miles. This regulatory-technical tension is restructuring procurement relationships between fleet maintenance networks and specialty chemical suppliers.
Growth Catalysts
- EPA Tier 3 Standards:Fleet operators in California, Texas, and Illinois are retrofitting existing heavy-duty trucks with emission-reducing additive protocols to avoid operational restrictions in designated low-emission zones.
- Long-haul freight intensity:Interstate corridors connecting Chicago, Dallas, and Los Angeles generate concentrated demand for deposit-control additives that restore fuel economy in vehicles exceeding 300,000 annual miles.
- Ashless dispersant chemistry:Advanced detergent formulations prevent soot-induced viscosity thickening in high-mileage diesel engines, extending oil drain intervals and reducing downtime costs for owner-operators.
Market Restraints
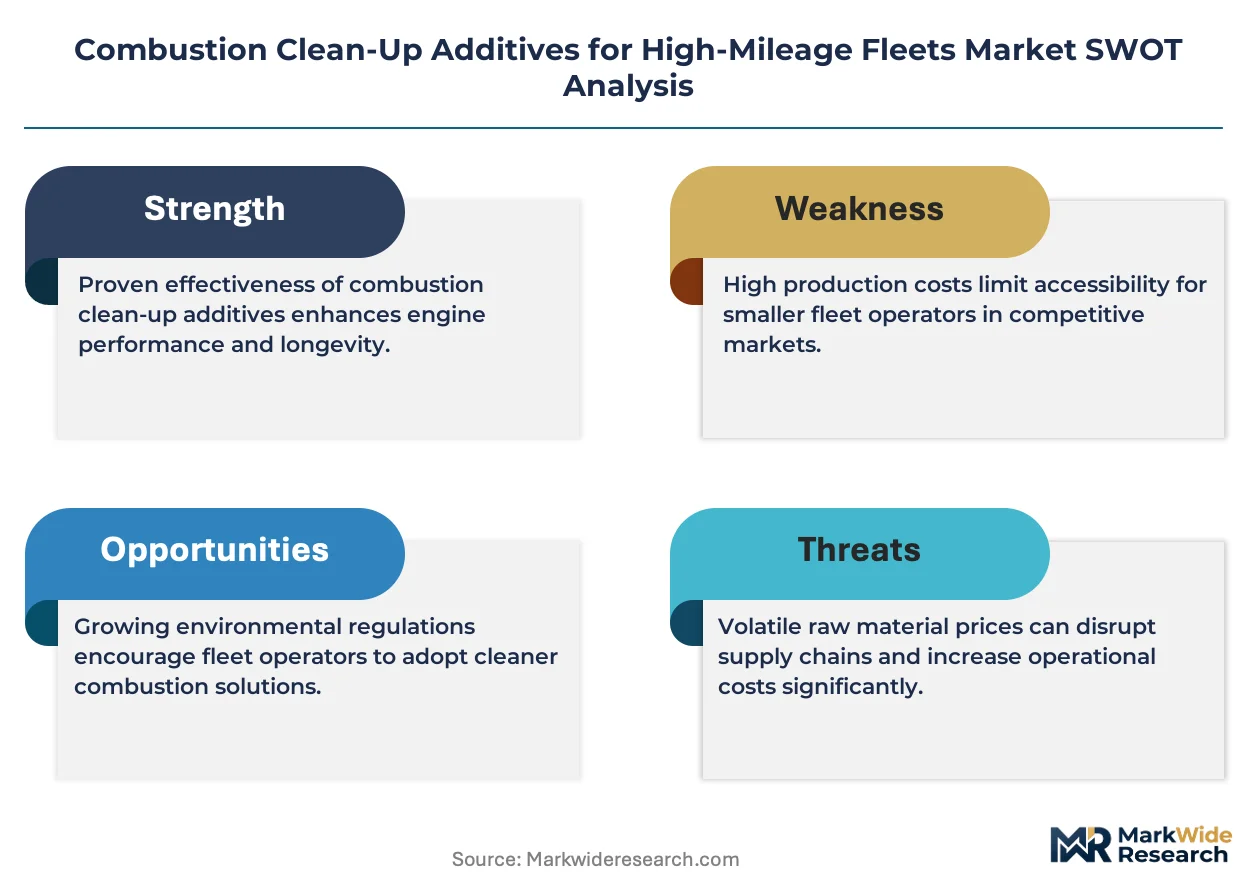
- Base oil price volatility:Group II and Group III base stock fluctuations compress additive blender margins, particularly for small-batch treat rate formulations serving regional fleet operators.
- Supply concentration in Texas-Louisiana corridor:Specialty chemical manufacturing clusters along the Gulf Coast create hurricane-related production disruption exposure for nationwide additive distribution networks.
- Technical limitation in gasoline direct injection compatibility:Existing combustion catalysts demonstrate reduced efficacy in GDI engines with cooled exhaust gas recirculation, constraining addressable fleet segments.
Strategic Opportunities
- Underpenetrated municipal transit authorities:City bus fleets in Ohio, Pennsylvania, and Michigan lag private logistics operators in additive adoption, presenting certified-supplier conversion potential.
- Technology convergence of telematics and predictive dosing:Integration of engine sensor data with automated additive injection systems enables condition-based treat rate optimization for variable-duty cycles.
- Inflation Reduction Act clean fuel incentives:Tax credits for low-carbon transportation fuels create procurement budget headroom for fleet operators to upgrade from basic detergents to multi-functional additive packages.
Industry Challenges
- Specialized tribochemistry expertise scarcity:Formulation chemists with diesel deposit control and wear protection dual competency command premium compensation, constraining R&D team scaling for mid-tier additive suppliers.
- API CK-4/FA-4 certification timeline compression:Accelerated oil category development cycles force simultaneous reformulation of additive packages to maintain OEM approval status across multiple engine platforms.
- Legacy fleet management software integration:Additive inventory tracking systems must interface with established maintenance platforms used by large multi-site operators, creating implementation friction for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combustion Clean-Up Additives for High-Mileage Fleets Market |
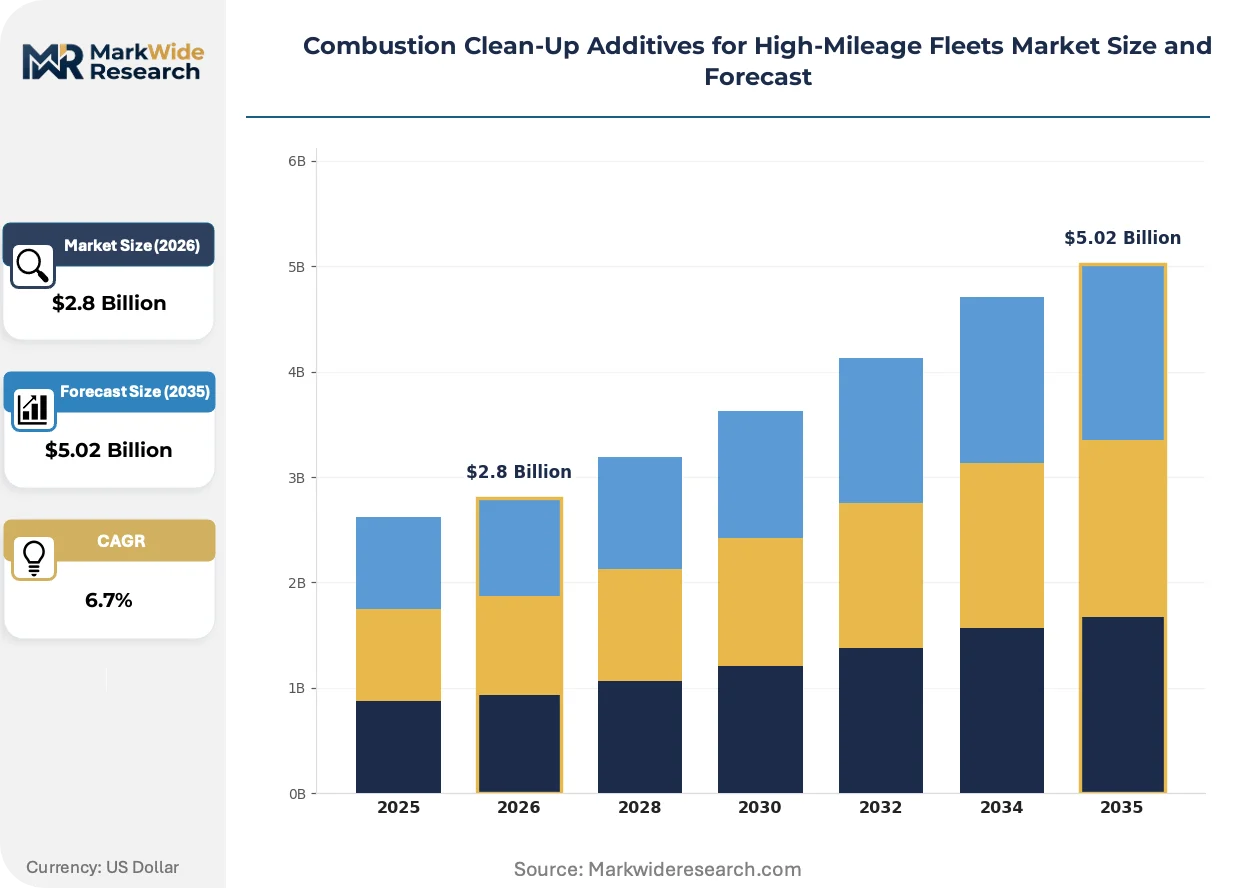
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Additives, Engine Oil Additives, Intake System Cleaners, Injector Cleaners, Emission Reducers Application: Heavy-Duty Trucks, Delivery Vans, Public Transport Vehicles, Construction Machinery, Agricultural Equipment End User: Fleet Operators, Commercial Transport Companies, Logistics Providers, Rental Agencies, Vehicle Maintenance Services Distribution Channel: Direct Sales, Automotive Aftermarket, E-Commerce Platforms, Specialized Distributors, Service Workshops |
| Companies Covered | BASF, Evonik Industries, The Lubrizol Corporation, Afton Chemical, Infineum, Innospec, Chevron, TotalEnergies, Lucas Oil Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combustion Clean-Up Additives for High-Mileage Fleets Market Trends and Innovations
Combustion clean-up additive development is pivoting from universal formulations toward segment-specific chemical architectures that address distinct deposit morphologies across engine technologies and duty cycles.
Nanoparticle-based friction modifiers incorporating boron and molybdenum compounds are rewriting wear protection economics for high-mileage fleets. Owner-operators managing 15-plus year-old equipment are adopting these advanced packages at treat rates below 1,000 ppm. The technology is compressing traditional split between premium synthetic and conventional mineral oil additive tiers.
The EPA's updated heavy-duty greenhouse gas standards for model year 2027 vehicles are forcing additive suppliers to validate deposit control performance under low-load, low-temperature operating conditions. Blenders must reformulate detergent systems to prevent injector coking in engines optimized for emissions rather than thermal efficiency. California Air Resources Board enforcement patterns are driving early adoption among fleets with significant intra-state exposure.
Fleet procurement departments are consolidating additive purchasing through integrated maintenance contracts rather than spot-market transactions. Third-party logistics providers with captive maintenance facilities are displacing independent jobbers as the primary distribution channel. This concentration is most visible across the I-80 corridor serving distribution hubs in Pennsylvania, Ohio, and Indiana.
Combustion Clean-Up Additives for High-Mileage Fleets Market Segmentation
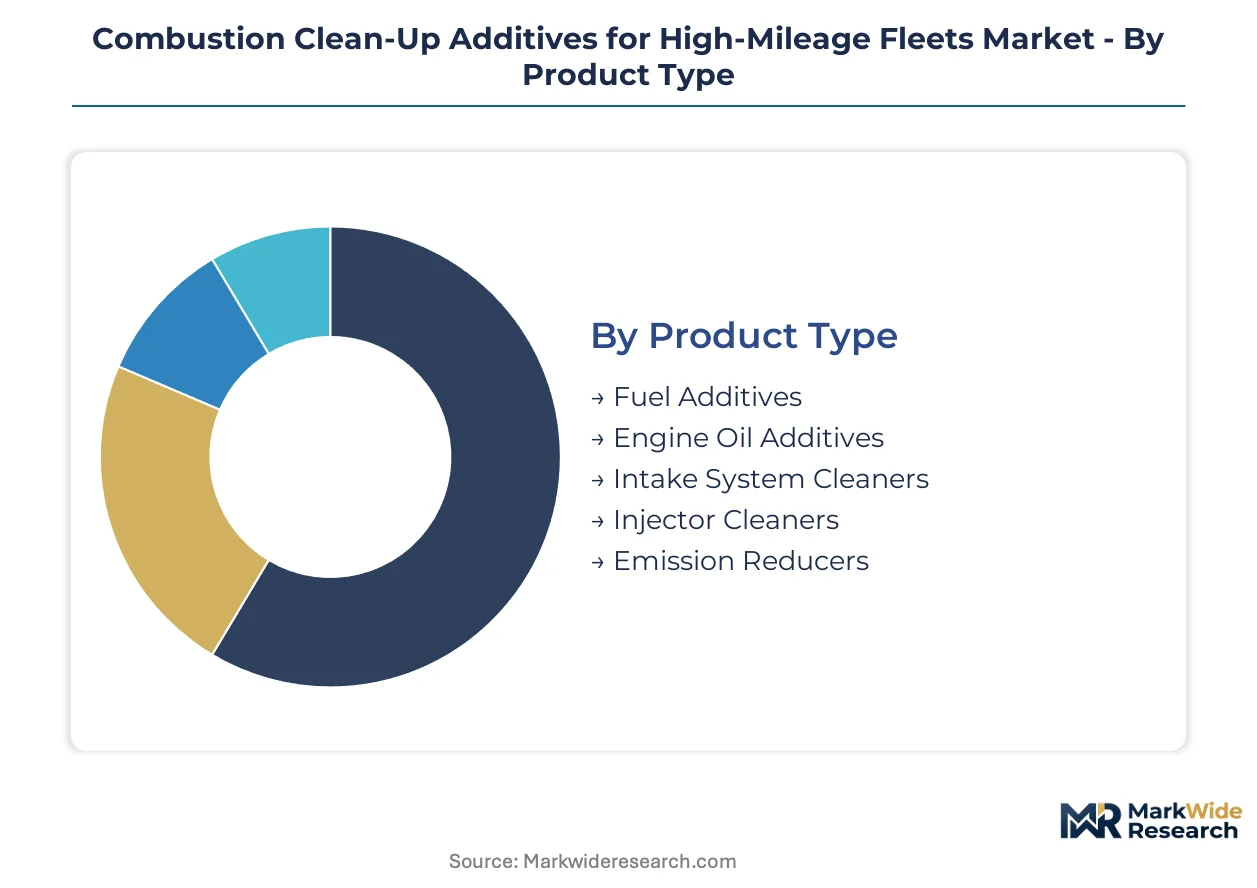
Segmentation in this market reflects divergent certification burdens and procurement patterns across chemical formulations and fleet types. Understanding which segments require EPA, API, or OEM validation determines supplier qualification timelines and pricing architecture for additive manufacturers.
Product Type:
API CK-4/FA-4 certification applies to engine oil additives, while EPA fuel registration governs fuel-borne chemistry; intake system and emission-reducing formulations face fragmented state-level approvals.
- Fuel Additives:Detergent and cetane improver formulations dosed at 50-5,000 ppm restore injector spray patterns and combustion efficiency in high-mileage diesel engines. Logistics providers operating interstate corridors in Texas, California, and Illinois specify these for vehicles exceeding 300,000 annual miles to maintain fuel economy warranties.
- Emission Reducers:Combustion catalysts and particulate matter suppressants target NOx and soot reduction for EPA Tier 3 and CARB compliance. Fleet operators in designated low-emission zones across Los Angeles, Houston, and Chicago retrofit legacy equipment with these formulations to avoid operational restrictions.
- Engine Oil Additives:Ashless dispersant packages prevent soot-induced viscosity thickening in extended drain intervals.
- Intake System Cleaners:Solvent-based deposits removal for throttle bodies and EGR valves.
- Injector Cleaners:Concentrated detergent shots for direct-injection carbon remediation.
Leading the category by volume: Fuel Additives. Growing fastest: Emission Reducers.
Application:
Utilization intensity and duty cycle severity determine treat rate economics and formulation durability requirements across vehicle classes.
- Heavy-Duty Trucks:Class 8 tractors operating 100,000-plus annual miles generate baseline demand for deposit-control and wear-protection packages. Interstate freight corridors connecting Dallas, Chicago, and Los Angeles concentrate procurement through integrated maintenance contracts with third-party logistics providers.
- Public Transport Vehicles:Municipal bus fleets in Ohio, Pennsylvania, and Michigan operate under certified-supplier procurement standards that mandate documented additive performance. Transit authorities lag private logistics operators in adoption, creating conversion potential for approved vendors.
- Delivery Vans:Last-mile urban circuits with stop-start duty cycles.
- Construction Machinery:Intermittent high-load operation in off-highway conditions.
- Agricultural Equipment:Seasonal use patterns with extended storage intervals.
Heavy-Duty Trucks anchor absolute volume. Public Transport Vehicles command the steepest expansion trajectory as municipal procurement standards tighten.
End User:
Procurement sophistication varies from centralized fleet management systems to decentralized owner-operator purchasing behavior.
- Logistics Providers:Third-party operators with captive maintenance facilities consolidate additive purchasing through multi-year integrated contracts. These buyers displace independent jobbers across the I-80 corridor serving distribution hubs in Pennsylvania, Ohio, and Indiana.
- Fleet Operators:Large multi-site operators require additive inventory tracking systems that interface with legacy fleet management software platforms.
- Commercial Transport Companies:Regional carriers with mixed equipment ages.
- Vehicle Maintenance Services:Independent service workshops with spot-market purchasing patterns.
- Rental Agencies:Turnover-focused operators prioritizing minimal maintenance expenditure.
Logistics Providers dominate contract value. Fleet Operators are gaining share fastest through telematics-integrated predictive dosing adoption.
Distribution Channel:
Channel selection determines working capital requirements and technical support obligations for additive suppliers.
- Specialized Distributors:Regional chemical distributors with tribochemistry expertise serve mid-sized fleet operators requiring formulation guidance. Gulf Coast supply concentration exposes these intermediaries to hurricane-related production disruption.
- Direct Sales:Large national accounts bypass intermediaries for volume pricing and custom treat rate engineering.
- Automotive Aftermarket:Retail and jobber networks serving owner-operators.
- Service Workshops:Maintenance facilities bundling additives with repair services.
- E-Commerce Platforms:Emerging channel for standardized formulations with documented specifications.
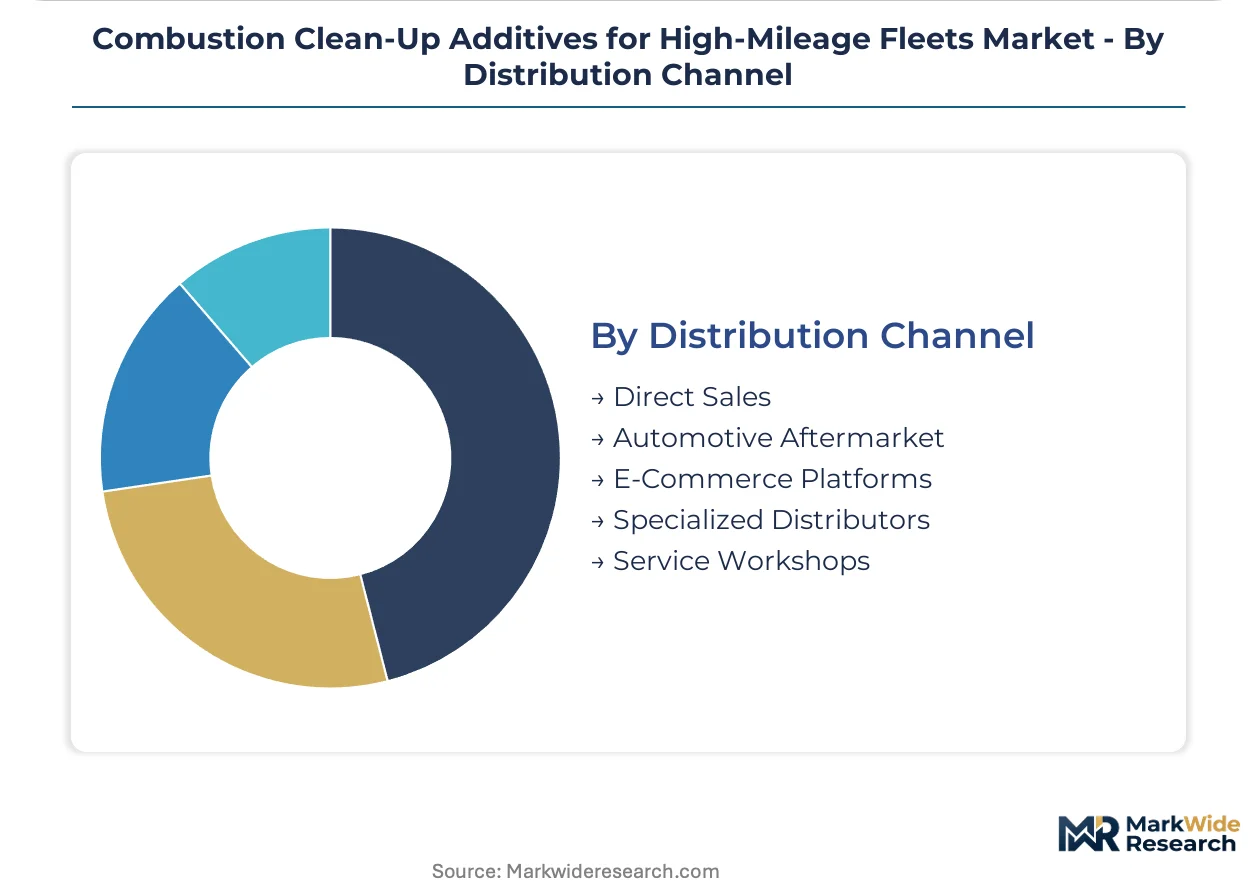
Specialized Distributors maintain the broadest reach. Direct Sales channels are climbing the fastest as procurement consolidates among large logistics providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-80 freight corridor spanning Pennsylvania, Ohio, and Indiana operates as a concentrated demand zone where logistics providers consolidate additive procurement through integrated maintenance contracts tied to federal clean fuel incentives.
United States
Interstate freight corridors connecting Dallas, Chicago, and Los Angeles generate concentrated demand for deposit-control additives in vehicles exceeding 300,000 annual miles. EPA Tier 3 emission standards compel fleet operators in California, Texas, and Illinois to retrofit legacy heavy-duty trucks with emission-reducing additive protocols. The Gulf Coast chemical manufacturing cluster in Texas and Louisiana supplies base stocks and specialty formulations, though hurricane exposure creates periodic distribution disruption.
Germany
Long-haul logistics operators serving the Rhine-Ruhr industrial corridor and Bavarian distribution hubs anchor European demand for high-performance engine oil additives. Euro VI standards and the EU Green Deal drive procurement of low-carbon combustion improvement technologies for commercial vehicle fleets. The BASF manufacturing complex in Ludwigshafen supplies fuel additives and engine oil formulations across European freight corridors.
China
Domestic logistics providers operating along the Beijing-Shanghai and Yangtze River Delta freight corridors are expanding additive adoption to extend vehicle lifecycles in aging heavy-duty truck populations. The Ministry of Ecology and Environment enforces China VI emission standards that parallel Euro VI stringency for commercial vehicles. Shandong Province hosts concentrated specialty chemical manufacturing serving domestic additive blenders and regional fleet operators.
Japan
Metropolitan bus fleets in Tokyo and Osaka generate premium demand for certified additive performance under municipal procurement standards. METI promotes low-carbon transportation technologies through fuel efficiency regulations affecting commercial vehicle operators. The Chubu region around Nagoya maintains specialty chemical production capacity serving domestic formulation requirements.
India
Long-distance freight operators on the Delhi-Mumbai Industrial Corridor are adopting deposit-control additives to manage high-sulfur fuel combustion in aging commercial vehicle fleets. The Central Pollution Control Board implements Bharat Stage VI standards that mandate emission control technology adoption. Gujarat's chemical manufacturing belt supplies base detergent formulations to domestic additive blenders serving regional logistics providers.
Combustion Clean-Up Additives for High-Mileage Fleets Market Competitive Landscape
Top-tier vendors anchor integrated supply relationships with multinational logistics providers, while mid-tier regional blenders compete on formulation customization and technical service proximity. The market structure reflects moderate consolidation around petrochemical majors with backward integration into base stock production, complemented by specialized additive houses focused on tribochemistry intellectual property. Three archetypes dominate: global diversified chemical conglomerates with captive additive divisions, independent lubricant additive specialists, and regional fuel treatment compounders serving owner-operator segments. Competitive dynamics center on API certification maintenance and strategic partnerships with third-party logistics maintenance networks.
Among the global diversified chemical conglomerates, BASF anchors the tier through its Ludwigshafen manufacturing complex and integrated supply position across European and North American freight corridors. The Lubrizol Corporation exemplifies the independent lubricant additive specialist archetype, occupying a position defined by ashless dispersant chemistry expertise for high-mileage diesel applications. Afton Chemical represents the formulation-focused competitor segment, sitting within the competitive landscape through specialized distribution relationships with fleet maintenance networks concentrated in North America.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| The Lubrizol Corporation |
| Afton Chemical |
| Infineum |
| Innospec |
| Chevron |
| TotalEnergies |
| Lucas Oil Products |
| Others |
Pricing and Supply Chain Analysis
API certification ladder bifurcation between CK-4/FA-4 validated packages and unregistered commodity blends manifests in both pricing power concentration among approved suppliers and supply chain configuration favoring backward-integrated petrochemical majors with captive base stock production.
Pricing Analysis
Short lead-time premiums attach to EPA-registered fuel additives delivered under 72-hour windows to California and Texas fleet operators facing CARB enforcement deadlines. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated CK-4 packages from API-licensed mid-tier formulations and unregistered commodity detergents. Cost compression in economy-tier spot formulations intensifies because Group II base oil volatility erodes blender margins. Owner-operators with 15-plus-year-old equipment demonstrate highest price sensitivity, while third-party logistics providers with captive maintenance facilities accept premium pricing for integrated contract certainty.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast specialty chemical clusters in Texas and Louisiana, where hurricane exposure threatens nationwide additive distribution networks. Manufacturing gravity centers on the Texas-Louisiana corridor for Group II/III base stocks, Ludwigshafen in Germany for ashless dispersant intermediates, and Shandong Province in China for domestic detergent feedstocks. Raw material dependencies include polyisobutylene for dispersant backbones, molybdenum compounds for friction modifiers, and boron esters for anti-wear chemistry. Tariff exposure on Chinese-sourced detergent intermediates constrains cost flexibility for regional blenders. Distribution runs through third-party logistics maintenance networks displacing independent jobbers across the I-80 corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanoparticle-based friction modifier chemistry is displacing legacy organometallic packages in high-mileage diesel applications, compressing the traditional synthetic-conventional additive tier split and forcing reformulation investment across supplier bases.
For Market Incumbents: Anchor integrated supply relationships with multinational logistics providers through multi-year maintenance contracts spanning the I-80 corridor. Deepen backward integration into Group III base stock production to defend margin position against Gulf Coast supply disruption. Prioritize API CK-4/FA-4 certification maintenance as accelerated oil category development cycles threaten OEM approval status across multiple engine platforms. For New Entrants and Emerging Players: The premium-economy price-point gap in municipal transit authorities across Ohio, Pennsylvania, and Michigan creates conversion potential for certified-supplier qualification. Target city bus fleets operating under documented performance procurement standards that lag private logistics adoption. Pursue telematics-integrated predictive dosing partnerships with mid-sized fleet operators seeking condition-based treat rate optimization. For Investors and Strategic Acquirers: Re-rating potential sits with independent lubricant additive specialists given ashless dispersant chemistry scarcity and premium compensation commanded by formulation chemists with dual diesel deposit control and wear protection competency. Long-term viability favors acquisition targets with established API certification pipelines and stranded relationships with fleet maintenance networks. Watch EPA heavy-duty greenhouse gas standards enforcement patterns for model year 2027 vehicles as inflection indicator for low-load deposit control formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Production | Captive Group II/III supply insulates margins from petrochemical volatility affecting regional blenders. |
| Telematics-Integrated Predictive Dosing Partnerships | Sensor-data-driven treat rate optimization creates switching costs with fleet operators adopting automated injection. |
| API CK-4/FA-4 Certification Acceleration | OEM approval maintenance secures pricing power against unregistered commodity competitors in economy tier. |
| Municipal Transit Authority Certification Programs | Documented performance standards in Ohio, Pennsylvania, and Michigan open premium margin pools lagging private adoption. |
| Gulf Coast Supply Diversification | Secondary manufacturing footprint outside hurricane-exposed Texas-Louisiana corridor reduces operational risk. |
Research Methodology
Document review covered EPA fuel registration databases, API certification directories, and SEC filings from petrochemical majors, complemented by interviews with fleet maintenance directors, additive procurement leads at third-party logistics providers, tribochemistry R&D directors, and specialized chemical distributors. Secondary validation drew from customs trade data, American Chemistry Council reports, and CARB enforcement pattern disclosures. Bottom-up segment sizing triangulated against top-down petrochemical capacity analysis.
Cross-referencing historical treat rate adoption curves with panel input from formulation chemists and fleet operators anchored volume projections across the analysis window. Segmentation dimensions modeled include product type certification tier, application duty cycle severity, end-user procurement sophistication, and regional regulatory enforcement intensity. CAGRs derived from elasticity-adjusted penetration rates for emission reducers and deposit-control additives. Industry-specific inputs incorporated EPA Tier 3 implementation timelines and Euro VI parallel adoption patterns.
Inputs from fleet maintenance networks and specialized distributors were available through the study window; gaps in real-time treat rate consumption telemetry introduce uncertainty bands around predictive dosing adoption curves. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and base oil price trajectory. Deviation in EPA heavy-duty greenhouse gas standards implementation pace or Gulf Coast hurricane frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
1,4 Butanediol Derivatives Market
Additives
Biosaccharide Gum Market
Additives
Friction Modifier Additives Market
Additives
Ammonium Phosphatide Market
Additives
Inorganic Rheology Modifiers Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Performance Minerals Additives Market
Additives
Supplemental Coolant Additives Market
Additives
Global Calcium Formate Market
Additives
Cosmetic Grade Color Additives Market
Additives
Liquid Thickeners Market
Additives
Automotive Additives Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Global Low-Profile Additive Market