
 Fresh Cherries Market | 2026-2036
Fresh Cherries Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Cherries Market Analysis
Direct-to-retail procurement is tilting as supermarket chains tighten specifications for Brix levels and defect rates. Stemilt Growers leverages integrated orchard-to-shelf logistics across the Pacific Northwest. Rainier Fruit Co. sustains its position through proprietary cultivar development in Washington State. Hood River Cherry Co. anchors regional supply with Columbia River Gorge microclimate advantages.
Fresh cherries are stone fruits of Prunus avium or Prunus cerasus species, harvested at soluble solids concentrations typically exceeding 16 Brix for premium grades and requiring hydrocooling within four hours of picking to maintain stem integrity and firmness. Sweet cherries dominate volume throughput in retail clamshell formats, while sour cherries command specialized margin pools in food processing channels. Organic certification segments attract differentiated pricing in European wholesale markets.
The USDA Agricultural Marketing Service administers grade standards for size and external defects, while FDA enforces Food Safety Modernization Act traceability requirements for domestic distribution. Turkey's Ministry of Agriculture and Forestry oversees export phytosanitary protocols governing access to Chinese and European buyers. Stakeholders must monitor evolving maximum residue limits in destination jurisdictions and calibrate orchard input programs accordingly.
Market Dynamics
The EU F-Gas Regulation is accelerating cold-chain technology replacement across post-harvest logistics, forcing capital redeployment into hydrocooling systems and controlled-atmosphere storage that preserve stem integrity during extended transit windows.
Growth Catalysts
- Premium Bakery Applications:High-Brix cherry varieties above 18 degrees soluble solids are displacing standard grades in European artisan baking channels, creating dedicated procurement contracts with Aegean growers.
- USDA Grade Standard Enforcement:Tightened size and external defect specifications under Agricultural Marketing Service protocols are consolidating supplier bases toward integrated orchard-to-retail operators capable of consistent compliance.
- Hydrocooling Technology Diffusion:Rapid field-cooling systems capable of sub-4-hour temperature reduction are expanding stem-retention rates and extending shelf life for Pacific Northwest export corridors.
Market Restraints
- Refrigerant Cost Volatility:EU F-Gas phasedown schedules are compressing hydrofluorocarbon availability and inflating cold-chain operating costs for Turkish export packers serving Chinese markets.
- Aegean Supply Concentration:Turkey's Izmir and Manisa districts control disproportionate export volume, exposing price discovery to single-region weather shocks and phytosanitary protocol disruptions.
- Fresh-Frozen Substitution:IQF sour cherry segments in industrial baking are capturing margin pools that fresh formats cannot serve due to seasonal availability constraints.
Strategic Opportunities
- Chinese Import Liberalization:Phytosanitary negotiations between Turkey's Ministry of Agriculture and Forestry and Chinese quarantine authorities are creating first-mover advantages for certified export orchards in Aegean districts.
- Organic Certification Arbitrage:EU Regulation 2018/848 compliance costs are segmenting wholesale pricing tiers, rewarding early adopters of integrated pest management in Washington State's Columbia River Gorge.
- Direct-to-Retail Channel Expansion:Supermarket chain consolidation in North American markets is displacing traditional wholesale auctions, favoring volume-contracting relationships with vertically integrated growers.
Industry Challenges
- Traceability System Integration:FDA Food Safety Modernization Act Section 204 requirements are forcing legacy orchard management systems to interoperate with blockchain-enabled lot-tracking platforms, compressing implementation timelines for mid-scale operators.
- Specialized Harvest Labor Scarcity:Hand-picking protocols for stem-retentive sweet cherry grades require skilled crews that compete with tree fruit sectors across simultaneous harvest windows in Yakima Valley and Hood River districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Cherries Market |
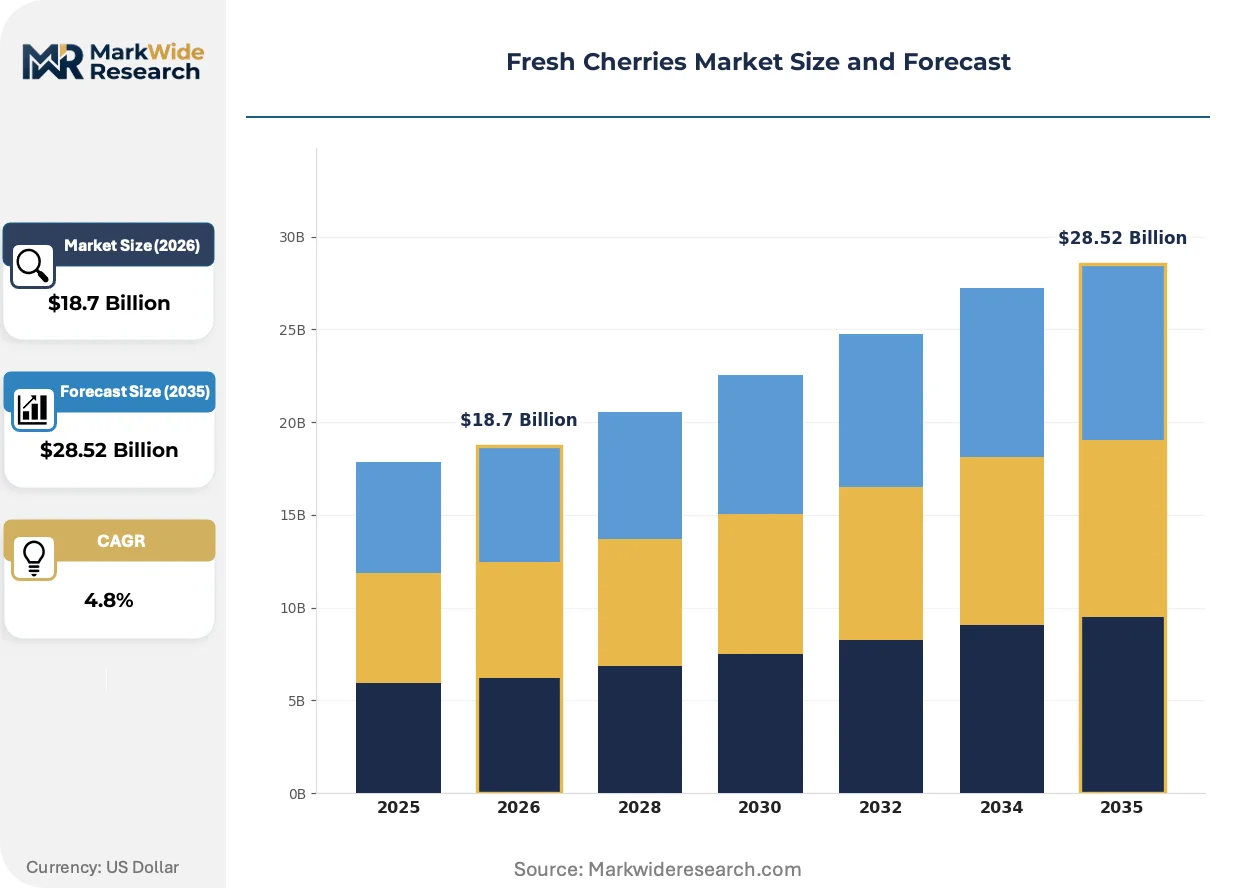
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Cherries, Sour Cherries, Organic Cherries, Conventional Cherries Packing Type: Bags, Boxes, Clamshells, Bulk Sales Channel: Retail, Wholesale, Online, Farmers Markets End User: Food Processing, Bakery, Fresh Consumption, Exporters |
| Companies Covered | Stemilt Growers, Rainier Fruit Co., Hood River Cherry Co., Leelanau Fruit Co., Dole plc, Joy Wing Mau Fruit Technologies Corporation Limited, Smeltzer Orchard Company, Cherry Hill Orchards, Vitin Fruits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Cherries Market Emerging Trajectories
Post-harvest handling protocols are converging with digital traceability platforms, reshaping how quality credentials travel with fruit from orchard to retail shelf. Three developments are compressing traditional intermediation structures.
Blockchain-enabled lot-tracking is digitizing provenance verification across export supply chains. Turkish packers serving EU retail chains are deploying distributed-ledger systems that immutably record hydrocooling timestamps, pesticide application dates, and phytosanitary certificate issuance. This infrastructure is compressing documentary inspection times at Rotterdam and Hamburg entry points while enabling real-time defect-rate attribution to source orchards.
The EU F-Gas Regulation's phasedown mandates are forcing refrigeration infrastructure replacement across cold-chain nodes. Packhouses in Bursa and Manisa provinces are retrofitting ammonia-CO2 cascade systems and magnetic-bearing compressors that eliminate synthetic refrigerant dependency. Washington State operators are adopting similar thermal architectures to preempt California Air Resources Board alignment pressures and secure organic market access.
Supermarket procurement consolidation is concentrating buying power around Brix-level specifications and defect-rate guarantees. Retail chains in Germany and the Netherlands are displacing traditional wholesale auction mechanisms with direct contracting relationships that specify minimum soluble solids thresholds and maximum stem-detachment percentages. This pattern is most visible in Pacific Northwest export corridors where Stemilt Growers and Rainier Fruit Co. maintain integrated logistics capabilities that satisfy tightened inbound quality protocols.
Fresh Cherries Market Segmentation
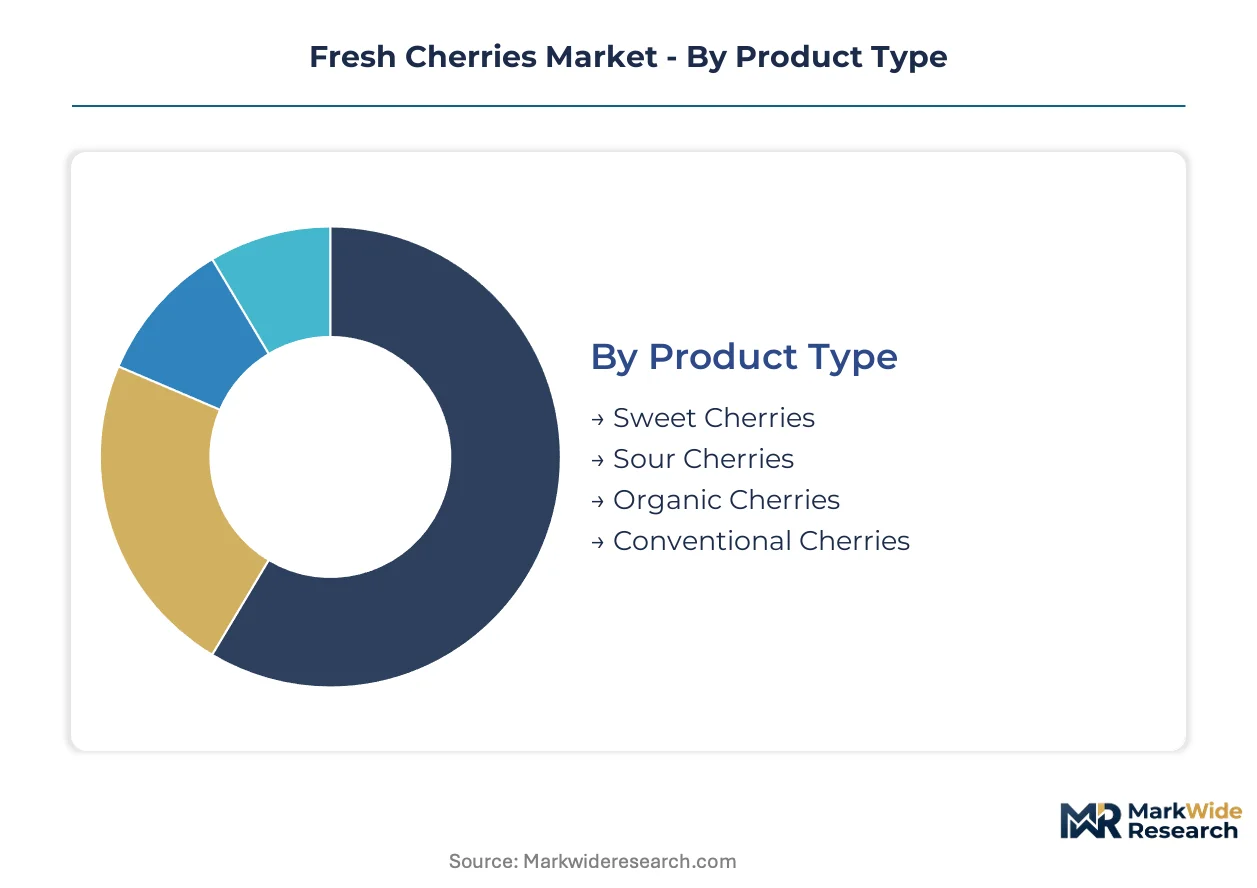
Fresh cherry segmentation reveals divergent velocity profiles across supply chains. Sweet varieties rotate through retail channels within days while sour cherries move through frozen processing pipelines spanning months. Understanding these cycle-time differentials shapes inventory positioning and capital allocation across the value chain.
Product Type:
Sweet varieties turn over fastest through hydrocooled export corridors, while organic certifications extend holding periods through compliance documentation stages.
- Sweet Cherries:Prunus avium varieties harvested above 16 Brix dominate Pacific Northwest export volumes through Stemilt Growers and Rainier Fruit Co. integrated logistics. Retail clamshell specifications in German and Dutch supermarket chains are concentrating procurement toward stem-retentive grades with sub-4-hour field cooling.
- Sour Cherries:Prunus cerasus species command extended processing windows in IQF and industrial baking channels. Turkey's Aegean districts supply concentrated volumes to European artisan bakeries seeking high-acid profiles for preserved applications.
- Organic Cherries:EU Regulation 2018/848 certification requirements extend documentation cycles and limit parallel conventional handling. Washington State's Columbia River Gorge microclimate supports integrated pest management protocols that satisfy European wholesale premium tiers.
- Conventional Cherries:Standard-input orchard management supports volume throughput in North American mass retail without certification overhead. USDA Agricultural Marketing Service grade standards govern size and defect specifications for domestic distribution.
Sweet cherries anchor the volume base while organic certification gains share at the steepest rate.
Packing Type:
Cost tiers separate premium presentation formats from commodity bulk handling, with cold-chain infrastructure requirements scaling non-linearly across the spectrum.
- Clamshells:Rigid PET containers with modified atmosphere properties protect stem integrity through extended retail shelf life. Pacific Northwest exporters deploy these formats for direct-to-supermarket contracts specifying Brix thresholds and defect-rate guarantees.
- Boxes:Corrugated formats with hydrocooled liner systems balance protection with pallet density for wholesale auction channels. Turkish packers in Bursa province are retrofitting ammonia-CO2 cascade refrigeration to maintain temperature integrity through Rotterdam entry points.
- Bags:Perforated polyethylene formats serve high-velocity retail segments with shorter shelf-life expectations. Hood River Cherry Co. utilizes these for regional Columbia River Gorge distribution with reduced cold-chain overhead.
- Bulk:Bin containers for industrial processing channels eliminate packaging cost but require immediate downstream freezing or processing. IQF sour cherry operations in Turkey's Manisa district rely on bulk reception for seasonal concentration.
Clamshells command the highest unit economics while bulk formats handle the greatest tonnage throughput.
Sales Channel:
Customer type segmentation separates specification-driven contract buyers from price-sensitive spot purchasers, with traceability requirements scaling accordingly.
- Retail:Consolidated supermarket chains in North America and Europe displace traditional wholesale auctions with direct contracting. FDA Food Safety Modernization Act Section 204 traceability mandates are forcing blockchain-enabled lot-tracking integration for these accounts.
- Wholesale:Traditional auction mechanisms persist in spot-market price discovery but lose share to integrated orchard-to-shelf operators. Turkish exporters serving Chinese markets navigate phytosanitary protocols through the Ministry of Agriculture and Forestry certification.
- Online:Direct-to-consumer platforms require specialized last-mile cold-chain packaging with expanded insulation and gel-pack configurations. Premium Brix varieties above 18 degrees soluble solids attract disproportionate repurchase rates in this channel.
- Farmers Markets:Localized procurement with minimal packaging and documentation overhead serves fresh consumption in growing districts. Yakima Valley and Hood River operators utilize these outlets for grade-B volume displacement.
Retail contracts provide revenue stability while online channels expand most quickly.
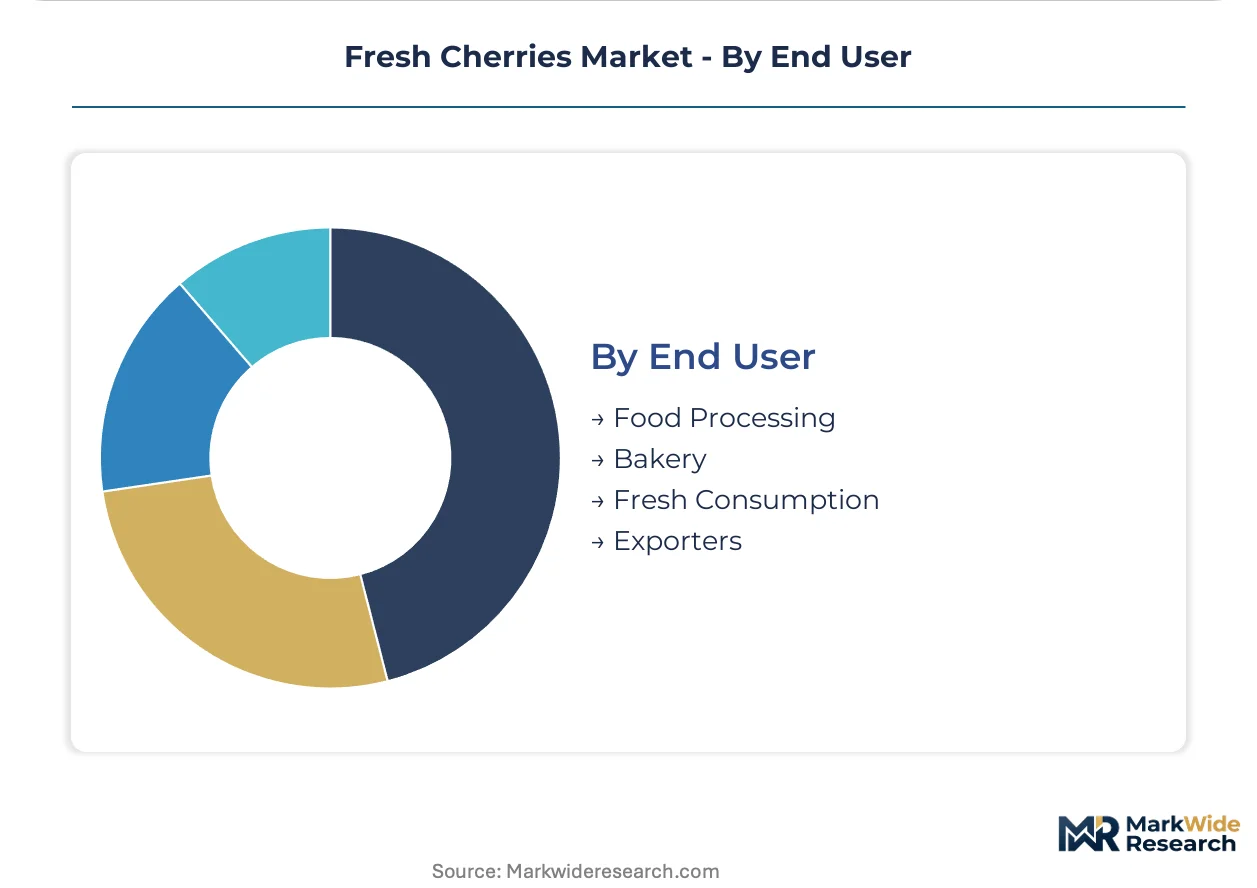
End User:
Application segmentation maps to divergent specification regimes, with food safety protocols and quality thresholds varying sharply across downstream categories.
- Fresh Consumption:Stem-retentive sweet cherry grades with firmness specifications above 300g/mm² command premium positioning. Hydrocooling within four hours of picking remains mandatory for Pacific Northwest export corridors serving Asian markets.
- Food Processing:IQF sour cherry segments capture industrial baking demand that fresh formats cannot serve due to seasonal constraints. Turkey's Aegean supply concentration exposes this channel to single-region weather shocks.
- Bakery:European artisan channels specify high-Brix varieties above 18 degrees soluble solids for preserved and fresh applications. Aegean growers are securing dedicated procurement contracts through direct relationships with German and Dutch buyers.
- Exporters:Phytosanitary compliance and refrigerant cost volatility under EU F-Gas phasedown schedules compress margins for Turkish packers serving Chinese markets. First-mover advantages accrue to certified orchards in Izmir and Manisa districts.
Fresh consumption anchors the volume base while bakery applications gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's import dominance, handling Aegean cherry volumes through hydrocooled container corridors that preserve stem integrity across extended transit windows.
Turkey
Izmir and Manisa districts concentrate Aegean export supply serving Chinese and European buyers. The Ministry of Agriculture and Forestry administers phytosanitary protocols that gate access to premium wholesale channels. Bursa province packhouses are retrofitting ammonia-CO2 cascade refrigeration to satisfy EU F-Gas phasedown mandates.
United States
Pacific Northwest export corridors rotate sweet cherry volumes through hydrocooling systems within four hours of picking. The USDA Agricultural Marketing Service enforces grade standards for size and external defects that consolidate supplier bases. Yakima Valley operators compete for skilled hand-picking crews across simultaneous tree fruit harvest windows.
Germany
Supermarket chain consolidation in North Rhine-Westphalia and Bavaria displaces traditional wholesale auctions with direct contracting. The EU F-Gas Regulation compresses hydrofluorocarbon availability and inflates cold-chain operating costs for Turkish exporters. Rotterdam and Hamburg entry points are deploying blockchain-enabled lot-tracking to compress documentary inspection times.
China
Phytosanitary negotiations with Turkish authorities are creating first-mover advantages for certified Aegean export orchards. SAMR traceability requirements intersect with FDA-aligned standards for re-export processing. Shanghai and Guangzhou cold-chain hubs are expanding controlled-atmosphere storage capacity for premium Brix varieties.
Fresh Cherries Market Vendor Landscape
On the supply side, the industry is consolidating around integrated orchard-to-retail operators capable of satisfying tightened Brix specifications and defect-rate guarantees. Three archetypes dominate: vertically integrated Pacific Northwest exporters with captive hydrocooling infrastructure, Aegean district specialists leveraging Turkish Ministry certification for Chinese market access, and diversified fruit conglomerates with multi-commodity cold-chain assets. Competitive dynamics center on strategic partnerships for traceability platform integration and capacity expansion in ammonia-CO2 refrigeration systems.
Among Pacific Northwest integrated operators, Stemilt Growers and Rainier Fruit Co. occupy positions exemplifying the premium-tier logistics archetype, while Hood River Cherry Co. anchors regional supply concentration within the Columbia River Gorge microclimate. These entities represent distinct competitive responses to supermarket procurement consolidation: Stemilt leverages cross-state orchard networks, Rainier sustains proprietary cultivar development, and Hood River exploits geographic specificity for differentiated grade positioning.
| Leading Market Players |
|---|
| Stemilt Growers |
| Rainier Fruit Co. |
| Hood River Cherry Co. |
| Leelanau Fruit Co. |
| Dole plc |
| Joy Wing Mau Fruit Technologies Corporation Limited |
| Smeltzer Orchard Company |
| Cherry Hill Orchards |
| Vitin Fruits |
| Others |
Supply Flow & Price Mechanics
EU F-Gas refrigerant phasedown schedules compress hydrofluorocarbon availability for Turkish export packers, forcing simultaneous repricing across cold-chain tiers and accelerating ammonia-CO2 cascade retrofits in Aegean packhouses. This regulatory chokepoint widens spreads between premium stem-retentive grades and standard bulk formats while reshaping procurement geography toward integrated orchard-to-retail operators.
Pricing Analysis
Volume-discount tiering structures separate supermarket direct contracts from spot-market auction purchases. Three-tier pricing stratification across premium organic, standard hydrocooled, and economy bulk levels reflects Brix thresholds and certification overhead. Cost compression in mid-tier conventional grades intensifies as EU F-Gas compliance inflates cold-chain operating expenses. Mass retail buyers in North America exhibit highest price sensitivity, while European artisan bakeries accept premiums for high-Brix Aegean varieties above 18 degrees soluble solids.
Supply Chain Analysis
Export-control regimes governing phytosanitary certification between Turkey's Ministry of Agriculture and Forestry and Chinese quarantine authorities restrict flow volumes to certified orchards. Supply concentrates in Turkey's Izmir and Manisa districts, Washington State's Yakima Valley, and Oregon's Hood River region. Hydrocooling infrastructure, skilled hand-picking labor, and ammonia-CO2 refrigeration systems constitute critical input dependencies. Single-region weather exposure in the Aegean creates vulnerability to harvest disruption. Distribution runs through Rotterdam and Hamburg cold-chain hubs for European retail, with Pacific Northwest corridors serving Asian markets via controlled-atmosphere container transit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supermarket chain consolidation across German and Dutch markets has shifted bargaining power toward specification-driven buyers, fragmenting traditional wholesale auction mechanisms and favoring volume-contracting relationships with vertically integrated growers.
For Market Incumbents: Pre-empt margin erosion in conventional grades by securing captive hydrocooling capacity in Columbia River Gorge microclimates and accelerating EU Regulation 2018/848 organic certification to capture premium tier spreads. Defend against IQF sour cherry substitution in industrial baking by locking multi-year direct contracts with Aegean growers for high-Brix fresh supply.
For New Entrants and Emerging Players: Pursue underdeveloped online direct-to-consumer channels where premium Brix varieties above 18 degrees soluble solids attract disproportionate repurchase rates. Target Chinese import liberalization opportunities through phytosanitary certification partnerships with Turkish Ministry-accredited orchards in Izmir district. Lead with specialized last-mile cold-chain packaging capabilities as the go-to-market differentiator.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown milestones reshape the acquisition landscape toward packhouse operators with completed ammonia-CO2 cascade retrofits. Long-term viability over the coming decade rests on backward integration into orchard assets with proven cultivar development programs. Monitor phytosanitary negotiation outcomes between Turkish and Chinese authorities as the signal for first-mover export capacity valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Retrofit | Ammonia-CO2 cascade systems eliminate synthetic refrigerant dependency under EU F-Gas mandates. |
| Direct-to-Retail Contracting | Supermarket consolidation in Germany and Netherlands displaces traditional wholesale auction mechanisms. |
| Organic Certification Investment | EU Regulation 2018/848 compliance unlocks premium pricing tiers in European wholesale markets. |
| Proprietary Cultivar Development | Rainier Fruit Co. demonstrates sustained positioning through exclusive variety breeding programs. |
| Blockchain Traceability Integration | FDA Food Safety Modernization Act Section 204 compliance compresses documentary inspection times at entry ports. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging orchard managers at Stemilt Growers and Rainier Fruit Co., Turkish Ministry of Agriculture and Forestry export certification officers, supermarket category buyers in North Rhine-Westphalia, and cold-chain logistics coordinators at Rotterdam port terminals. Secondary validation drew from USDA Agricultural Marketing Service grade standard filings, EU F-Gas Regulation implementation schedules, FDA Food Safety Modernization Act guidance documents, and Turkish customs export statistics. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Calibration approaches anchored projections to historical hydrocooling adoption curves, phytosanitary protocol negotiation timelines, and organic certification penetration patterns. Segmentation dimensions spanned product type (sweet, sour, organic, conventional), packing format (clamshell, box, bag, bulk), sales channel (retail, wholesale, online, farmers market), and end-use application (fresh consumption, food processing, bakery, export). CAGRs were derived from trend extrapolation of Brix specification tightening and cold-chain technology diffusion rates, with cross-reference to orchard input cost indices and labor availability metrics in Yakima Valley and Hood River districts.
Macroeconomic conditions sit as an overlay; deviation in energy prices, refrigerant commodity costs, or harvest labor wage inflation would shift the trajectory. Forecasts reflect documented assumptions regarding Chinese import liberalization timing and EU F-Gas phasedown adherence. Material shifts in Aegean weather patterns, phytosanitary protocol disruptions, or supermarket procurement consolidation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Dragon Fruit Powder Market