
 Lemon Juice Concentrate Market | 2026-2036
Lemon Juice Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Lemon Juice Concentrate Market Outlook
Argentina is narrowing its cost advantage in lemon juice concentrate as drought cycles compress yields and lift farmgate prices. Döhler leverages backward integration into Argentine citrus estates to secure raw material continuity. SunOpta competes through certified organic processing lines that command premium placement in North American retail channels. Kiril Mischeff anchors European supply through long-term offtake contracts with Spanish cooperatives.
Lemon juice concentrate denotes citrus juice reduced to solids content between 32 and 58 degrees Brix through evaporation, then stabilized via pasteurization or freezing for industrial reconstitution. The product serves primarily as a pH regulator, flavor base, and natural preservative in beverage and sauce formulations. Liquid concentrate occupies the dominant volume position due to its compatibility with high-speed bottling lines, while organic concentrate captures the fastest expansion as clean-label mandates from the beverage industry tighten ingredient specifications. Powdered concentrate holds niche status in bakery applications where water activity control matters, though its higher processing cost limits mainstream penetration.
The FDA enforces juice hazard analysis and critical control point rules that mandate pathogen screening for imported concentrates, while the EPA regulates pesticide residue thresholds under the Food Quality Protection Act. These frameworks elevate compliance costs for suppliers without certified processing infrastructure. Stakeholders must monitor how climate volatility in Mediterranean and South American growing belts reshapes supply reliability and procurement timelines.
Market Dynamics
Climate volatility in Mediterranean and South American citrus belts is compressing harvest windows and forcing processors to reconfigure procurement timelines around shorter, more intense supply pulses.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened residue limits and traceability mandates for imported concentrates are accelerating demand for certified-clean supply chains among European beverage formulators.
- Cold-press technology:Mexican processors expanding cold-press capacity are capturing premium export contracts from US natural juice bottlers seeking flavor integrity.
- Clean-label beverage pipelines:North American manufacturers reformulating around natural citrus bases are pulling additional concentrate volume into high-margin positioning.
Market Restraints
- Input cost volatility:Argentine drought cycles are lifting farmgate lemon prices and eroding the country's historical cost advantage in concentrate production.
- Supply concentration risk:Heavy reliance on Spanish cooperatives for European supply creates vulnerability to Mediterranean heat events and water stress.
- Regulatory friction:FDA juice HACCP rules mandating pathogen screening for imports elevate compliance costs for suppliers without certified processing infrastructure.
Strategic Opportunities
- Organic certification premium:Clean-label mandates from beverage industry procurement teams are opening price premiums for certified organic concentrate lines.
- Powdered concentrate niche:Bakery applications requiring precise water activity control represent underexploited demand for spray-dried formats despite higher processing costs.
- Backward integration:Control over Argentine citrus estates offers processors raw material continuity insurance against climate-driven supply interruptions.
Industry Challenges
- Certification timeline compression:Organic and residue-free certifications require 18-36 month conversion periods that misalign with sudden demand spikes from brand reformulations.
- Cold-chain capex intensity:Frozen concentrate stabilization demands continuous refrigeration infrastructure that strains working capital for mid-scale processors.
- Traceability system integration:EU mandatory origin documentation requires IT upgrades that fragment procurement workflows across legacy ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lemon Juice Concentrate Market |
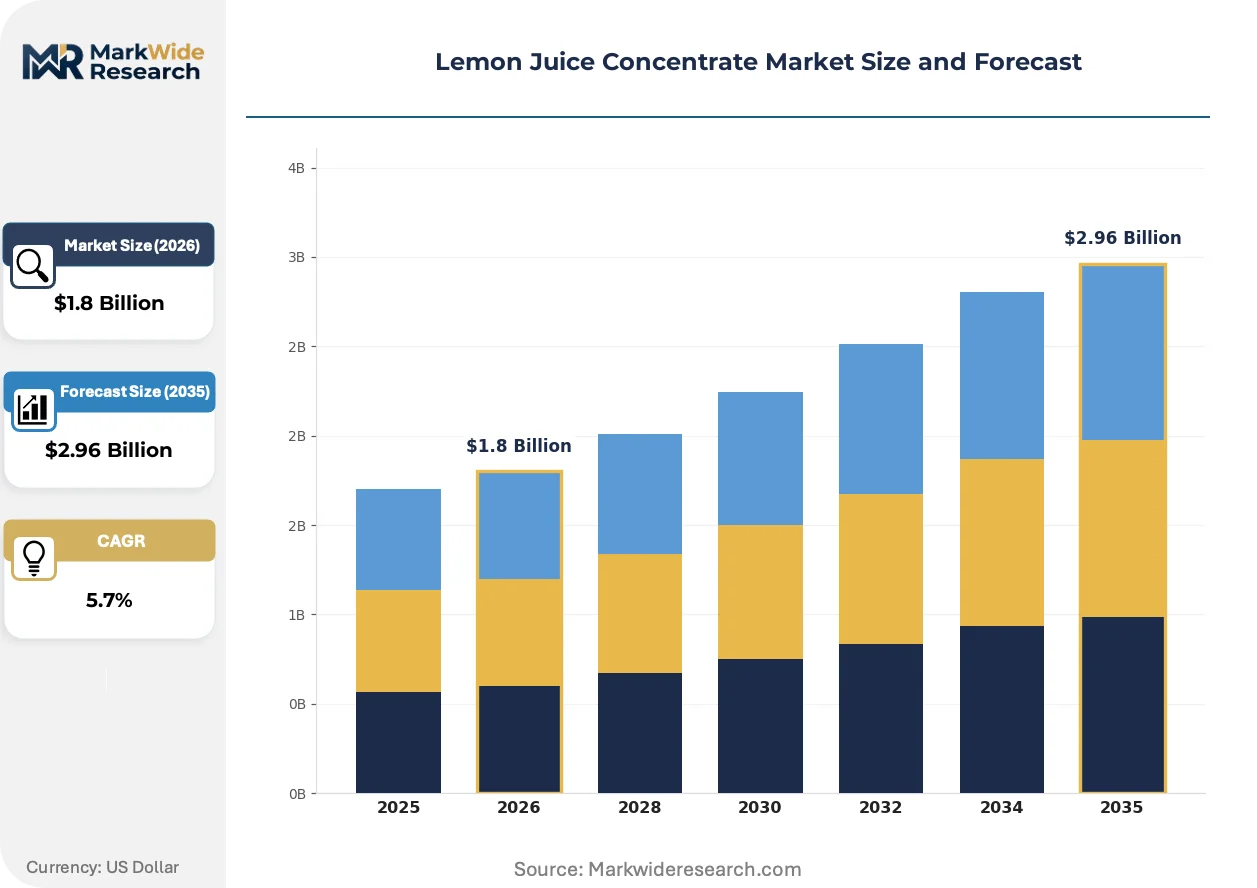
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Concentrate, Liquid Concentrate, Powdered Concentrate, Organic Concentrate End User: Beverage Industry, Food Processing, Household, Bakery Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | SunOpta, Cobell, Döhler, Kiril Mischeff, Lemon Concentrate, The Coca-Cola Company, Asia Farm F&B Pte Ltd., Cardak Concentrate Fruit Juice, CitroGlobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lemon Juice Concentrate Market Strategic Shifts
Digital traceability systems and climate-adaptive processing technologies are reshaping how concentrate suppliers demonstrate provenance and secure supply continuity against harvest volatility.
NIR spectroscopy coupled with blockchain-based lot tracking is digitizing quality verification workflows from orchard to reconstitution facility. Major beverage bottlers in Germany and the Netherlands are mandating real-time Brix and acidity data feeds for contract compliance. This transparency layer is digitizing supplier scorecards and compressing approval cycles for new concentrate sources.
REACH-compliant solvent recovery systems are tightening effluent standards for European concentrate processors operating near water-stressed catchments. The regulation is forcing capital redeployment into closed-loop evaporation infrastructure. Spanish and Italian facilities are responding by retrofitting mechanical vapor recompression units to reduce freshwater draw and discharge liability.
Direct contracting between bottlers and estate-level processors is displacing traditional cooperative aggregation channels in Argentina and Mexico. Large US beverage manufacturers are establishing preferred supplier relationships with single-estate cold-press operations. This disintermediation concentrates volume commitments among fewer, larger processors and marginalizes smaller cooperative exporters without scale to meet minimum lot requirements.
Lemon Juice Concentrate Market Segmentation
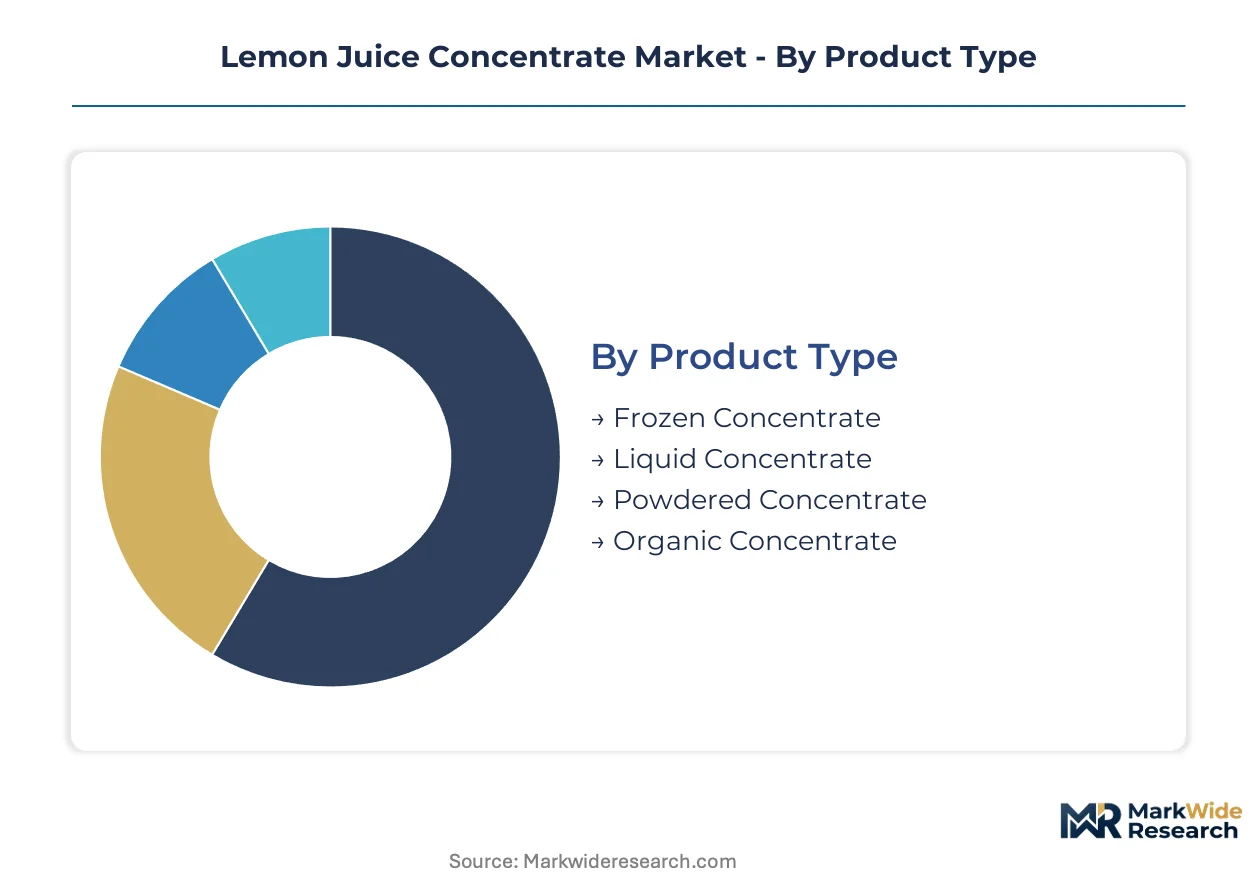
Procurement teams in the lemon juice concentrate market navigate four distinct segmentation dimensions that shape formulation compatibility, shelf-life requirements, and margin capture. Each category reflects divergent cost structures and customer priorities across industrial and retail channels.
Product Type:
Cost tier differentiation separates commodity-grade concentrates from certified-organic and stabilized formats commanding procurement premiums.
- Liquid Concentrate:Reduced to 32-58 degrees Brix through vacuum evaporation, this format dominates high-speed bottling lines at US and Mexican beverage plants. Demand concentrates among North American manufacturers reformulating around natural citrus bases for clean-label positioning.
- Organic Concentrate:Sourced from certified orchards with 18-36 month conversion timelines, this segment captures the steepest expansion trajectory as EU Farm to Fork residue limits tighten and beverage procurement teams mandate traceable supply chains.
- Frozen Concentrate:Pasteurized and blast-frozen for flavor preservation, this format serves premium juice bottlers requiring minimal thermal degradation despite continuous cold-chain infrastructure costs.
- Powdered Concentrate:Spray-dried to sub-5% moisture for water activity control, this niche format supplies bakery applications where precise moisture management outweighs higher processing costs.
Liquid concentrate holds installed capacity. Organic concentrate is rotating up the share rankings.
End User:
Application-driven demand splits between industrial-scale formulation and retail-ready consumption patterns.
- Beverage Industry:Constitutes the dominant volume sink, with pH regulation and natural preservative functions driving procurement from Argentine and Spanish processors. Cold-press capacity expansion in Mexico is capturing premium contracts from US natural juice bottlers seeking flavor integrity.
- Food Processing:Sauce and condiment manufacturers leverage concentrate for acidity standardization. FDA juice HACCP pathogen screening mandates elevate compliance costs for suppliers without certified infrastructure.
- Bakery:Powdered concentrate penetration remains limited by cost, though precise water activity control creates formulation advantages for industrial bakeries.
- Household:Small-format retail sales concentrate through supermarket and online channels, with organic certification commanding shelf placement premiums.
Beverage industry holds installed capacity. Food processing is rotating up the share rankings.
Packaging Type:
Volume and shelf-life requirements dictate material selection across ambient, chilled, and frozen distribution tiers.
- Bottles:HDPE and glass containers dominate liquid concentrate for industrial reconstitution facilities requiring precise dosing and compatibility with high-speed production lines.
- Tetra Packs:Aseptic carton technology extends ambient shelf life for food service and retail channels, with European processors adopting REACH-compliant solvent recovery systems to tighten effluent standards.
- Cans:Metal packaging serves frozen concentrate stabilization, though cold-chain capex intensity strains working capital for mid-scale distributors.
- Pouches:Flexible format growth concentrates in household and food service segments seeking portion control and reduced shipping cube.
Bottles hold installed capacity. Tetra Packs are rotating up the share rankings.
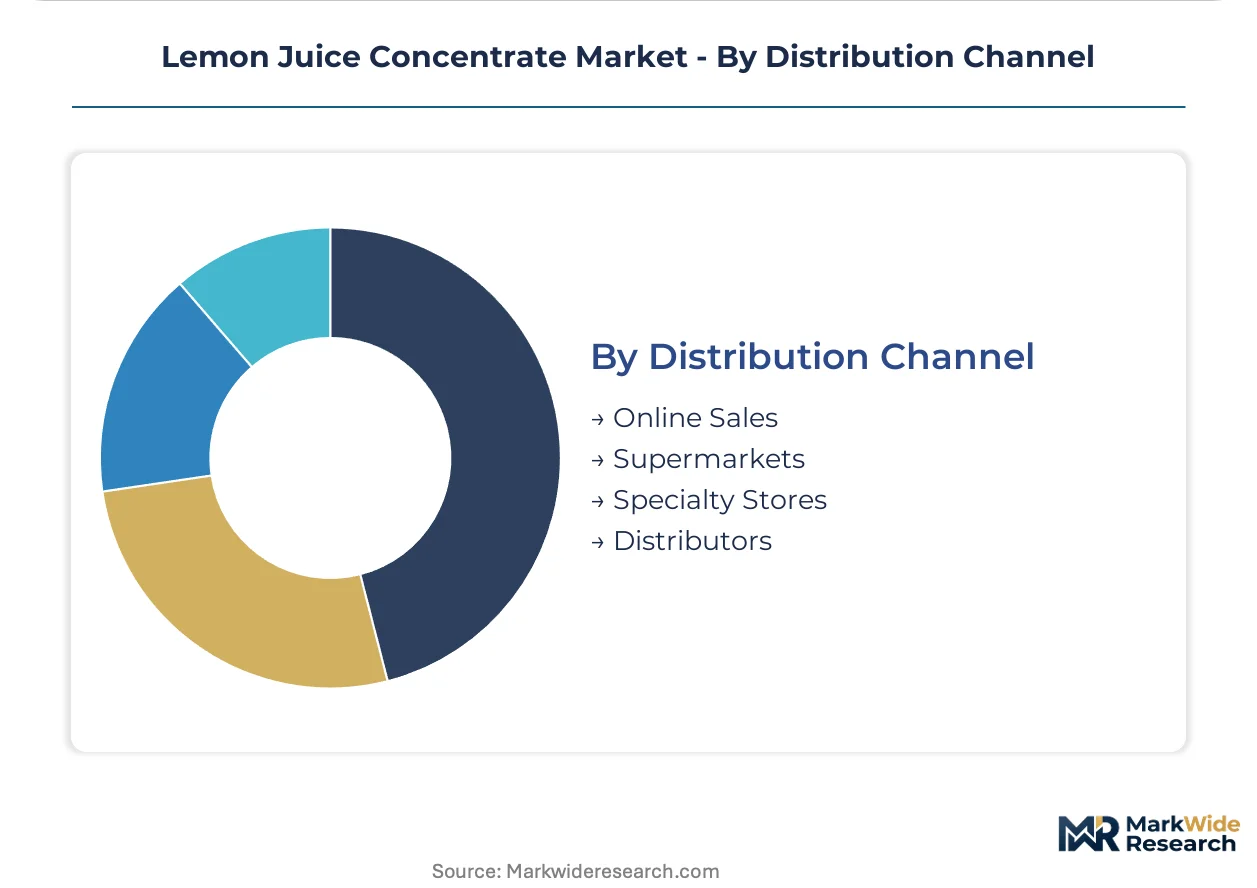
Distribution Channel:
Customer type and order scale fragment procurement workflows between direct industrial contracting and retail intermediation.
- Distributors:Industrial ingredient distributors aggregate volume from Argentine cooperatives and Spanish processing estates, though direct bottler-to-estate contracting is displacing traditional aggregation channels for large US manufacturers.
- Supermarkets:Retail concentrate sales concentrate in North American and European chains, with organic SKUs capturing premium placement in clean-label aisles.
- Specialty Stores:Natural food retailers and ethnic grocery channels serve niche demand for single-origin and cold-pressed concentrates with provenance documentation.
- Online Sales:E-commerce penetration accelerates for household-format concentrates, with blockchain-based lot tracking enabling digital traceability compliance for EU-bound shipments.
Distributors hold installed capacity. Online sales are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina consumes lemon juice concentrate primarily as an industrial reconstitution input for beverage manufacturing, while Germany and the United States drive premium demand for certified-organic formats with full traceability documentation.
Argentina
Beverage bottlers in Buenos Aires and Mendoza provinces absorb the bulk of domestic concentrate output for carbonated soft drink acidulation. The country's national food safety regulator enforces residue monitoring protocols under Mercosur alignment pressures. Tucumán province hosts the densest clustering of evaporator facilities, where drought-induced farmgate price spikes are compressing processor margins.
Spain
Murcia and Valencia autonomous communities supply European beverage manufacturers with liquid concentrate for clean-label reformulation pipelines. EFSA residue limit enforcement under the EU Farm to Fork Strategy tightens import competition for non-EU suppliers. Almería province processors are retrofitting mechanical vapor recompression units to meet REACH-compliant effluent standards.
United States
California and Florida bottlers pull concentrate volume for natural juice positioning in retail channels. FDA juice HACCP rules mandate pathogen screening for all Argentine and Mexican imports, elevating compliance costs for uncertified suppliers. Ventura County cold-press operations are capturing premium contracts from national beverage brands seeking flavor integrity.
Mexico
Jalisco and Michoacán processors are expanding cold-press capacity to serve US natural juice bottlers with minimal thermal degradation formats. The country's federal commission for protection against sanitary risk enforces alignment with FDA import protocols. Colima state estate-level operations are displacing traditional cooperative aggregation through direct preferred-supplier contracts.
Germany
Bavarian and North Rhine-Westphalian beverage formulators drive demand for organic concentrate with blockchain-tracked provenance. ECHA REACH compliance requirements force solvent recovery system investments among contract processors. Hamburg port logistics clusters are digitizing supplier scorecards with real-time Brix and acidity data feeds for contract compliance.
Lemon Juice Concentrate Market Competitive Environment
Capability concentration sits with estate-integrated processors controlling Argentine citrus assets; scale advantage sits with diversified ingredient houses operating multi-fruit processing networks. The market structures around three tiers: backward-integrated estate operators, certified-organic specialists, and commodity-scale evaporators serving industrial acidulation demand. Dominant competitive moves include direct bottler-to-estate contracting that disintermediates cooperative channels, and refrigerated capacity expansion to capture frozen concentrate premiums.
Among estate-integrated operators, Döhler anchors the backward-integration archetype through Argentine citrus asset control. SunOpta and Kiril Mischeff occupy positions within the certified-organic tier, representing the premium-channel specialization vector. These three companies exemplify how procurement teams now prioritize traceability documentation and climate-resilient supply continuity over pure unit cost optimization.
| Leading Market Players |
|---|
| SunOpta |
| Cobell |
| Döhler |
| Kiril Mischeff |
| Lemon Concentrate |
| The Coca-Cola Company |
| Asia Farm F&B Pte Ltd. |
| Cardak Concentrate Fruit Juice |
| CitroGlobe |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Argentine evaporator facilities during drought-compressed harvests is forcing processors to bid aggressively for limited fruit, elevating farmgate premiums and reshaping supplier pricing power across export tiers.
Pricing Analysis
Long-term offtake contracts with Spanish cooperatives anchor European pricing stability, while spot purchases in Argentine drought years trigger volatile premiums. Price differentiation rests on organic certification grade and cold-press processing tier. Cost compression in commodity-grade liquid concentrate is intensifying because Mexican capacity expansion erodes Argentine cost advantage. Small-scale cooperatives exhibit highest price sensitivity; estate-integrated processors with backward integration into citrus assets demonstrate lowest sensitivity due to captive supply buffers.
Supply Chain Analysis
EU Farm to Fork Strategy residue documentation requirements restrict concentrate flows from non-certified suppliers into European beverage channels. Geographic supply concentration centers on Argentina, Spain, and Mexico as dominant export origins. Raw material dependencies include Tucumán province lemons, Murcia region citrus, and Jalisco estate fruit. Single-source vulnerability runs through Mediterranean heat events threatening Spanish cooperative output. Distribution runs through industrial ingredient distributors aggregating cooperative volume, though direct bottler-to-estate contracting is displacing traditional channels for large US manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lemon juice concentrate market is accelerating through clean-label disruption as EU Farm to Fork traceability mandates and North American natural beverage reformulations compress procurement timelines for certified supply chains.
For Market Incumbents: Insulate margin position by deepening backward integration into Argentine citrus estates before drought cycles erode raw material access further. Accelerate organic certification pipeline investments to capture 18-36 month conversion premiums ahead of competitor capacity. Prioritize cold-chain infrastructure in Mexico to defend against emerging estate-level processors capturing US premium contracts.
For New Entrants and Emerging Players: Establish a beachhead in powdered concentrate for industrial bakery applications where water activity control commands formulation stickiness despite higher processing costs. Target specialty store channels with single-origin cold-pressed formats carrying blockchain-tracked provenance documentation. Pursue direct-to-bottler contracting models that bypass cooperative aggregation layers and capture full margin capture.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across frozen concentrate stabilization infrastructure as continuous refrigeration demands strain working capital for mid-scale processors. Estate-integrated operators with captive Argentine citrus assets represent the most defensible acquisition profile over the five-to-ten year horizon. Monitor EU mandatory origin documentation IT upgrade timelines as signal for procurement workflow fragmentation creating distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Argentine Citrus Estates | Döhler's estate control secures raw material continuity against climate-driven supply interruptions. |
| Organic Certification Pipeline Investment | SunOpta's certified processing lines command premium placement in North American retail channels. |
| Cold-Press Capacity Expansion | Mexican processors capture premium export contracts from US natural juice bottlers seeking flavor integrity. |
| Blockchain-Based Traceability Implementation | German beverage bottlers mandate real-time Brix and acidity data feeds for contract compliance. |
| REACH-Compliant Solvent Recovery Retrofit | Spanish facilities deploy mechanical vapor recompression to reduce freshwater draw and discharge liability. |
Study Parameters
A spread of perspectives from beverage formulation executives, procurement leads at North American bottlers, Argentine estate operators, Spanish cooperative managers, and Mexican cold-press technicians converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade records, FDA import inspection data, EU Farm to Fork strategy documentation, and SEC filings from publicly traded ingredient houses. Bottom-up volume modeling from processor capacity utilization and top-down demand estimation from beverage industry reformulation pipelines were triangulated to constrain forecast variance.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, end-use application, packaging format, and distribution channel. CAGRs were derived from fitted growth curves calibrated to historical concentrate trade flows and projected clean-label beverage pipeline expansions. Industry-specific forecast inputs included drought probability distributions in Argentine growing belts and EU residue limit enforcement timelines.
Sensitivities concentrate around climate volatility in Mediterranean and South American citrus belts, sudden EU traceability mandate acceleration, and cold-chain infrastructure investment pacing. Forecasts reflect documented assumptions on cooperative aggregation channel displacement rates and organic certification conversion timelines. Material shifts in Argentine drought frequency or EU Farm to Fork enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Fresh Lemons Market