
 Sea Buckthorn Market | 2026-2036
Sea Buckthorn Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Buckthorn Market Analysis
The capital-intensity divergence between small-batch organic processors and industrial extractors is unwinding competitive stability in sea buckthorn supply chains. SIBU Sea Berry Therapy leverages vertical integration from Mongolian orchards to finished oils, sustaining margin control across volatile raw material cycles. STADA Arzneimittel AG competes through pharmaceutical-grade extraction certifications, while Erbology Ltd differentiates via cold-pressed, single-origin positioning in premium channels.
Sea buckthorn comprises deciduous shrubs producing berries with exceptional omega-7 palmitoleic acid concentrations, typically extracted through cold-pressing or CO2 supercritical methods for oil retention. The plant serves nutraceutical, cosmetic, and pharmaceutical industries seeking natural anti-inflammatory and tissue-regenerative compounds. Oil formulations command the highest margin pools due to concentration thresholds required for dermal and dietary applications, while juice segments face commoditization from bulk Chinese supply. Cosmetics applications are expanding fastest as formulators replace synthetic emollients with sea buckthorn-derived alternatives in K-beauty and European natural skincare lines.
EU REACH and EFSA novel food frameworks govern ingredient approval and residue limits for European market access, while China's NMPA and GB standards regulate domestic processing and export certification. Organic certification under USDA National Organic Program and EU 2018/848 create tiered pricing structures that segment procurement channels. Stakeholders must monitor evolving pharmacopeia monograph adoptions that could reclassify sea buckthorn extracts from food-grade to API-grade status, fundamentally altering compliance costs and customer qualification requirements.
Market Dynamics
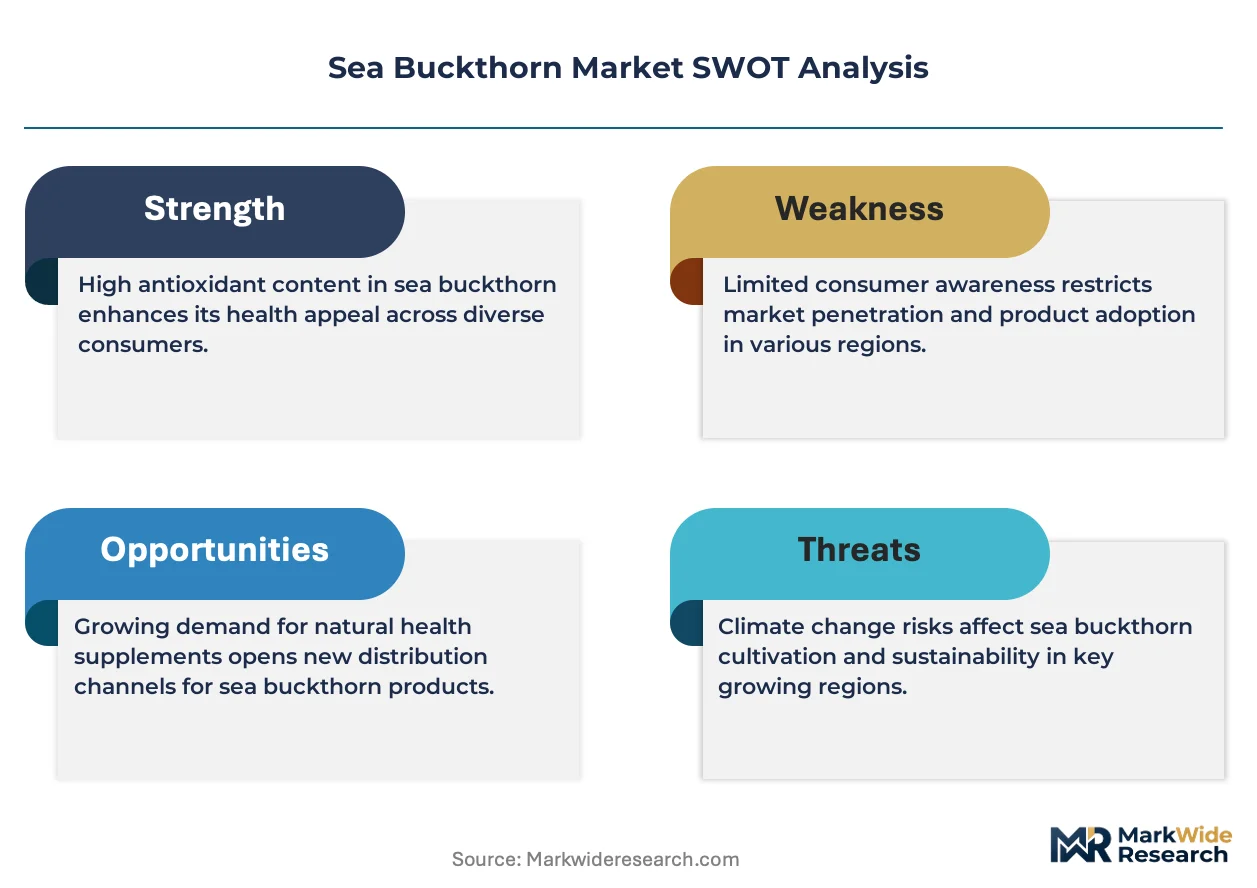
Industrial-scale berry processing in China's Ningxia Autonomous Region is consolidating raw material flows while REACH compliance and organic certification requirements in Germany are fragmenting procurement channels into traceability-verified tiers.
Growth Catalysts
- Omega-7 nutraceutical formulations:Cosmetic and dietary supplement manufacturers are accelerating extraction contracts for palmitoleic acid concentrates, pulling volume through cold-pressing and CO2 supercritical facilities.
- EU 2018/848 organic certification:Premium channel segmentation is creating price premiums for certified-origin oils, rewarding processors with backward integration into Mongolian and Ningxia orchard networks.
- K-beauty emollient substitution:Formulators in South Korea are replacing synthetic moisturizers with sea buckthorn-derived alternatives, expanding cosmetics applications faster than traditional nutraceutical channels.
Market Restraints
- Raw material concentration risk:Overreliance on Ningxia state-backed cultivation programs exposes processors to regional climate volatility and single-source supply disruptions.
- EFSA novel food framework friction:European market entry requires extensive safety dossiers for new oil formulations, extending approval timelines and freezing smaller exporters from premium segments.
- Juice segment commoditization:Bulk Chinese berry supply is compressing margins in non-oil applications, diverting capital toward extraction infrastructure and away from whole-fruit processing.
Strategic Opportunities
- Pharmacopeia API-grade reclassification:Evolving monograph adoptions could elevate extracts from food-grade to active pharmaceutical ingredient status, opening pharmaceutical manufacturing partnerships.
- USDA National Organic Program tiered pricing:Three-tier pricing structure across premium, standard, and economy levels allows processors to capture margin pools from distinct certification-segmented buyer clusters.
- European natural skincare channel expansion:Cold-pressed, single-origin positioning aligns with clean beauty mandates in Germany and France, creating direct-to-brand supply relationships outside commodity exchanges.
Industry Challenges
- Supercritical extraction capex intensity:CO2 extraction equipment requires substantial upfront investment, constraining mid-scale processors from reaching pharmaceutical-grade certification thresholds.
- Dual certification timeline complexity:Simultaneous pursuit of EU organic and REACH compliance creates documentation bottlenecks, delaying market entry by 18-24 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Buckthorn Market |
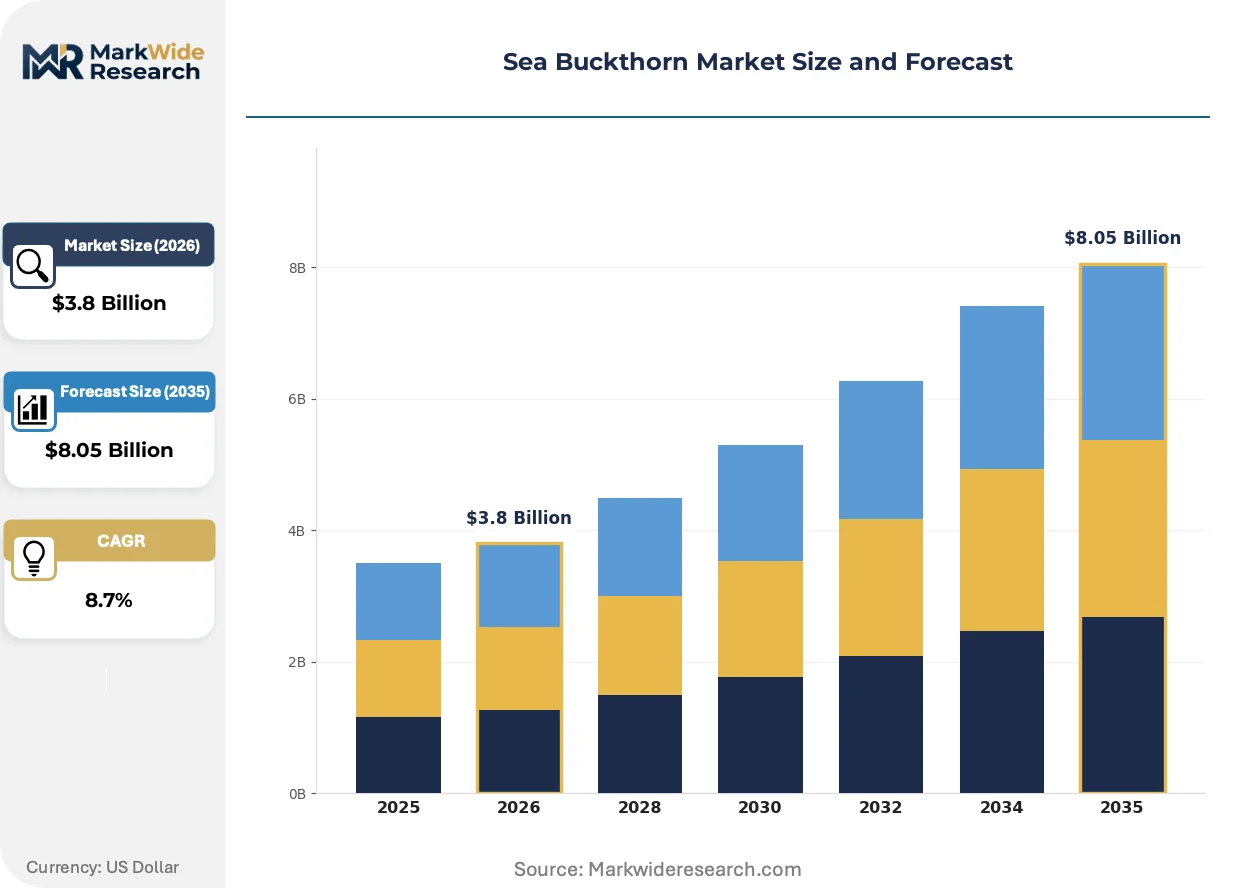
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Juice, Capsules Application: Nutraceuticals, Cosmetics, Pharmaceuticals, Food & Beverages End User: Hospitals, Clinics, Retailers, Manufacturers Sales Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | SeabuckWonders, SIBU Sea Berry Therapy, Weleda AG, W.S. Badger Company Inc., Natura Health Products, Wellsash, Erbology Ltd, STADA Arzneimittel AG, TEREZIA COMPANY s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Buckthorn Market Emerging Trajectories
Extraction technology convergence with cosmetic formulation science is reshaping value capture, while regulatory frameworks are hardening traceability requirements and buyer procurement patterns are fragmenting around certification tiers.
CO2 supercritical extraction is supplanting traditional cold-pressing for high-purity omega-7 retention in pharmaceutical-grade applications. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these systems to meet EMA quality standards. The technology is compressing viable supplier pools to processors with capital reserves for advanced equipment.
REACH substance registration deadlines are tightening residue limit documentation for berry-derived imports into European cosmetic supply chains. ECHA compliance costs are forcing mid-scale processors to abandon spot-market sales in favor of long-term brand partnerships with verified traceability. German formulators are responding by consolidating supplier bases to vertically integrated orchard-to-oil operators.
Certification-driven procurement fragmentation is splitting buyer behavior between organic-tagged premium channels and conventional bulk supply. Direct contracting between cosmetic brands and Ningxia processors is replacing trader-mediated spot purchases. South Korean skincare manufacturers are most visibly adopting this model, establishing captive supply relationships that bypass traditional export intermediaries.
Sea Buckthorn Market Segmentation
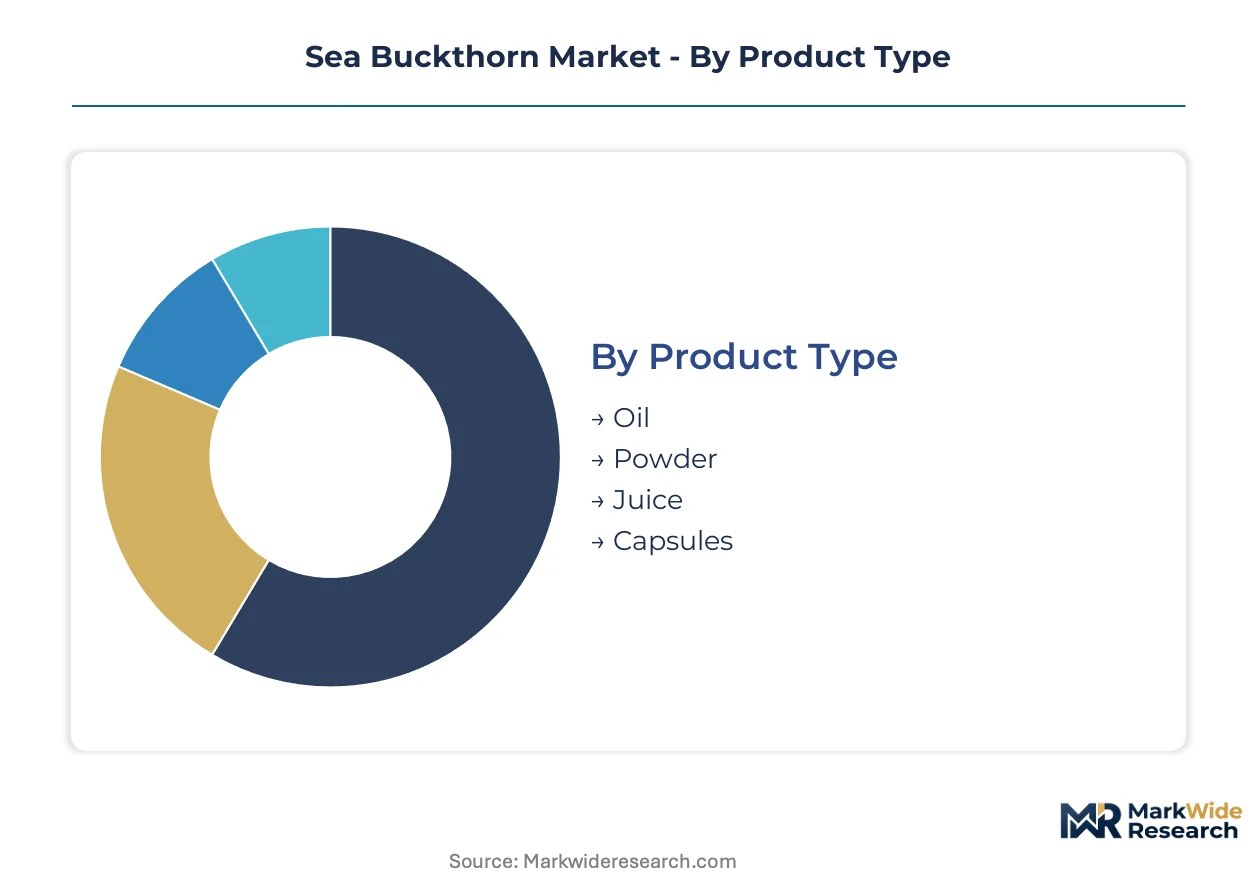
Sea buckthorn value capture diverges sharply across extraction formats and end-use specifications. Pharmaceutical-grade oil commands premium multiples over commoditized juice, while certification tiers fragment procurement channels into traceability-verified supply relationships.
Product Type:
Oil formulations concentrate margin pools due to palmitoleic acid thresholds required for dermal and dietary applications, while bulk powder and juice segments face compression from Chinese oversupply.
- Oil:Cold-pressed and CO2 supercritical extracts retain omega-7 concentrations for pharmaceutical and cosmetic formulations. Demand concentrates in German nutraceutical contract manufacturers seeking EMA-quality certifications for palmitoleic acid concentrates.
- Powder:Spray-dried berry extracts serve food fortification and supplement blending applications with lower purity requirements than oil derivatives. Demand concentrates in European private-label supplement manufacturers prioritizing cost-efficient formulation over bioactive retention thresholds.
- Juice:Whole-fruit processing yields commoditized volumes for beverage applications.
- Capsules:Encapsulated oil and powder blends target direct-to-consumer supplement channels.
Oil holds installed capacity. Powder is rotating up the share rankings.
Application:
Cosmetics applications are expanding most quickly as K-beauty and European natural skincare lines displace synthetic emollients, while nutraceuticals anchor volume throughput.
- Nutraceuticals:Dietary supplement manufacturers formulate omega-7 concentrates for anti-inflammatory and metabolic health positioning. SIBU Sea Berry Therapy and Erbology Ltd compete through cold-pressed, single-origin certifications in premium channels.
- Cosmetics:Formulators in South Korea and Germany replace synthetic moisturizers with sea buckthorn-derived alternatives in clean beauty lines. REACH compliance requirements are consolidating supplier bases to vertically integrated orchard-to-oil operators with verified residue documentation.
- Pharmaceuticals:API-grade extraction awaits pharmacopeia monograph adoption for tissue-regenerative compound classification.
- Food & Beverages:Juice and powder incorporation into functional beverages and fortified foods faces margin pressure from bulk Ningxia supply.
Nutraceuticals dominate volume throughput. Cosmetics is climbing the fastest.
End User:
Procurement authority is shifting from hospital formularies toward retail and manufacturing channels as direct-to-brand contracting bypasses traditional distribution intermediaries.
- Retailers:Health food chains and specialty supplement stores curate certified-origin SKUs for clean-label consumers. German organic retailers under EU 2018/848 requirements are consolidating supplier relationships with Mongolian and Ningxia processors demonstrating backward orchard integration.
- Manufacturers:Cosmetic and nutraceutical contract manufacturers specify extraction methods and certification tiers in direct procurement agreements. South Korean skincare manufacturers establish captive supply relationships that displace trader-mediated spot purchases.
- Hospitals:Clinical nutrition and wound care applications await pharmacopeia reclassification for API-grade status.
- Clinics:Functional medicine practitioners recommend omega-7 supplements for mucosal and dermatological conditions.
Manufacturers hold procurement leverage. Retailers is gaining share fastest.
Sales Channel:
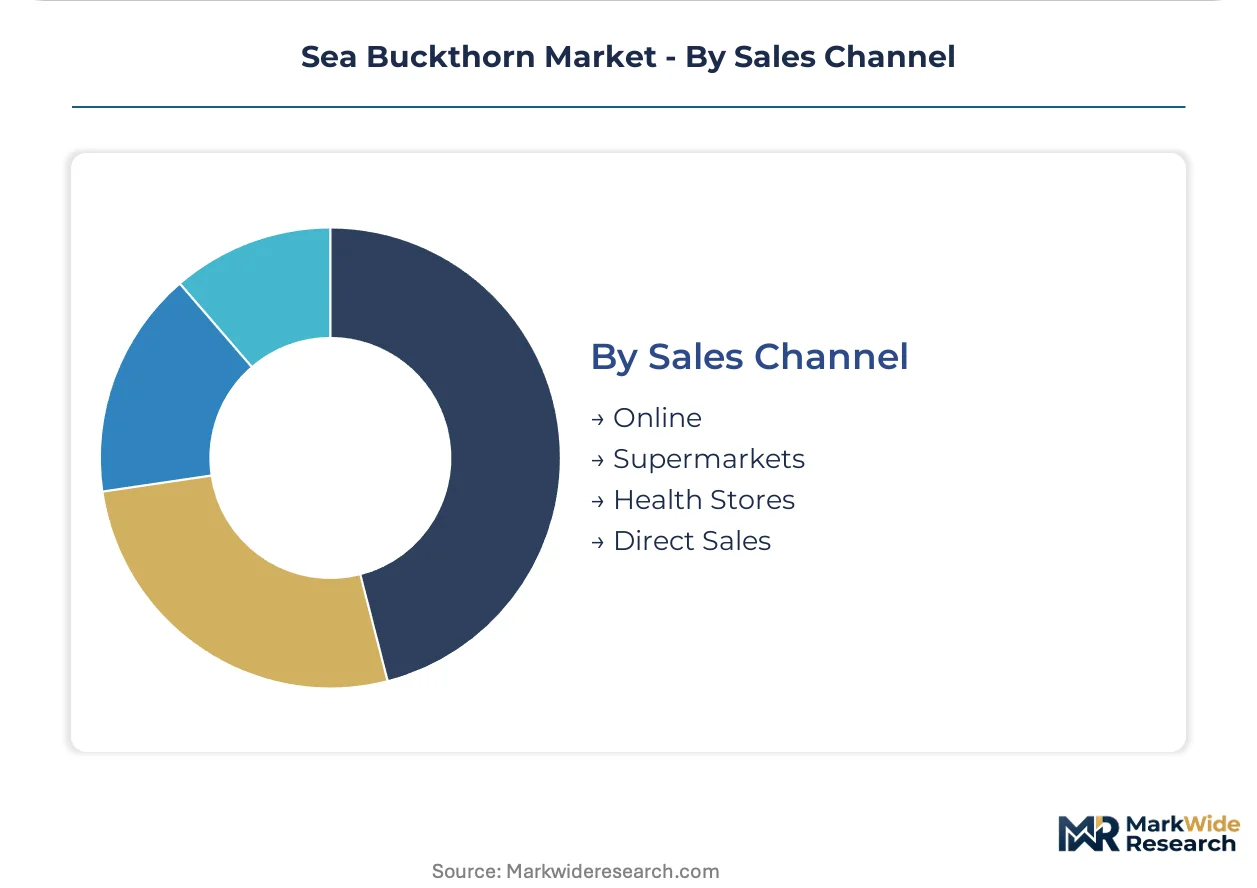
Channel fragmentation reflects certification-tier segmentation, with premium oils bypassing conventional retail for direct brand relationships while bulk juice moves through commodity exchanges.
- Direct Sales:Long-term supply contracts between cosmetic brands and Ningxia processors eliminate intermediary markups. REACH documentation requirements under ECHA frameworks favor direct relationships with traceability-verified operators over spot-market sourcing.
- Online:E-commerce platforms enable single-origin and organic-certified positioning for premium oil SKUs. Erbology Ltd and comparable specialists leverage direct-to-consumer channels to communicate cold-pressed extraction narratives.
- Health Stores:Brick-and-mortar specialty retailers curate USDA National Organic Program certified products for clean-label demographics.
- Supermarkets:Mass-market juice and capsule distribution faces price compression from bulk Chinese supply.
Direct sales holds contract value. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and South Korea absorb premium pricing for certified-origin oils, while mass-market channels in China and North America squeeze margins on bulk juice and powder formats.
Germany
EMA-quality certifications for palmitoleic acid concentrates drive procurement from cold-pressing and CO2 supercritical facilities. EU 2018/848 organic certification and REACH substance registration under ECHA tighten residue limit documentation for berry-derived imports. Processing clusters in Bavaria and Baden-Württemberg consolidate supplier relationships to vertically integrated orchard-to-oil operators.
China
State-backed cultivation programs in Ningxia Autonomous Region support industrial-scale berry processing for domestic nutraceutical and export markets. NMPA and GB standards regulate processing and export certification for oil and juice derivatives. Yinchuan processing corridors concentrate CO2 extraction capacity serving pharmaceutical-grade contract manufacturers.
South Korea
K-beauty formulators displace synthetic emollients with sea buckthorn-derived alternatives in clean skincare lines. MFDS cosmetic ingredient safety assessments govern novel oil formulation approvals. Seoul metropolitan area manufacturers establish captive supply relationships with Ningxia processors, bypassing traditional export intermediaries.
United States
USDA National Organic Program certification creates tiered pricing structures segmenting procurement channels for premium supplement and cosmetic applications. FDA dietary supplement regulations and FTC labeling requirements govern omega-7 health claim substantiation. West Coast nutraceutical contract manufacturers source cold-pressed oils through direct Mongolian orchard partnerships.
Switzerland
Swissmedic pharmaceutical-grade extraction standards attract nutraceutical contract manufacturers seeking EMA-aligned quality certifications. Organic certification under EU 2018/848 and Swiss federal organic ordinances create premium channel segmentation. Basel-region processors leverage proximity to German and French markets for cross-border cosmetic brand supply relationships.
Sea Buckthorn Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with orchard-to-oil operators commanding margin control against trader-dependent processors. Market structure tilts toward backward integration as raw material volatility rewards captive supply networks. Two strategic archetypes dominate: vertically integrated Mongolian-Ningxia operators with certification stack depth, and German-Swiss pharmaceutical-grade extractors with EMA-quality infrastructure. Competitive moves center on pharmacopeia monograph positioning for API-grade reclassification and direct-to-brand contracting that eliminates intermediary markups.
Among orchard-integrated specialists, SIBU Sea Berry Therapy and Erbology Ltd exemplify the premium-tier archetype through cold-pressed, single-origin positioning. STADA Arzneimittel AG occupies the pharmaceutical-grade extraction tier with EMA-aligned certification infrastructure. SeabuckWonders represents North American market presence through organic-certified channel development.
| Leading Market Players |
|---|
| SeabuckWonders |
| SIBU Sea Berry Therapy |
| Weleda AG |
| W.S. Badger Company Inc. |
| Natura Health Products |
| Wellsash |
| Erbology Ltd |
| STADA Arzneimittel AG |
| TEREZIA COMPANY s.r.o. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for cold-pressed sea buckthorn oil create pricing leverage for backward-integrated processors in Ningxia and Mongolia, compressing margins for trader-dependent operators who lack orchard control and EFSA-compliant traceability documentation.
Pricing Analysis
After-sales service contracts for technical extraction support and formulation consulting drive lifetime value for CO2 supercritical equipment vendors. Three-tier pricing structure across premium, standard, and economy levels segments procurement channels, with EU 2018/848 organic certification and REACH residue documentation commanding substantial premiums over conventional bulk supply. Cost compression in juice segments is intensifying because Ningxia state-backed cultivation programs flood commodity channels with unprocessed berry volume. Cosmetic contract manufacturers in South Korea and Germany demonstrate the lowest price sensitivity due to clean beauty mandates and captive supply requirements.
Supply Chain Analysis
China and Mongolia anchor sea buckthorn cultivation and primary processing, with Germany and Switzerland hosting pharmaceutical-grade extraction infrastructure for EMA-quality oil concentrates. Raw material flows draw from Ningxia Autonomous Region orchards, Mongolian high-altitude plantations, and scattered European organic plots for premium channel differentiation. Single-source vulnerability concentrates in Ningxia's state-backed cultivation zones, where regional climate volatility and policy shifts threaten uninterrupted berry supply. Distribution runs through direct long-term contracts between cosmetic brands and orchard-integrated processors, displacing traditional trader-mediated spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sea buckthorn's trajectory as a high-growth disruption rests on CO2 supercritical extraction convergence with cosmetic formulation science, creating defensible margin pools for operators with pharmacopeia-grade certification infrastructure.
For Market Incumbents: Shield margin positions by deepening backward integration into Mongolian orchard networks and accelerating pharmacopeia monograph positioning for API-grade reclassification. EFSA novel food framework friction threatens smaller competitors with 18-24 month approval delays, creating acquisition opportunities for REACH-compliant operators with documentation depth. For New Entrants and Emerging Players: Lead with single-origin, cold-pressed positioning in European natural skincare channels where clean beauty mandates displace synthetic emollient suppliers. The most penetrable white space sits in direct-to-brand contracting for K-beauty formulators seeking verified traceability outside Ningxia commodity flows, leveraging USDA National Organic Program certification as market entry credential. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory fragmentation between EU REACH, EFSA novel food, and China's NMPA creates tiered pricing inefficiencies that vertically integrated operators can exploit across multiple compliance regimes. Acquisition targets should demonstrate captive orchard supply and dual certification stack depth. The signal to watch is pharmacopeia monograph adoption elevating extracts from food-grade to API-grade status, fundamentally altering customer qualification requirements and margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Networks | Captive supply of Ningxia and Mongolian berries insulates processors from raw material volatility and trader markups. |
| Pharmacopeia Monograph Positioning | API-grade reclassification under EMA or USP standards opens pharmaceutical manufacturing partnerships and premium pricing tiers. |
| Dual Certification Stack Investment | Simultaneous EU 2018/848 organic and REACH compliance creates defensible segmentation in German and French cosmetic channels. |
| Direct-to-Brand Contracting Model | Long-term supply agreements with South Korean skincare manufacturers bypass commodity exchanges and capture margin pools. |
| CO2 Supercritical Capacity Expansion | Pharmaceutical-grade extraction infrastructure meets EMA quality standards and compresses viable supplier competition. |
Methodological Framework
Desk research of customs trade databases, ECHA REACH registration filings, and NMPA export certification records preceded structured interviews with CO2 extraction equipment manufacturers, cosmetic formulation scientists at German contract manufacturers, Ningxia berry processing plant managers, and Mongolian orchard cooperative directors. Primary fieldwork validated secondary data on capacity utilization, certification timelines, and procurement contract structures. Bottom-up triangulation across processor output estimates and top-down demand calibration from end-use consumption patterns anchored value projections.
Variance decomposition across extraction method, certification tier, and end-use application shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include product format, application channel, and geographic regulatory cluster. CAGRs derived from installed capacity expansion trajectories, substitution elasticity estimates for synthetic emollients, and pharmacopeia adoption probability weightings. Industry-specific forecast inputs incorporated EFSA novel food approval timelines and K-beauty formulation substitution rates.
Forecasts assume regulatory continuity in EU REACH substance registration, EFSA novel food frameworks, and China's NMPA processing standards; material policy shifts in residue limits or organic certification requirements would require re-modeling. Recalibration cycles align with material shifts in pharmacopeia monograph adoptions, climate events affecting Ningxia cultivation yields, and South Korean cosmetic ingredient safety assessment updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Frozen Vegetables Market