
 GCC Basmati Rice Market | 2026-2036
GCC Basmati Rice Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Basmati Rice Market Intelligence
Pakistan's rice milling corridor is narrowing its quality variance through modernized sorting and aging infrastructure, tightening export-grade consistency for Gulf-bound shipments. KRBL Limited leverages integrated procurement networks across Punjab and Haryana to sustain volume commitments to Saudi distributors. LT Foods controls premium positioning through proprietary aging protocols and direct retail partnerships across Dubai and Riyadh. Matco Foods anchors mid-tier supply through Karachi-based processing capacity serving wholesale channels in Oman and Bahrain.
Basmati rice denotes a long-grain aromatic variety derived from Oryza sativa, characterized by minimum elongation ratios of 1.8 post-cooking, amylose content between 20-22 percent, and mandatory aging periods of 12-18 months to develop signature fragrance and non-sticky texture. The grain serves as a staple carbohydrate across South Asian diaspora communities and high-end hospitality operations throughout the Arabian Peninsula, where texture integrity and aroma intensity command price premiums. Traditional Basmati occupies the dominant value pool among product type segments, though organic certification is capturing faster volume growth as Saudi retailers impose stricter sourcing transparency requirements. Supermarkets and hypermarkets control the primary distribution channel, with online retailers gaining traction among expatriate households seeking direct-to-door delivery of specific regional brands.
Gulf Standardization Organization frameworks and Saudi Food and Drug Authority regulations enforce maximum pesticide residue limits and mandatory country-of-origin labeling on all packaged rice imports. The UAE's Ministry of Climate Change and Environment coordinates with Emirates Authority for Standardization and Metrology to conduct port-of-entry testing for aflatoxin and heavy metal contamination, rejecting non-compliant batches outright. Stakeholders must monitor evolving halal certification harmonization across GCC customs unions and pre-position laboratory partnerships near Jeddah and Jebel Ali to preempt border delays.
Market Dynamics
Gulf food safety authorities have tightened pesticide residue thresholds and origin-verification protocols, compelling exporters to upgrade laboratory testing and blockchain traceability systems. This regulatory compression is reshaping procurement relationships and processing investments across the value chain.
Growth Catalysts
- SFDA residue mandates:Saudi Food and Drug Authority enforcement of maximum pesticide limits is accelerating laboratory partnerships near Jeddah, creating compliance-service demand.
- Hypermarket consolidation:Saudi Arabia's central corridor retail chains are absorbing larger volume commitments around specific aging specifications and amylose content standards.
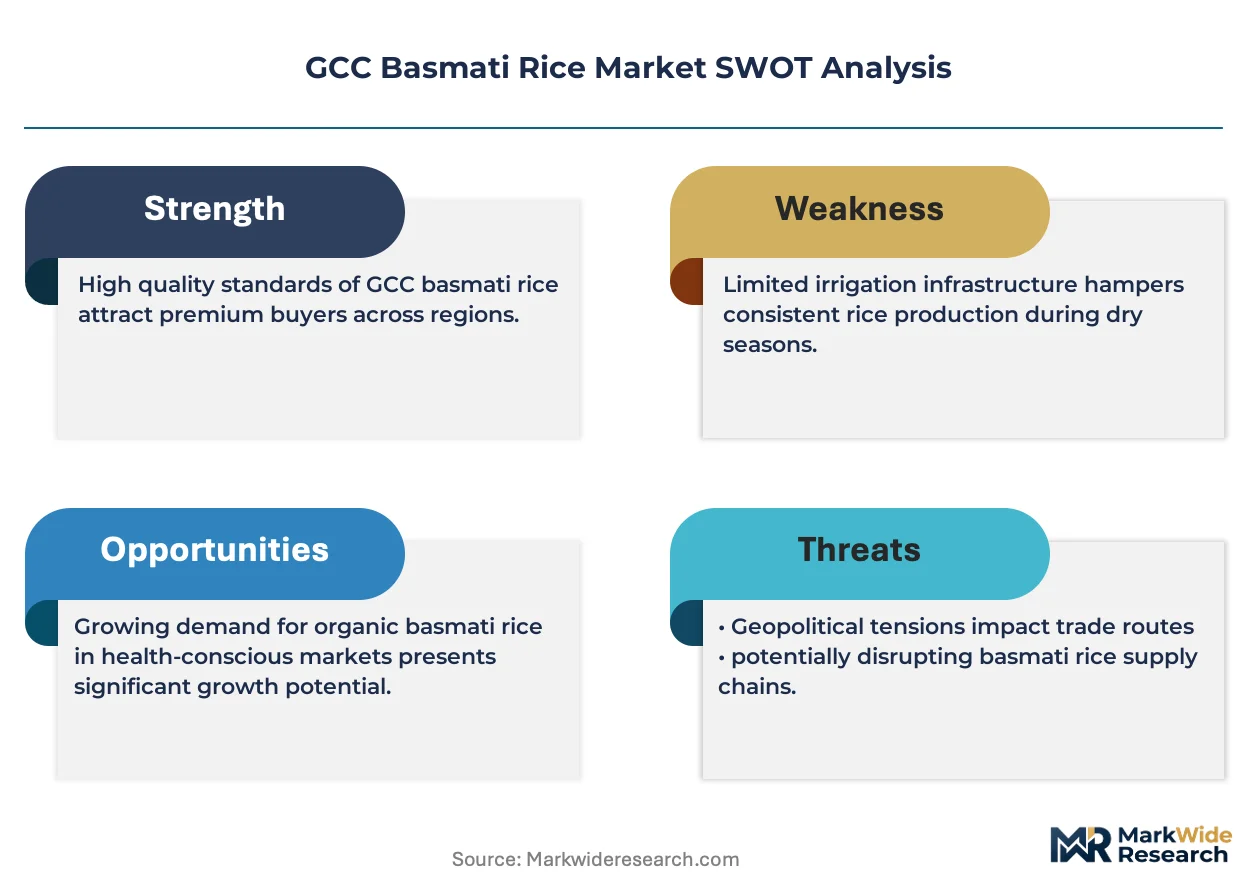
- Blockchain traceability:Origin-verification protocols are hybridizing with port-of-entry testing systems, reducing border delays for certified shipments.
Market Restraints
- Input cost volatility:Irrigation water scarcity in Punjab and Haryana is compressing milling margins and export-grade consistency.
- Supply concentration risk:Karachi-based processing capacity anchors mid-tier supply, creating single-point vulnerability for Oman and Bahrain wholesale channels.
- Technical limitation:Aflatoxin and heavy metal contamination detection at UAE port-of-entry rejects non-compliant batches outright, destroying inventory value.
Strategic Opportunities
- Organic certification tailwind:Saudi retailers are imposing stricter sourcing transparency requirements, capturing faster volume growth in premium positioning.
- Direct-to-door channel innovation:Online retailers are gaining traction among UAE expatriate households seeking specific regional brands.
- Hospitality application expansion:High-end hospitality operations throughout the Arabian Peninsula command price premiums for texture integrity and aroma intensity.
Industry Challenges
- Halal certification harmonization:Evolving GCC customs union requirements demand pre-positioned laboratory partnerships to preempt border delays.
- Capex intensity:Modernized sorting and aging infrastructure requires substantial capital deployment to narrow quality variance for Gulf-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Basmati Rice Market |
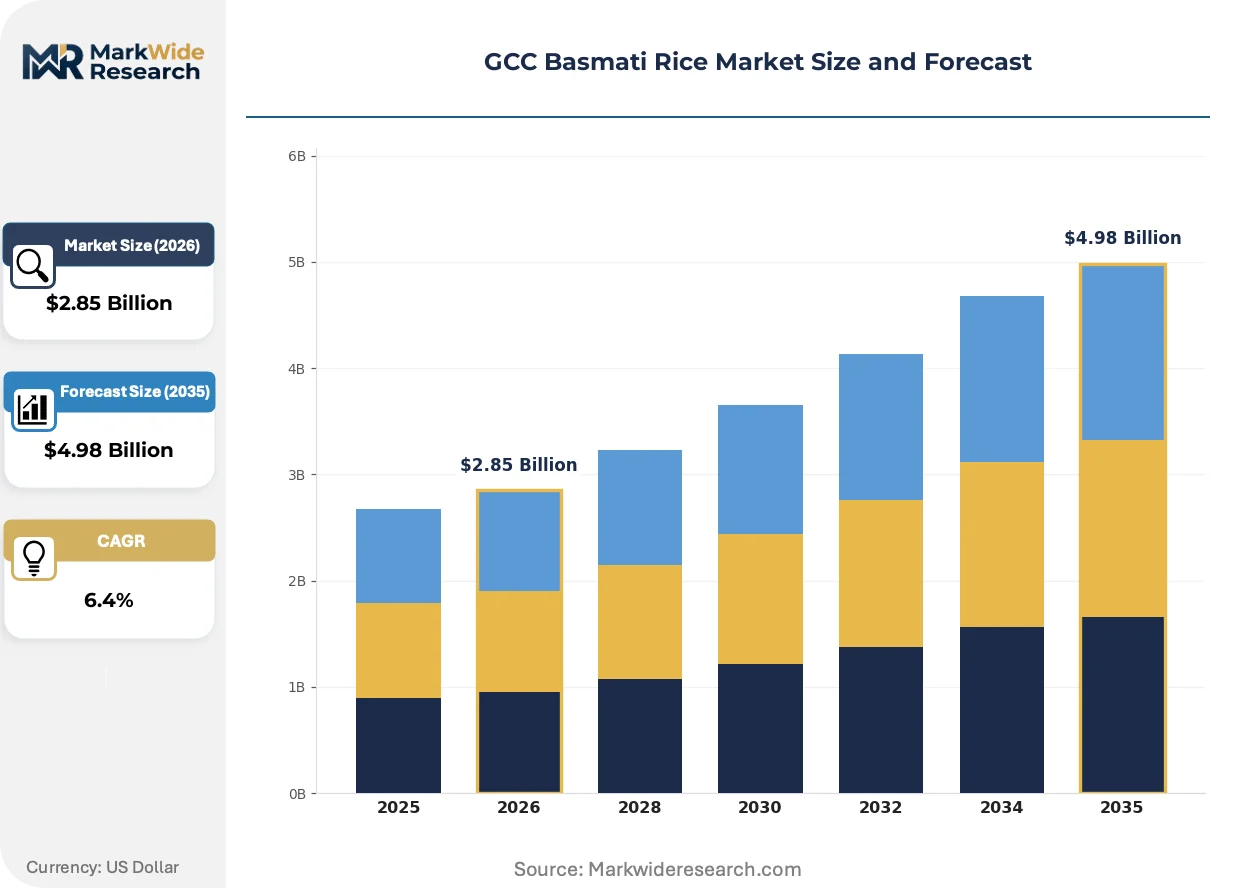
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Basmati, Organic Basmati, Parboiled Basmati, Instant Basmati Packaging Type: Bags, Boxes, Bulk, Sachets Distribution Channel: Supermarkets, Online Retailers, Wholesale, Specialty Stores End User: Households, Restaurants, Food Service, Exporters |
| Companies Covered | ITC Limited, Shri Lal Mahal Group, KRBL Limited, Amar Singh Chawal Wala, Amira Nature Foods, LT Foods, Kohinoor Foods, Matco Foods, Adani Wilmar Ltd, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Basmati Rice Market Strategic Shifts & Innovations
Processing technology and regulatory enforcement are converging to reshape competitive positioning across the GCC rice trade. Three developments are actively restructuring how value is captured and defended.
Near-infrared spectroscopy is hybridizing with automated color-sorting systems to verify amylose content and aging compliance at line speed. Saudi hypermarket chains are adopting these systems for inbound quality assurance, compressing the window for non-compliant shipments to reach retail shelves.
Emirates Authority for Standardization and Metrology coordination with the UAE Ministry of Climate Change and Environment is tightening port-of-entry testing protocols for aflatoxin and heavy metal contamination. This enforcement is diverting non-compliant batches to secondary markets, raising effective compliance costs for Pakistan-based exporters serving Dubai and Abu Dhabi.
Expatriate household purchasing is fragmenting across direct-to-door delivery platforms that bypass traditional wholesale channels. This channel disintermediation is most visible in Dubai and Riyadh, where South Asian diaspora communities are consolidating purchases around specific regional brands with verified origin documentation.
GCC Basmati Rice Market Segmentation
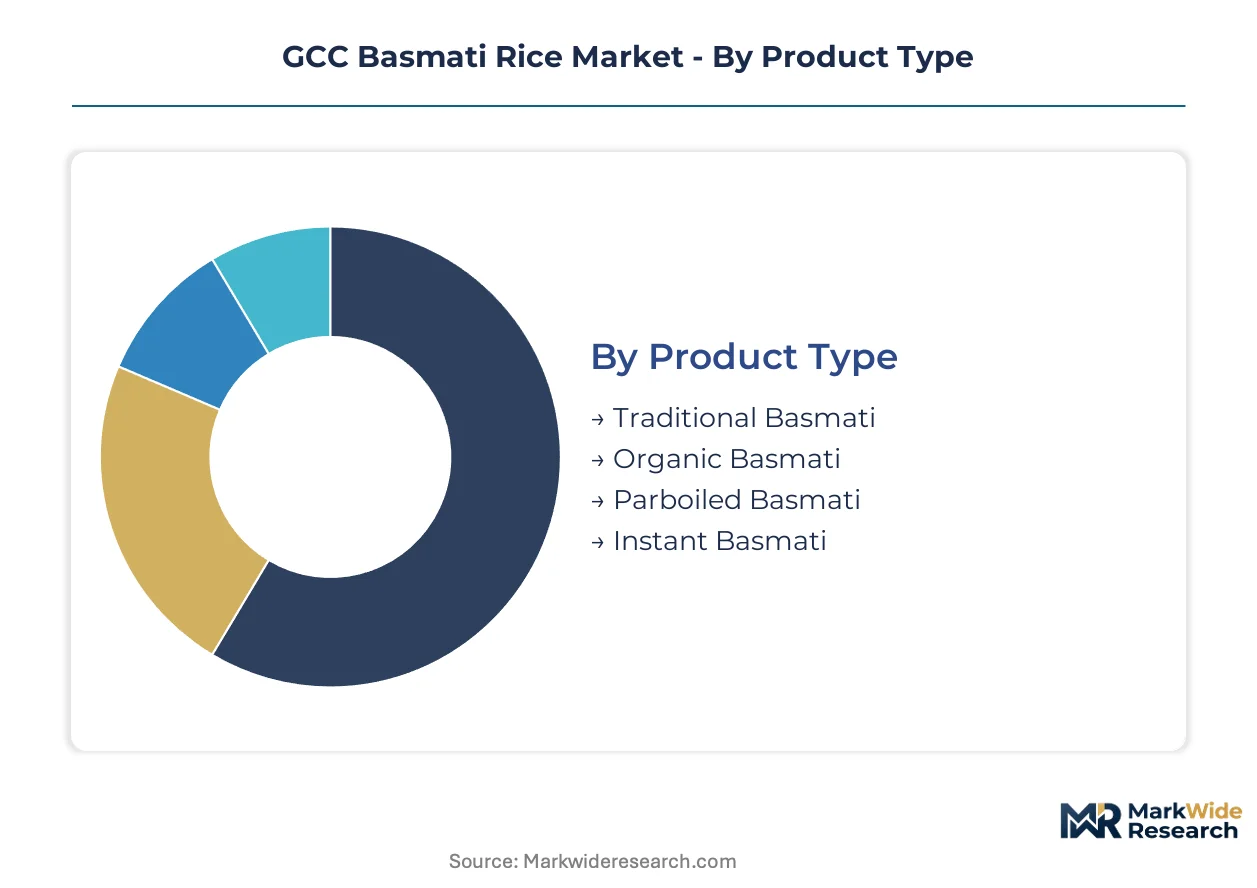
Segmentation in the GCC Basmati rice trade reflects divergent compliance burdens and channel economics. Grain specification, packaging format, and route-to-market each impose distinct capital requirements and margin structures on suppliers serving Saudi and UAE buyers.
Product Type:
Mature varieties dominate volume commitments while emerging formats capture regulatory tailwinds and convenience premiums.
- Traditional Basmati:Long-grain aromatic rice aged 12-18 months with 20-22% amylose content and minimum 1.8 elongation ratio post-cooking. Saudi hypermarket chains consolidate procurement around specific aging specifications, with SFDA residue mandates compressing the supplier base to laboratory-certified exporters.
- Organic Basmati:Certified grains produced without synthetic pesticides or fertilizers, subject to blockchain traceability protocols for origin verification. Saudi retailers impose stricter sourcing transparency requirements, accelerating volume shifts toward certified supply chains.
- Parboiled Basmati:Partially boiled grains with gelatinized starch and firmer texture, favored by institutional food service operations across the UAE for extended holding properties.
- Instant Basmati:Pre-cooked and dehydrated grains targeting convenience-oriented expatriate households in Dubai and Riyadh seeking reduced preparation time.
Traditional Basmati handles the majority of throughput; Organic Basmati is expanding most quickly on share.
Packaging Type:
Cost tier stratification separates premium retail formats from bulk procurement systems serving institutional buyers.
- Bags:Woven polypropylene or laminated paper sacks in 5kg, 10kg, and 25kg denominations, the standard format for Saudi hypermarket shelves and household pantry stocking.
- Boxes:Rigid cardboard containers with tamper-evident seals and origin labeling, commanding shelf space in UAE premium retail channels with enhanced brand visibility.
- Bulk:Loose grain shipments in containerized quantities for Omani and Bahraini wholesale distributors and large-scale hospitality operations.
- Sachets:Single-serve portion packs targeting food service portion control and airline catering contracts across the Gulf.
Bags absorb the dominant procurement volume; Boxes are climbing the fastest as retail branding investments intensify.
Distribution Channel:
Customer type fragmentation is restructuring route-to-market economics, with direct-to-door platforms disintermediating traditional wholesale layers.
- Supermarkets:Brick-and-mortar retail chains across Saudi Arabia's central corridor consolidating volume around long-grain aromatic varieties with verified amylose content.
- Online Retailers:Direct-to-door delivery platforms gaining traction among UAE expatriate households seeking specific regional brands with verified origin documentation.
- Wholesale:Karachi-based processing capacity anchors mid-tier supply for Omani and Bahraini distribution networks.
- Specialty Stores:Ethnic grocery outlets serving South Asian diaspora communities in Dubai and Riyadh with curated regional brand selections.
Supermarkets control the primary volume channel; Online Retailers are gaining share fastest through platform disintermediation.
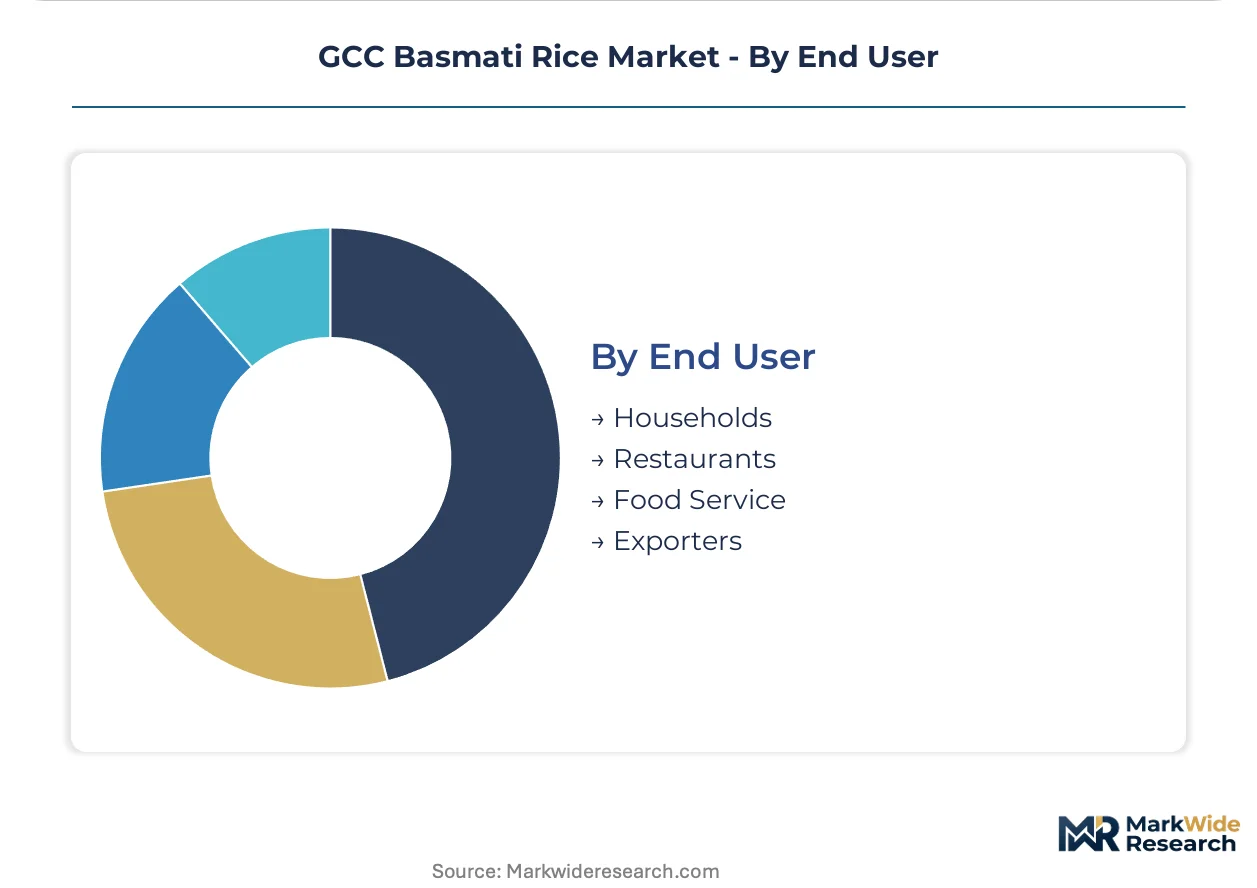
End User:
Application-driven specification divergence separates household aroma preferences from institutional texture requirements.
- Households:Consumer units prioritizing fragrance intensity and cooking elongation, with Saudi families showing preference for aged grains and specific regional provenance.
- Restaurants:Independent and chain dining operations throughout the Arabian Peninsula commanding price premiums for texture integrity in biryani and pilaf applications.
- Food Service:Institutional catering and hospitality operations requiring consistent batch performance and extended holding properties for buffet service.
- Exporters:Re-export traders processing Gulf-bound shipments through Jeddah and Jebel Ali for redistribution to secondary African and Central Asian markets.
Households represent the dominant demand pool; Food Service is the fastest mover on share as hospitality capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA enforcement of pesticide residue limits anchors Saudi Arabia's regulatory framework, reshaping procurement relationships across the Gulf trade corridor. The six GCC states exhibit divergent demand intensities and compliance burdens as food safety authorities tighten origin-verification protocols.
Saudi Arabia
Hypermarket chains across Riyadh and Jeddah consolidate procurement around aged grains with verified amylose content, absorbing larger volume commitments than any other Gulf state. SFDA mandates on maximum residue limits compel exporters to pre-position laboratory partnerships near Jeddah's port facilities. The central corridor between Riyadh and Dammam hosts the densest concentration of institutional buyers specifying 12-18 month aging protocols.
United Arab Emirates
Expatriate households in Dubai and Abu Dhabi drive platform-based purchasing through direct-to-door delivery channels, fragmenting traditional wholesale relationships. Emirates Authority for Standardization and Metrology coordinates with the Ministry of Climate Change and Environment to conduct port-of-entry testing for aflatoxin contamination at Jebel Ali. Dubai's South Asian diaspora communities consolidate purchases around specific regional brands with blockchain-verified origin documentation.
Oman
Wholesale distributors in Muscat and Salalah anchor mid-tier supply absorption, sourcing primarily from Karachi-based processing capacity. The country's national food safety regulator enforces GCC-standard pesticide thresholds with less stringent port-of-entry testing frequency than Saudi or UAE counterparts. The Batinah coastal strip serves as the primary distribution node for re-export to secondary African markets.
Bahrain
Small-format retail and hospitality operations command premium positioning for texture integrity in biryani applications, though absolute volumes trail larger GCC states. The national health regulator aligns with Gulf Standardization Organization frameworks on mandatory country-of-origin labeling. Manama's traditional souk districts maintain curated selections of aged grains targeting South Asian household segments.
Qatar
High-end hospitality operations in Doha command price premiums for aroma intensity as hotel capacity expands ahead of regional event cycles. The national food safety authority enforces halal certification harmonization requirements that demand pre-positioned laboratory partnerships to preempt border delays. Lusail's emerging retail infrastructure attracts branded grain commitments from premium-positioned exporters.
GCC Basmati Rice Market Key Industry Players
Integrated processors and specialized exporters split the market along vertical control axes, with laboratory certification capabilities determining tier placement. The supplier base concentrates around Indian and Pakistani origin points, though UAE-based traders intermediate significant re-export volumes. Three archetypes dominate: Punjab-Haryana integrated millers with captive aging infrastructure, Karachi-based mid-tier processors serving wholesale channels, and Dubai-headquartered trading houses coordinating GCC distribution. Competitive moves center on laboratory partnerships near Jeddah and Jebel Ali, plus blockchain traceability system deployment to satisfy tightening origin-verification protocols.
Among India-based integrated processors, KRBL Limited and LT Foods occupy positions within the premium-tier certification vector, while ITC Limited exemplifies the diversified conglomerate archetype with cross-category food presence. These entities represent contrasting strategic postures: specialized basmati depth versus portfolio breadth, with each anchoring distinct risk-return profiles for Gulf buyers navigating compliance-intensive procurement environments.
| Leading Market Players |
|---|
| ITC Limited |
| Shri Lal Mahal Group |
| KRBL Limited |
| Amar Singh Chawal Wala |
| Amira Nature Foods |
| LT Foods |
| Kohinoor Foods |
| Matco Foods |
| Adani Wilmar Ltd |
| Others |
Cost & Logistics Intelligence
Punjab and Haryana's integrated milling corridor concentrates aging infrastructure and laboratory certification capacity, translating upstream control into pricing power for Gulf-bound shipments. SFDA residue mandates compress the compliant supplier base, allowing certified exporters to command premiums over Karachi-based mid-tier processors serving wholesale channels in Oman and Bahrain.
Pricing Analysis
Price spreads widen between Jeddah-port laboratory-certified shipments and Dubai wholesale lots lacking blockchain traceability documentation. Three-tier pricing structure across premium certified, standard commercial, and economy bulk levels separates aged grains with verified amylose content from parboiled alternatives. Pricing pressure stems from irrigation water scarcity compressing milling margins in Punjab and Haryana. Institutional buyers across Saudi Arabia's central corridor show lowest price sensitivity, prioritizing batch consistency and SFDA compliance over per-unit cost.
Supply Chain Analysis
Karachi-based processors Matco Foods and smaller mid-tier operators hold contract-milling concentration for Oman and Bahrain wholesale absorption. Geographic supply centers on India, Pakistan, and limited UAE re-export trading capacity. Raw material flows draw from Punjab and Haryana paddy procurement networks, with aging infrastructure and laboratory testing equipment as critical processing inputs. Single-source vulnerability concentrates in Karachi-based mid-tier capacity serving Muscat and Salalah distribution nodes. Distribution runs through Saudi hypermarket chains, UAE direct-to-door platforms, and Omani wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. SFDA laboratory certification requirements and blockchain traceability mandates create switching costs that lock in compliant suppliers and lock out uncertified competitors.
For Market Incumbents: Insulate market position by deepening laboratory partnerships near Jeddah and Jebel Ali to preempt border delays from evolving halal certification harmonization. Deploy capital toward captive aging infrastructure in Punjab and Haryana to narrow quality variance and defend margin position against irrigation water scarcity compressing export-grade consistency. Channel control through direct retail partnerships across Riyadh and Dubai hypermarket chains reinforces tier placement. For New Entrants and Emerging Players: Organic certification white space in Saudi premium retail channels represents the most penetrable entry point, with faster volume growth capturing regulatory tailwinds from stricter sourcing transparency requirements. Direct-to-door delivery platform partnerships with UAE expatriate households offer disintermediation leverage around specific regional brands with verified origin documentation. Go-to-market execution should anchor on blockchain traceability system deployment as table stakes for SFDA compliance. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because laboratory certification capabilities and aging infrastructure determine tier placement in a tightening regulatory environment. Acquisition targets should screen for Punjab-Haryana integrated millers with captive procurement networks and existing SFDA laboratory partnerships. The signal to watch is consolidation velocity among Karachi-based mid-tier processors as margin compression from input cost volatility accelerates exit pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Partnership Pre-Positioning | SFDA and Emirates Authority for Standardization and Metrology coordination reduces border delay risk for certified shipments. |
| Blockchain Traceability Deployment | Origin-verification protocols satisfy Saudi retailer transparency mandates and accelerate volume shifts toward certified supply chains. |
| Captive Aging Infrastructure Investment | Punjab and Haryana integrated milling capacity narrows quality variance for Gulf-bound export-grade consistency. |
| Direct-to-Consumer Platform Integration | Online retailer partnerships bypass wholesale layers and capture UAE expatriate household fragmentation. |
| Organic Certification Program | Saudi retailer sourcing requirements capture faster volume growth in premium positioning segments. |
Research Approach
Desk research of customs trade databases, Gulf Standardization Organization regulatory filings, and SFDA enforcement precedents preceded structured interviews with rice milling operations managers, Saudi hypermarket category buyers, UAE food safety laboratory directors, and Karachi-based export trading house procurement leads. Primary fieldwork across Punjab, Haryana, and Karachi processing corridors validated secondary data on aging infrastructure capacity and laboratory certification penetration. Bottom-up volume modeling triangulated against top-down GCC import absorption estimates.
Assumptions held fixed include SFDA residue mandate enforcement intensity, GCC customs union halal certification harmonization trajectory, and irrigation water availability in Punjab and Haryana across the analysis window. Segmentation dimensions modeled encompass product type, packaging format, distribution channel, and end-user application with geographic regulatory cluster overlay. CAGRs derived from trend extrapolation of historical import volumes adjusted for channel shift dynamics and hospitality capacity expansion in Qatar and Saudi Arabia.
Macroeconomic conditions sit as an overlay; deviation in GCC currency peg stability, South Asian monsoon patterns, or global freight rate volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and infrastructure investment continuity. Quarterly review of SFDA laboratory partnership expansion rates and blockchain traceability system deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soy Grits Market
Grains
Europe Maize Market
Grains
00 Flour Market
Grains
Asia-Pacific Rice Market
Grains
GMO Corn Market
Grains
Pulses Market
Grains
United States Maize Market
Grains
China Maize Market
Grains
Durum Wheat Flour Market
Grains
Quinoa Flour Market
Grains
Grain Bins Market
Grains
Tunisia Grain Market
Grains
China Wheat Protein Market
Grains
Heritage Grain Market
Grains
Oat Bran Market
Grains
Global Precooked Corn Flour Market