
 Passover Humidifiers Market | 2026-2036
Passover Humidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Passover Humidifiers Market Analytics
FDA 510(k) premarket notification requirements for heated respiratory humidifiers is shifting the cost-of-entry calculus for Passover-specific device variants. Fisher & Paykel Healthcare Limited leverages its integrated respiratory care platform to sustain manufacturing scale across humidification systems. ResMed anchors its position through specialized sleep and respiratory therapy expertise that extends into seasonal religious use cases. Koninklijke Philips N.V. competes on brand strength and channel control within home healthcare distribution networks.
Passover humidifiers are electrically powered devices that add moisture to ambient air through evaporative, ultrasonic, or steam-based mechanisms, typically operating at output rates between 300-500 mL per hour to maintain relative humidity between 40-60% in enclosed ritual spaces during the week-long observance. Their primary purpose centers on preventing respiratory irritation and preserving vocal cord function during extended Passover seders and communal gatherings in climate-controlled environments. Ultrasonic humidifiers dominate residential deployment due to silent operation and compact form factors suited to home seder tables. Healthcare Facilities represent the fastest-growing end-user channel as hospitals and long-term care centers serving Orthodox populations expand culturally competent respiratory support programs.
FDA oversight of heated humidifiers as Class II medical devices intersects with EPA energy efficiency standards for residential appliances, creating dual compliance obligations for manufacturers targeting both clinical and consumer Passover applications. CE marking under EU MDR and IEC 60601-1 electrical safety standards further constrain design freedom for devices intended for export markets. Stakeholders must monitor evolving synagogue building codes and ventilation mandates that could either expand installation requirements or restrict portable unit deployment in communal worship spaces.
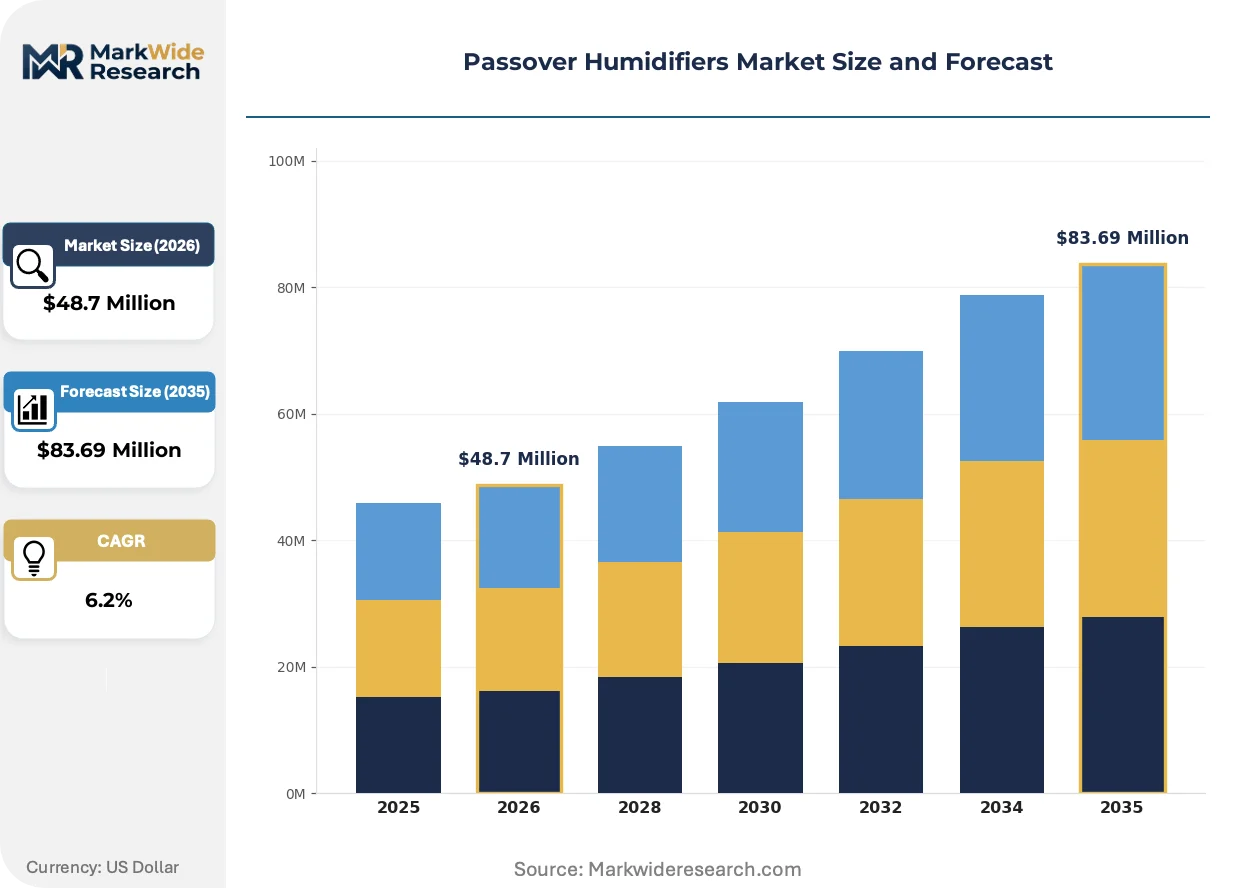
Market Dynamics
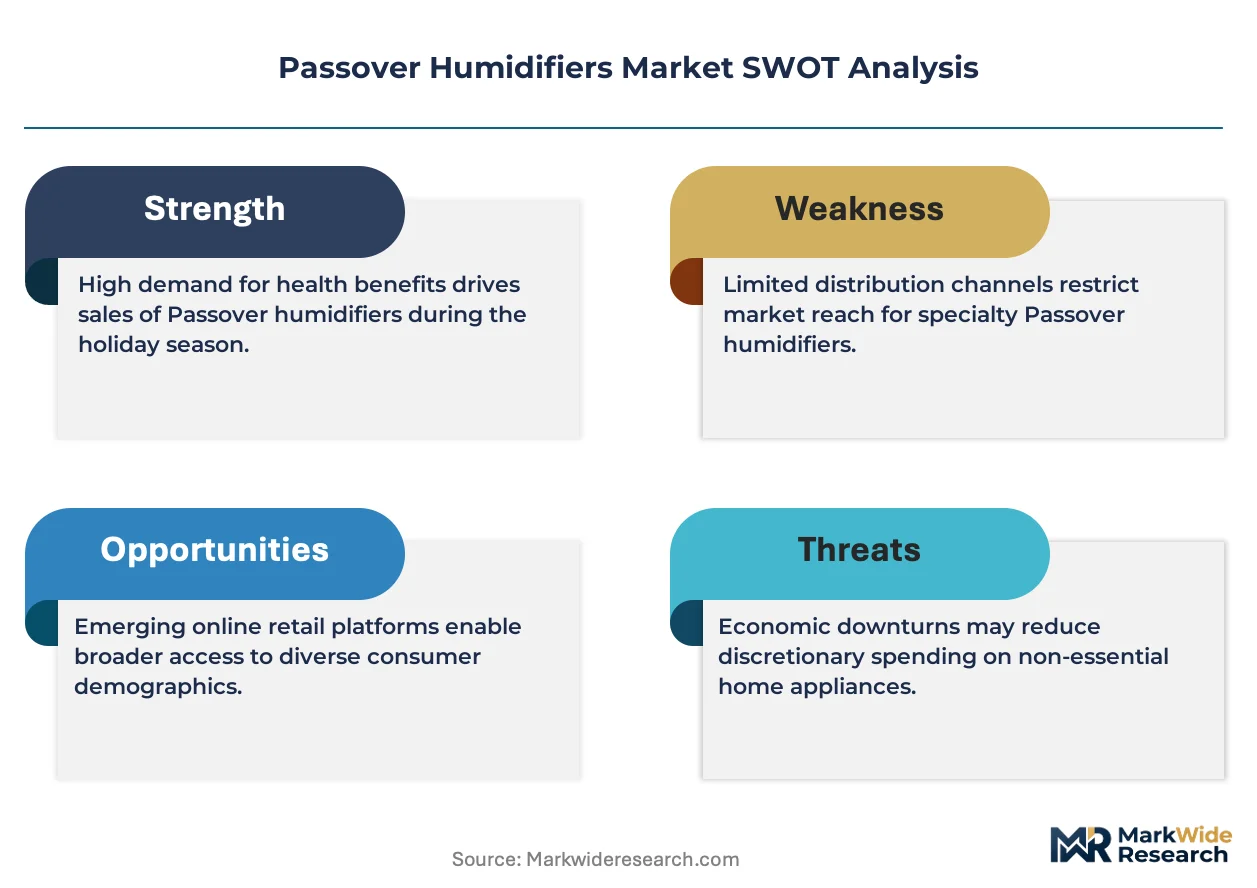
FDA 510(k) premarket notification requirements for heated respiratory humidifiers are compressing the competitive field by elevating compliance costs for Passover-specific device variants. Synagogue congregations and healthcare facilities serving Orthodox populations now demand dual-certified units that satisfy both clinical standards and ritual use cases.
Growth Catalysts
- Healthcare Facilities channel:Hospitals and long-term care centers serving Orthodox Jewish populations are expanding culturally competent respiratory support programs that incorporate Passover humidification protocols.
- FDA Class II device classification:Elevated compliance thresholds are filtering out marginal competitors and concentrating market share among established respiratory equipment manufacturers with existing 510(k) clearances.
- Ultrasonic technology adoption:Silent operation and compact form factors are accelerating residential deployment across home seder tables where noise disruption would interrupt ritual observance.
Market Restraints
- Dual compliance burden:Intersection of FDA medical device rules with EPA energy efficiency standards creates overlapping certification costs that constrain product development budgets.
- Seasonal demand concentration:Seven-day annual observance window compresses revenue recognition and forces manufacturers to absorb year-round carrying costs for single-peak inventory cycles.
- Input cost volatility:Piezoelectric transducers and medical-grade plastics face supply instability from concentrated Asian component suppliers, pressuring unit economics.
Strategic Opportunities
- CE marking expansion:EU MDR compliance pathway opens access to European Orthodox communities in London, Antwerp, and Paris with underserved ritual equipment needs.
- Smart humidity sensing convergence:Integration of IoT-enabled environmental monitors with ultrasonic bases creates premium positioning for tech-forward synagogue installations.
- Healthcare channel penetration:Pulmonology practices and respiratory therapy clinics represent underdeveloped prescription-driven distribution for clinical-grade Passover units.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise at the intersection of respiratory therapy equipment and religious observance requirements remains concentrated among a limited pool of regulatory affairs professionals.
- Legacy HVAC integration complexity:Portable humidifier deployment in older synagogue buildings with fixed ventilation infrastructure requires custom installation protocols that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passover Humidifiers Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative Humidifiers, Ultrasonic Humidifiers, Steam Vaporizers, Impeller Humidifiers End User: Residential Users, Commercial Spaces, Healthcare Facilities, Educational Institutions Distribution Channel: Online Retailers, Specialty Stores, Convenience Stores, Wholesale Distributors Application: Home Use, Office Use, Medical Use, Industrial Use |
| Companies Covered | Fisher & Paykel Healthcare Limited, ResMed, Koninklijke Philips N.V., Teleflex Incorporated, Hamilton Medical, Vapotherm, Precision Medical, Inc., CAREL INDUSTRIES S.p.A., Drive DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passover Humidifiers Market Evolving Landscape
Smart environmental control systems are penetrating ritual spaces as congregations invest in automated climate management. Three distinct vectors are reshaping product development priorities and buyer expectations across the Passover humidifier segment.
Ultrasonic transducer arrays with embedded humidity sensors are integrating real-time environmental feedback loops that adjust output rates based on occupancy detection. Synagogue facilities managers in Brooklyn and Monsey are piloting these networked systems ahead of peak season. The technology is integrating building automation protocols that compress manual intervention requirements during extended seder services.
EPA Energy Star certification requirements for residential appliances are tightening test procedures for evaporative and steam-based units. Manufacturers must now submit verified standby power consumption data that disqualifies legacy heating element designs. Passover humidifier lines targeting consumer channels are responding by redesigning thermal cores to meet the revised 2026 efficiency thresholds.
Institutional procurement officers at hospital systems are consolidating vendor relationships through multi-year respiratory equipment contracts that bundle Passover humidifiers with standard nebulizer and oxygen concentrator purchases. This channel compression is displacing standalone seasonal orders that previously flowed through religious supply distributors. The pattern is most visible in the New York metropolitan area where major health systems serve concentrated Orthodox populations.
Passover Humidifiers Market Segmentation
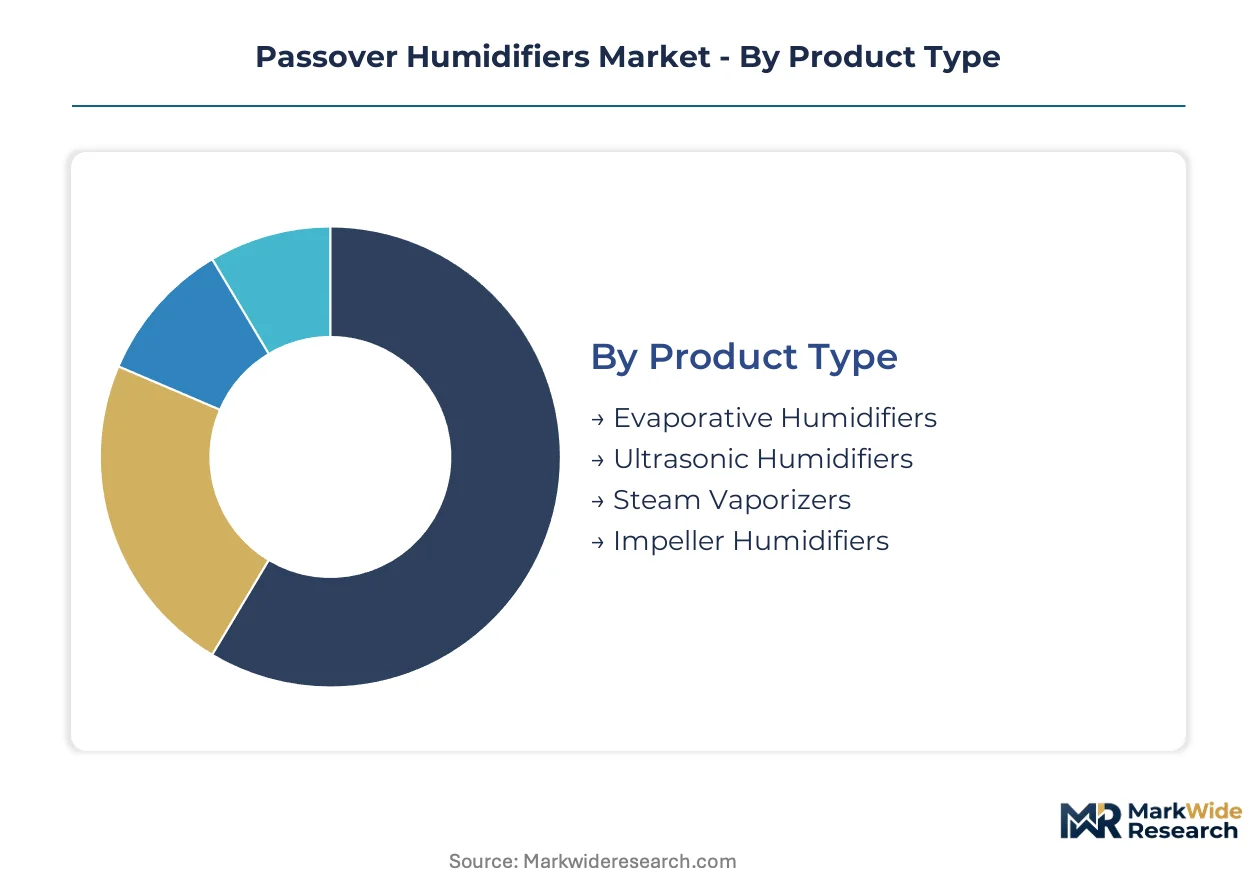
Segmentation reveals how Passover humidifier demand fragments across distinct technical specifications, procurement channels, and institutional contexts. Buyers prioritize silent operation for residential seders, clinical certification for healthcare facilities, and building automation compatibility for synagogue installations.
Product Type:
Integration depth separates portable tabletop units from permanently installed humidification systems within ritual spaces.
- Ultrasonic Humidifiers:Piezoelectric transducers generate micro-fine mist through high-frequency vibration without heating elements, enabling silent operation at 300-500 mL/hr output. Brooklyn and Monsey synagogue facilities managers are piloting networked arrays with embedded humidity sensors ahead of peak season. Demand concentrates in residential seder tables where noise disruption would interrupt ritual observance.
- Evaporative Humidifiers:Wick-based systems draw water through porous media while fans force air across saturated surfaces, producing cool mist through passive evaporation. These units dominate older synagogue buildings with fixed HVAC infrastructure where electrical load constraints limit heating element deployment. Volume placements concentrate in cost-sensitive congregational procurement.
- Steam Vaporizers:Boiling-water systems with medical-grade thermal cores.
- Impeller Humidifiers:Rotating disk mechanisms flinging water against diffuser screens.
Volume placements concentrate in Ultrasonic Humidifiers; the faster expansion belongs to Evaporative Humidifiers as building automation integration accelerates.
End User:
Procurement authority distinguishes individual household decisions from institutional purchasing committees with multi-year capital planning cycles.
- Healthcare Facilities:Hospitals and long-term care centers serving Orthodox populations are expanding culturally competent respiratory support programs. These institutions demand dual-certified units satisfying FDA 510(k) requirements for heated respiratory humidifiers alongside ritual use specifications. New York metropolitan area health systems bundle Passover humidifiers with nebulizer and oxygen concentrator contracts.
- Residential Users:Individual households purchase compact units for single-family seders through online retailers and specialty Judaica distributors. Brooklyn's Crown Heights and Borough Park neighborhoods generate concentrated seasonal demand as extended families host multi-generational gatherings. Price sensitivity drives ultrasonic technology preference over steam-based alternatives.
- Commercial Spaces:Synagogue sanctuaries and community centers with centralized climate control.
- Educational Institutions:Yeshiva dormitories and day school multipurpose rooms requiring durable construction.
Procurement volume clusters in Residential Users; Healthcare Facilities are climbing the fastest as institutional respiratory programs expand.
Distribution Channel:
Channel selection reflects buyer urgency, technical support requirements, and certification documentation needs.
- Online Retailers:E-commerce platforms enable rapid seasonal procurement with comparative specification review. Residential buyers in Orthodox communities across New York and New Jersey leverage two-day delivery windows for last-minute seder preparation. Return policies and warranty registration simplify post-holiday storage decisions.
- Specialty Stores:Judaica retailers and medical equipment dealers provide hands-on demonstration and rabbinical certification consultation. These channels capture synagogue board members seeking installation guidance for permanent sanctuary deployments. Staff expertise on humidity output rates and ritual space dimensions differentiates against mass-market alternatives.
- Wholesale Distributors:Bulk procurement intermediaries serving hospital systems and synagogue networks.
- Convenience Stores:Limited seasonal stocking for emergency replacement purchases.
Transaction volume flows through Online Retailers; Specialty Stores are gaining share fastest as institutional buyers prioritize technical consultation.
Application:
Use case severity determines regulatory exposure, from unregulated residential comfort to FDA-scrutinized clinical respiratory therapy.
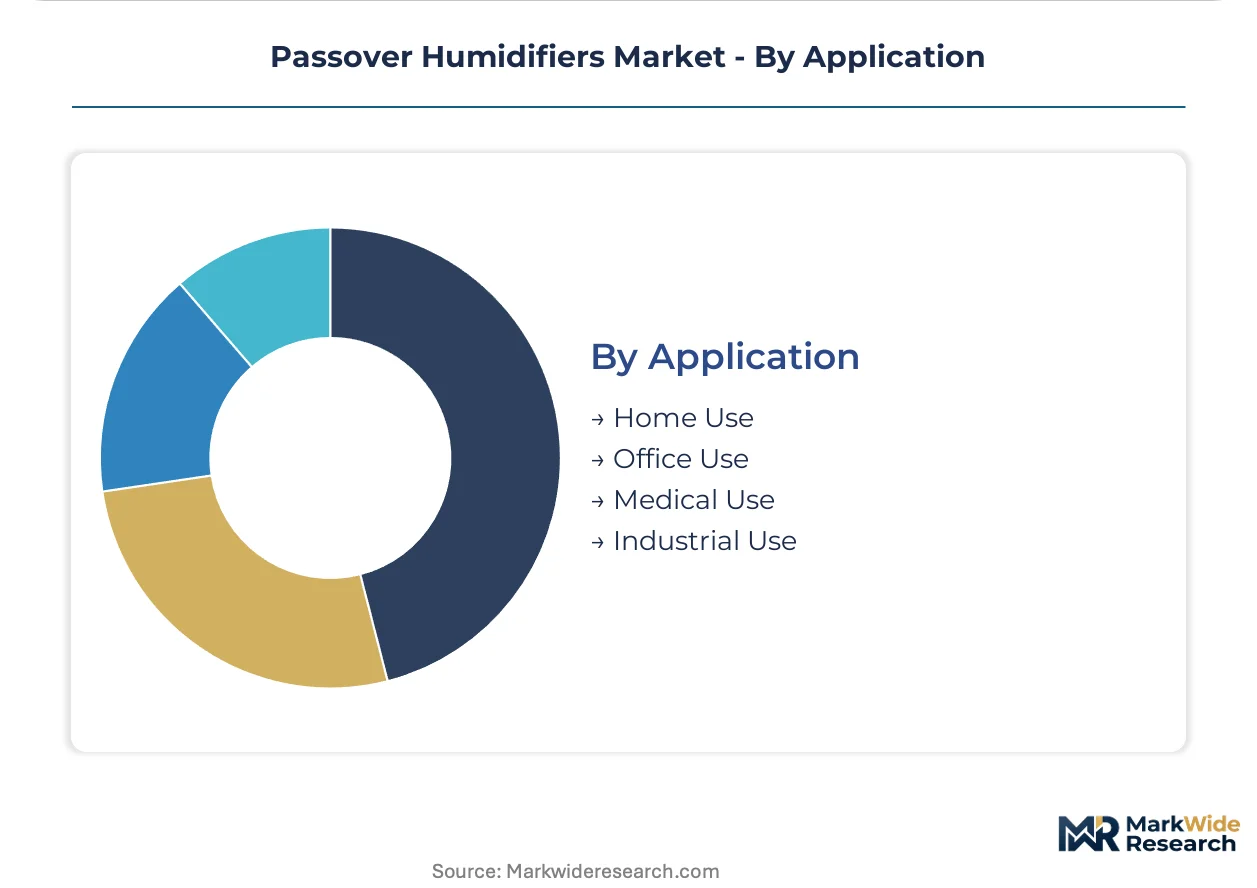
- Home Use:Residential seder tables and bedroom humidification for overnight guests operate outside medical device classification. Compact ultrasonic units with 1-2 gallon tank capacity dominate this segment. Brooklyn and Monsey households prioritize silent operation and automatic shutoff safety features.
- Medical Use:Hospital pulmonary wards and long-term care respiratory therapy programs require heated humidifiers meeting FDA Class II device standards. These applications intersect with EPA energy efficiency standards for residential appliances, creating dual compliance obligations. Institutional procurement officers consolidate vendor relationships through multi-year equipment contracts.
- Office Use:Workplace wellness programs and co-working spaces with Jewish employee populations.
- Industrial Use:Manufacturing facilities with precision humidity requirements for sensitive materials.
Deployment volume concentrates in Home Use; Medical Use shows the steepest expansion trajectory as healthcare facilities develop culturally competent protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodox Jewish communities in the United States generate the dominant share of Passover humidifier procurement, with concentrated demand clusters in Brooklyn, Monsey, and Lakewood driving seasonal volume spikes each spring.
United States
FDA 510(k) premarket notification requirements for heated respiratory humidifiers filter marginal competitors from the Passover-specific device market. EPA Energy Star certification thresholds for residential appliances create dual compliance obligations for manufacturers targeting both clinical and consumer applications. Brooklyn's Crown Heights and Borough Park neighborhoods generate concentrated ultrasonic humidifier demand as extended families host multi-generational seders requiring silent operation.
Israel
Domestic production of ritual equipment serves local Orthodox congregations and exports to diaspora communities in Europe and North America. The Ministry of Health regulates medical-grade humidification devices under pharmaceutical equipment standards that intersect with religious import requirements. Jerusalem and Bnei Brak manufacturing clusters specialize in compact ultrasonic units designed for apartment-scale seders with strict noise limitations.
United Kingdom
London's Stamford Hill and Golders Green Orthodox communities sustain year-round specialty retailers that expand inventory for Passover seasonal demand. MHRA medical device regulations align with EU MDR transition timelines, creating compliance complexity for imported respiratory humidifiers. Manchester's Prestwich neighborhood represents a secondary demand cluster where synagogue facilities managers pilot smart humidity sensing systems ahead of peak season.
Belgium
Antwerp's diamond district adjacent Orthodox population maintains distinctive procurement patterns through Dutch-speaking and Yiddish-speaking distribution channels. FAMHP medical device oversight applies EU MDR classification rules that elevate documentation requirements for heated humidifier variants. Local importers specialize in dual-certified units satisfying both clinical standards and rabbinical supervision requirements for ritual use.
Canada
Toronto's Thornhill and Montreal's Outremont neighborhoods concentrate Canadian Passover humidifier demand within dense Orthodox residential corridors. Health Canada medical device licensing requirements for respiratory humidification equipment parallel FDA Class II standards, easing cross-border product certification for US manufacturers. Vancouver's smaller Orthodox community relies on e-commerce fulfillment from Seattle distribution centers during compressed seasonal windows.
Passover Humidifiers Market Competitive Landscape
North American respiratory equipment manufacturers anchor the premium tier; European climate control specialists hold complementary positions in building-integrated systems. Market structure concentrates among established medical device producers with existing FDA 510(k) clearances, filtering out consumer appliance entrants lacking clinical certification infrastructure. Three archetypes dominate: integrated respiratory care platforms, specialized humidification technology developers, and diversified home healthcare conglomerates. Competitive moves center on multi-year institutional procurement contracts and CE marking expansion into European Orthodox communities.
Within the integrated respiratory care tier, Fisher & Paykel Healthcare Limited and ResMed exemplify manufacturers leveraging sleep therapy expertise into seasonal religious applications. Koninklijke Philips N.V. occupies a position bridging home healthcare distribution networks with clinical certification depth. These three companies represent the dominant competitive anchors, each sitting within distinct strategic postures—manufacturing scale, specialized therapy focus, and channel control respectively.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare Limited |
| ResMed |
| Koninklijke Philips N.V. |
| Teleflex Incorporated |
| Hamilton Medical |
| Vapotherm |
| Precision Medical, Inc. |
| CAREL INDUSTRIES S.p.A. |
| Drive DeVilbiss Healthcare |
| Others |
Value Network & Pricing Analysis
Ultrasonic transducer miniaturization is compressing unit production costs while simultaneously concentrating manufacturing expertise among Asian component specialists. This dual effect tightens margins for final assemblers in North America and Europe even as retail prices face downward pressure from commoditized consumer-grade units.
Pricing Analysis
Volume concentrates in economy-grade ultrasonic units for residential seders, while margins concentrate in FDA-cleared clinical variants for healthcare procurement. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the consumer tier is intensifying because EPA Energy Star compliance adds redesign overhead. Synagogue procurement committees show lowest price sensitivity; individual households in Brooklyn's Crown Heights exhibit highest.
Supply Chain Analysis
Piezoelectric transducer supply rests on Japanese and Chinese specialty ceramics producers with limited alternative sourcing. Medical-grade ABS housings draw from German and South Korean polymer compounders. Single-source vulnerability in MEMS humidity sensors creates procurement risk for smart-enabled product lines. Distribution runs through medical equipment GPOs for institutional buyers and Judaica specialty retailers for congregational procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passover humidifier supply is tightening around FDA 510(k) clearance capacity, which props pricing power for incumbent respiratory equipment manufacturers while filtering marginal competitors from clinical channels.
For Market Incumbents: Deepen backward integration into piezoelectric transducer supply through captive sourcing agreements with Japanese ceramics specialists. Expand 510(k) clearance portfolios to cover heated ultrasonic variants before emerging entrants secure predicate device pathways. This defends against white-label competitors from consumer appliance sectors. For New Entrants and Emerging Players: Small-scale yeshiva dormitory operators represent an underserved buyer archetype with unconsolidated procurement and limited technical specification demands. Target this segment through direct e-commerce fulfillment with simplified ultrasonic units lacking clinical certification. This avoids head-to-head competition with entrenched hospital system vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified home healthcare conglomerates seeking seasonal product line extensions. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch FDA 510(k) submission backlogs as the inflection signal—clearance delays compress valuation multiples for pre-revenue entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Expansion | Unlocks hospital procurement channels serving Orthodox populations in New York and New Jersey. |
| CE Marking Pathway Completion | Opens European Orthodox communities in London and Antwerp currently underserved by certified suppliers. |
| Smart Sensor Integration | Positions premium units for synagogue building automation upgrades in Brooklyn and Monsey. |
| Healthcare GPO Contracting | Bundles Passover humidifiers with nebulizer purchases across New York metropolitan health systems. |
| Specialty Retail Partnership | Secures rabbinical certification consultation channels for congregational procurement committees. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EPA Energy Star certification records, and hospital GPO contract filings, complemented by interviews with respiratory therapy equipment procurement managers, synagogue facilities directors in Brooklyn and Monsey, Judaica specialty retailers, and biomedical engineering consultants. Secondary sources included customs import data for piezoelectric components, SEC 10-K filings from listed respiratory equipment manufacturers, and building automation protocol documentation. Bottom-up unit shipment estimates were triangulated against top-down revenue aggregation across distribution channels.
Historical shipment patterns were cross-referenced against panel input from procurement officers at five hospital systems serving Orthodox populations. The analytical framework modeled demand across product type, end user, distribution channel, and application dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation with aggregate market value constraints. Industry-specific inputs included seasonal inventory cycle compression effects and dual compliance cost burdens for FDA-EPA intersecting requirements.
Revisions become necessary when FDA classification rules shift for heated humidifiers, EPA Energy Star test procedures tighten, or synagogue building codes mandate fixed HVAC integration over portable deployment. A small set of named triggers—regulatory reclassification, component supply disruption, and institutional procurement consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
Soft Starter Market