
 US Vegetable Oil Market | 2026-2036
US Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
US Vegetable Oil Market Insights
Midwest crush capacity expansion is tilting the domestic supply balance toward higher-oleic soybean varieties. Cargill Incorporated leverages its river-based logistics network to anchor origination throughput across Illinois and Iowa processing hubs. Archer Daniels Midland Company sustains multi-oil refining complexity at its Decatur complex, competing on scale in both food-grade and industrial channels. Bunge Limited differentiates through backward integration into farmer origination, controlling elevator receipts across the Corn Belt.
Vegetable oil comprises triglycerides extracted from oilseed crops through mechanical pressing or solvent extraction, typically refined to achieve smoke points above 230°C for frying stability and oxidative resistance for shelf life. Its primary commercial purpose spans food manufacturing, where it provides texture, heat transfer, and flavor carrier functions in processed products. Soybean oil leads volume due to embedded crush economics, while canola oil captures premium positioning in retail and foodservice channels with lower saturated fat profiles. Industrial applications, including renewable diesel and oleochemical feedstocks, represent the fastest-expanding demand pool as biofuel mandates tighten. Supermarkets and wholesale channels distribute the bulk of food-grade volume, though online retail is gaining traction in specialty and organic segments.
The FDA governs nutritional labeling and trans fat declarations, the USDA administers commodity programs and biofuel policy, and the EPA sets renewable fuel standards that redirect soybean oil toward diesel refiners. These frameworks collectively shape crush margins, product specifications, and channel access across the value chain. Stakeholders must monitor RFS obligation pathways and state-level low-carbon fuel standards to anticipate feedstock competition between food and fuel end uses.
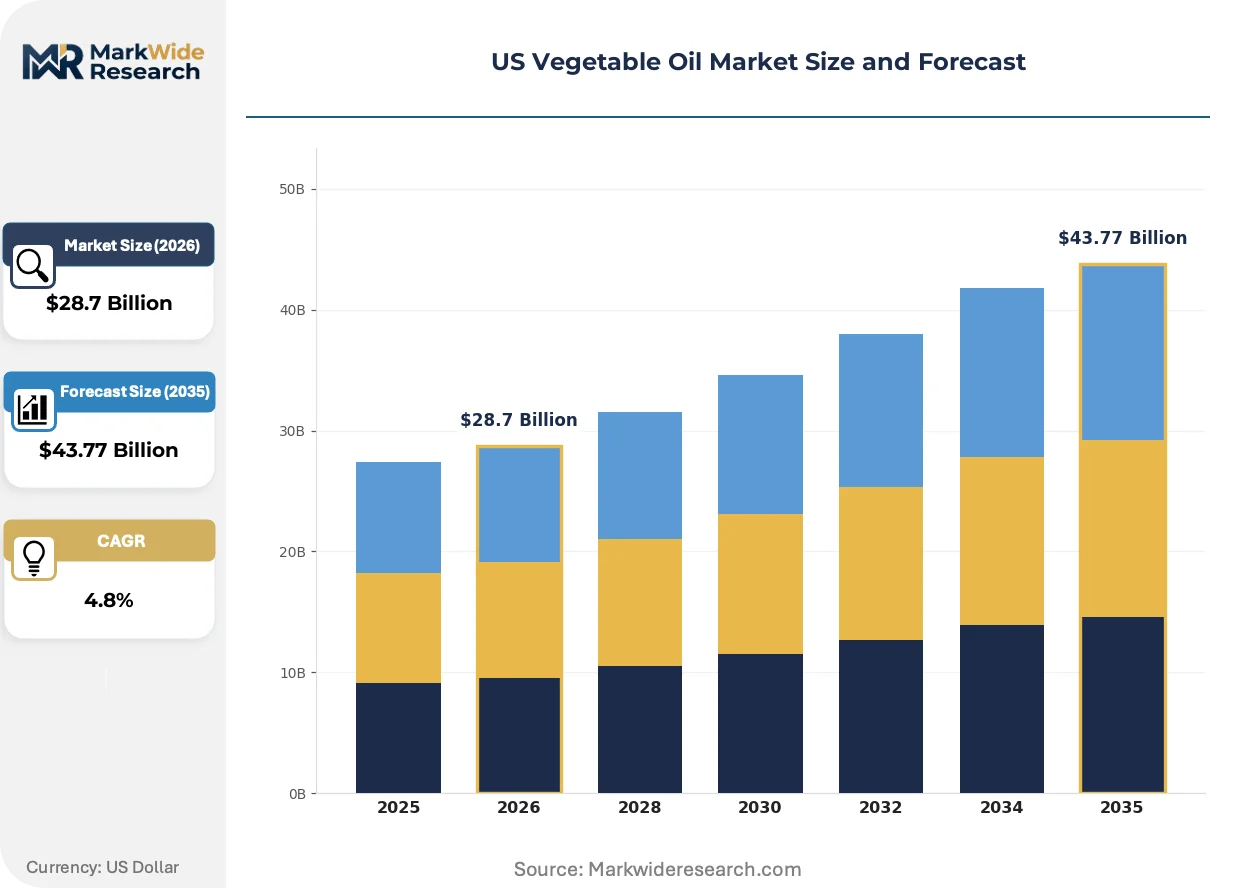
Market Dynamics
The US vegetable oil market is undergoing structural recalibration as the EPA's renewable fuel standards redirect soybean crush capacity toward renewable diesel feedstocks, tightening food-grade supply and compressing margins for traditional refining operations.
Growth Catalysts
- USDA Biofuel Mandates:Federal renewable volume obligations expand demand for soybean oil as a diesel feedstock, pulling additional crush capacity into industrial channels and supporting price floors across the commodity complex.
- Clean-Label Reformulation:Food manufacturers are eliminating partially hydrogenated oils to meet FDA trans fat labeling requirements, accelerating absorption of higher-oleic soybean and canola varieties with improved oxidative stability.
- Midwest Processing Clusters:River-adjacent crush facilities in Illinois and Iowa leverage barge logistics to link Corn Belt origination with Gulf Coast export terminals, reducing inland freight spreads and improving origination capture rates.
Market Restraints
- Input Cost Volatility:Soybean futures price swings driven by South American weather patterns transmit directly into crush margins, compressing returns for processors lacking origination hedging infrastructure.
- Regulatory Friction:The FDA's updated nutritional labeling requirements impose reformulation costs on mid-sized food manufacturers without the R&D budgets of national processors, creating compliance asymmetries.
- Substitution Threat:Palm oil imports from Southeast Asia undercut domestic soybean oil pricing in industrial applications where saturated fat profiles are not constrained, displacing volume in oleochemical feedstocks.
Strategic Opportunities
- State Low-Carbon Fuel Standards:California's LCFS and emerging programs in Oregon and Washington create credit premiums for lower-carbon-intensity vegetable oil pathways, rewarding processors with verified supply chain traceability.
- Specialty Oil Channels:Organic and non-GMO segments remain underpenetrated in mainstream retail, offering margin expansion for crushers with identity-preserved handling infrastructure and third-party certification.
- Renewable Diesel Integration:Refinery offtake agreements with renewable diesel producers in Louisiana and Texas provide forward demand visibility, enabling crush capacity investments with contracted revenue floors.
Industry Challenges
- Capex Intensity for Refinery-Grade Processing:Meeting renewable diesel producers' strict free fatty acid and moisture specifications requires solvent extraction upgrades and pretreatment investments that strain mid-tier processor balance sheets.
- Certification Timeline Compression:Non-GMO Project and organic certifications demand 36-month transition periods and audit documentation that delays market entry, disadvantaging smaller origination networks against established players with dedicated compliance staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vegetable Oil Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Canola Oil, Palm Oil, Sunflower Oil End Use: Food Processing, Household Cooking, Industrial Applications, Cosmetics Distribution Channel: Supermarkets, Online Retail, Wholesale, Convenience Stores Packaging Type: Bottles, Cans, Pouches, Bulk Containers |
| Companies Covered | Conagra Brands, JM Smucker Company, Cargill Incorporated, Riceland Foods, Fuji Oil Holding, Bunge Limited, Ventura Foods, Perdue Agribusiness, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vegetable Oil Market Trends and Innovations
Processing technology and regulatory frameworks are converging to reshape how vegetable oils move from crush facilities to end-use applications, with implications for capital deployment and competitive positioning across the value chain.
Enzymatic interesterification is hybridizing conventional chemical refining with biological catalysis to produce structured lipids with tailored melting profiles. Snack food manufacturers in the Midwest are piloting these enzymatically modified oils to eliminate trans fats without sacrificing shelf stability. The technology is compressing R&D cycles for clean-label reformulations while raising equipment costs for processors.
The EPA's renewable fuel standard pathway approvals for soybean oil-based renewable diesel are redirecting crush economics toward industrial offtake contracts. Refiners in the Gulf Coast corridor are locking in multi-year supply agreements with Iowa and Illinois processors, tightening food-grade availability and supporting basis differentials. Food manufacturers are responding by accelerating canola oil substitution in frying applications.
Identity-preserved supply chains are capturing premium pricing in retail channels as verification technology reduces traceability costs. Supermarket private-label programs in the Northeast and Pacific Coast are replacing commodity soybean oil with non-GMO verified alternatives, forcing regional distributors to reconfigure blending and storage infrastructure. This shift is most visible in foodservice channels serving K-12 and university accounts with mandated sustainability procurement policies.
US Vegetable Oil Market Segmentation
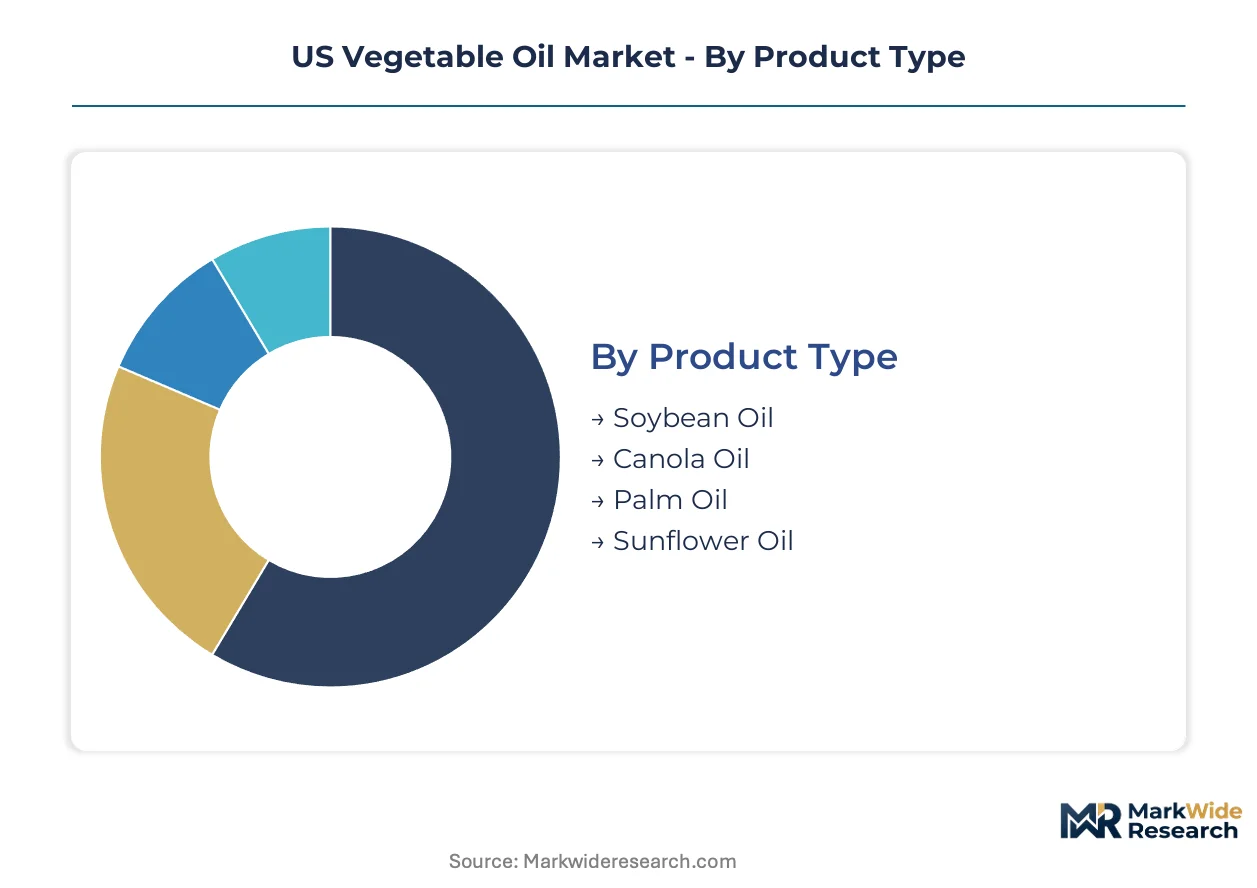
Vegetable oil segmentation reveals how crush economics, channel infrastructure, and end-use specifications fragment demand across distinct commercial pathways. Each dimension carries implications for margin capture, logistics configuration, and regulatory exposure.
Product Type:
After-sales service intensity varies sharply across oil types, with high-oleic varieties demanding technical support for shelf-life management and industrial buyers requiring specification compliance documentation.
- Soybean Oil:Triglyceride composition with polyunsaturated fat profiles above 50% dominates crush economics due to embedded protein meal co-production. Food manufacturers in Illinois and Iowa absorb volumes through river-adjacent terminals, though EPA renewable diesel mandates are redirecting supply toward industrial offtake contracts.
- Canola Oil:Lower saturated fat content at 7% versus soybean's 15% positions this variety for premium retail and foodservice channels requiring clean-label reformulations. Northeast supermarket private-label programs are accelerating identity-preserved sourcing to meet sustainability procurement mandates.
- Palm Oil:Southeast Asian imports undercut domestic pricing where saturated fat constraints do not apply.
- Sunflower Oil:High oleic variants serve specialty frying applications with superior oxidative stability.
Soybean oil holds the largest share; momentum sits with canola oil as food manufacturers accelerate trans fat elimination.
End Use:
Application-driven cost tiers separate commodity food processing from premium cosmetic formulations, with industrial channels capturing volume through offtake agreements.
- Food Processing:Manufacturers deploy vegetable oils for texture modification, heat transfer, and flavor carrier functions across snack, bakery, and prepared meal categories. FDA trans fat labeling requirements are forcing reformulation toward higher-oleic soybean and canola varieties with improved frying stability.
- Industrial Applications:Renewable diesel refiners in Louisiana and Texas are locking in multi-year supply agreements with Midwest crushers, tightening food-grade availability. EPA renewable fuel standard pathway approvals for soybean oil-based diesel are redirecting crush economics toward industrial channels.
- Household Cooking:Retail bottles and pouches serve direct consumer frying and sautéing demand.
- Cosmetics:Refined grades with low free fatty acid content supply oleochemical feedstocks for personal care formulations.
Food processing commands the greatest volume; industrial applications are climbing the fastest as biofuel mandates tighten.
Distribution Channel:
Channel concentration reflects geographic clustering of processing infrastructure and the logistics economics of bulk versus packaged movement.
- Supermarkets:Dominant channel for food-grade volume, with private-label programs in the Northeast and Pacific Coast replacing commodity soybean oil with non-GMO verified alternatives. Retailers are forcing distributors to reconfigure blending infrastructure for identity-preserved supply chains.
- Wholesale:Foodservice distributors supply K-12 and university accounts with mandated sustainability procurement policies, creating premium pricing for traceable oils. River-barge logistics from Illinois and Iowa processing hubs link origination to Gulf Coast terminals.
- Online Retail:Gaining traction in specialty and organic segments with compressed delivery timelines.
- Convenience Stores:Small-format packaged oils serve immediate household replenishment demand.
Supermarkets retain the largest share; online retail is gaining share fastest as specialty oil penetration expands.
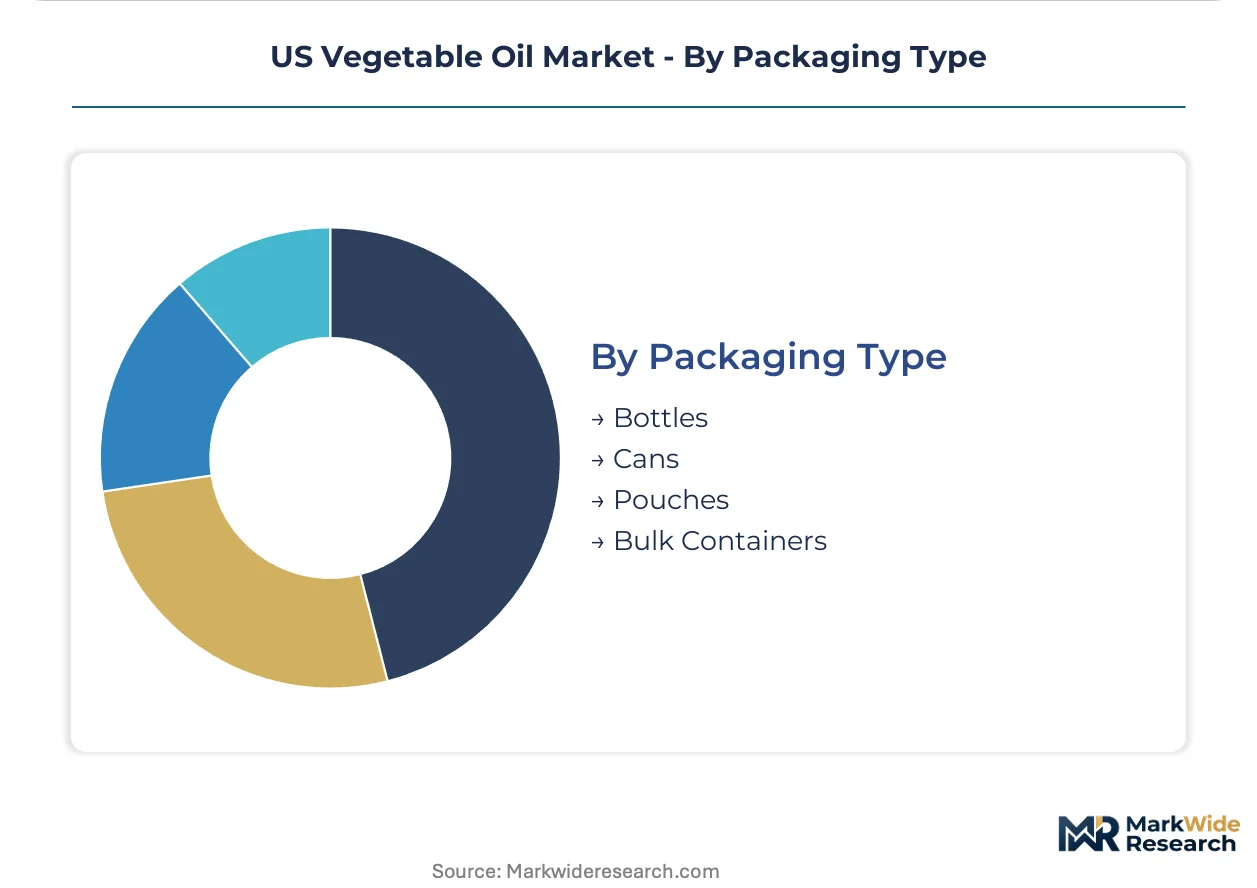
Packaging Type:
Packaging selection tracks end-use volume scale and shelf-life requirements, with bulk formats dominating industrial offtake and retail formats requiring oxidative protection.
- Bulk Containers:Tanker trucks and railcars move refined oils from Decatur complex and river-adjacent crush facilities to renewable diesel refiners and food manufacturers. Industrial buyers specify strict free fatty acid and moisture parameters that require solvent extraction upgrades.
- Bottles:PET and glass containers dominate supermarket and convenience store channels, with light-blocking formulations extending shelf life for high-oleic varieties. Labeling real estate accommodates FDA nutritional declarations and non-GMO verification marks.
- Pouches:Flexible formats reduce material costs for value-tier household cooking segments.
- Cans:Metal packaging serves foodservice and export markets requiring extended storage stability.
Bulk containers hold the largest share; pouches are expanding most quickly as material cost pressures reshape retail economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USDA anchors Midwest origination economics through commodity programs and biofuel mandates that redirect crush capacity toward renewable diesel feedstocks. River-adjacent processing clusters in Illinois and Iowa link Corn Belt soybean production to Gulf Coast export terminals. State-level low-carbon fuel standards in California and the Pacific Northwest create geographic premiums for verified supply chains.
Midwest (Illinois/Iowa)
Crush facilities along the Mississippi and Illinois Rivers absorb the majority of domestic soybean origination. The EPA's renewable fuel standard obligations pull increasing volumes into industrial offtake contracts with Louisiana and Texas refiners. Decatur, Illinois hosts multi-oil refining complexes competing on scale across food-grade and industrial channels.
Gulf Coast (Louisiana/Texas)
Renewable diesel refiners in this corridor are locking in multi-year supply agreements with Midwest processors, tightening food-grade availability. The region's port infrastructure enables soybean oil export to international oleochemical markets. Barge logistics from river-adjacent crush hubs reduce inland freight spreads to these terminal markets.
California
The state's Low Carbon Fuel Standard generates credit premiums for lower-carbon-intensity vegetable oil pathways. Food manufacturers and distributors serving K-12 and university accounts face mandated sustainability procurement policies. Supermarket private-label programs are replacing commodity soybean oil with non-GMO verified alternatives.
Northeast Corridor
Retail and foodservice channels concentrate demand for canola oil with lower saturated fat profiles. The FDA's trans fat labeling requirements accelerate clean-label reformulations among regional food processors. Identity-preserved supply chains are capturing premium pricing as verification technology reduces traceability costs.
Pacific Northwest
Emerging state-level low-carbon fuel standards in Oregon and Washington replicate California's credit premium structure. Specialty and organic oil segments show underpenetrated growth potential in mainstream retail. Regional distributors are reconfiguring blending and storage infrastructure for traceable supply chains.
US Vegetable Oil Market Competitive Landscape
Capability concentration sits with integrated crushers controlling origination infrastructure; scale advantage sits with diversified agribusiness conglomerates operating multi-oil refining complexes. The market structure tilts toward consolidation among river-adjacent processors with barge logistics access. Three archetypes dominate: backward-integrated originators, multi-oil refiners, and specialty oil distributors. Competitive moves center on crush capacity expansion and renewable diesel offtake agreements.
Among integrated agribusiness operators, Cargill Incorporated, Bunge Limited, and Archer Daniels Midland Company exemplify the scale-driven tier. Cargill leverages river-based logistics networks across Illinois and Iowa processing hubs. Bunge occupies a position within the origination-control archetype through elevator receipt management. Archer Daniels Midland anchors multi-oil refining complexity at its Decatur complex, competing across both food-grade and industrial channels. These three represent how crush economics and logistics integration determine competitive positioning.
| Leading Market Players |
|---|
| Conagra Brands |
| JM Smucker Company |
| Cargill Incorporated |
| Riceland Foods |
| Fuji Oil Holding |
| Bunge Limited |
| Ventura Foods |
| Perdue Agribusiness |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
Crush capacity concentration along the Mississippi and Illinois Rivers concentrates origination pricing power among three integrated processors. These river-adjacent facilities capture margin pools downstream through barge-linked logistics that compress freight spreads to Gulf Coast refiners and food manufacturers.
Pricing Analysis
Basis differentials between Iowa river terminals and Louisiana Gulf Coast refineries compress as renewable diesel offtake agreements multiply. Three-tier pricing structure across identity-preserved premium, standard food-grade, and industrial feedstock levels segments buyers by certification requirements and volume scale. Pricing pressure stems from palm oil import competition in oleochemical applications where saturated fat constraints do not apply. Mid-sized food manufacturers exhibit highest price sensitivity due to reformulation cost burdens without R&D scale advantages.
Supply Chain Analysis
Tariff exposure between Southeast Asian palm oil exporters and US industrial buyers dominates supply chain risk assessment for non-food applications. Domestic soybean origination draws from Illinois, Iowa, and Indiana farm receipts; solvent extraction capacity rests on hexane supply and natural gas feedstock costs. Single-source vulnerability concentrates in Mississippi River barge logistics during low-water periods. Distribution runs through river terminals to Decatur refining complexes and Gulf Coast renewable diesel facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
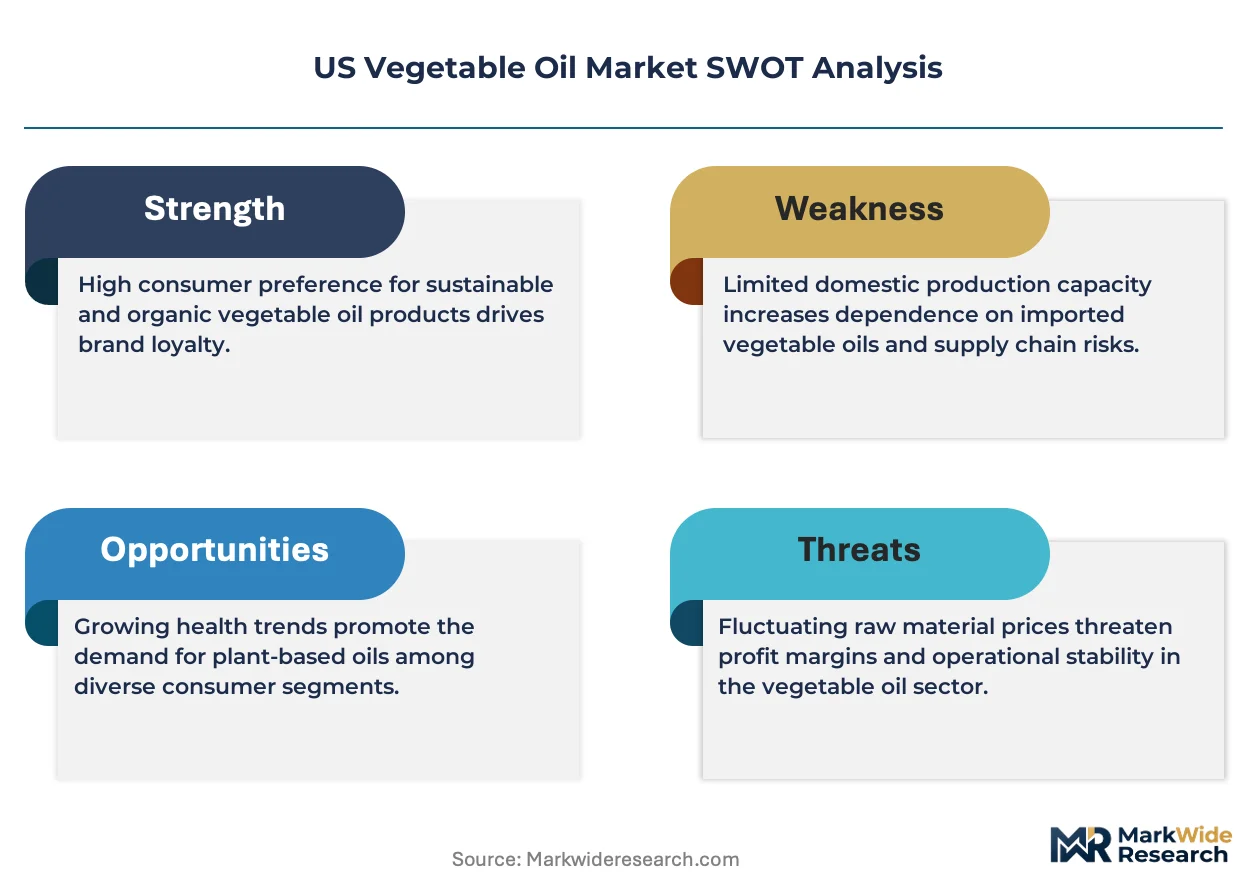
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA renewable fuel standard obligations create switching costs that lock industrial buyers into long-term soybean oil offtake contracts.
For Market Incumbents: Pre-empt specialty oil channel capture by accelerating identity-preserved handling infrastructure investments ahead of 36-month organic certification timelines. Defensive consolidation through elevator receipt control in the Corn Belt counters Bunge's origination dominance. Certification investment in non-GMO Project verification creates channel access barriers against mid-tier crushers lacking compliance staff scale.
For New Entrants and Emerging Players: Pacific Northwest state-level low-carbon fuel standards represent underpenetrated geography where Oregon and Washington programs replicate California's credit premium structure. White-space targets include organic retail segments where supermarket private-label programs force distributor infrastructure reconfiguration. Go-to-market angle centers on verified supply chain traceability technology that reduces audit documentation burdens for smaller origination networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap processors lacking solvent extraction upgrades for renewable diesel free fatty acid specifications. Long-term viability favors integrated operators with river logistics access and multi-oil refining complexity. Watch EPA pathway approval timelines for alternative feedstocks as inflection signals for crush margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Offtake Agreement | Locks forward demand visibility for Iowa and Illinois crush capacity investments. |
| Identity-Preserved Handling Infrastructure | Captures premium pricing in Northeast and Pacific Coast supermarket private-label programs. |
| Solvent Extraction Upgrade | Meets Louisiana and Texas refiners' strict free fatty acid and moisture specifications. |
| Organic Certification Investment | Opens 36-month transition timelines for underpenetrated mainstream retail segments. |
| River Logistics Network Expansion | Compresses inland freight spreads between Corn Belt origination and Gulf Coast terminals. |
Research Methodology
Operator-level perspectives from crush facility managers, renewable diesel refinery procurement leads, food manufacturer R&D directors, and supermarket category buyers anchored the qualitative base. Secondary validation drew from USDA commodity program disclosures, EPA renewable fuel standard pathway approvals, FDA nutritional labeling guidance, and SEC filings by integrated agribusiness operators. Bottom-up volume modeling triangulated against top-down crush capacity utilization estimates across the analysis window.
Scenario-bracketing framed projections across low, base, and high cases reflecting biofuel mandate stringency and South American soybean production variability. Segmentation dimensions modeled included oil type, end-use application, distribution channel, and packaging format alongside geographic processing cluster. CAGRs were derived from trend extrapolation of crush margins and renewable diesel feedstock demand curves. Industry-specific inputs incorporated RFS obligation pathways and state-level low-carbon fuel standard credit pricing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by river-adjacent processors or accelerated palm oil tariff adjustments would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Global Cocoa Products Market
Ingredients
Bouillon Cubes Market
Ingredients
North America Carrageenan Market
Ingredients
Corn Starch Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Marine Peptides Market
Ingredients
North America Dairy Protein Market
Ingredients
Agarwood Oil Market
Ingredients
Beetroot Powder Market
Ingredients
Hexane-Free Protein Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
South America Fermented Ingredients Market
Ingredients
South America Clean Ingredients Market
Ingredients
Ice Cream Bases Market