
 Palm Mid-Fraction Market | 2026-2036
Palm Mid-Fraction Market Size, Share, and Industry Trends Forecast 2026-2036
Palm Mid-Fraction Market Analytics
Market Context
Indonesia is fragmenting its palm mid-fraction capacity across Kalimantan and Sumatra to reduce logistics costs and secure feedstock proximity. IOI Corporation Berhad leverages integrated refining complexes in Malaysia to sustain margin capture from crude palm oil through finished oleochemicals. Musim Mas Group anchors its competitive stance through controlled shipping channels and dedicated olein storage terminals in Singapore and Rotterdam. Wilmar International Limited dominates procurement networks across Indonesian smallholder cooperatives, securing volume throughput for its fractionation plants.
Technical Profile and Segment Structure
Palm mid-fraction comprises the triglyceride subset separated through crystallization and filtration of palm oil, typically yielding iodine values between 32 and 44 with melting points near 35°C, serving as the functional backbone for cocoa butter substitutes and premium confectionery fats. The palm olein segment leads volume throughput due to its dominance in food frying and cooking oil formulations across Asian and African markets. Fatty acids represent the fastest-expanding product category as chemical producers convert them into surfactants and lubricant bases, while refined oil maintains mature, price-competitive positioning in bulk commodity channels. Personal care applications concentrate margin pools through cosmetic-grade certifications and specialized olein derivatives for emollient formulations.
Regulatory Environment and Outlook
The EU Deforestation Regulation and REACH compliance requirements in Europe reshape market access for Southeast Asian exporters, forcing traceability investments from plantation to port. Indonesia's national sustainability certification system and Malaysia's MSPO standards create dual compliance layers for producers serving both European and Asian buyers. Stakeholders must monitor evolving biodiesel blending mandates in Indonesia and Brazil, as policy shifts in either jurisdiction redirect palm olein flows between food and energy markets.
Market Dynamics
Fractionation capacity concentration in Johor and Riau provinces has created a supply chokepoint where crystallization technology upgrades determine margin capture. The EU Deforestation Regulation's traceability mandates are forcing upstream investments that reshape competitive positioning between integrated refiners and merchant processors.
Growth Catalysts
- EU Deforestation Regulation:Traceability requirements from plantation to port are accelerating certification infrastructure buildout across Indonesian and Malaysian supply chains.
- Confectionery fat substitution:Cocoa butter price volatility is pulling food manufacturers toward palm mid-fraction formulations for premium chocolate coatings.
- Biodiesel blending mandates:Indonesia's B35 program and Brazil's RenovaBio framework are redirecting palm olein flows between food and energy applications.
Market Restraints
- Crude palm oil price volatility:El Niño-driven supply disruptions in Kalimantan and Sumatra create margin compression for fractionators lacking upstream plantation control.
- EU Deforestation Regulation compliance costs:Satellite verification systems and chain-of-custody documentation impose fixed cost burdens on smallholder-dependent supply chains.
- Soybean oil substitution:South American crushers are capturing share in Asian frying oil markets through aggressive freight arbitrage into India and China.
Strategic Opportunities
- Indian specialty fats market:Vanaspati reformulation toward trans-fat-free profiles creates pull for high-oleic palm mid-fraction in commercial bakery applications.
- Cosmetic-grade olein certification:RSPO-IP and mass balance schemes unlock premium positioning in European personal care formulations.
- Dry fractionation technology convergence:Membrane filtration integration with conventional crystallization is collapsing energy intensity for mid-fraction producers.
Industry Challenges
- Fractionation process engineering talent:Crystallization kinetics expertise concentrates among retiring specialists at Malaysian and Indonesian refiners.
- MSPO and ISPO dual certification timelines:Audit backlogs and documentation gaps delay market access for mid-tier processors serving European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palm Mid-Fraction Market |
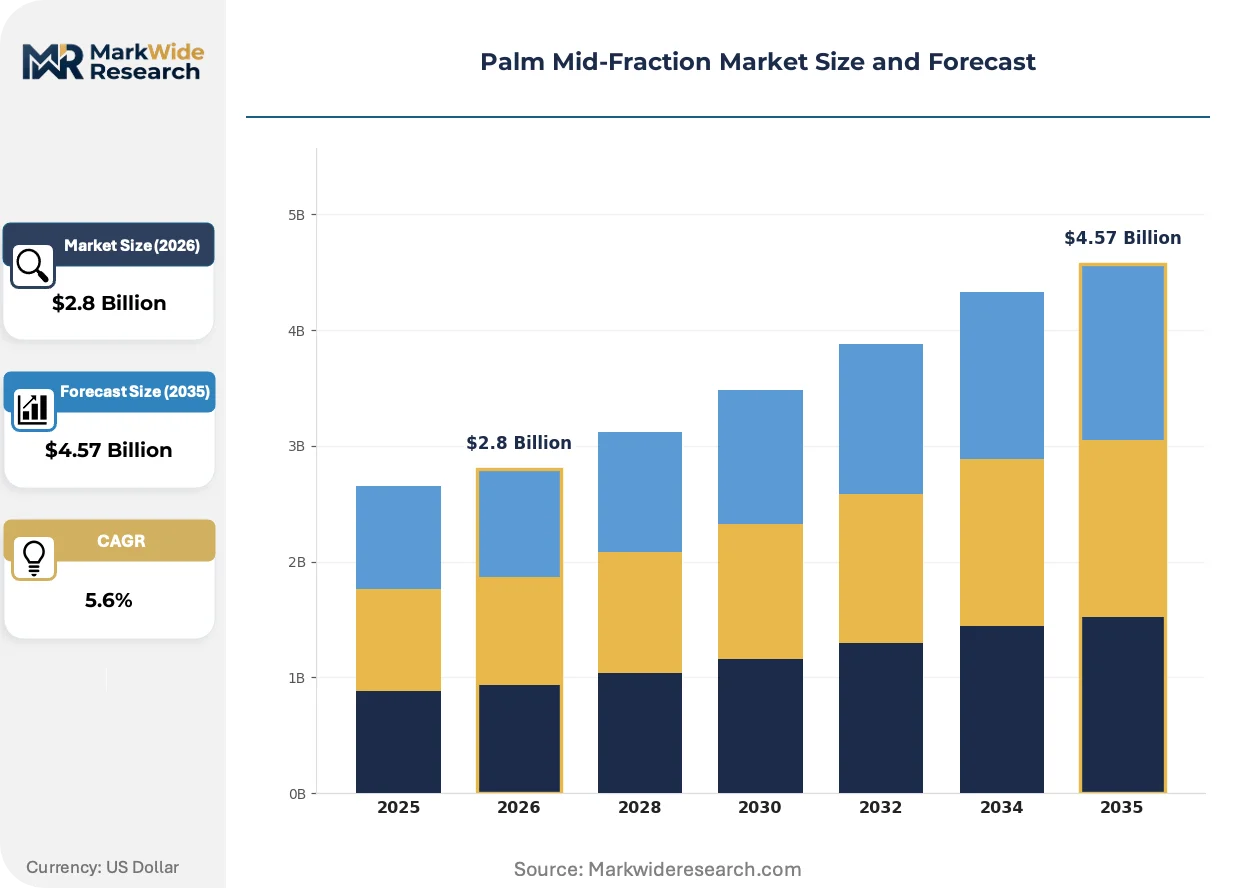
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Palm Stearin, Palm Olein, Fatty Acids Application: Food Industry, Personal Care, Biofuel, Industrial Lubricants End User: Food Manufacturers, Cosmetic Companies, Energy Providers, Chemical Producers Distribution Channel: Direct Sales, Wholesale, Retail, E-commerce |
| Companies Covered | IOI Corporation Berhad, Musim Mas Group, Wilmar International Limited, Mewah Group, Golden Agri-Resources Ltd, Cargill, Incorporated, Kuala Lumpur Kepong Berhad, AAK AB, Sime Darby Plantation Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palm Mid-Fraction Market Evolving Landscape
Fractionation technology is compressing the cost structure for mid-fraction production while regulatory traceability requirements are reshaping procurement relationships. These forces are simultaneously enabling new product categories and constraining market access for non-compliant suppliers.
Dry fractionation with automated crystal washing is collapsing the energy differential between palm mid-fraction and enzymatically interesterified alternatives. European confectionery manufacturers are adopting these materials for premium coating applications at accelerating pace. The technology is collapsing the historical premium commanded by cocoa butter equivalents in temperate climate formulations.
REACH compliance requirements in Europe are forcing reformulation of oleochemical derivatives used in surfactant applications. ECHA substance evaluation deadlines are compressing registration timelines for palm-based fatty acid esters. Specialty chemical producers serving German and Dutch industrial markets are responding by segregating supply chains for EU versus Asian-bound production.
Buyers in the Indian subcontinent are consolidating procurement through direct refinery relationships, bypassing traditional trading houses. Large-format food service operators and consumer goods manufacturers are establishing annual volume commitments with Johor-based fractionators. This concentration is most visible in Maharashtra and Gujarat states where bulk oil distributors are losing share to integrated supply contracts.
Palm Mid-Fraction Market Segmentation
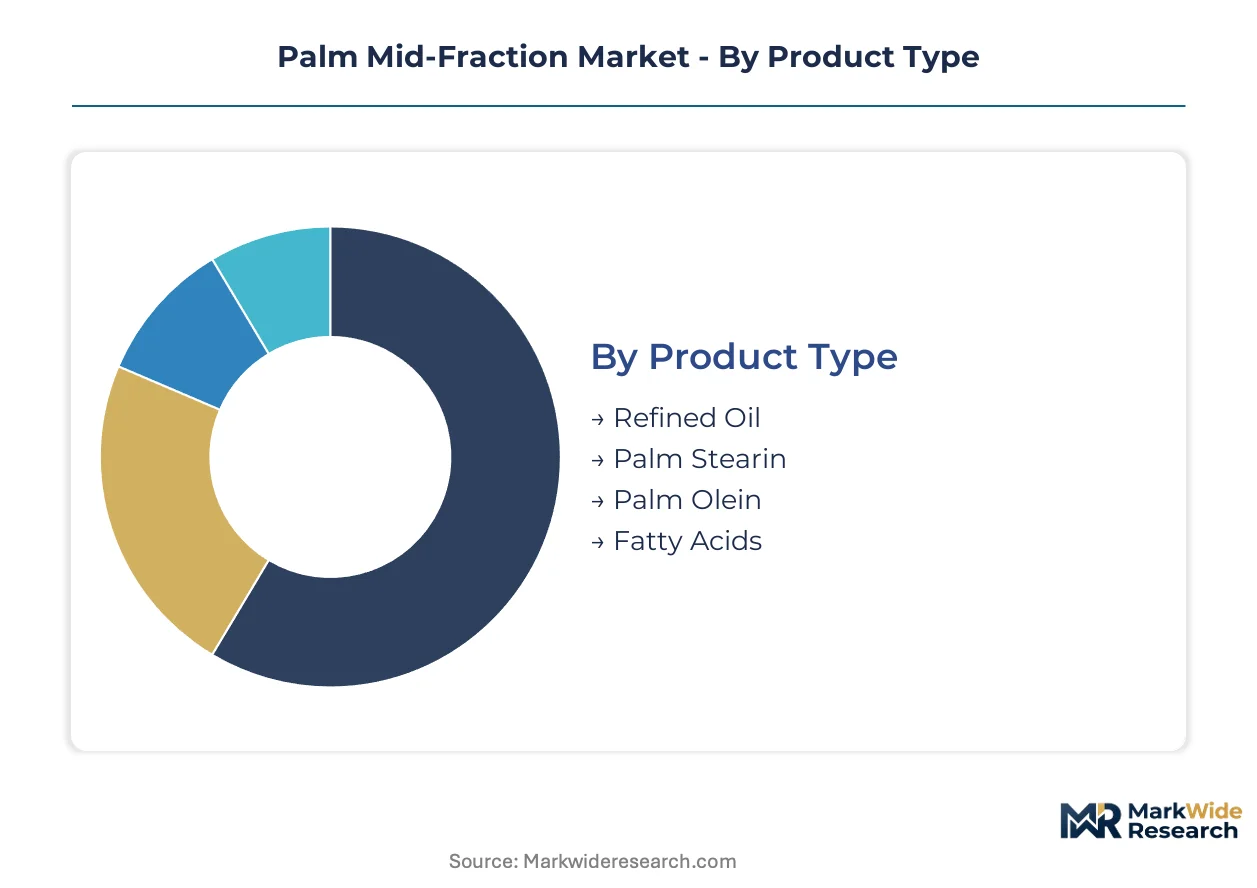
Palm mid-fraction segmentation reveals distinct velocity profiles across product categories. Crystallization cycles and certification requirements create divergent inventory turns that reshape procurement strategies for integrated refiners and merchant processors.
Product Type:
Cycle times vary sharply across this category, with liquid fractions turning over fastest and solid derivatives requiring extended crystallization holds. Processing intensity and storage specifications dictate working capital deployment patterns.
- Palm Olein:The liquid fraction separated through controlled crystallization, characterized by iodine values between 56 and 60 and clear appearance at room temperature. Demand concentrates in Indonesian and Malaysian food manufacturing clusters where high-volume frying applications absorb steady throughput. Biodiesel blending mandates in Indonesia periodically divert volumes from food channels, creating supply tightness in Asian cooking oil markets.
- Fatty Acids:Derived through hydrolysis or saponification of palm oil triglycerides, yielding C12-C18 carbon chains for downstream oleochemical conversion. Chemical producers in Germany and the Netherlands are expanding procurement from certified segregated supply chains to satisfy REACH registration requirements for surfactant feedstocks. This segment gains share at the steepest rate as personal care and industrial lubricant formulators seek renewable alternatives to petrochemical bases.
- Refined Oil:Bleached and deodorized palm oil serving bulk commodity channels with minimal downstream processing.
- Palm Stearin:The higher-melting solid fraction crystallized from crude palm oil, supplying margarine and shortening formulations.
Palm olein anchors the volume base while fatty acids gain share at the steepest rate.
Application:
Margin structures diverge sharply across this dimension, with commodity food applications compressing returns and certified specialty channels preserving premium capture. Regulatory compliance costs distribute unevenly, forcing strategic choices about market access investment.
- Food Industry:Encompasses frying oils, confectionery fats, margarines, and bakery shortenings formulated from palm mid-fraction derivatives. Manufacturers in India are reformulating vanaspati products toward trans-fat-free profiles, pulling high-oleic palm olein into commercial bakery applications. EU Deforestation Regulation traceability mandates impose documentation burdens that favor integrated refiners over merchant traders in European supply chains.
- Personal Care:Cosmetic-grade olein and fatty acid esters serving emollient, surfactant, and formulation base applications. Formulators in France and Germany are consolidating procurement around RSPO-IP certified mass balance schemes, creating tiered pricing structures that reward supply chain segregation investments. This application commands the highest margin premiums but requires dedicated storage and handling infrastructure.
- Biofuel:Palm olein and fatty acid methyl esters converted to biodiesel through transesterification processes.
- Industrial Lubricants:Palm-based base stocks and fatty acid derivatives replacing mineral oil formulations in metalworking and hydraulic fluids.
Food industry applications absorb the dominant volume share while personal care channels deliver the strongest margin expansion trajectory.
End User:
Procurement sophistication varies dramatically, with multinational food manufacturers imposing strict certification requirements and energy buyers prioritizing volume scale over traceability granularity. Contract structures reflect these divergent capability thresholds.
- Food Manufacturers:Multinational confectionery and processed food producers with established supplier audit programs and sustainability scorecards. Nestlé and Unilever procurement teams are consolidating direct refinery relationships in Johor and Riau, bypassing traditional trading intermediaries. These buyers demand satellite-verified deforestation-free documentation that smallholder-dependent supply chains struggle to deliver.
- Chemical Producers:Oleochemical specialists converting fatty acids into surfactants, lubricant additives, and polymer intermediates. BASF and Evonik operations in Ludwigshafen and Antwerp are segregating production lines between EU-bound and Asian-bound output to manage REACH compliance complexity. This end user segment is expanding most quickly as industrial decarbonization targets drive renewable feedstock substitution.
- Cosmetic Companies:Beauty and personal care formulators sourcing certified cosmetic-grade olein derivatives.
- Energy Providers:Biodiesel blenders and renewable fuel producers purchasing palm olein for transesterification.
Food manufacturers dominate current procurement volumes while chemical producers are capturing share fastest through specialty fatty acid demand.
Distribution Channel:
Channel economics reflect shipment scale and relationship intensity, with direct contracts capturing efficiency gains and retail fragments serving dispersed small-buyer demand. Digital platforms are penetrating spot-market segments without displacing relationship-based bulk procurement.
- Direct Sales:Annual volume commitments between fractionators and large-format end users with dedicated logistics arrangements. IOI Corporation and Wilmar International have expanded direct contracting teams in Mumbai and Lagos to capture African and South Asian frying oil demand. These relationships typically incorporate price adjustment clauses tied to crude palm oil futures benchmarks.
- Wholesale:Bulk distributors and trading houses aggregating volumes for regional redistribution to mid-scale processors.
- Retail:Packaged consumer oils sold through supermarket and traditional trade channels.
- E-commerce:Digital platforms facilitating spot transactions and specialty product discovery for small-batch buyers.
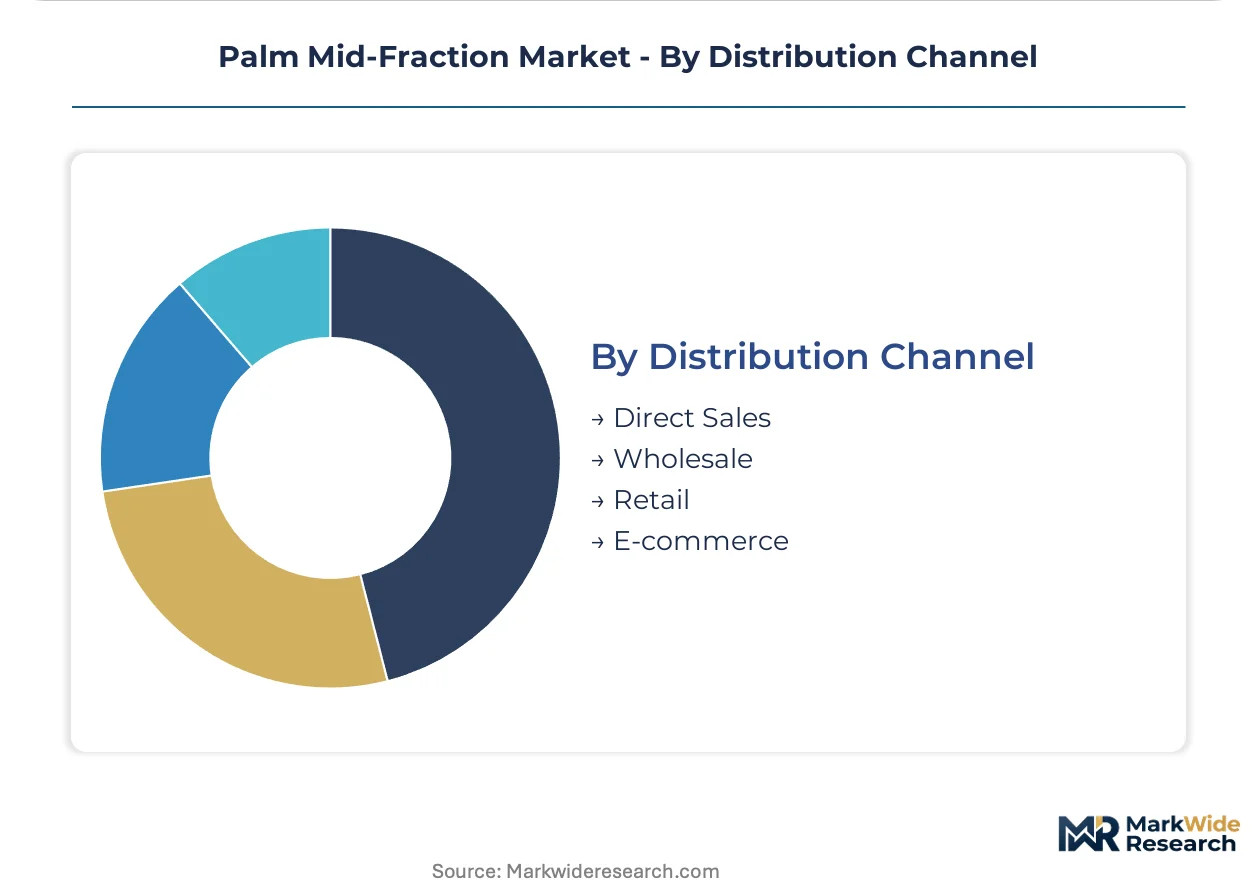
Direct sales channels handle the majority of volume throughput while e-commerce penetration remains concentrated in specialty and spot-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fractionation capacity clusters in Johor and Riau provinces concentrate supply-side leverage for Southeast Asian refiners serving global oleochemical demand. Kalimantan and Sumatra expansion projects aim to reduce feedstock logistics costs for Indonesian processors. European traceability mandates and Asian food manufacturing growth pull trade flows in divergent directions.
Indonesia
Domestic biodiesel blending mandates redirect palm olein volumes between food and energy channels, creating periodic tightness in cooking oil supply. The national sustainability certification system imposes documentation requirements that smallholder cooperatives struggle to satisfy. Fractionation complexes in Riau province expand crystallization capacity to capture margin from crude palm oil through finished mid-fraction products.
Malaysia
Integrated refining complexes in Johor sustain margin capture across the value chain from plantation to oleochemical derivatives. MSPO standards create compliance layers for producers serving both European and Asian buyers simultaneously. Port infrastructure in Pasir Gudang and Tanjung Pelepas anchors shipping logistics for mid-fraction exports to India and China.
India
Vanaspati reformulation toward trans-fat-free profiles generates pull for high-oleic palm mid-fraction in commercial bakery applications. FSSAI regulations on edible oil quality standards reshape procurement specifications for bulk food manufacturers. Maharashtra and Gujarat states see consolidation of direct refinery relationships as large-format food service operators bypass traditional trading intermediaries.
Germany
REACH compliance deadlines compress registration timelines for palm-based fatty acid esters used in surfactant applications. ECHA substance evaluation protocols force reformulation of oleochemical derivatives serving industrial lubricant markets. BASF and Evonik operations in Ludwigshafen segregate production lines between EU-bound and Asian-bound output to manage regulatory complexity.
Netherlands
Rotterdam storage terminals serve as distribution nodes for certified segregated supply chains entering European personal care formulations. ECHA registration requirements for downstream oleochemical derivatives impose documentation burdens on importers. Chemical producers in Antwerp expand procurement from mass balance schemes to satisfy cosmetic-grade certification demands from French and German formulators.
Palm Mid-Fraction Market Competitive Landscape
Vertically integrated plantation-refiners and merchant fractionators split the market along control of upstream feedstock access. The competitive terrain favors operators with captive crude palm oil supply and dedicated logistics infrastructure. Three archetypes dominate: integrated agribusiness conglomerates with plantation-to-port control, specialized oleochemical processors with certification expertise, and global trading houses with balance sheet capacity for bulk arbitrage. Capacity expansion in Riau and Johor provinces and strategic partnerships for European traceability compliance represent the dominant competitive moves.
Among Southeast Asian integrated operators, IOI Corporation Berhad, Musim Mas Group, and Wilmar International Limited occupy positions that exemplify the plantation-refiner archetype. These Malaysian and Singapore-linked entities anchor procurement networks across Indonesian smallholder cooperatives and maintain fractionation complexes with direct shipping access to Indian and European markets. Their structural positioning reflects the industry pattern where upstream feedstock control determines margin sustainability through volatile crude palm oil price cycles.
| Leading Market Players |
|---|
| IOI Corporation Berhad |
| Musim Mas Group |
| Wilmar International Limited |
| Mewah Group |
| Golden Agri-Resources Ltd |
| Cargill, Incorporated |
| Kuala Lumpur Kepong Berhad |
| AAK AB |
| Sime Darby Plantation Berhad |
| Others |
Value Network & Pricing Analysis
Singapore-Rotterdam shipping corridor cost dynamics compress margin capture for Johor and Riau fractionators while amplifying price spreads between certified and uncertified palm mid-fraction grades in European personal care channels.
Pricing Analysis
The EU Deforestation Regulation dictates the pricing tier structure across palm mid-fraction markets, separating RSPO-IP certified mass balance shipments from conventional bulk olein. Three-tier pricing structure across premium cosmetic-grade, standard food-grade, and economy biodiesel-feedstock levels reflects certification investment and traceability granularity. Cost compression in standard food-grade channels is intensifying because Indonesian biodiesel mandates periodically divert olein volumes and tighten supply. Smallholder-dependent cooperatives exhibit highest price sensitivity due to documentation compliance burdens, while multinational cosmetic formulators demonstrate lowest sensitivity given emollient formulation premiums.
Supply Chain Analysis
Export-control regimes limiting biotechnology transfers have minimal direct impact on palm fractionation flows, though REACH registration requirements function as de facto trade restrictions on fatty acid esters entering European chemical markets. Supply concentrates in Indonesia, Malaysia, and Singapore, with Riau and Johor provinces anchoring crystallization capacity. Raw material flows draw from Kalimantan and Sumatra crude palm oil estates, membrane filtration equipment, and Rotterdam storage terminal access. Single-source vulnerability concentrates in Indonesian smallholder cooperative networks lacking satellite verification infrastructure. Distribution runs through direct annual volume contracts between fractionators and large-format food manufacturers, supplemented by wholesale trading house aggregation for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palm mid-fraction markets approach a platform-economics inflection as traceability infrastructure and certification interoperability become the dominant competitive moat rather than raw processing scale alone.
For Market Incumbents: Pre-empt soybean oil substitution threats in Indian frying markets by accelerating high-oleic palm olein formulation partnerships with Maharashtra and Gujarat bakery operators. Deepen backward integration into Kalimantan plantation assets to secure feedstock during El Niño-driven supply disruptions. Prioritize MSPO-ISPO dual certification infrastructure to maintain European market access against audit backlog delays affecting mid-tier competitors.
For New Entrants and Emerging Players: Establish a beachhead in cosmetic-grade olein certification services, where RSPO-IP mass balance scheme expertise commands premium positioning among French and German personal care formulators. Target underpenetrated dry fractionation technology integration, where membrane filtration convergence with crystallization collapses energy intensity and opens margin capture for specialized engineering firms. Deploy direct refinery relationship models in African markets, bypassing traditional trading house intermediaries that dominate Lagos and Mumbai procurement channels.
For Investors and Strategic Acquirers: Fractionators with captive plantation control and dedicated Rotterdam storage terminals present the strongest acquisition profile for long-term viability across volatile crude palm oil cycles. These assets anchor margin sustainability through supply disruptions while capturing premium flows into certified European channels. Monitor biodiesel blending mandate shifts in Indonesia and Brazil as the critical inflection signal redirecting olein volumes between food and energy applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Kalimantan estate control secures feedstock proximity and reduces logistics cost exposure during El Niño events. |
| Dual Certification Infrastructure Buildout | MSPO-ISPO parallel compliance unlocks simultaneous European and Asian market access for integrated refiners. |
| Membrane Filtration Technology Adoption | Dry fractionation energy convergence collapses cost differential against enzymatic interesterification alternatives. |
| Direct Refinery Relationship Expansion | Annual volume contracts with Mumbai and Lagos operators displace traditional trading house intermediaries. |
| Rotterdam Storage Terminal Access | Dedicated olein terminals anchor certified segregated supply chain distribution into German and Dutch chemical markets. |
Research Methodology
A standing panel of fractionation plant managers, procurement leads at European cosmetic formulators, RSPO certification auditors, and Rotterdam terminal operators provided ongoing calibration across primary fieldwork and secondary validation. Customs data from Indonesian and Malaysian trade ministries, ECHA substance registration databases, SEC filings from listed agribusiness conglomerates, and MSPO audit reports supplied triangulation anchors. Bottom-up volume estimates from individual refinery capacity utilization combined with top-down trade flow analysis to bracket market sizing.
Scenario-bracketing around biodiesel mandate policy shifts and El Niño frequency distributions bounded high-low projections across the analysis window. Segmentation modeling incorporated product type crystallization cycles, application-specific certification requirements, end-user procurement sophistication tiers, and distribution channel relationship intensity. CAGRs derived from historical trade elasticity patterns and capacity expansion pipelines, with specific weighting for REACH compliance cost pass-through and Indian vanaspati reformulation velocity.
Sensitivities concentrate around EU Deforestation Regulation enforcement timelines and Indonesian B35 program implementation consistency. Forecasts reflect documented assumptions on smallholder cooperative documentation capability and membrane filtration adoption curves. Material shifts in European traceability verification technology or Brazilian RenovaBio framework expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Vitamin D Ingredients Market
Ingredients
Organic Edible Oil Market
Ingredients
Potato Granules Market
Ingredients
Soy Derivatives Market
Ingredients
France Soy Protein Market
Ingredients
Vegan Ingredients Market
Ingredients
White Wheat Malt Market
Ingredients
Bread Flour Market
Ingredients
Elecampane Root Market
Ingredients
Aroma Ingredients Market
Ingredients
High Protein Flour Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Mineral Premix Market
Ingredients
North America Cocoa Products Market
Ingredients
Valerian Root Oil Market