
 Ben Oil Market | 2026-2036
Ben Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Ben Oil Market Analysis
Cold-press extraction is narrowing the quality gap between artisanal and commercial ben oil output. AOS Products Pvt. Ltd. leverages integrated moringa estates in Rajasthan to secure feedstock consistency. Kerfoot Group anchors European distribution through its specialty oils trading infrastructure. Jedwards International, Inc. competes on bulk volume for North American cosmetic compounders.
Ben oil is a light, non-drying vegetable oil extracted from Moringa oleifera seeds with a high oleic acid profile exceeding 70 percent and a characteristic low viscosity suited to precision lubrication and skincare formulations. Its primary commercial purpose centers on cosmetic emollients, biodegradable lubricants, and aviation-compatible hydraulic fluids. Refined oil commands the dominant margin pool due to deodorization and color-stability requirements in pharmaceutical and aviation applications, while crude oil sustains growth in artisanal soap and regional cosmetic markets where minimal processing carries premium positioning. Synthetic oil occupies a niche defending against supply seasonality, though its higher unit cost limits expansion beyond military and emergency-reserve contracts.
India's BIS certification framework and the FSSAI's evolving standards for cosmetic-grade vegetable oils shape product specifications and cross-border market access for unrefined exports. The EPA's renewable lubricant guidelines and REACH registration requirements in Europe further filter which grades enter industrial channels. Stakeholders must monitor feedstock substitution risks as moringa cultivation competes with food-crop land use in tropical belts.
Market Dynamics
Cold-press extraction technology is compressing quality variance between artisanal and commercial ben oil, while India's BIS certification tightens import thresholds and Southeast Asian cosmetics formulators rewrite sourcing specifications.
Growth Catalysts
- REACH registration in Europe:Pharmaceutical-grade ben oil gains preferential market access through ECHA-compliant supply chains, displacing unregistered competitors from industrial channels.
- Aviation hydraulic fluid demand:Biodegradable lubricant mandates from the FAA and EPA steer procurement toward high-oleic vegetable oils with established cold-flow performance.
- Kerala processing corridor concentration:Clustered refining infrastructure in southern India reduces logistics costs for cosmetic compounders targeting Middle East export markets.
Market Restraints
- Moringa seed price volatility:Feedstock costs fluctuate with monsoon patterns across Rajasthan and Tamil Nadu, compressing margins for non-integrated processors.
- Refined grade supply concentration:Deodorization capacity clusters among three Indian states, creating bottleneck risk for pharmaceutical and aviation contract volumes.
- Synthetic ester substitution:Military and emergency-reserve buyers maintain dual-source strategies with petroleum-derived alternatives during seed harvest shortfalls.
Strategic Opportunities
- EU Green Deal bio-lubricant quotas:Renewable hydraulic fluid mandates create dedicated offtake channels for ISCC-certified ben oil from 2027 compliance deadlines.
- Direct-to-compounder e-procurement:Specialty chemical platforms bypass traditional distributor markups for mid-volume North American skincare manufacturers.
- Precision fermentation convergence:Biotechnology firms explore microbial oleic acid production as complementary feedstock, reducing agricultural land-use tension.
Industry Challenges
- Cold-press technician scarcity:Skilled operators who balance yield against oxidation control command premium wages in Rajasthan's processing belt.
- BIS-FSSAI certification timeline:Dual approval pathways for cosmetic-grade exports extend time-to-market by eight to fourteen months for new market entrants.
- Legacy solvent extraction asset stranding:Refiners face retrofit decisions as cold-press specifications displace hexane-processed output from premium contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ben Oil Market |
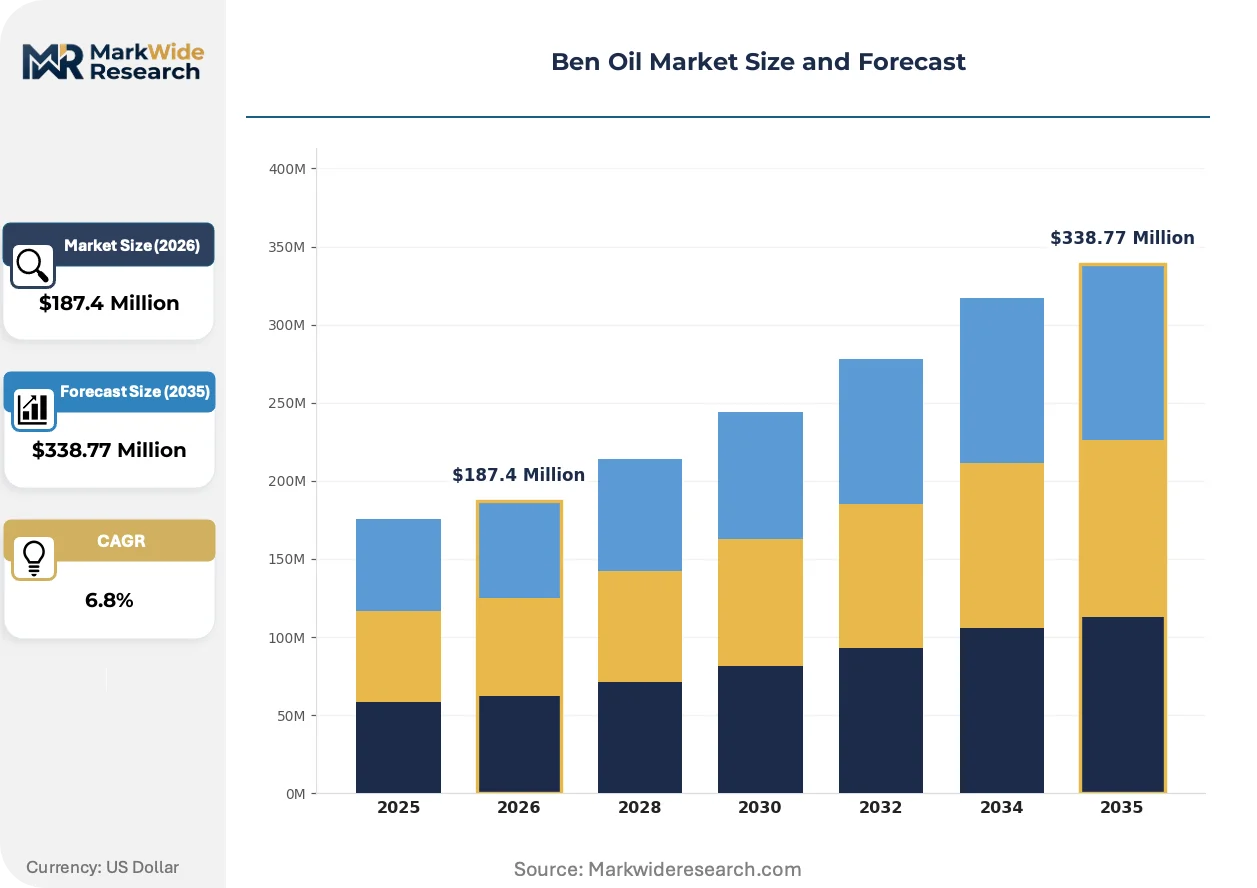
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Refined Oil, Synthetic Oil, Others Application: Industrial, Automotive, Aviation, Marine Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Quality Grade: Premium, Standard, Economy, Others |
| Companies Covered | AOS Products Pvt. Ltd., Avi Naturals, Dawn Moringa, Katyani Exports, Jedwards International, Inc., Kerfoot Group, Asili Natural Oils, Green India, Ayuritz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ben Oil Market Emerging Trajectories
Extraction technology, regulatory chemistry standards, and procurement digitization are simultaneously rewriting competitive requirements across the ben oil value chain.
Supercritical CO2 extraction is migrating from laboratory-scale pilots to commercial installations serving European pharmaceutical compounders. Swiss and German lubricant blenders now specify CO2-extracted grades for aviation hydraulic formulations where residual solvent limits are tightening. This technology is compressing the addressable market for traditional hexane-refined output in premium segments.
India's BIS quality certification mandates now require heavy metal and pesticide residue testing for all unrefined ben oil export lots. The framework eliminates informal traders from formal supply chains and redirects volume toward integrated estate processors with in-house laboratory capabilities. Kerala and Maharashtra facilities are responding with captive testing infrastructure rather than third-party outsourcing.
Cosmetics formulators in Southeast Asia now contract directly with Rajasthan estate operators through blockchain-verified provenance platforms. This channel disintermediation eliminates two distributor layers for mid-tier compounders in Vietnam and Indonesia. The shift is most visible in emulsion stability specifications where cold-pressed origin documentation commands price premiums over blended certificates of analysis.
Ben Oil Market Segmentation
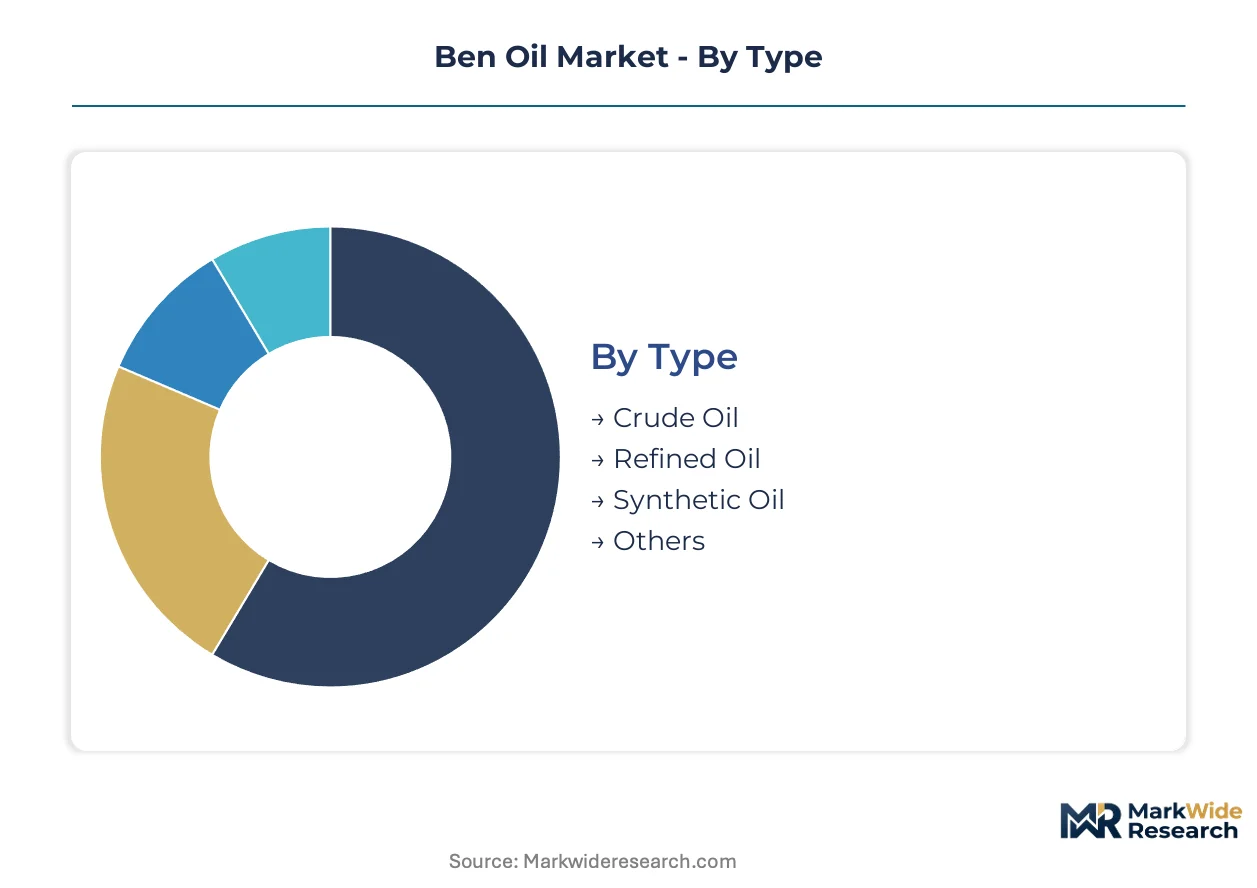
Ben oil procurement cycles vary dramatically by processing depth and end-use certification requirements. Segment boundaries are hardening as cold-press specifications displace solvent-extracted volumes from premium contracts.
Type:
Refined grades turn inventory fastest in aviation and pharmaceutical channels, while crude oil moves slowly through artisanal cosmetic networks.
- Refined Oil:Deodorized and color-stabilized output meeting ECHA REACH and FAA biodegradable lubricant specifications. Demand concentrates in Swiss and German aviation hydraulic blenders where residual solvent limits are tightening.
- Crude Oil:Minimally processed grades carrying premium positioning in regional cosmetic markets. Kerala's processing corridor and Maharashtra's contract manufacturing belt absorb the largest volumes for soap and emulsion formulations.
- Synthetic Oil:Petroleum-derived esters defending against moringa seed harvest shortfalls in military and emergency-reserve procurement.
- Others:Blended and co-processed grades serving price-sensitive industrial lubricant applications.
Refined oil anchors the volume base while crude oil gains share at the steepest rate.
Application:
Aviation and automotive specifications command the highest quality premiums, while industrial buyers optimize for unit cost.
- Aviation:High-oleic profiles exceeding 70 percent with established cold-flow performance for FAA-compliant hydraulic systems. European lubricant blenders now specify CO2-extracted grades exclusively.
- Automotive:Biodegradable lubricant mandates from the EPA steer procurement toward vegetable-derived base stocks for precision engine applications.
- Industrial:Bulk volume consumption in precision machinery where low viscosity and oxidation stability reduce maintenance intervals.
- Marine:Emerging demand from port authorities with environmental discharge restrictions in North Sea and Mediterranean jurisdictions.
Industrial applications absorb the largest tonnage while aviation specifications expand most quickly.
Distribution Channel:
Direct procurement compresses cycle times for compounders with certified supply requirements, while retail channels serve fragmented artisanal demand.
- Direct Sales:Estate-to-compounder relationships through blockchain-verified provenance platforms. Southeast Asian cosmetics formulators in Vietnam and Indonesia now bypass two distributor layers.
- E-commerce:Specialty chemical platforms serving mid-volume North American skincare manufacturers with reduced markup structures.
- Wholesale:Traditional bulk aggregation for industrial lubricant blenders with established hexane-refined supply contracts.
- Retail:Small-package sales to artisanal soap makers and regional cosmetic producers with minimal certification requirements.
Wholesale channels still dominate total volume while direct sales climb the fastest.
Quality Grade:
Premium grades carry extended certification timelines, while economy tiers move immediately upon harvest availability.
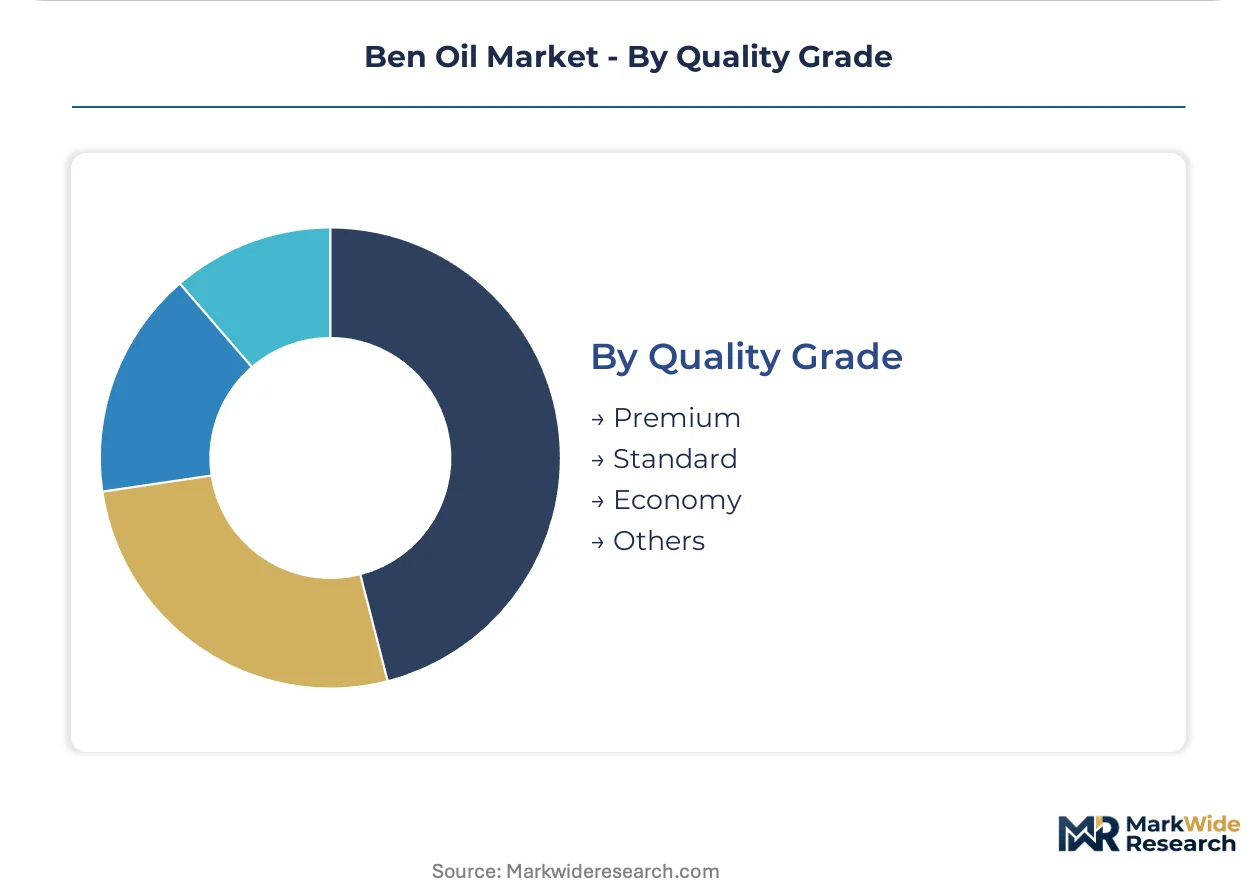
- Premium:BIS-certified and FSSAI-compliant grades with heavy metal and pesticide residue documentation. India's integrated estate processors with captive laboratory capabilities control this tier.
- Standard:Deodorized output meeting cosmetic-grade vegetable oil specifications without full pharmaceutical certification.
- Economy:Unrefined grades for artisanal soap and regional cosmetic markets where minimal processing carries origin-based premiums.
- Others:Custom-blended specifications for military and emergency-reserve contracts with synthetic ester dual-sourcing.
Economy grades sustain the widest volume base while premium certification is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation hydraulic fluid blenders in Switzerland and Germany, cosmetics formulators in Southeast Asia, and integrated estate processors in Rajasthan represent three distinct buyer archetypes pulling ben oil through differentiated supply chains. Each geography imposes unique certification burdens and cluster advantages.
India
BIS quality certification mandates and FSSAI cosmetic-grade standards filter unrefined export volumes toward integrated processors with captive laboratories. The Kerala processing corridor and Maharashtra's contract manufacturing belt concentrate deodorization capacity for Middle East-bound pharmaceutical and aviation contracts. Rajasthan's moringa estates supply feedstock to compounders seeking cold-pressed origin documentation.
Germany
Swiss and German lubricant blenders specify CO2-extracted grades exclusively for aviation hydraulic formulations where ECHA REACH residual solvent limits are tightening. The country's national chemical regulator enforces documentation requirements that displace unregistered competitors from industrial channels. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg host precision blending facilities serving FAA-compliant aerospace procurement.
United States
EPA renewable lubricant guidelines steer mid-volume skincare manufacturers and automotive compounders toward vegetable-derived base stocks. The Federal Aviation Administration maintains biodegradable hydraulic fluid mandates that favor high-oleic profiles with established cold-flow performance. Specialty chemical platforms in the Northeast and California bypass traditional distributor markups for direct-to-compounder e-procurement.
Vietnam
Cosmetics formulators contract directly with Rajasthan estate operators through blockchain-verified provenance platforms, eliminating two distributor layers from historical supply chains. The country's national pharmaceutical regulator aligns with ASEAN cosmetic directive harmonization for heavy metal and pesticide residue testing. Ho Chi Minh City-based emulsion compounders specify cold-pressed origin documentation for premium positioning in regional skincare markets.
Switzerland
Pharmaceutical-grade ben oil gains preferential market access through ECHA-compliant supply chains serving precision lubricant and skincare formulations. Swissmedic maintains stringent documentation requirements for cosmetic-grade vegetable oil imports that redirect volume toward certified estate processors. Basel and Zurich host specialty trading infrastructure anchoring European distribution for supercritical CO2-extracted grades.
Ben Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated estate operators capture premium-tier margins and trading houses aggregate bulk volume. The vendor base separates into three archetypes: backward-integrated moringa estate processors with captive laboratory capabilities, specialty oils trading houses with European distribution infrastructure, and international bulk distributors serving North American cosmetic compounders. Competitive moves center on certification timeline compression and direct-to-compounder platform development.
Among India-based integrated processors, AOS Products Pvt. Ltd. and Katyani Exports exemplify the estate-operator archetype with captive feedstock control. Kerfoot Group occupies a position within the European specialty trading tier, while Jedwards International, Inc. anchors the North American bulk distribution vector. These three named entities represent distinct competitive positions without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| AOS Products Pvt. Ltd. |
| Avi Naturals |
| Dawn Moringa |
| Katyani Exports |
| Jedwards International, Inc. |
| Kerfoot Group |
| Asili Natural Oils |
| Green India |
| Ayuritz |
| Others |
Supply Flow & Price Mechanics
Monsoon-driven moringa seed price volatility in Rajasthan and Tamil Nadu compresses margin structures for non-integrated processors while simultaneously widening spreads between premium cold-pressed grades and solvent-extracted alternatives. This feedstock instability forces a bifurcated supply chain response where backward-integrated estate operators capture pricing power and merchant refiners accept thinner margins.
Pricing Analysis
Cost-plus contracts with moringa seed indexation dominate procurement between Rajasthan estate operators and European pharmaceutical compounders. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified pharmaceutical grades from deodorized cosmetic tiers and unrefined artisanal lots. Pricing pressure stems from synthetic ester substitution in military procurement channels during harvest shortfalls. Industrial lubricant blenders exhibit highest price sensitivity while aviation hydraulic formulators accept premiums for REACH-registered cold-pressed documentation.
Supply Chain Analysis
India's BIS export certification framework functions as a de facto restricted-technology control, filtering unrefined volumes toward integrated processors with captive laboratory capabilities. Supply concentrates in India, with secondary processing clusters in Germany and Switzerland for supercritical CO2 extraction. Raw material flows draw from Rajasthan moringa estates, Tamil Nadu seed aggregation networks, and Kerala deodorization infrastructure. Single-source vulnerability concentrates in the Kerala processing corridor where three states control pharmaceutical-grade deodorization capacity. Distribution runs through estate-to-compounder direct channels for premium tiers and wholesale bulk aggregation for industrial lubricant blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction scale-up represents a technological inflection disrupting traditional hexane refining economics and rewriting premium-grade access rules. EU Green Deal bio-lubricant quotas from 2027 compliance deadlines accelerate this disruption window.
For Market Incumbents: Entrench feedstock security through captive moringa estate expansion in Rajasthan and Tamil Nadu. Accelerate BIS-FSSAI certification timeline compression to eight-month approval cycles. Cold-press technician scarcity in Rajasthan's processing belt threatens margin sustainability without workforce development investment. For New Entrants and Emerging Players: Pursue direct-to-compounder e-procurement platforms serving mid-volume North American skincare manufacturers. White-space concentration sits in blockchain-verified provenance documentation for Southeast Asian cosmetics formulators. ISCC certification investment unlocks EU Green Deal offtake channels ahead of incumbent retrofit completion. For Investors and Strategic Acquirers: EU REACH registration deadlines reshape the acquisition landscape toward ECHA-compliant supply chain assets with established aviation blender relationships. Five-to-ten year viability hinges on precision fermentation convergence reducing agricultural land-use tension. Watch for microbial oleic acid production cost parity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Moringa Estates | Captive feedstock control insulates Rajasthan processors from monsoon-driven seed price volatility. |
| Supercritical CO2 Extraction Scale-Up | Swiss and German pharmaceutical compounders now specify CO2 grades exclusively for aviation hydraulic formulations. |
| ISCC Certification Investment | EU Green Deal bio-lubricant quotas create dedicated offtake channels from 2027 compliance deadlines. |
| Blockchain Provenance Platform Development | Southeast Asian cosmetics formulators in Vietnam bypass two distributor layers through direct Rajasthan estate contracting. |
| Precision Fermentation Feedstock Partnership | Biotechnology firms explore microbial oleic acid production reducing agricultural land-use competition in tropical belts. |
Methodological Framework
A standing panel of cold-press extraction technicians, BIS certification auditors, aviation hydraulic formulators, and Kerala refinery operations managers provided ongoing calibration against secondary validation. Primary interviews with estate operators, specialty oils traders, and cosmetics procurement directors combined with customs trade data, BIS export certification records, and ECHA REACH registration databases. Bottom-up seed production estimates and top-down lubricant demand aggregation triangulated volume figures.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include processing depth (refined/crude/synthetic), end-use certification tier (pharmaceutical/cosmetic/industrial), and geographic production cluster. CAGRs derived from compound growth trajectory analysis against feedstock availability constraints and regulatory compliance timeline assumptions. Forecast inputs incorporated monsoon pattern variability and cold-press technician wage inflation.
Sensitivities concentrate around EU Green Deal quota implementation timing and precision fermentation cost reduction curves. Forecasts reflect documented assumptions on moringa seed yield stability and REACH registration continuation. Material shifts in synthetic ester substitution economics or BIS-FSSAI certification pathway duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Ingredients Market
Ingredients
North America Potato Protein Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
White Wheat Malt Market
Ingredients
Peanut Ingredients Market
Ingredients
Stabilized Starch Market
Ingredients
Date Syrup Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Vegetable Powder Market
Ingredients
Biotech Ingredients Market
Ingredients
Bakery Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Modified Soya Flour Market
Ingredients
Dark Yeast Extract Market
Ingredients
Cocoa Solids Market
Ingredients
Potato Peel Powder Market